
 Europe Temperature Sensors Market | 2026-2036
Europe Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Temperature Sensors Market Foresight
The capability gap between capital-heavy sensor fabricators and assembly-only competitors is collapsing as wafer-level packaging and MEMS foundry investments reshape cost structures. Siemens AG leverages its industrial automation ecosystem to bundle temperature sensing with process control platforms. STMicroelectronics sustains R&D intensity through captive MEMS fabrication in France and Italy. TE Connectivity Ltd anchors European automotive supply relationships with AEC-Q200-qualified thermistor lines.
A temperature sensor transduces thermal energy into an electrical signal through thermoelectric, resistive, or radiative mechanisms, typically achieving accuracy from ±0.1°C for platinum RTDs to ±2°C for low-cost thermocouples. Its primary purpose is enabling closed-loop thermal management in safety-critical and efficiency-optimized systems. Thermocouples dominate heavy industrial process control where extreme temperature ranges and vibration tolerance outweigh precision requirements. Infrared sensors represent the fastest-expanding product category as non-contact measurement gains traction in food safety and medical screening applications. Smart sensor architectures with embedded digital compensation and IO-Link connectivity are capturing margin pools previously held by analog transmitter suppliers.
REACH restrictions on lead and cadmium in sensing elements are forcing reformulation of traditional thick-film thermistor compositions. The EU Green Deal's carbon border adjustment mechanism and Ecodesign requirements are elevating demand for energy-efficient HVAC and building automation sensors. EMA medical device regulations and CE marking under the MDR impose stringent biocompatibility and calibration traceability standards on clinical temperature probes. Stakeholders must monitor how the EU AI Act's risk classification framework affects smart sensor data processing architectures and cloud-connected thermal monitoring systems.
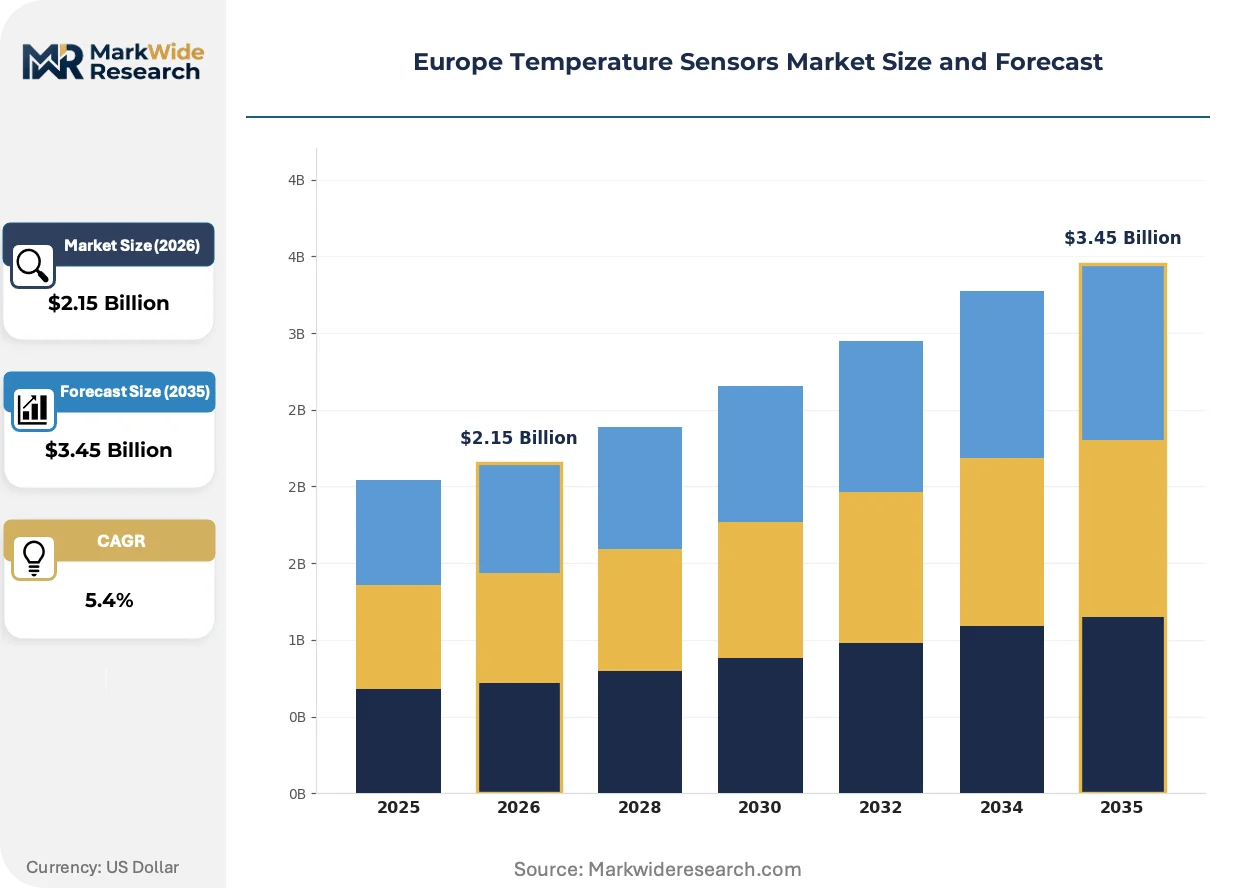
Market Dynamics
Wafer-level MEMS fabrication investments are collapsing the historical cost advantage of analog thermistor suppliers, compressing margins across Europe's sensor value chain while accelerating captive production by automotive OEMs.
Growth Catalysts
- Automotive electrification mandates:Germany's KBA and France's DGEC regulations on thermal runaway detection in battery packs are mandating multi-point temperature monitoring architectures in EV powertrains.
- REACH material restrictions:ECHA's phased elimination of lead and cadmium in sensing elements is forcing reformulation investments that favor established European compounders with in-house thick-film expertise.
- Netherlands process automation cluster:Rotterdam-Antwerp chemical corridor demand for SIL-rated temperature transmitters is pulling IO-Link compatible smart sensor volumes.
Market Restraints
- Platinum group metal volatility:RTD element costs fluctuate with South African and Russian palladium supply disruptions, squeezing sensor fabricator margins.
- MEMS foundry concentration:European temperature sensor designers depend on TSMC and GlobalFoundries Dresden for wafer supply, creating single-source vulnerability.
- Thermocouple substitution ceiling:Infrared non-contact sensors cannot displace grounded thermocouples in high-pressure hydrogen applications due to optical path contamination risks.
Strategic Opportunities
- Poland industrial automation:Underpenetrated food processing and pharmaceutical packaging sectors present white space for hygienic RTD probe suppliers.
- EU AI Act compliance services:Risk classification requirements for cloud-connected thermal monitoring create recurring revenue streams in sensor data architecture consulting.
- Digital compensation convergence:Embedded linearization algorithms combined with IO-Link output stages enable premium pricing against analog transmitter incumbents.
Industry Challenges
- Calibration technician scarcity:ISO/IEC 17025 traceability requirements for medical and automotive sensors outpace available metrology talent in Eastern Europe.
- MDR certification timelines:EMA clinical temperature probe approvals now average 18-24 months, freezing product launch schedules.
- Legacy 4-20mA integration friction:Smart sensor IO-Link adoption requires costly gateway infrastructure in brownfield process plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Temperature Sensors Market |
| Market Size in 2026 | $2.15 Billion |
| Market Size in 2035 | $3.45 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermocouples, RTDs, Thermistors, Infrared Sensors Technology: Digital, Analog, Wireless, Smart Sensors End User: Manufacturing, HVAC, Automotive, Food & Beverage Application: Industrial Automation, Process Control, Environmental Monitoring, Medical Devices |
| Companies Covered | Siemens AG, ABB Ltd, STMicroelectronics, NXP Semiconductors, Robert Bosch GmbH, Honeywell International Inc., Texas Instruments Incorporated, TE Connectivity Ltd, WIKA Alexander Wiegand SE & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Temperature Sensors Market Shifts & Advancements
Digital compensation architectures and non-contact measurement modalities are fragmenting the historical dominance of analog resistive sensors, while regulatory pressure on material content and data governance accelerates supplier consolidation.
MEMS-based platinum thin-film RTDs are fragmenting the industrial temperature sensor landscape by integrating signal conditioning and digital output on a single die. German automotive Tier-1s are adopting these devices for battery thermal runaway detection at volumes that threaten discrete thermistor module suppliers. The technology is fragmenting procurement patterns as OEMs bypass traditional transmitter houses to source calibrated sensing elements directly from foundry partners.
REACH authorization requirements for nickel compounds in sensing elements are forcing European thermistor manufacturers toward copper-nickel-manganese alloy reformulations. ECHA's 2025 sunset date for uncontrolled nickel usage is accelerating R&D spend among thick-film paste compounders in Germany and Italy. Medical probe suppliers face the steepest compliance burden as biocompatibility testing cycles for new electrode materials extend qualification timelines.
Sensor-as-a-service procurement models are displacing capital equipment purchases in building automation and cold chain logistics. Facility managers in France and the Netherlands now lease calibrated temperature monitoring networks with guaranteed uptime SLAs rather than owning sensor hardware. This shift concentrates contract value with integrated platform vendors and compresses spot market demand for standalone probe replacements.
Europe Temperature Sensors Market Segmentation
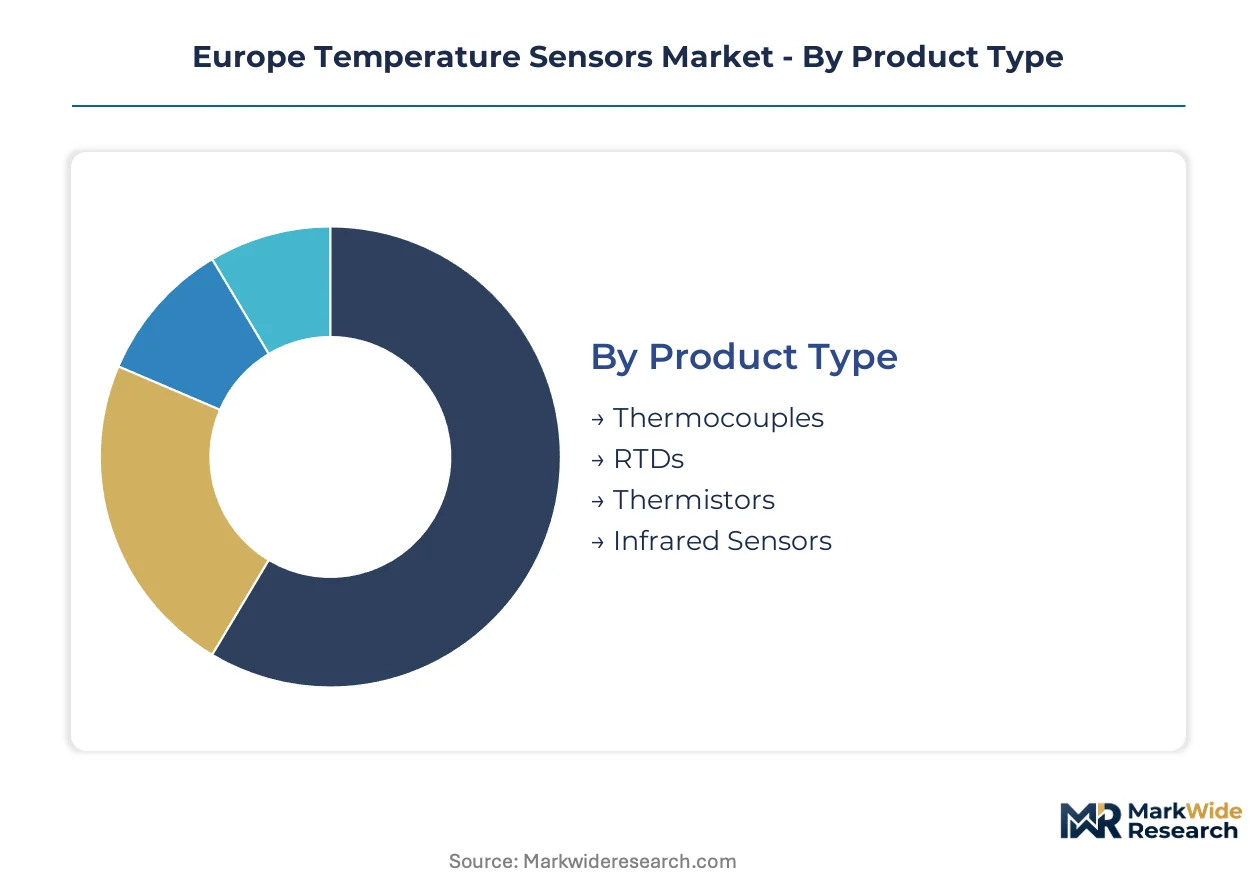
European temperature sensor procurement patterns diverge sharply across thermal measurement principles, with substitution pressures reshaping category economics. Material compliance costs and digital integration requirements favor certain architectures over legacy alternatives.
Product Type:
Thermocouples face intensifying displacement pressure from MEMS-based alternatives in automotive battery monitoring, while infrared architectures capture share in food safety and building automation.
- Thermocouples:These junction-based devices employ dissimilar metal pairs generating millivolt signals proportional to temperature differentials. Germany's KBA mandates for EV thermal runaway detection sustain demand in high-vibration powertrain environments where mechanical ruggedness outweighs precision requirements.
- RTDs:Platinum thin-film elements deliver ±0.1°C accuracy through resistance-temperature correlation. The Netherlands' Rotterdam-Antwerp chemical corridor purchases SIL-rated RTD transmitters for hazardous process control, though palladium supply volatility compresses fabricator margins.
- Thermistors:Ceramic oxide compositions provide cost-optimized measurement for HVAC and consumer appliance markets. REACH nickel restrictions force copper-nickel-manganese reformulations among German and Italian thick-film compounders.
- Infrared Sensors:Non-contact pyrometers and thermal imagers measure radiated energy without media contact. France's food safety inspectors and Dutch cold chain operators drive adoption where hygiene or contamination risks prohibit probe insertion.
Thermocouples retain volume leadership; infrared sensors hold the steepest expansion curve.
Technology:
Cost tier differentiation separates premium digital architectures from commoditized analog outputs, with wireless connectivity commanding intermediate positioning.
- Digital:Embedded ADCs and linearization algorithms output calibrated temperature values directly. IO-Link compatibility enables Polish pharmaceutical packagers to bypass analog transmitter infrastructure.
- Analog:Resistive or voltage outputs require external signal conditioning. Legacy 4-20mA installations in brownfield German process plants sustain replacement demand despite smart sensor migration.
- Wireless:Battery-powered or energy-harvesting nodes eliminate cabling in remote monitoring scenarios. French building automation retrofits favor wireless deployments where conduit installation proves cost-prohibitive.
- Smart Sensors:Integrated microcontrollers enable edge processing, diagnostic functions, and predictive maintenance protocols. EU AI Act risk classification requirements complicate cloud-connected thermal monitoring architectures.
Analog outputs retain installed-base dominance; smart sensors claim the most aggressive growth trajectory.
End User:
Application maturity varies across customer verticals, with electrification mandates accelerating automotive procurement cycles relative to established industrial segments.
- Manufacturing:Process industries deploy temperature sensing for reactor control, extrusion monitoring, and quality assurance. Belgian chemical processors specify ATEX-certified probes for explosive atmosphere compliance.
- HVAC:Building automation systems regulate thermal comfort and energy efficiency. EU Green Deal Ecodesign requirements elevate demand for precision duct and zone sensors across French commercial construction.
- Automotive:Battery pack thermal management, motor winding protection, and cabin climate control consume multi-point sensor arrays. German OEMs source calibrated MEMS elements directly from foundry partners, bypassing traditional module suppliers.
- Food & Beverage:Pasteurization validation, cold chain integrity, and cooking process control mandate hygienic probe designs. Italian dairy processors and Spanish seafood exporters drive demand for EHEDG-certified sanitary RTDs.
Manufacturing maintains volume leadership; automotive exhibits the most rapid demand acceleration.
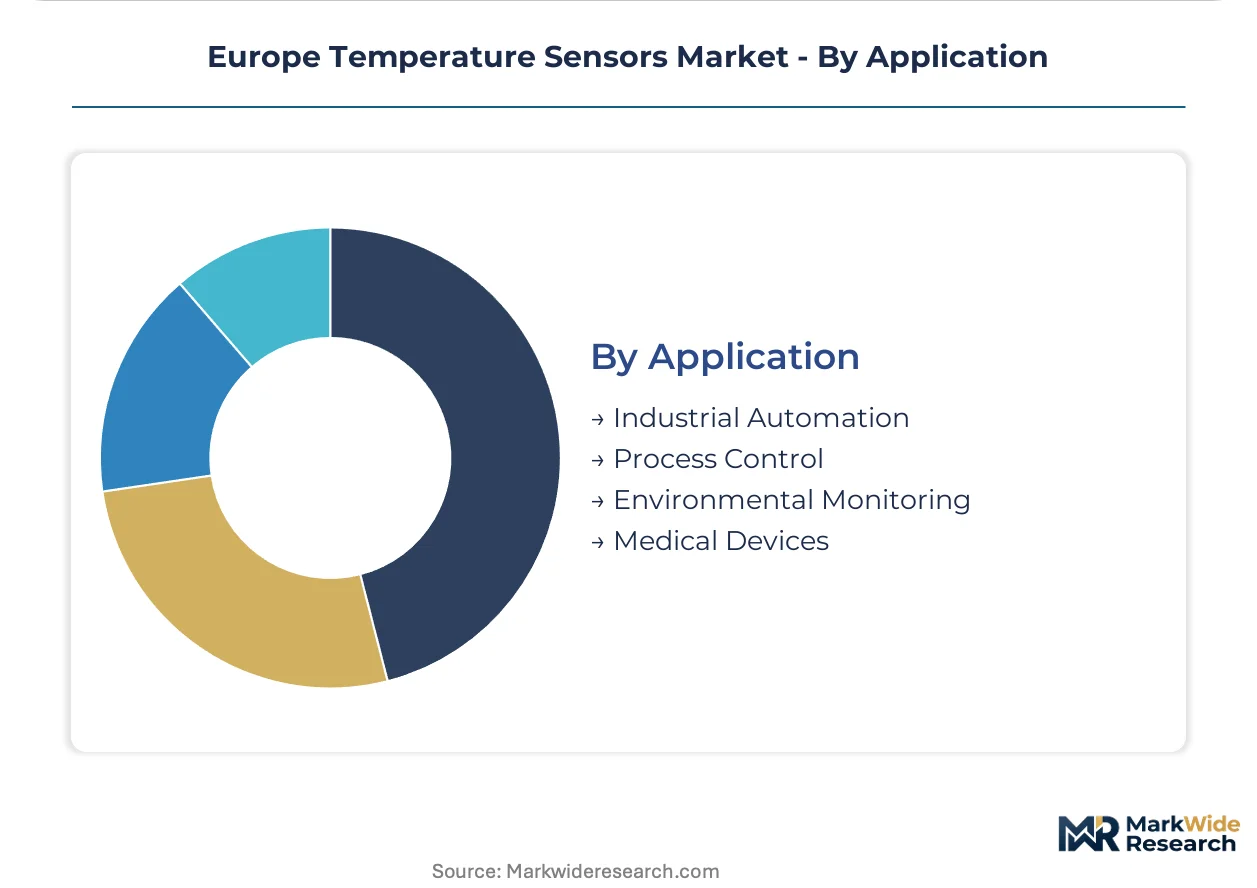
Application:
Customer type concentration shapes procurement patterns, with regulated medical and safety-critical industrial segments commanding premium pricing against environmental monitoring commoditization.
- Industrial Automation:PLC-integrated temperature monitoring governs manufacturing throughput and safety interlocks. Siemens AG bundles sensing with TIA Portal process control platforms in German automotive supplier parks.
- Process Control:Refinery, chemical, and pharmaceutical reactors require redundant temperature measurement with SIL certification. ECHA material restrictions force sensor reformulation investments that favor established European compounders.
- Environmental Monitoring:Weather stations, water quality systems, and emissions monitoring deploy ruggedized outdoor sensors. Public procurement budgets constrain pricing flexibility despite climate adaptation infrastructure spending.
- Medical Devices:Clinical temperature probes, patient warming systems, and sterilization equipment demand biocompatibility and calibration traceability. EMA MDR certification timelines now average 18-24 months, freezing product launch schedules.
Industrial automation retains volume leadership; medical devices present the steepest regulatory barrier but highest margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes temperature sensors at intensity levels unmatched elsewhere in Europe, driven by automotive electrification mandates and industrial automation density that dwarf Mediterranean markets where HVAC and food safety applications dominate procurement patterns.
Germany
KBA regulations on EV battery thermal runaway detection and the EU Green Deal's industrial decarbonization timeline are accelerating multi-point sensor deployments. The Stuttgart-Munich automotive corridor sources calibrated MEMS elements directly from foundry partners, bypassing traditional module suppliers in favor of captive procurement relationships.
France
DGEC electrification mandates and ANSM medical device oversight are reshaping demand composition toward clinical-grade probes and building automation networks. The Île-de-France region anchors sensor-as-a-service procurement models where facility managers lease calibrated monitoring networks with uptime SLAs rather than owning hardware outright.
Netherlands
Rotterdam-Antwerp chemical corridor demand for SIL-rated temperature transmitters is pulling IO-Link compatible smart sensor volumes into Dutch distribution channels. ECHA REACH compliance obligations concentrate reformulation investments among thick-film paste compounders serving this process automation cluster.
Italy
EHEDG-certified sanitary RTD demand from dairy processors in Lombardy and Emilia-Romagna is elevating hygienic probe specifications. EMA MDR certification timelines averaging 18-24 months are freezing product launch schedules for medical temperature probe suppliers based in northern industrial districts.
Poland
Underpenetrated food processing and pharmaceutical packaging sectors in the Warsaw-Łódź manufacturing belt present white space for hygienic RTD probe suppliers. ISO/IEC 17025 traceability requirements for medical and automotive sensors outpace available metrology talent, creating calibration service bottlenecks.
Europe Temperature Sensors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum commanding bundled platform plays and the lower tier competing on material expertise and certification velocity. The market structure favors compounders with in-house thick-film capabilities and captive MEMS fabrication assets over assembly-only competitors. Two strategic archetypes dominate: industrial automation conglomerates leveraging ecosystem bundling, and semiconductor fabricators with captive European foundry access. Competitive moves concentrate on wafer-level packaging investments and REACH-compliant material reformulation partnerships.
Among German-based industrial conglomerates, Siemens AG exemplifies the platform-bundling archetype through its automation ecosystem integration. STMicroelectronics and TE Connectivity Ltd occupy positions within the semiconductor and connectivity tiers respectively, with the former representing captive European MEMS fabrication capabilities and the latter anchoring automotive supply relationships through AEC-Q200-qualified product lines.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| STMicroelectronics |
| NXP Semiconductors |
| Robert Bosch GmbH |
| Honeywell International Inc. |
| Texas Instruments Incorporated |
| TE Connectivity Ltd |
| WIKA Alexander Wiegand SE & Co. KG |
| Others |
Supply & Pricing Matrix
REACH authorization timelines for nickel compounds and cadmium alternatives simultaneously gate supplier qualification and stratify price tiers across European temperature sensor procurement. ECHA's phased elimination deadlines compress margins for compounders lacking in-house thick-film reformulation capabilities while rewarding established players with premium positioning on certified material lines.
Pricing Analysis
Long-term offtake agreements dominate procurement between German automotive OEMs and MEMS foundry partners, locking in volume commitments for calibrated sensing elements at terms that exclude spot-market competitors. Three-tier pricing structure across AEC-Q200-certified premium, industrial-grade standard, and economy analog tiers reflects differentiation by certification burden and traceability depth. Cost compression in the economy thermistor segment intensifies as Asian assembly houses capture replacement demand in HVAC aftermarket channels. Polish pharmaceutical packagers exhibit acute price sensitivity due to constrained capital budgets, while Dutch chemical processors prioritize SIL-rated reliability over unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for platinum-group metal feedstock arriving from South African refiners, compressing margins for RTD fabricators dependent on just-in-time palladium delivery. Wafer supply concentrates in Taiwan and Germany, with TSMC and GlobalFoundries Dresden anchoring MEMS temperature sensor production for European automotive and industrial customers. Raw material dependencies on South African palladium, Chinese rare earth processing, and German thick-film paste compounders create single-source vulnerability for critical sensing elements. Distribution runs through specialized industrial distributors in the Netherlands and direct foundry relationships for high-volume German automotive Tier-1s.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-as-a-service procurement models in French building automation and Dutch cold chain logistics expand recurring revenue pools faster than hardware replacement cycles, repositioning contract value toward platform vendors with calibration and uptime guarantee capabilities.
For Market Incumbents: Fortify captive MEMS fabrication assets in France and Italy against displacement by automotive OEMs sourcing directly from foundry partners. Deepen backward integration into REACH-compliant thick-film paste compounders to defend margin position against reformulation cost pressures from ECHA nickel restrictions. Prioritize IO-Link gateway bundling to capture brownfield process plant upgrade cycles. For New Entrants and Emerging Players: Differentiate on hygienic RTD probe designs targeting Poland's underpenetrated food processing and pharmaceutical packaging sectors where ISO/IEC 17025 calibration scarcity creates service-attach opportunities. Pursue sensor-as-a-service platform positioning in French facility management procurement, leasing calibrated networks with uptime SLAs rather than competing on hardware unit cost. For Investors and Strategic Acquirers: ECHA's 2025 sunset date for uncontrolled nickel usage reshapes the acquisition landscape toward compounders with proven copper-nickel-manganese alloy formulations and biocompatibility testing infrastructure. Long-term viability over a five-to-ten-year window favors targets with captive European MEMS foundry access and established automotive qualification pathways. Monitor EU AI Act risk classification implementation as the signal to watch for cloud-connected thermal monitoring compliance service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level MEMS Integration | Enables German automotive OEMs to bypass traditional module suppliers for battery thermal management. |
| REACH-Compliant Material Reformulation | Secures supplier qualification for ECHA nickel sunset deadlines across medical and industrial probe lines. |
| IO-Link Platform Bundling | Captures Dutch chemical corridor demand for SIL-rated smart sensor transmitters with embedded diagnostics. |
| Sensor-as-a-Service Deployment | Locks in recurring revenue from French facility managers leasing calibrated temperature monitoring networks. |
| Calibration Service Infrastructure | Addresses Eastern European metrology talent scarcity for ISO/IEC 17025 traceability requirements. |
Research Methodology
Desk research of ECHA regulatory filings, EU automotive production databases, and semiconductor foundry capacity disclosures preceded structured interviews with MEMS process engineers, automotive Tier-1 procurement directors, and industrial automation system integrators. Primary fieldwork captured procurement pattern shifts across German OEM captive sourcing strategies and Dutch chemical corridor transmitter specifications. Secondary validation drew from EMA medical device registration data, REACH authorization timelines, and customs trade records for platinum-group metal imports. Bottom-up segment sizing triangulated against top-down European industrial automation and automotive production forecasts.
Variance decomposition across product type, technology tier, end-use vertical, and application category informed the analytical framework over the projection horizon. Modeled segmentation captured thermocouple, RTD, thermistor, and infrared architectures; digital, analog, wireless, and smart sensor outputs; manufacturing, HVAC, automotive, and food and beverage end users; plus industrial automation, process control, environmental monitoring, and medical device applications. CAGRs derived from regression against automotive electrification mandate compliance schedules and EU Green Deal Ecodesign implementation trajectories. Industry-specific inputs included KBA thermal runaway detection regulatory timelines and ECHA material restriction phase-in schedules.
Forecasts assume regulatory continuity in REACH authorization procedures and EU AI Act risk classification frameworks; material policy acceleration or delay would require re-modeling. Supply disruption scenarios for South African palladium and Taiwanese wafer capacity represent specific risk factors that could revise volume and value projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Sensor Based Sorting System Market