
 Electric Power Sports Market | 2026-2036
Electric Power Sports Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Power Sports Market Analysis
Lithium-iron-phosphate battery pack integration is narrowing the performance gap between electric and internal-combustion powertrains in off-road applications. Stark Future leverages in-house motor design to sustain premium positioning in competitive motocross segments. Surron anchors volume distribution through direct-to-consumer channels across European and North American markets. BRP competes across multiple power sport categories with established dealer infrastructure that electric entrants must replicate.
Electric power sports encompass battery-electric recreational vehicles engineered for off-road, track, and adventure use, typically incorporating brushless DC motors with peak outputs from 5 kW to above 10 kW, regenerative braking systems, and IP67-rated enclosures for mud and water ingress protection. These vehicles serve commercial adventure fleets, competitive athletes, and recreational riders seeking torque-dense propulsion without fossil fuel dependence. Electric motorcycles occupy the premium margin pool as early adopters absorb higher price points for performance parity with 250cc to 450cc gasoline equivalents. E-bikes with sub-1 kW ratings dominate unit volumes through commuter crossover demand and lower regulatory barriers. The above-10 kW segment leads R&D intensity as manufacturers chase sustained output for desert racing and extended trail applications.
EPA off-road emission exemptions for electric powertrains eliminate certification burdens that constrain gasoline engine development timelines. NHTSA emerging standards for low-speed electric vehicle lighting and braking shape product compliance roadmaps for street-legal dual-sport variants. EU F-Gas Regulation and REACH chemical restrictions influence battery thermal management fluid selections and pack sealing material choices for European market entry. Stakeholders must monitor evolving state-level OHV trail access policies and battery recycling mandates as these frameworks determine where electric fleet investments deliver permitted operating hours.
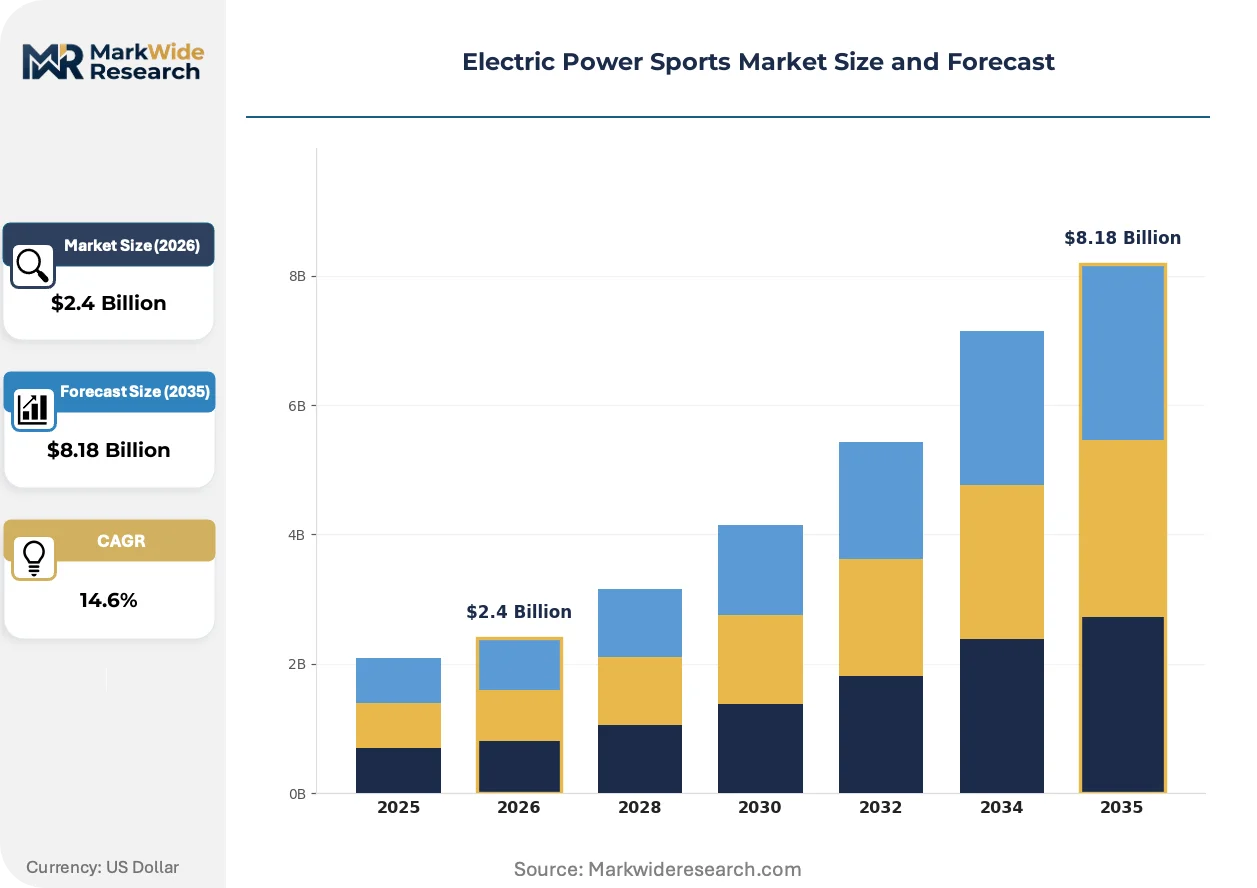
Market Dynamics
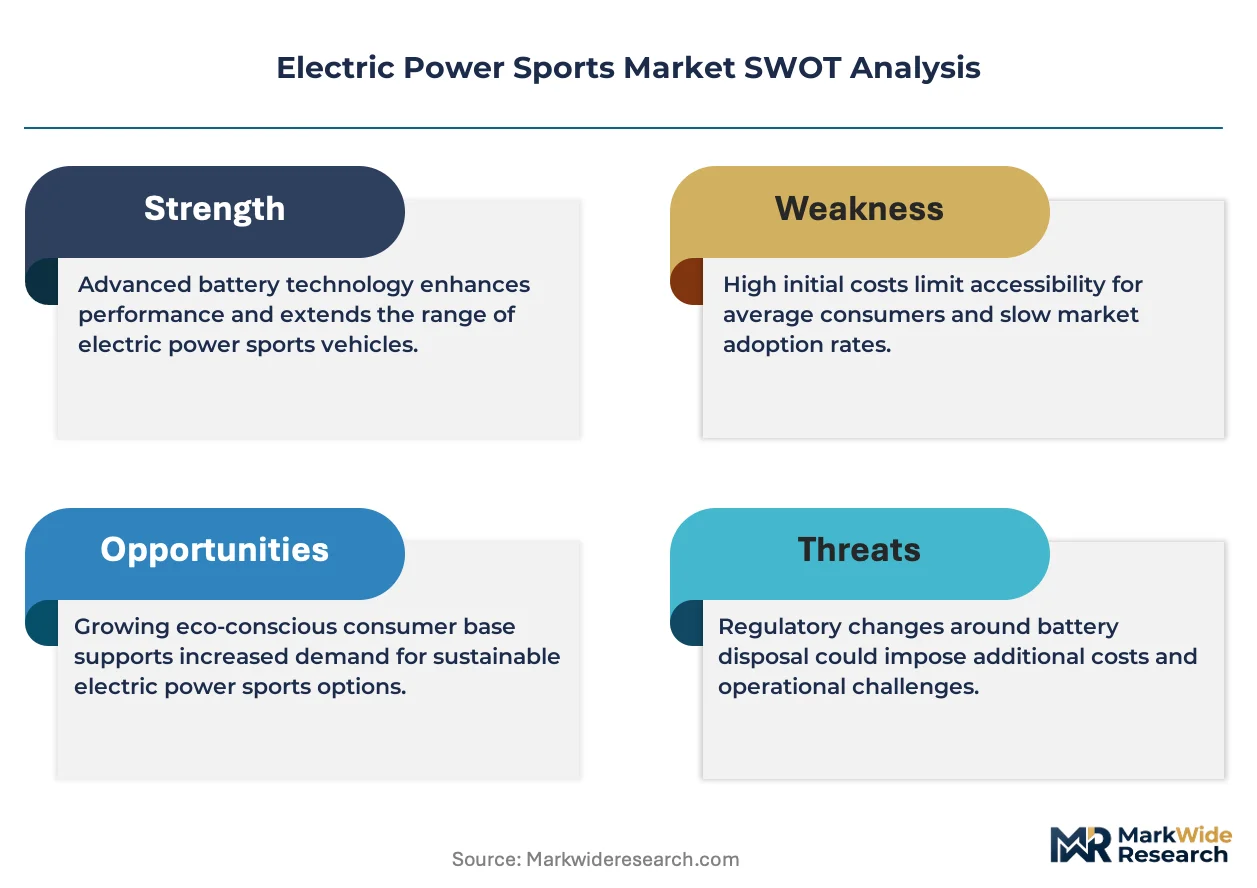
Lithium-iron-phosphate battery pack integration is narrowing the performance gap between electric and internal-combustion powertrains in off-road applications, while EPA emission exemptions for electric off-road categories accelerate product development cycles relative to gasoline equivalents.
Growth Catalysts
- EPA Off-Road Exemptions:The EPA's elimination of certification burdens for electric powertrains compresses development timelines from 18-24 months to under 12 months, enabling faster model refresh cycles.
- Lithium-Ion Energy Density Gains:Cell-level improvements above 250 Wh/kg extend trail range for desert racing applications, reducing range anxiety among recreational riders.
- Adventure Fleet Electrification:Commercial operators across Arizona and Utah recreation corridors are replacing gasoline fleets to secure permitted operating hours under tightening noise ordinances.
Market Restraints
- Lithium Price Volatility:Cathode material cost swings constrain margin stability for battery pack producers serving the above-10 kW performance segment.
- Dealer Infrastructure Concentration:Established gasoline power sports networks in rural North American markets limit direct-to-consumer penetration for electric entrants lacking service footprint.
- Thermal Management Complexity:IP67 sealing requirements for mud and water ingress protection conflict with passive cooling efficiency in desert racing conditions.
Strategic Opportunities
- EU F-Gas Compliance Services:Battery thermal management fluid redesigns for REACH chemical restrictions create advisory revenue streams for engineering consultancies entering European markets.
- Dual-Sport Street-Legal Variants:NHTSA emerging standards for low-speed electric vehicle lighting and braking open urban commuter crossover demand beyond pure off-road use.
- Direct-to-Consumer Subscription:Battery-as-a-service models bypass dealer resistance while capturing recurring revenue from recreational riders in coastal California and Pacific Northwest markets.
Industry Challenges
- Motor Control Firmware Talent Scarcity:Brushless DC inverter programming expertise concentrates in automotive and industrial automation sectors, forcing power sports OEMs to compete for embedded systems engineers.
- State-Level OHV Access Fragmentation:Inconsistent trail electrification policies across Bureau of Land Management districts complicate fleet investment planning for commercial operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Power Sports Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Motorcycles, E-Scooters, E-Bikes, Electric All-Terrain Vehicles Power Rating: Below 1 kW, 1-5 kW, 5-10 kW, Above 10 kW Distribution Channel: Online Retail, Specialty Stores, Authorized Dealers, Rental Services End User: Athletes, Recreational Users, Commuters, Adventure Enthusiasts |
| Companies Covered | Altis, Rawrr, Stark Future, LiveWire, Surron, BRP, E Ride Pro, Can-Am, DRR USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Power Sports Market Emerging Trajectories
Telematics integration is reshaping how fleet operators manage utilization and maintenance scheduling, compressing the information asymmetry between manufacturers and end-users that historically defined aftermarket parts economics.
Regenerative braking calibration algorithms are digitizing traction control for off-road terrain, enabling real-time torque vectoring previously requiring mechanical differential locks. Stark Future and Surron embed these systems in premium motocross platforms, while adventure tour operators in Moab and Sedona adopt them for fleet consistency across varying rider skill levels.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon-free thermal management fluid adoption, forcing pack designers to reformulate dielectric coolants and gasket materials for European market entry. Manufacturers targeting German and French distribution must validate alternative chemistries through ECHA substance authorization pathways before 2027 compliance deadlines.
Adventure tourism procurement is consolidating around outcome-based fleet availability contracts rather than unit purchase, shifting risk from operator to OEM for battery degradation and downtime. This model concentrates in Utah and Arizona desert corridors where seasonal demand volatility makes capital ownership uneconomical for smaller tour operators.
Electric Power Sports Market Segmentation
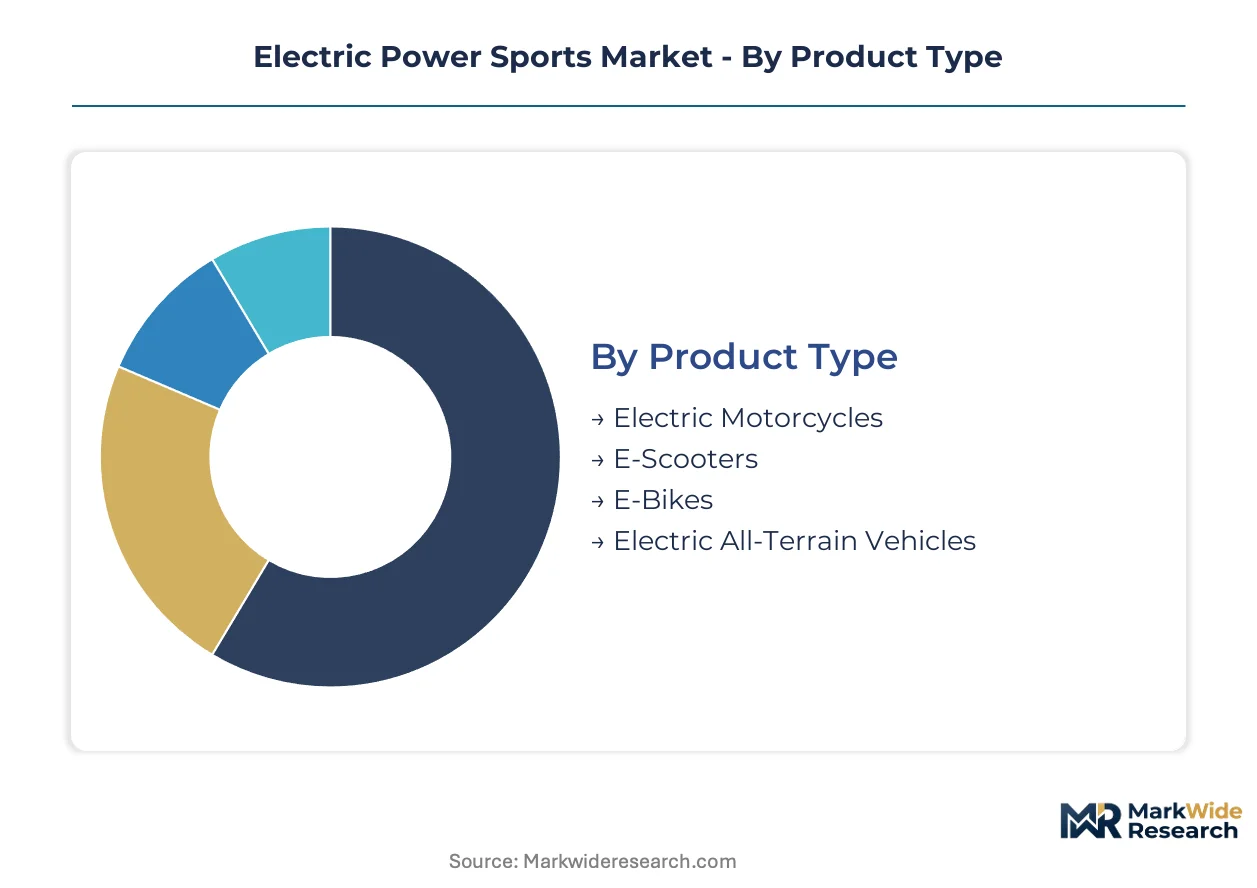
Segmentation in electric power sports reveals how torque density, regulatory thresholds, and rider skill levels partition demand across distinct hardware configurations. Each dimension exposes different margin structures and competitive dynamics that manufacturers must navigate.
Product Type:
Application context determines battery sizing, motor cooling requirements, and frame geometry across recreational and competitive use cases.
- Electric Motorcycles:Full-size dirt bikes and motocross platforms with 5-15 kW peak outputs and swappable battery packs. Arizona and Utah desert racing circuits absorb premium units as commercial fleets replace 250cc-450cc gasoline equivalents under tightening noise ordinances.
- E-Scooters:Standing and seated variants with sub-2 kW hub motors, folding mechanisms, and commuter-optimized range. Urban California and Pacific Northwest markets drive volume through last-mile connectivity demand and lane-splitting legal exemptions.
- E-Bikes:Pedal-assist bicycles with 250W-750W mid-drive or hub motors, torque sensors, and trail-legal speed limiters. European regulatory caps at 25 km/h shape motor controller firmware for German and French distribution.
- Electric All-Terrain Vehicles:Four-wheeled utility and sport platforms with independent suspension, 10+ kW continuous output, and cargo racks. Ranch operators and hunting outfitters in Texas and Colorado deploy these for silent property access.
Electric motorcycles command the established base. The steepest expansion runs through electric all-terrain vehicles.
Power Rating:
Cost tier alignment separates entry-level commuter hardware from performance-grade racing equipment with thermal management complexity.
- Below 1 kW:Hub motor e-bikes and standing scooters with passive cooling, minimal battery mass, and price points under premium motorcycle tiers. Commuter crossover demand in coastal European cities and Asian megacities sustains manufacturing scale.
- 1-5 kW:Mid-drive e-bikes and light motorcycles with liquid-cooled controllers, 2-4 kWh packs, and trail-legal classifications. Recreational riders in German forest trail networks and Dutch cycling infrastructure favor this bracket for licensing simplicity.
- 5-10 kW:Full-size electric dirt bikes with regenerative braking, inverted forks, and motocross-grade suspension. Competitive athletes in AMA-sanctioned events and amateur race series absorb units as battery energy density closes the gap with 250cc four-strokes.
- Above 10 kW:Desert racing motorcycles and high-performance ATVs with active thermal management, 8+ kWh packs, and sustained wide-open-throttle capability. Professional race teams and commercial adventure operators in Moab and Sedona corridors concentrate procurement here despite lithium price volatility.
The 5-10 kW bracket anchors current manufacturing investment. Above-10 kW systems are climbing the fastest as desert range requirements harden.
Distribution Channel:
Customer type and purchase urgency shape whether buyers engage direct-to-consumer platforms, physical service networks, or temporary access models.
- Online Retail:Direct-to-consumer websites and third-party marketplaces with video-based assembly support and remote diagnostics. Surron and similar entrants bypass dealer concentration in rural North America through this channel.
- Specialty Stores:Independent bicycle dealers and power sports shops with floor inventory, test ride facilities, and maintenance bays. European urban centers and US coastal metros sustain this tier for first-time electric adopters seeking hands-on validation.
- Authorized Dealers:OEM-captive networks with factory-trained technicians, warranty administration, and parts distribution. BRP and legacy manufacturers leverage existing gasoline power sports infrastructure here.
- Rental Services:Fleet operators offering hourly, daily, or seasonal access with insurance bundling and guided tour packages. Utah and Arizona adventure tourism corridors consolidate procurement through outcome-based availability contracts rather than unit purchase.
Authorized dealers retain the incumbent position. Rental services are gaining share fastest as seasonal operators shed capital ownership risk.
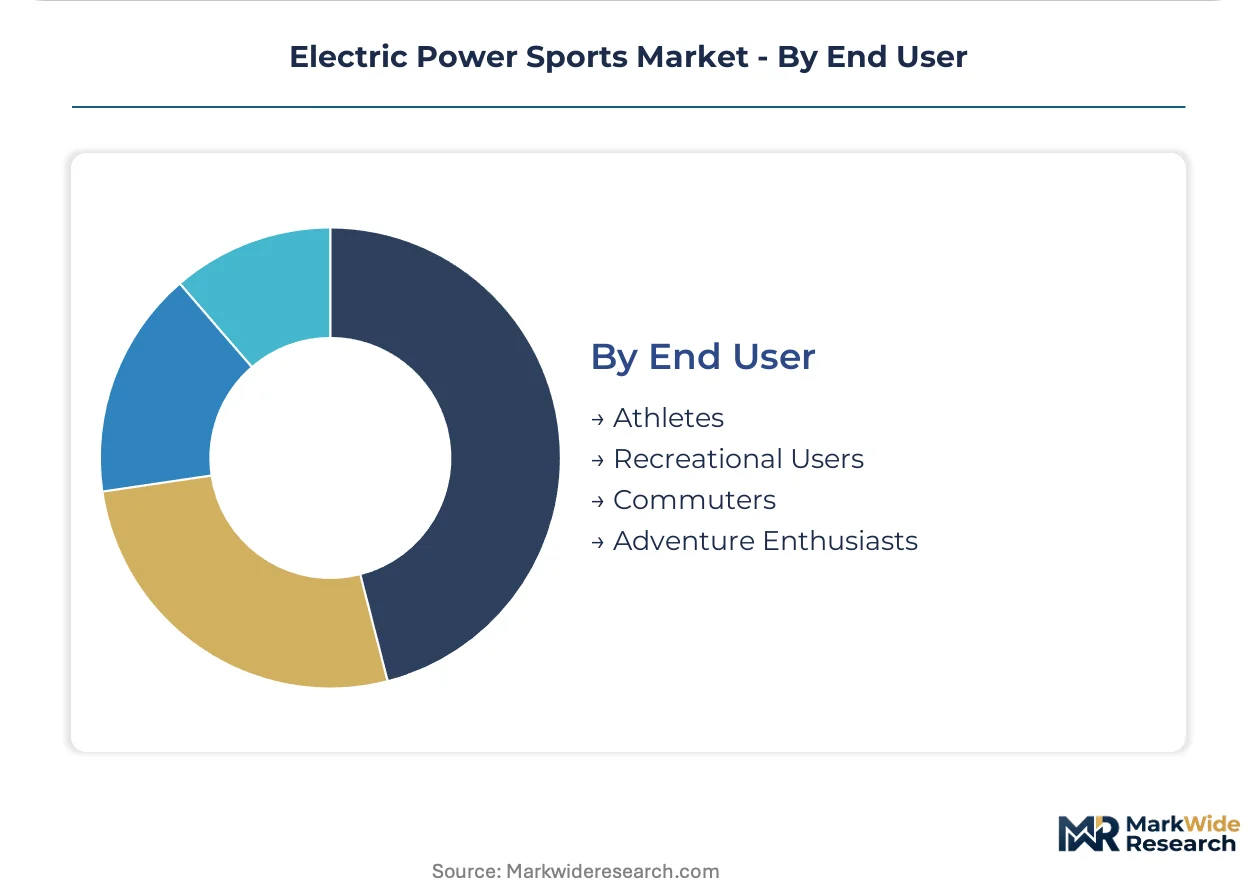
End User:
Volume concentration and margin capture diverge sharply between competitive performance seekers and utility-focused riders.
- Athletes:Amateur and professional racers requiring FIM or AMA homologation, spare battery inventory, and telemetry integration for training analysis. Motocross training facilities in Florida and California cluster demand for premium-tier hardware.
- Recreational Users:Weekend trail riders and casual off-road enthusiasts prioritizing reliability, moderate range, and dealer service proximity. This segment spreads across suburban and exurban markets in Texas, Colorado, and the Mountain West.
- Commuters:Urban and suburban riders using electric two-wheelers for daily transportation with cargo capacity and weather protection requirements. Lane-filtering legality in California and rising congestion pricing in European capitals steer selection toward sub-5 kW formats.
- Adventure Enthusiasts:Multi-day backcountry explorers and overland tour participants demanding extended range, charging infrastructure compatibility, and self-recovery capability. Guided tour operators in Moab, Sedona, and Baja California procure fleet-scale volumes with seasonal utilization guarantees.
Recreational users provide the volume foundation. Adventure enthusiasts are expanding most quickly as commercial fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers export electric power sports hardware to European adventure tourism operators and Australian mining fleet managers, establishing a trans-Pacific trade corridor for high-torque off-road vehicles.
United States
Arizona and Utah desert recreation corridors absorb premium electric motorcycles for commercial fleet replacement under tightening noise ordinances. EPA off-road emission exemptions eliminate certification burdens that constrain gasoline engine development timelines. Moab and Sedona adventure operators consolidate procurement through outcome-based availability contracts rather than unit purchase.
Germany
Forest trail networks in Bavaria and Baden-Württemberg sustain mid-drive e-bike demand for recreational riders seeking licensing simplicity. EU F-Gas Regulation phase-down schedules accelerate hydrofluorocarbon-free thermal management fluid adoption, forcing pack designers to reformulate dielectric coolants. ECHA substance authorization pathways dominate pre-market validation timelines for battery thermal management systems.
France
Provence-Alpes-Côte d'Azur adventure operators pilot silent ATV fleets for backcountry access permits in noise-sensitive alpine zones. REACH chemical restrictions influence battery pack sealing material choices and thermal management fluid selections. Lyon engineering consultancies capture advisory revenue from redesign services for European market entry compliance.
Japan
Tokyo and Osaka metropolitan areas drive sub-5 kW electric two-wheeler demand through congestion pricing and lane-filtering infrastructure. METI standards for battery recycling and end-of-life handling shape OEM service network requirements. Kansai manufacturing clusters produce precision motor controllers for export to North American motocross platforms.
Australia
Queensland and Western Australia mining operations deploy silent electric ATVs for property access and survey work in noise-restricted tenements. TGA-equivalent electrical safety standards for off-road vehicle lighting and braking influence product compliance roadmaps. Perth-based fleet managers integrate telematics for utilization tracking across remote site deployments.
Electric Power Sports Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Authorized dealer networks retain incumbent positioning through factory-trained technicians and warranty administration, while direct-to-consumer entrants bypass rural service gaps through video-based assembly support. Three archetypes dominate: legacy gasoline power sports incumbents leveraging existing infrastructure, pure-play electric specialists with in-house motor design, and volume-oriented direct-to-consumer brands. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into dual-sport street-legal variants.
Among pure-play electric specialists, Stark Future and Surron occupy distinct positioning vectors. Stark Future exemplifies the premium-tier motor-design archetype with captive powertrain engineering. Surron anchors volume distribution through direct-to-consumer channels across European and North American markets. BRP represents legacy infrastructure leverage, competing across multiple power sport categories with established dealer networks that electric entrants must replicate.
| Leading Market Players |
|---|
| Altis |
| Rawrr |
| Stark Future |
| LiveWire |
| Surron |
| BRP |
| E Ride Pro |
| Can-Am |
| DRR USA |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Long Beach container rates compress margin structures for battery pack importers while concentrating procurement leverage among Arizona and Utah fleet operators who negotiate volume-based availability contracts. This freight corridor's volatility feeds directly into three-tier pricing stratification across premium, standard, and economy performance tiers.
Pricing Analysis
Next-generation solid-state battery architectures command substantial premiums over current-generation lithium-iron-phosphate packs and prior-generation nickel-manganese-cobalt systems. Three-tier pricing structure across premium, standard, and economy levels reflects motor controller sophistication and thermal management complexity rather than raw battery capacity. Cost compression in the sub-5 kW commuter tier intensifies because of direct-to-consumer channel expansion and minimal dealer service requirements. Commercial adventure fleet operators exhibit lowest price sensitivity due to outcome-based contracting models, while individual recreational riders in exurban Texas and Colorado markets resist premium positioning without local service infrastructure.
Supply Chain Analysis
Foxconn and BYD Electronics dominate contract manufacturing capacity for motor controller assemblies and battery management systems serving electric power sports OEMs. Component sourcing concentrates in China for lithium-ion cells, Taiwan for semiconductor power modules, and Germany for precision suspension hardware. Cathode material supply rests on Chilean lithium carbonate and Indonesian nickel processing, exposing producers to commodity price volatility and export licensing restrictions. Distribution runs through authorized dealer networks in rural North American markets and direct-to-consumer platforms in coastal European urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric power sports platforms are approaching an interoperability inflection where battery-swapping standards and telematics APIs determine ecosystem lock-in, mirroring the smartphone accessory economy's platform consolidation dynamics.
For Market Incumbents: Build certification moats around EPA emission exemption documentation and NHTSA street-legal homologation pathways to delay pure-play electric specialists. Defensive consolidation should prioritize captive motor controller firmware development and exclusive distribution agreements with Arizona and Utah adventure fleet operators facing seasonal utilization volatility. BRP and legacy manufacturers must replicate direct-to-consumer service capabilities before Surron and Stark Future establish rural maintenance footprints.
For New Entrants and Emerging Players: Pursue dual-sport street-legal variants as the most penetrable white-space segment, exploiting NHTSA emerging standards for low-speed electric vehicle lighting and braking that incumbent gasoline networks navigate slowly. Target Pacific Northwest commuter markets with subscription-based battery-as-a-service models that bypass dealer resistance. Go-to-market execution should emphasize video-based assembly support and remote diagnostics to overcome rural service gaps.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy gasoline power sports parents seeking to divest electric divisions lacking dealer network integration. Long-term viability across the projection horizon hinges on thermal management IP and firmware talent retention rather than battery pack assembly scale. Watch EU F-Gas Regulation compliance timelines as the inflection signal—manufacturers failing ECHA substance authorization pathways before phase-down deadlines face market exclusion.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Launch | Subscription models bypass dealer concentration in rural North American markets while capturing recurring revenue from coastal California riders. |
| Dual-Sport Street-Legal Certification | NHTSA compliance opens urban commuter crossover demand beyond pure off-road applications in congestion-pricing metros. |
| Thermal Management Fluid Redesign | ECHA authorization pathways for hydrofluorocarbon-free coolants determine European market entry viability before regulatory deadlines. |
| Telematics Platform Integration | Fleet utilization tracking compresses information asymmetry between Stark Future and Moab adventure operators managing seasonal demand. |
| Motor Controller Firmware Acquisition | Embedded systems talent scarcity forces power sports OEMs to acquire automotive inverter programming capabilities. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with electric power sports OEM product managers, battery pack engineering directors, Arizona fleet procurement officers, and NHTSA regulatory affairs specialists; alongside secondary validation through EPA emission exemption filings, EU ECHA substance authorization databases, SEC manufacturer disclosures, and Bureau of Land Management OHV trail access policy records. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Forecast inputs span power rating tiers, product type categories, distribution channel structures, and end-user archetypes across the analysis window. CAGRs derive from segmented growth rate blending weighted by current revenue concentration. Industry-specific modeling incorporates lithium price volatility scenarios, state-level trail electrification policy trajectories, and motor control firmware talent availability indices.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices, container freight rates, or semiconductor foundry utilization would shift the trajectory. Forecasts embed assumptions regarding EPA exemption continuity and EU F-Gas phase-down adherence. Quarterly review of cathode material futures, BLM district OHV access rulings, and embedded systems engineering salary indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
India Uninterruptible Power Supply (UPS) Market
Power
Distributed Buoyancy Modules Market
Power
Equatorial Guinea Power Market
Power
Global Hydraulic Turbine Market
Power
Global Ancillary Services Power Market
Power
North America Microturbine Market
Power
Asia-Pacific Package Substation Market
Power
Europe Frequency Converter Market
Power
Global Advanced Marine Power Supply Market
Power
North America CHP Market
Power
Solar UPS Market
Power
Residential Micro Inverter Market
Power
Statcom Market
Power
Critical Power Market
Power
Sudan Power EPC Market
Power
Power Rental Market