
 Iran Power Market | 2026-2036
Iran Power Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Power Market Foresight
Industrial consumers in steel, petrochemicals, and cement are rotating toward captive and distributed generation as grid reliability concerns persist. MAPNA Group leverages its integrated engineering and manufacturing platform to dominate domestic gas turbine supply. Tabiran Co. competes through specialized transformer and switchgear production for transmission upgrades. KPV Solar Iran anchors the emerging photovoltaic segment with module assembly and EPC capabilities.
Iran power encompasses electricity generation, transmission, and distribution infrastructure operating across thermal, hydro, renewable, and nuclear sources, with combined-cycle gas turbines achieving thermal efficiencies above 58 percent in modern installations. The system serves residential, commercial, industrial, and utility end users through both centralized and distributed architectures. Thermal generation occupies the largest installed capacity share due to abundant domestic natural gas reserves, though solar and wind segments are expanding fastest under capacity addition targets. Utility-scale installations sustain the dominant revenue pool, while distributed generation is gaining structural importance in industrial zones seeking supply security.
The Ministry of Energy and Tavanir Holding Company shape market structure through generation licensing, tariff setting, and grid interconnection standards. The Renewable Energy and Energy Efficiency Organization (SATBA) administers feed-in tariff mechanisms and power purchase agreements for non-thermal sources. Stakeholders must monitor fuel allocation politics, sanctions-related equipment import constraints, and provincial grid investment priorities as determinants of viable project development timelines.
Market Dynamics
Combined-cycle gas turbine retrofits are compressing thermal fleet economics while SATBA feed-in tariffs pull capital toward distributed solar. This dual-track evolution splits investment flows between legacy asset optimization and greenfield renewable deployment.
Growth Catalysts
- Steel and petrochemical procurement:Industrial clusters along the Persian Gulf coastal corridor are expanding electricity offtake to support capacity additions in metallurgy and chemicals.
- SATBA feed-in tariff framework:The Renewable Energy and Energy Efficiency Organization guarantees long-term power purchase agreements for photovoltaic and wind projects.
- Gas turbine efficiency gains:Advanced blade cooling and combustion tuning push modern combined-cycle installations past 58 percent thermal efficiency.
Market Restraints
- Equipment import constraints:Sanctions restrict access to Western gas turbine controls and high-voltage switchgear, forcing reliance on Chinese and Russian supply channels.
- Natural gas allocation politics:The Ministry of Petroleum competes with power generators for feedstock, creating seasonal fuel availability volatility.
- Grid interconnection bottlenecks:Transmission capacity lags behind generation additions in Kerman and Yazd provinces, stranding renewable output.
Strategic Opportunities
- Khorasan Razavi distributed solar:Eastern provinces with high irradiance and land availability remain underpenetrated for utility-scale photovoltaic development.
- Industrial captive generation:Cement and steel producers are installing behind-the-meter gas turbines and solar arrays to bypass grid reliability risks.
- Combined-cycle retrofit services:Aging thermal fleets require efficiency upgrades and digital control system replacements.
Industry Challenges
- Specialized turbine technician scarcity:Domestic engineering programs produce insufficient graduates trained in advanced gas turbine maintenance and hot gas path inspection.
- Foreign equipment financing complexity:Letters of credit for imported generation equipment face processing delays through sanctioned banking channels.
- Legacy grid control integration:New renewable capacity requires synchronization with aging SCADA systems operated by provincial distribution companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Power Market |
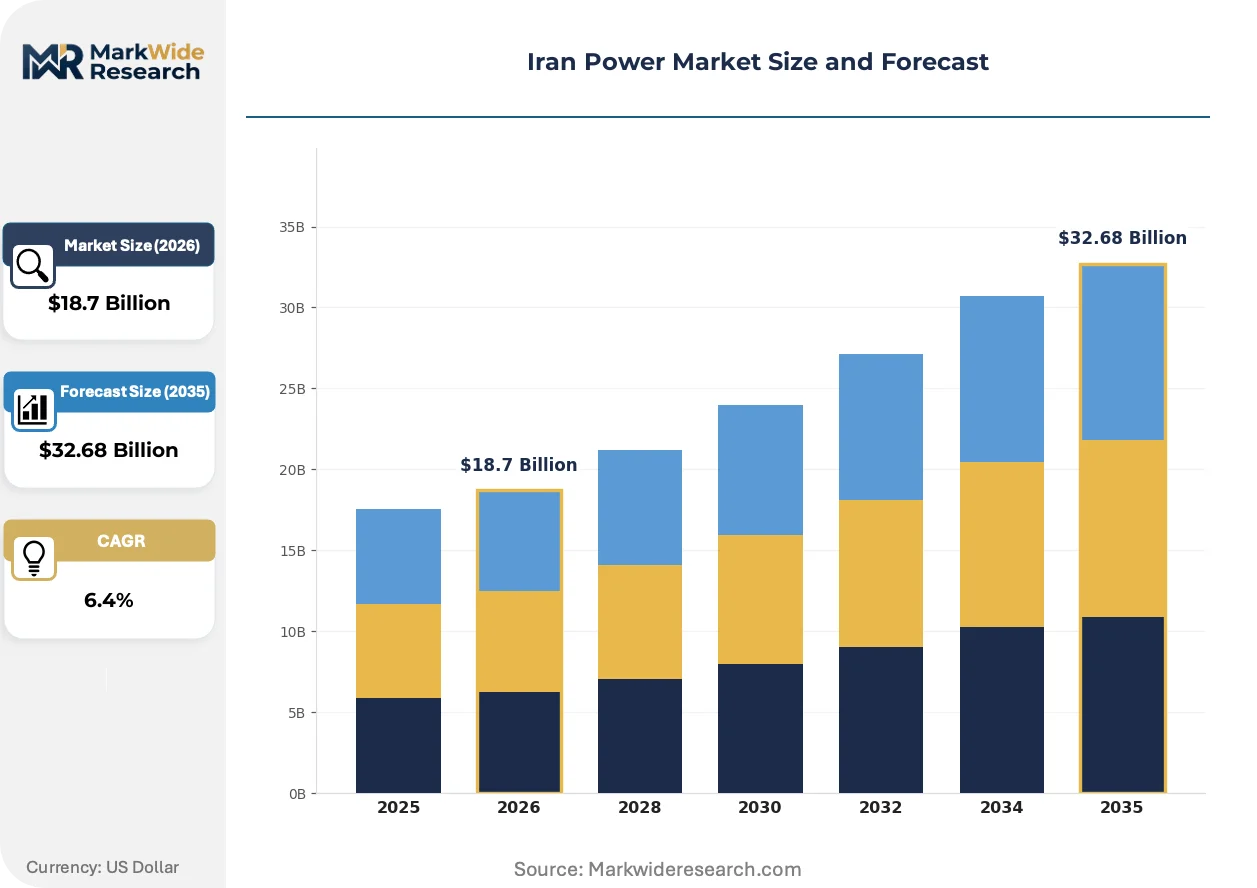
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Thermal, Hydro, Nuclear Technology: Solar, Wind, Gas Turbine, Biomass End User: Residential, Commercial, Industrial, Utility Installation: Onshore, Offshore, Distributed, Centralized |
| Companies Covered | Tabiran Co., Isfahan Power Generation Company, MAPNA Group, Azerbaijan Power Generation Company, Bandar Abbas Power Generation Company, Besat Power Generation Management Company, KPV Solar Iran, Zahedan Power Generation Company, Ardabil Electricity Distribution Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Power Market Shifts & Advancements
Digitalization of asset performance management and modular construction methods are compressing project development timelines. These shifts intersect with evolving procurement preferences and regulatory incentives.
Advanced gas turbine inlet air cooling is decomposing the traditional seasonal output penalty that plagued Iranian thermal plants through hot summer months. Petrochemical complexes in Asaluyeh are retrofitting evaporative and absorption chilling systems to sustain rated capacity during peak demand periods. This technology is decomposing the historical trade-off between installed capacity and ambient temperature derating.
SATBA has tightened domestic content requirements for solar module assembly and inverter manufacturing. The regulation mandates minimum local value-add thresholds for projects to qualify for feed-in tariff rates. Developers are responding by partnering with domestic electronics assemblers in Shiraz and Tehran to source compliant components.
Long-term electricity supply contracts are fragmenting into shorter tenors and volume-flexible structures. Large industrial offtakers in the steel sector are negotiating take-or-pay clauses with annual reopener provisions rather than decade-long fixed commitments. This pattern is most pronounced in Isfahan Province where multiple generators compete for anchor tenant status.
Iran Power Market Segmentation
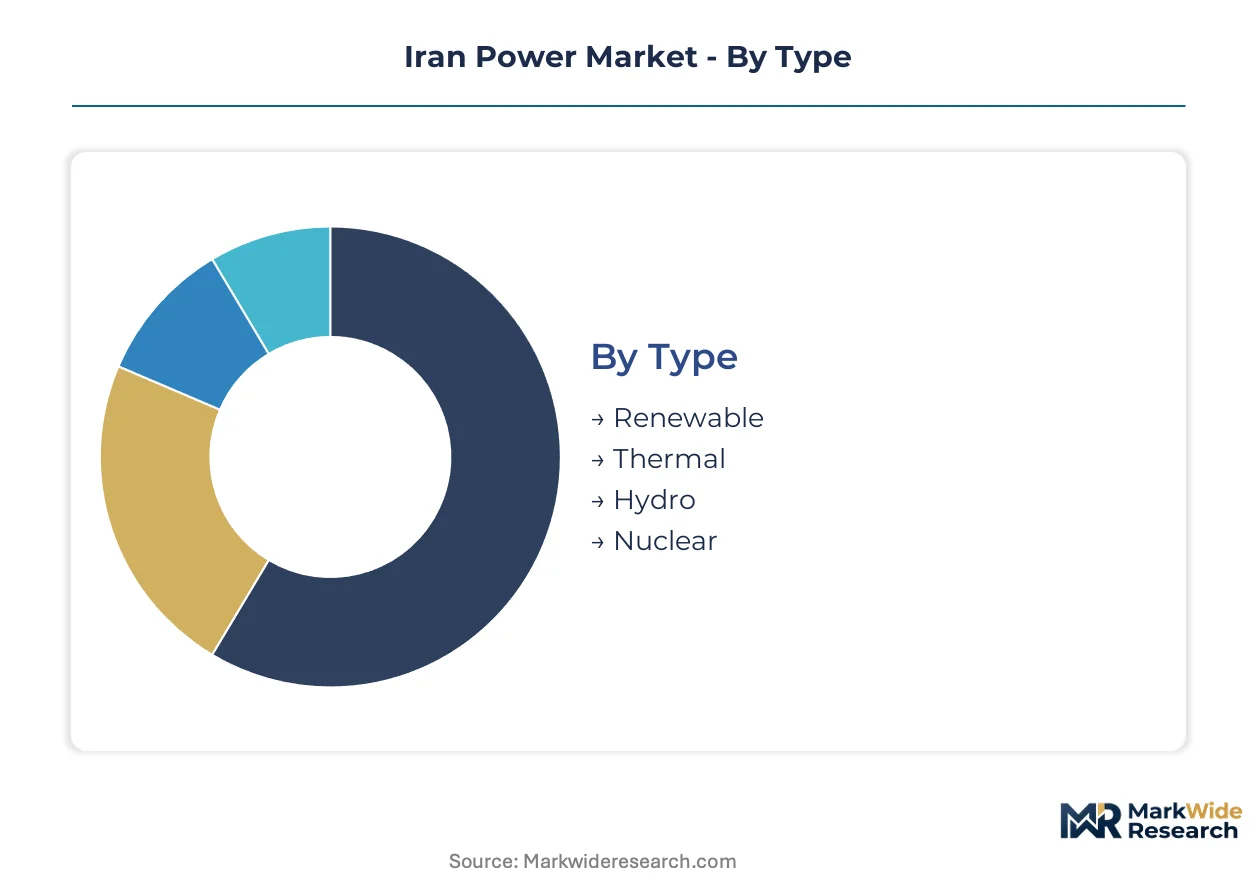
Segmentation in the Iran power market reveals how fuel allocation politics, sanctions-driven supply constraints, and provincial grid bottlenecks reshape investment viability across generation technologies and customer categories. Understanding these divisions exposes where capital can actually deploy versus where projects strand.
Type:
Margins pool heaviest in thermal retrofits and distributed solar where fuel security premiums and SATBA tariff guarantees create predictable returns.
- Thermal:Combined-cycle gas turbines dominate installed base, burning domestically produced natural gas at efficiencies exceeding 58 percent in modern installations. Steel mills in Isfahan Province and petrochemical complexes along the Persian Gulf corridor anchor baseload procurement, though Ministry of Petroleum feedstock competition creates seasonal volatility.
- Renewable:Photovoltaic and wind capacity additions accelerate under SATBA feed-in tariff mechanisms, with developers targeting Kerman and Yazd provinces for high irradiance and land availability. Grid interconnection bottlenecks in these same regions strand output and compress realized margins.
- Hydro:Existing dams on the Karun and Karkheh rivers provide seasonal peaking capacity, constrained by water availability fluctuations and limited new site potential.
- Nuclear:The Bushehr facility contributes baseload supply, with expansion plans facing equipment import constraints through sanctioned banking channels.
The dominant share belongs to Thermal, while Renewable is closing the gap fastest.
Technology:
Technology choice hinges on whether developers can secure Western controls through third-country channels or must accept Chinese and Russian alternatives with shorter maintenance intervals.
- Gas Turbine:Advanced blade cooling and combustion tuning push thermal efficiency past 58 percent, with MAPNA Group dominating domestic supply. Petrochemical complexes in Asaluyeh retrofit inlet air chilling to sustain rated output through summer temperature peaks.
- Solar:SATBA mandates minimum domestic content thresholds for module assembly and inverter manufacturing, pushing developers toward Shiraz and Tehran electronics assemblers. Khorasan Razavi Province remains underpenetrated for utility-scale deployment despite superior irradiance.
- Wind:Class III and IV turbines suit Iran's moderate wind resource, with projects clustering in Manjil and Binalood where topography accelerates airflow.
- Biomass:Agricultural residue-fired plants serve small industrial loads, limited by feedstock collection logistics and seasonal supply consistency.
Gas Turbine holds the largest operational footprint, though Solar is expanding most quickly.
End User:
Customer segmentation tracks reliability premiums and contract flexibility, with industrial offtakers paying more to bypass grid instability.
- Industrial:Steel, cement, and petrochemical producers rotate toward captive generation—behind-the-meter gas turbines and solar arrays—to insulate operations from distribution failures. Procurement contracts fragment into shorter tenors with annual reopener provisions rather than decade-long commitments.
- Utility:Tavanir Holding Company and provincial distribution companies procure bulk supply through centralized auctions, though payment delays and currency conversion complexities burden independent generators.
- Residential:Subsidized tariffs suppress realized revenue per kilowatt-hour, with demand concentrated in Tehran Province where air conditioning loads spike summer consumption.
- Commercial:Shopping centers and office complexes in urban corridors face the same reliability constraints as residential users, with limited scale to justify captive generation investments.
Industrial offtakers command the highest effective tariffs, while Utility procurement maintains the largest volume base.
Installation:
Physical configuration determines whether projects face transmission bottlenecks or fuel allocation politics.
- Centralized:Utility-scale thermal and renewable plants feed the national grid, requiring interconnection agreements with Tavanir and provincial distribution companies. Transmission capacity lags behind generation additions in Kerman and Yazd, stranding renewable output.
- Distributed:Behind-the-meter installations at industrial sites bypass grid reliability risks entirely, with cement and steel producers leading adoption. SATBA feed-in tariffs extend to smaller-scale solar feeding into distribution networks.
- Onshore:All current renewable capacity sits onshore, with land availability and grid proximity driving site selection.
- Offshore:No operational capacity exists, with Caspian Sea and Persian Gulf technical potential unexplored due to equipment access constraints and water depth challenges.
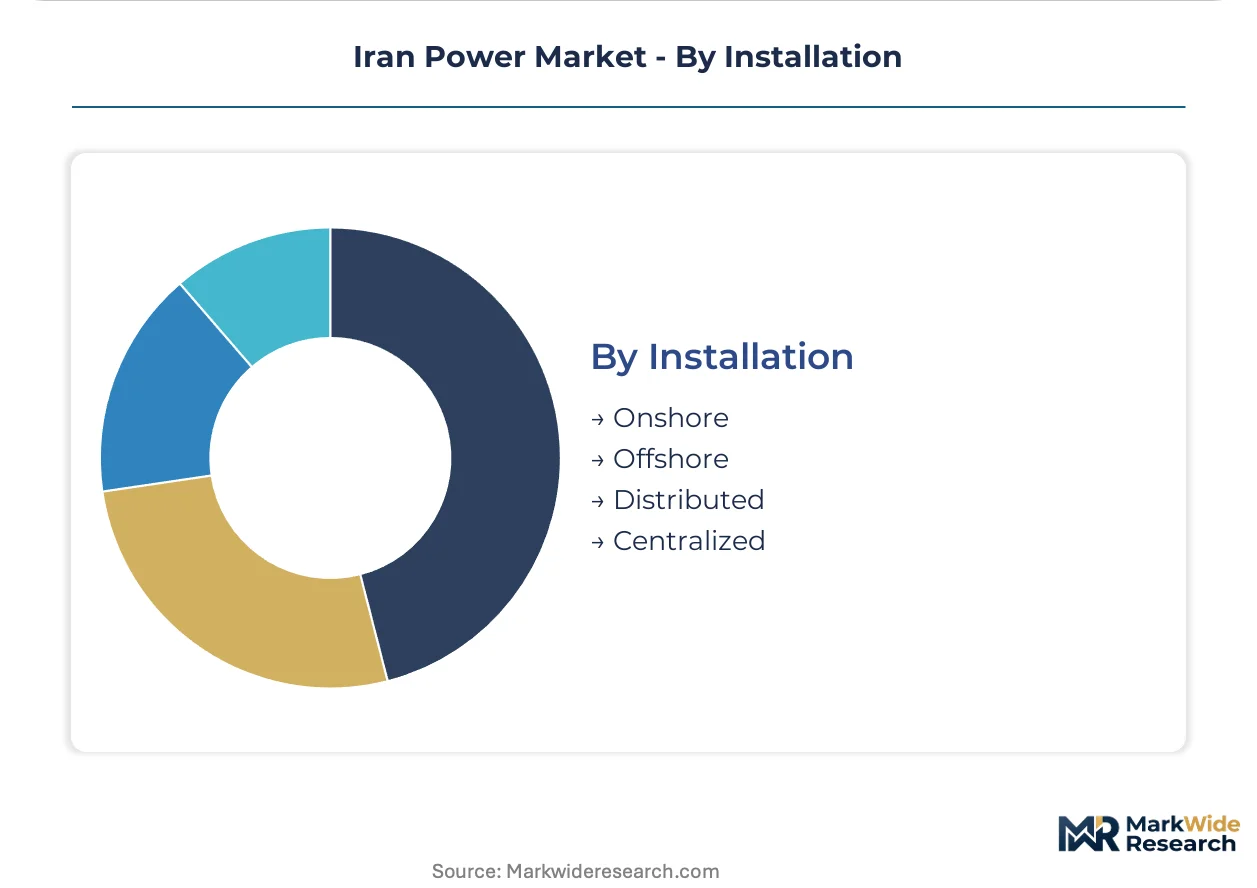
Centralized installations retain the dominant share, while Distributed configurations are gaining structural importance fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iran exports electricity to neighboring Iraq, Afghanistan, and Pakistan through cross-border transmission lines managed by the Ministry of Energy. These trade corridors anchor regional energy diplomacy and generate hard currency revenue streams.
Tehran Province
Tehran Province concentrates residential and commercial electricity demand, with air conditioning loads spiking summer consumption beyond grid capacity. SATBA administers feed-in tariff mechanisms for distributed solar installations feeding into the provincial distribution network. Urban density limits utility-scale renewable deployment, pushing developers toward rooftop photovoltaic systems.
Persian Gulf Coastal Corridor
The Persian Gulf coastal corridor hosts steel mills and petrochemical complexes expanding electricity offtake for metallurgy and chemicals production. The Ministry of Petroleum competes with power generators for natural gas feedstock, creating seasonal fuel availability volatility. Asaluyeh petrochemical complexes retrofit inlet air chilling systems to sustain gas turbine output through summer temperature peaks.
Kerman Province
Kerman Province offers high solar irradiance and land availability attracting utility-scale photovoltaic developers under SATBA power purchase agreements. Grid interconnection bottlenecks strand renewable output and compress realized margins for independent generators. Provincial distribution companies operate aging SCADA systems requiring synchronization upgrades for new capacity integration.
Yazd Province
Yazd Province combines desert solar resources with cement and steel industrial clusters seeking captive generation alternatives. Behind-the-meter gas turbines and solar arrays bypass grid reliability risks for producers negotiating shorter-tenor supply contracts. Transmission capacity expansion lags behind generation additions, creating curtailment risks for centralized projects.
Khorasan Razavi Province
Khorasan Razavi Province remains underpenetrated for utility-scale photovoltaic development despite superior irradiance metrics and available land banks. The Renewable Energy and Energy Efficiency Organization extends feed-in tariff eligibility to eastern provinces to diversify geographic capacity distribution. Mashhad industrial zones present distributed generation opportunities for developers partnering with domestic electronics assemblers.
Iran Power Market Competitive Landscape
Player mix skews toward integrated engineering conglomerates and provincial generation utilities with captive fuel access. Market structure concentrates around state-affiliated entities controlling generation licensing and grid interconnection standards. Two strategic archetypes dominate: vertically integrated equipment manufacturers with domestic assembly capabilities, and provincial distribution companies managing legacy thermal fleets. Competitive moves center on combined-cycle retrofit contracting and distributed solar engineering partnerships.
Within the integrated engineering tier, MAPNA Group anchors domestic gas turbine supply through manufacturing and EPC capabilities. Tabiran Co. occupies a position among specialized electrical equipment producers serving transmission upgrade requirements. KPV Solar Iran represents the emerging photovoltaic segment with module assembly and project development functions. These three entities exemplify the archetype spectrum spanning thermal legacy optimization and renewable transition.
| Leading Market Players |
|---|
| Tabiran Co. |
| Isfahan Power Generation Company |
| MAPNA Group |
| Azerbaijan Power Generation Company |
| Bandar Abbas Power Generation Company |
| Besat Power Generation Management Company |
| KPV Solar Iran |
| Zahedan Power Generation Company |
| Ardabil Electricity Distribution Company |
| Others |
Supply & Pricing Matrix
Take-or-pay contracts with annual reopener provisions now dominate industrial procurement in Iran, locking steel and petrochemical buyers into supply security while preserving price visibility against Ministry of Petroleum fuel allocation volatility. This contract structure feeds directly into equipment sourcing decisions, as developers weigh Chinese turbine controls against Western alternatives accessed through third-country channels.
Pricing Analysis
Combined-cycle gas turbine retrofits command premium pricing over greenfield thermal installations, while distributed solar undercuts centralized renewable bids after SATBA domestic content adjustments. Price differentiation separates MAPNA-serviced efficiency upgrades from Russian-equivalent alternatives with shorter maintenance intervals. Cost compression in imported switchgear intensifies as sanctions force reliance on non-Western supply channels. Industrial captive generators show lowest price sensitivity, absorbing reliability premiums to bypass grid instability.
Supply Chain Analysis
Extended lead times for gas turbine hot gas path components now stretch eighteen to twenty-four months through sanctioned banking corridors. Equipment procurement draws from China, Russia, and Turkey as primary supply nodes. Blade alloys, high-voltage transformers, and SCADA control systems face single-source vulnerability through restricted Western channels. Distribution runs through MAPNA Group's domestic assembly platform and provincial distribution company warehousing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran's power market is recovering from cyclical lows as industrial load growth in steel and petrochemicals restarts capacity expansion programs deferred during peak sanctions pressure.
For Market Incumbents: Compound defensive positioning through combined-cycle retrofit contracting and digital control system upgrades. MAPNA Group and provincial generation utilities must deepen backward integration into blade casting and inverter assembly before Chinese competitors capture domestic content thresholds. Threat substitution from distributed solar erodes centralized thermal margins; lever vertical integration into EPC services to capture project development premiums. For New Entrants and Emerging Players: Lead with utility-scale photovoltaic development in Khorasan Razavi Province, where irradiance metrics and land availability exceed current penetration. White-space targets include industrial captive generation for cement producers in Yazd and transformer manufacturing for transmission upgrades. Go-to-market angle: partnership with Shiraz electronics assemblers to satisfy SATBA domestic content mandates. For Investors and Strategic Acquirers: Capital is best deployed toward integrated engineering conglomerates with captive fuel access and licensed generation portfolios. Long-term viability hinges on sustained industrial electricity demand growth and sanctions relief trajectory. Acquisition target archetype: provincial distribution companies with stranded renewable interconnection rights. Signal to watch: Ministry of Energy licensing velocity for cross-border export capacity to Iraq and Pakistan.| Strategic Initiative | Industry Significance |
|---|---|
| Combined-Cycle Retrofit Contracting | MAPNA Group captures efficiency upgrade revenue as aging thermal fleets require modernization. |
| Domestic Content Partnership | Developers secure SATBA feed-in tariff eligibility through Shiraz and Tehran electronics assemblers. |
| Industrial Captive Generation Buildout | Steel and cement producers bypass grid reliability risks with behind-the-meter installations. |
| Cross-Border Export Capacity Expansion | Hard currency revenue streams anchor regional energy diplomacy with Iraq and Afghanistan. |
| Digital Control System Integration | Provincial distribution companies synchronize aging SCADA infrastructure with renewable additions. |
Research Methodology
Desk research of SATBA regulatory filings, Tavanir generation statistics, and Ministry of Energy licensing databases preceded structured interviews with IPP project developers, EPC contractors, utility planning officers, and gas turbine maintenance specialists. Secondary validation drew from customs trade records, provincial distribution company procurement disclosures, and cross-border electricity export agreements. Bottom-up project pipelines were triangulated against top-down fuel allocation forecasts.
Variance decomposition across fuel source, generation capacity tier, and regional grid type shaped analytical framework development over the projection horizon. CAGRs were derived from segment-level capacity addition trajectories and tariff-adjusted revenue modeling. Forecast inputs incorporated Ministry of Petroleum natural gas allocation schedules and SATBA feed-in tariff revision protocols.
The analysis sits within stated boundaries; outcomes outside sustained sanctions relief or abrupt fuel subsidy reform would require recalibration. Forecasts reflect documented assumptions regarding industrial load growth and equipment import channel stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Colombia Power Market
Power
Europe Submarine Power Cables Market
Power
High Voltage DC Power System Market
Power
Residential Micro Inverter Market
Power
Asia-Pacific Power Market
Power
Global Power Line Communication (PLC) Systems Market
Power
Middle East and Africa Combined Heat & Power Market
Power
India Power Market
Power
Spain Power Market
Power
Wind Turbine Drivetrain Market
Power
Global Marine Power Systems Market
Power
Asia-Pacific Power Purchase Agreement Market
Power
Europe Power Market
Power
Brazil Power Market
Power
Norway Power Market
Power
Malaysia Power EPC Market