
 IoT Device Management Platform Market | 2026-2036
IoT Device Management Platform Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Device Management Platform Market Outlook
Buyer concentration across industrial manufacturing is rebalancing as mid-sized factories fragment into platform adopters while automotive OEMs consolidate vendor relationships. Microsoft Azure IoT Central dominates cloud-native orchestration for multi-site deployments. AWS IoT Device Management anchors edge-to-cloud connectivity with deep integration into existing enterprise infrastructure. IBM Watson IoT Platform specializes in AI-driven anomaly detection for asset-intensive environments.
An IoT device management platform is a software layer that provisions, monitors, diagnoses, and secures connected endpoints through protocols such as MQTT and CoAP with over-the-air firmware delivery as a core functional parameter. Its primary commercial purpose is to maintain operational continuity across distributed device fleets while enforcing security policies at scale. Cloud-based deployment leads in new installations because manufacturers prioritize elastic scalability without capital-intensive server commitments. The security solution segment commands premium positioning as ransomware targeting operational technology networks intensifies compliance-driven procurement. LPWAN technology occupies a growing niche in agricultural and utility monitoring where cellular cost structures prove prohibitive.
The EU AI Act and GDPR impose algorithmic transparency and data residency mandates that reshape platform architecture decisions across European deployments. The US FCC governs spectrum allocation for unlicensed IoT radios, directly constraining which connectivity protocols platforms can reliably orchestrate. Stakeholders must monitor how NIST cybersecurity frameworks evolve to mandate software bill of materials disclosure for connected device supply chains.
Market Dynamics
Platform vendors face mounting pressure from the EU AI Act's algorithmic transparency mandates, which force architectural redesigns of predictive maintenance engines and anomaly detection systems across European industrial deployments.
Growth Catalysts
- GDPR data residency requirements:European manufacturers must localize device telemetry processing, creating demand for sovereign cloud instances and edge-native orchestration layers that keep data within national boundaries.
- Automotive OEM sensor proliferation:Connected vehicle programs in Germany generate massive fleet management contracts requiring real-time over-the-air firmware delivery and certificate lifecycle automation.
- LPWAN protocol maturation:Agricultural cooperatives and utility operators deploy NB-IoT and LoRaWAN-based monitoring at scale where cellular economics fail, expanding addressable device populations.
Market Restraints
- Silicon supply concentration:Edge gateway chipset availability hinges on Taiwanese foundry capacity, creating procurement bottlenecks for hardware-dependent platform rollouts.
- EU AI Act compliance costs:Algorithmic impact assessments and conformity documentation impose six-figure certification burdens on mid-sized platform vendors.
- Cellular module price volatility:5G RedCap component costs fluctuate with memory pricing, compressing margins for connectivity-inclusive platform bundles.
Strategic Opportunities
- India manufacturing automation:PLI scheme incentives for electronics production trigger demand for localized device management platforms serving contract manufacturers in Tamil Nadu and Karnataka.
- Digital twin convergence:Unity between real-time device telemetry and physics-based simulation models opens premium pricing for asset-intensive operators in process industries.
- CSRD sustainability reporting:Corporate emissions disclosure mandates create attach opportunities for platforms that meter energy consumption at the device level across distributed industrial estates.
Industry Challenges
- Embedded systems security expertise:Platform vendors struggle to hire firmware engineers with operational technology hardening skills as ransomware campaigns targeting industrial controllers intensify.
- brownfield integration complexity:Decades-old SCADA architectures in German automotive plants resist API-native connectivity, forcing expensive protocol translation gateway deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Device Management Platform Market |
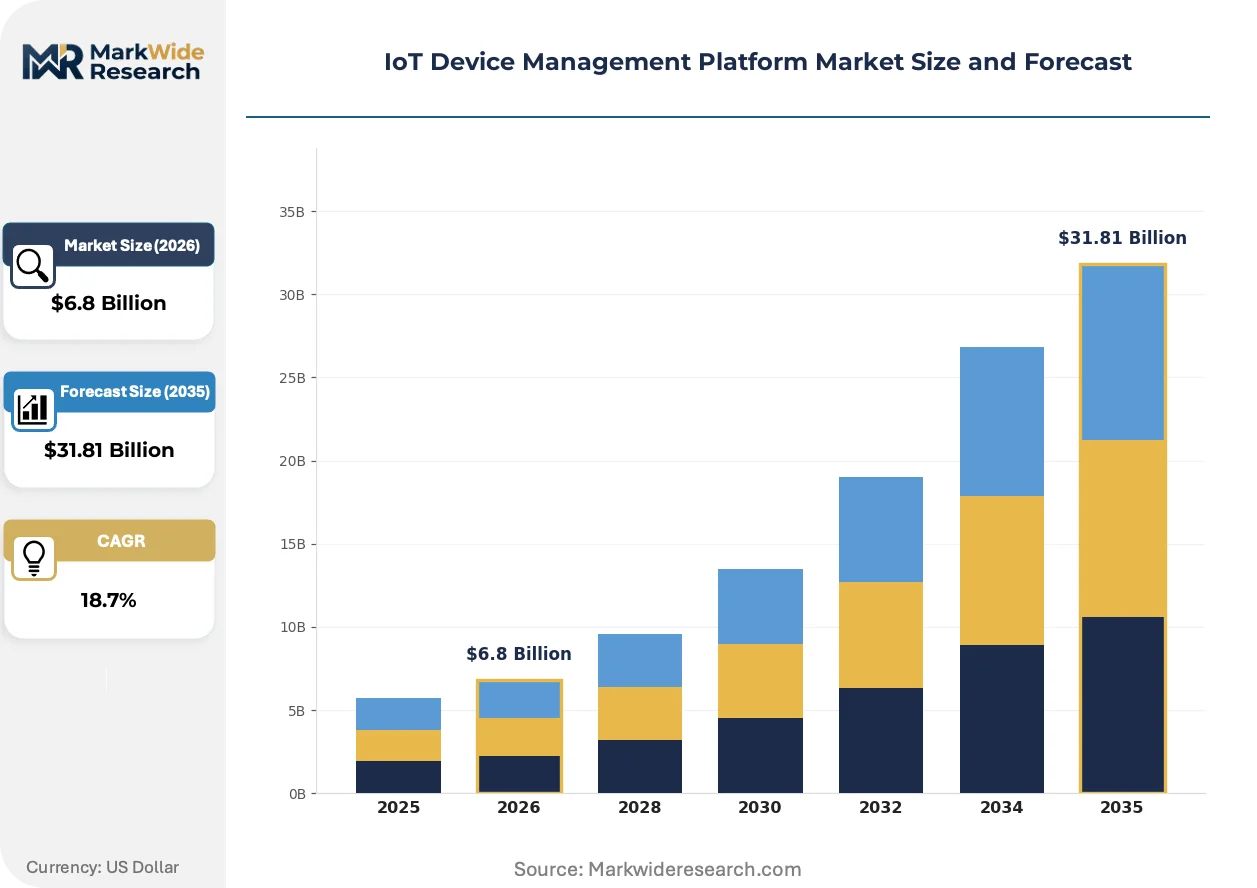
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.81 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Technology: LPWAN, Zigbee, Bluetooth, Wi-Fi End User: Manufacturing, Healthcare, Retail, Transportation Solution: Monitoring, Security, Analytics, Automation |
| Companies Covered | IBM Watson IoT Platform, Kaa IoT Platform, AWS IoT Device Management, Cisco IoT Connectivity Management Platform, Jamf Pro, Microsoft Azure IoT Central, HCLTech Decode, Portainer, Cumulocity IoT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Device Management Platform Market Strategic Shifts
Device management architectures are pivoting from cloud-centric models toward distributed intelligence as edge computing economics improve and latency requirements tighten across industrial control applications.
Edge-native AI inference is unifying local decision-making with centralized fleet governance. Automotive tier-one suppliers deploy tensor-optimized gateways that process vibration signatures at the machine rather than transmitting raw telemetry. This compression of compute geography reduces backhaul costs while satisfying EU AI Act requirements for explainable on-premise processing.
REACH substance restrictions on persistent organic pollutants are forcing hardware redesigns for outdoor IoT endpoints. Industrial sensor housings must eliminate certain flame retardants, triggering platform vendors to certify alternative enclosures and update device catalogs. German chemical manufacturers face the steepest compliance timelines given their large installed bases of legacy monitoring equipment.
Buying committees now mandate software bill of materials disclosure before platform procurement. NIST cybersecurity framework adoption among US industrial operators requires vendors to enumerate third-party dependencies and vulnerability exposure. This documentation burden favors established platforms with mature supply chain auditing over emerging entrants lacking dedicated compliance functions.
IoT Device Management Platform Market Segmentation
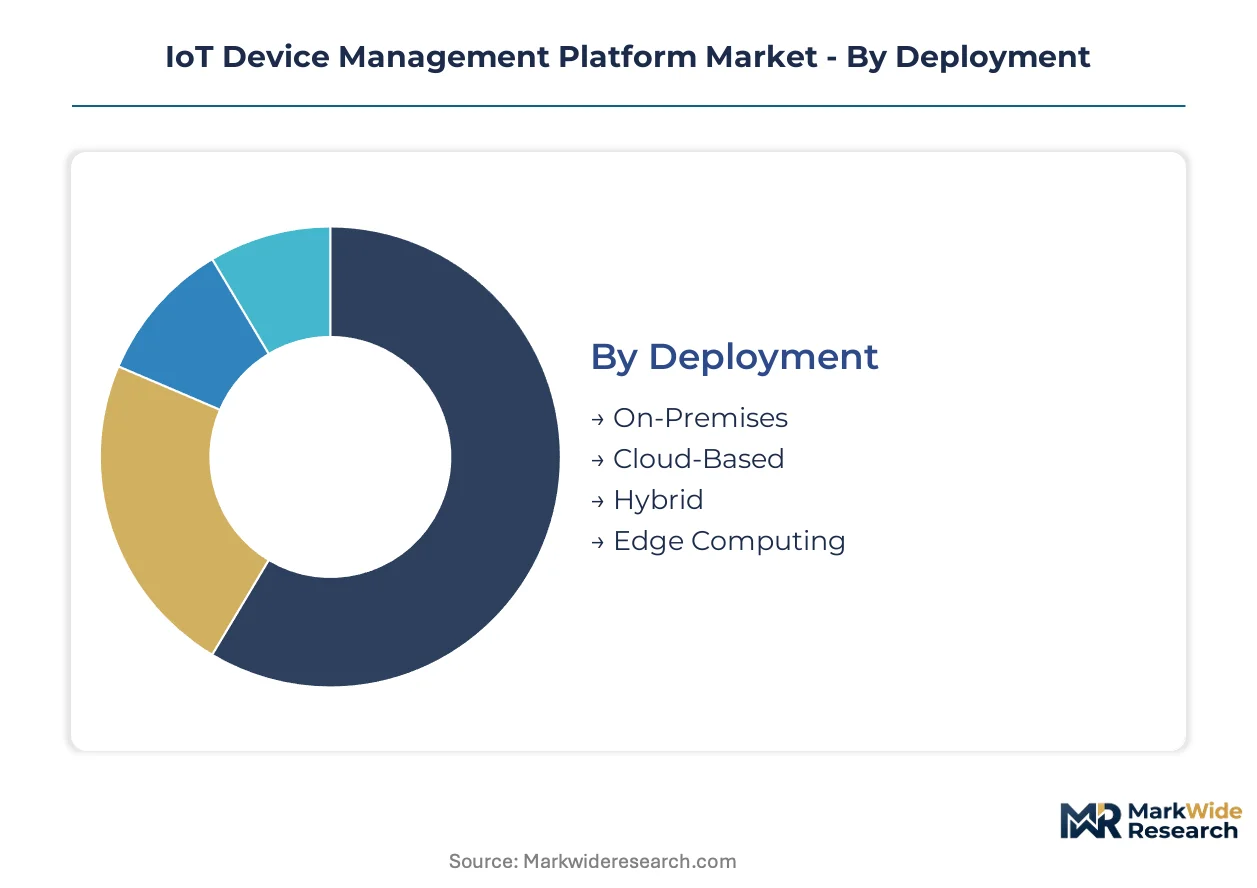
Deployment architecture determines total cost of ownership and compliance posture for connected device fleets. Platform selection across these dimensions locks manufacturers into specific upgrade cycles and integration obligations.
Deployment:
Upgrade cycles vary dramatically by infrastructure commitment, with cloud-native deployments enabling quarterly feature refreshes while on-premises installations stretch replacement intervals across multiple years.
- Cloud-Based:Elastic compute resources scale with device fleet expansion without capital expenditure. German automotive OEMs favor this model for multi-site predictive maintenance programs requiring rapid provisioning across supplier networks.
- Edge Computing:Tensor-optimized gateways process telemetry locally to satisfy EU AI Act explainability mandates. Manufacturing plants in Bavaria deploy these for sub-10-millisecond control loop latency on assembly lines.
- On-Premises:Dedicated server infrastructure maintains data sovereignty for defense and critical infrastructure operators.
- Hybrid:Workload splitting between local and remote processing balances latency against analytics depth.
Cloud-based deployments sit at the top of the volume ranking, with edge computing climbing the fastest.
Technology:
Protocol selection constrains device density, battery life, and geographic coverage for specific monitoring applications.
- LPWAN:NB-IoT and LoRaWAN enable decade-long battery life for sparse rural deployments. Agricultural cooperatives across the Netherlands deploy these for soil moisture monitoring where cellular tariffs would consume operating budgets.
- Wi-Fi:High-throughput local area connectivity dominates indoor industrial environments with existing infrastructure. German chemical manufacturers retrofit legacy sensor networks using Wi-Fi 6E for deterministic latency.
- Zigbee:Mesh topology suits building automation with self-healing network resilience.
- Bluetooth:Low-energy variants support proximity-based asset tracking and condition monitoring.
Wi-Fi holds the largest installed base, while LPWAN gains share fastest in agricultural and utility monitoring.
End User:
Industry verticals impose distinct latency, security, and integration requirements that reshape platform feature prioritization.
- Manufacturing:Predictive maintenance and digital twin integration command premium platform tiers. Automotive tier-one suppliers in Stuttgart require real-time vibration analysis across thousands of CNC machines.
- Healthcare:FDA and GDPR compliance mandates drive investment in certificate lifecycle automation and audit logging. Connected medical device fleets in Berlin hospitals demand 99.999% uptime guarantees.
- Transportation:Fleet telematics and over-the-air firmware delivery dominate procurement specifications.
- Retail:Inventory tracking and cold chain monitoring prioritize low-cost connectivity modules.
Manufacturing generates the highest contract values, with healthcare expanding most quickly on regulatory tailwinds.
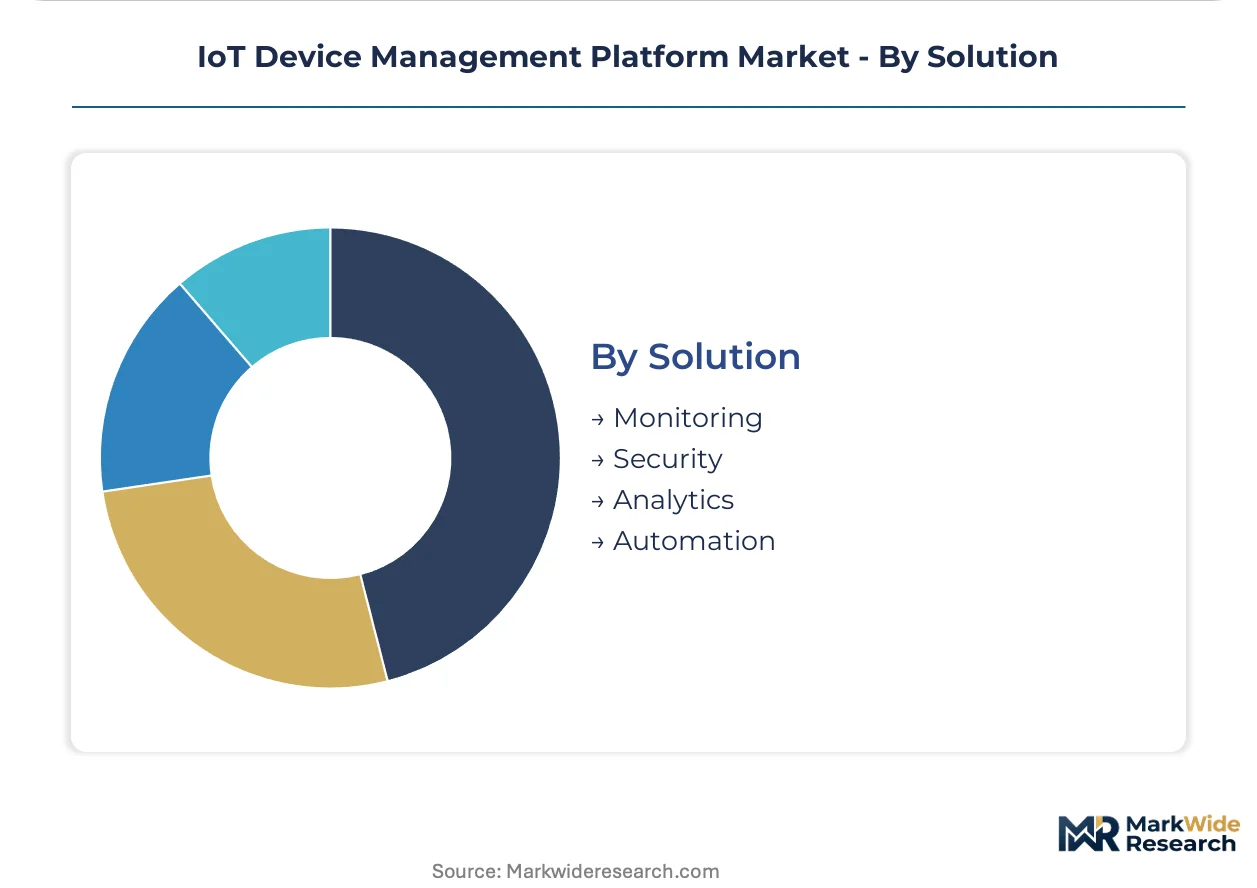
Solution:
Functional modules determine platform stickiness and renewal rates through embedded workflow integration.
- Security:Certificate management, firmware signing, and intrusion detection address ransomware targeting operational technology. NIST framework adoption among US industrial operators mandates software bill of materials disclosure.
- Analytics:AI-driven anomaly detection transforms raw telemetry into maintenance recommendations. EU AI Act transparency requirements force architectural redesigns of these engines for European deployments.
- Monitoring:Real-time device health dashboards and alerting form the baseline platform capability.
- Automation:Rule-based orchestration triggers actions across device fleets without human intervention.
Security commands premium pricing, with analytics showing the steepest expansion trajectory on AI integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive OEMs generate larger contract values than India's contract manufacturers, yet both geographies expand on divergent regulatory foundations and industrial automation timelines.
Germany
Automotive OEM sensor proliferation and predictive maintenance workflows drive enterprise-scale deployments across supplier networks. The EU AI Act and GDPR impose algorithmic transparency and data residency mandates that reshape platform architecture decisions. Stuttgart's tier-one suppliers require real-time vibration analysis across thousands of CNC machines, anchoring cloud-native orchestration demand.
United States
Industrial manufacturers prioritize elastic scalability without capital-intensive server commitments, favoring cloud-based deployments. The FCC governs spectrum allocation for unlicensed IoT radios, directly constraining which connectivity protocols platforms orchestrate. NIST cybersecurity framework adoption among industrial operators mandates software bill of materials disclosure, favoring established vendors with mature compliance functions.
India
PLI scheme incentives for electronics production trigger demand for localized device management platforms serving contract manufacturers. The country's national electronics regulator enforces localization requirements for critical infrastructure deployments. Tamil Nadu and Karnataka manufacturing clusters adopt edge-native platforms to satisfy data sovereignty expectations from multinational OEMs.
China
Industrial conglomerates expand platform adoption to manage sensor fleets across state-owned manufacturing estates. MIIT standards and dual carbon goals accelerate energy metering at the device level for emissions disclosure. Yangtze River Delta electronics manufacturers deploy hybrid architectures balancing latency against analytics depth.
Netherlands
Agricultural cooperatives deploy LPWAN-based monitoring at scale where cellular economics prove prohibitive for sparse rural deployments. REACH substance restrictions force hardware redesigns for outdoor IoT endpoints, triggering platform vendors to certify alternative enclosures. Dutch greenhouse operators in the Randstad region integrate soil moisture sensors with decade-long battery life expectations.
IoT Device Management Platform Market Competitive Environment
US-based cloud hyperscalers anchor one tier; European industrial specialists and open-source platforms hold differentiated positions in compliance-heavy and developer-centric segments respectively. The vendor base concentrates around three strategic archetypes: cloud-native orchestration providers with multi-site deployment capabilities, edge-optimized platforms serving latency-sensitive industrial control, and API-centric solutions targeting brownfield integration complexity. Competitive moves center on strategic partnerships with semiconductor vendors and portfolio diversification into digital twin convergence.
Within the cloud-native tier, Microsoft Azure IoT Central and AWS IoT Device Management represent the scale-driven deployment model, while IBM Watson IoT Platform exemplifies AI-driven anomaly detection specialization for asset-intensive environments. These three entities occupy positions reflecting divergent bets on where platform value accumulates—elastic infrastructure, embedded intelligence, or industrial domain expertise.
| Leading Market Players |
|---|
| IBM Watson IoT Platform |
| Kaa IoT Platform |
| AWS IoT Device Management |
| Cisco IoT Connectivity Management Platform |
| Jamf Pro |
| Microsoft Azure IoT Central |
| HCLTech Decode |
| Portainer |
| Cumulocity IoT |
| Others |
Value Chain & Pricing Dynamics
German automotive OEM procurement committees anchor platform pricing power through multi-year enterprise contracts that bundle edge hardware, cloud orchestration, and predictive maintenance modules into unified subscription tiers. Their concentration across Stuttgart and Munich supplier networks enforces volume-discount leverage that compresses margins for mid-sized platform vendors lacking comparable scale.
Pricing Analysis
Capacity additions in India's Tamil Nadu electronics manufacturing clusters are reshaping price floors for edge gateway hardware that platforms bundle with software subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled predictive maintenance tiers from basic monitoring dashboards, with certification under EU AI Act conformity procedures commanding fifteen to twenty percent premiums. Cost compression in standard-tier connectivity modules is intensifying because 5G RedCap component supply fluctuates with memory spot markets. Mid-sized industrial manufacturers in Bavaria show highest price sensitivity, while German automotive OEMs prioritize latency guarantees and certificate lifecycle automation over per-unit costs.
Supply Chain Analysis
India's PLI scheme local-content mandates and China's MIIT cybersecurity certification requirements are reshaping sourcing patterns for platform vendors serving Asian manufacturing clusters. Edge gateway production draws from Taiwan, China, and South Korea for tensor-optimized chipsets, with firmware signing modules and LoRaWAN radio components as critical dependencies. Single-source vulnerability concentrates in Taiwanese foundry capacity for industrial-grade processors. Distribution runs through systems integrators with OT-hardening expertise, particularly in German automotive supplier networks and Indian electronics manufacturing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform procurement has shifted toward premium specifications as EU AI Act compliance and NIST cybersecurity framework adoption elevate algorithmic transparency and software bill of materials disclosure to mandatory evaluation criteria. This quality migration favors vendors with mature compliance functions and documented supply chain auditing over cost-optimized entrants.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Accelerate EU AI Act conformity documentation and NIST framework alignment to widen compliance moats against emerging cloud-native challengers. Acquire specialized OT security firms to address firmware engineering talent scarcity intensified by ransomware campaigns targeting industrial controllers. For New Entrants and Emerging Players: Edge-native AI inference for sub-10-millisecond control loops offers the most penetrable wedge into German automotive tier-one supplier networks resistant to cloud-centric latency profiles. Target agricultural cooperatives in the Netherlands with LPWAN-optimized platforms where cellular economics fail. Lead with developer-centric API portfolios that reduce brownfield SCADA integration complexity. For Investors and Strategic Acquirers: Cloud hyperscalers with industrial vertical specialization are the most active acquirers in this space, seeking edge-optimized platforms to complement centralized orchestration offerings. Acquisition target archetype: mid-cap vendors with documented EU AI Act compliance and established relationships with German automotive procurement committees. Watch for inflection when NIST mandates software bill of materials disclosure for federal contractor supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies edge-native inference with centralized fleet governance for EU AI Act compliance. |
| Strategic Partnership | Semiconductor vendor alliances secure tensor-optimized gateway supply for automotive OEMs. |
| Acquisition of Specialist Firm | OT security expertise addresses firmware engineering scarcity in ransomware-hardened deployments. |
| Geographic Expansion | Localized instances in Tamil Nadu satisfy PLI scheme and multinational OEM data sovereignty requirements. |
| Product Launch | Digital twin convergence modules open premium pricing for process industry asset-intensive operators. |
Study Parameters
Multiple input streams — primary interviews with IoT platform engineering directors, automotive OEM procurement leads, and industrial cybersecurity specialists; secondary validation through hyperscaler capex disclosures, EU regulatory filings, and semiconductor trade data; plus customs records for edge gateway hardware flows — were reconciled through bottom-up device fleet modeling and top-down market sizing triangulation.
Historical deployment trajectories across German automotive supplier networks were cross-referenced against panel input from platform vendor sales leadership to anchor growth assumptions. Segmentation dimensions modeled span deployment architecture, connectivity protocol, end-use vertical, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted fleet expansion curves and replacement cycle analysis, with EU AI Act implementation timelines and India PLI scheme incentive windows as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwanese foundry capacity constraints, 5G RedCap component price volatility, and evolution of NIST cybersecurity framework mandates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
Iiot (Industrial Internet of Things) Technology Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
Intelligent IoT Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
IoT Integration Market