
 Global IoT in Automobile Market | 2026-2036
Global IoT in Automobile Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT in Automobile Market Foresight
The embedded software layer is fragmenting into domain-specific architectures for powertrain, cockpit, and chassis control. Robert Bosch GmbH leverages its cross-domain ECU portfolio to anchor integrated IoT gateway solutions across multiple vehicle platforms. NXP Semiconductors specializes in secure vehicle networking silicon, while Intel Corporation competes through its Mobileye subsidiary's edge-computing vision stacks for autonomous driving.
IoT in automobile denotes the ecosystem of connected sensors, embedded controllers, and cloud-linked platforms that enable real-time data exchange between vehicles, infrastructure, and fleet management systems, typically operating over cellular V2X protocols with sub-100-millisecond latency requirements for safety-critical functions. Infotainment Systems and Advanced Driver-Assistance Systems command the dominant margin pools as software-defined features generate recurring service revenue streams. Fleet Management applications are expanding fastest among end-use verticals as logistics operators mandate real-time asset visibility and predictive maintenance to minimize unscheduled downtime.
The EU AI Act, UNECE WP.29 cybersecurity regulations, and China's MIIT connected-vehicle standards collectively reshape product development roadmaps by mandating encrypted over-the-air update capabilities and standardized data logging for incident reconstruction. NHTSA's pending software transparency requirements in the United States will further extend compliance obligations for OEMs selling into North America. Stakeholders must monitor divergence between regional certification regimes when architecting scalable IoT platforms intended for multi-market deployment.
Market Dynamics
Fleet operators are mandating predictive maintenance platforms that compress vehicle downtime through real-time sensor telemetry, forcing OEMs to rearchitect embedded software stacks around over-the-air update capabilities.
Growth Catalysts
- UNECE WP.29 cybersecurity mandates:European regulators now require encrypted telematics architectures and standardized data logging, accelerating Tier-1 supplier investment in compliant gateway ECUs.
- Fleet Management vertical expansion:Logistics operators across Germany, the United States, and China are deploying connected vehicle platforms to enable real-time asset visibility and route optimization.
- Cellular V2X protocol maturation:Sub-100-millisecond latency specifications for safety-critical functions are now technically achievable, unlocking autonomous emergency braking and intersection collision avoidance deployments.
Market Restraints
- Semiconductor supply concentration:Advanced node silicon for automotive networking and edge computing remains concentrated among a limited set of foundry operators in Taiwan and South Korea.
- Regulatory fragmentation:Divergent certification timelines between the EU AI Act, China's MIIT connected-vehicle standards, and NHTSA pending software transparency requirements extend product development cycles.
- Legacy vehicle integration costs:Retrofitting pre-2020 vehicle platforms with compliant telematics hardware and secure OTA infrastructure demands substantial redesign of power distribution and gateway modules.
Strategic Opportunities
- India commercial vehicle digitization:The country's PLI scheme for automotive electronics and accelerating freight corridor development create concentrated demand for connected fleet platforms.
- Software-defined revenue streams:Infotainment and ADAS feature unbundling enables subscription-based monetization models that decouple revenue from unit production cycles.
- Edge-to-cloud architecture convergence:Integration of vehicle-side inference engines with centralized fleet analytics platforms is compressing latency for predictive maintenance alerts.
Industry Challenges
- Embedded cybersecurity talent scarcity:Automotive engineering clusters in Stuttgart, Detroit, and Shanghai are competing for limited pools of specialists capable of implementing UNECE-compliant secure boot and intrusion detection systems.
- Multi-market certification complexity:OEMs architecting scalable IoT platforms must simultaneously satisfy EU AI Act algorithmic transparency requirements, Chinese data localization mandates, and NHTSA incident reconstruction logging standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT in Automobile Market |
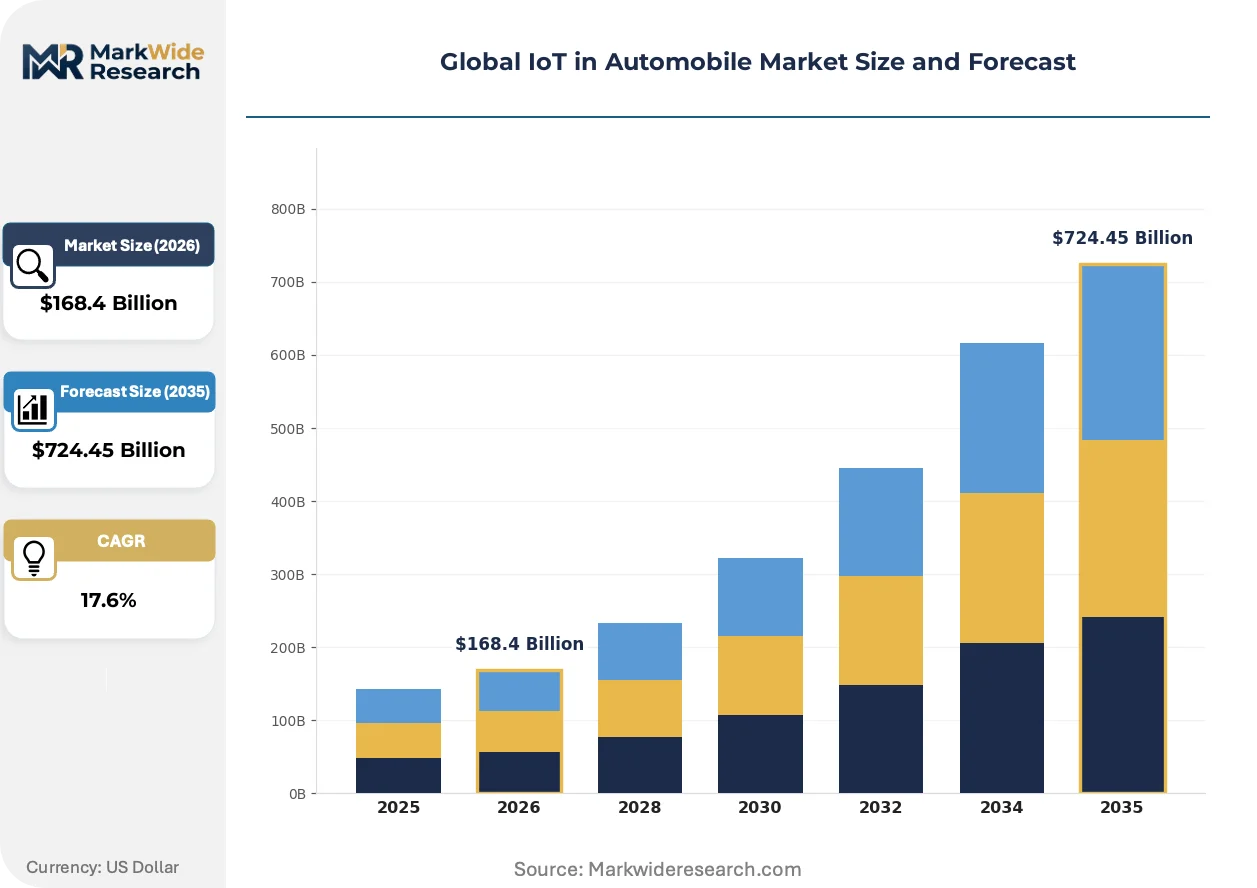
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $724.45 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telematics Units, Infotainment Systems, Advanced Driver-Assistance Systems, Vehicle Tracking Devices, Connectivity Modules Technology: Bluetooth, Cellular Networks, Wi-Fi, Dedicated Short-Range Communications, Satellite Communication Application: Fleet Management, Predictive Maintenance, Remote Diagnostics, Usage-Based Insurance, Smart Parking End User: Vehicle Manufacturers, Fleet Operators, Car Rental Services, Logistics Companies, Aftermarket Providers |
| Companies Covered | Robert Bosch GmbH, NXP Semiconductors, Intel Corporation, Texas Instruments, Harman International Industries, TomTom International, STMicroelectronics, Infineon Technologies, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT in Automobile Market Shifts & Advancements
Automotive IoT architectures are fragmenting into domain-specific software stacks that decouple hardware from feature deployment, enabling faster iteration cycles and reducing platform lock-in for fleet operators.
Software-defined vehicle platforms are hybridizing traditional powertrain, chassis, and cockpit control domains into unified compute architectures. Tier-1 suppliers and OEMs in Germany and Japan are adopting zonal E/E architectures that consolidate distributed ECUs into fewer, more powerful domain controllers. This convergence is compressing wiring harness complexity and enabling centralized over-the-air feature deployment across multiple vehicle programs.
The EU AI Act's risk-based classification system for automated driving functions is forcing algorithmic transparency and human oversight mandates into product roadmaps. European OEMs must now document training data provenance and model performance metrics for type approval. This regulatory pressure is most acute for Level 2+ and Level 3 automation programs targeting German and French passenger vehicle markets.
Commercial fleet operators are consolidating vendor relationships around integrated telematics providers that bundle hardware, connectivity, and analytics. This concentration is displacing point-solution vendors in North American and European logistics markets. Large trucking and delivery fleets now prioritize single-platform visibility across mixed-asset pools over best-of-breed component sourcing.
Global IoT in Automobile Market Segmentation
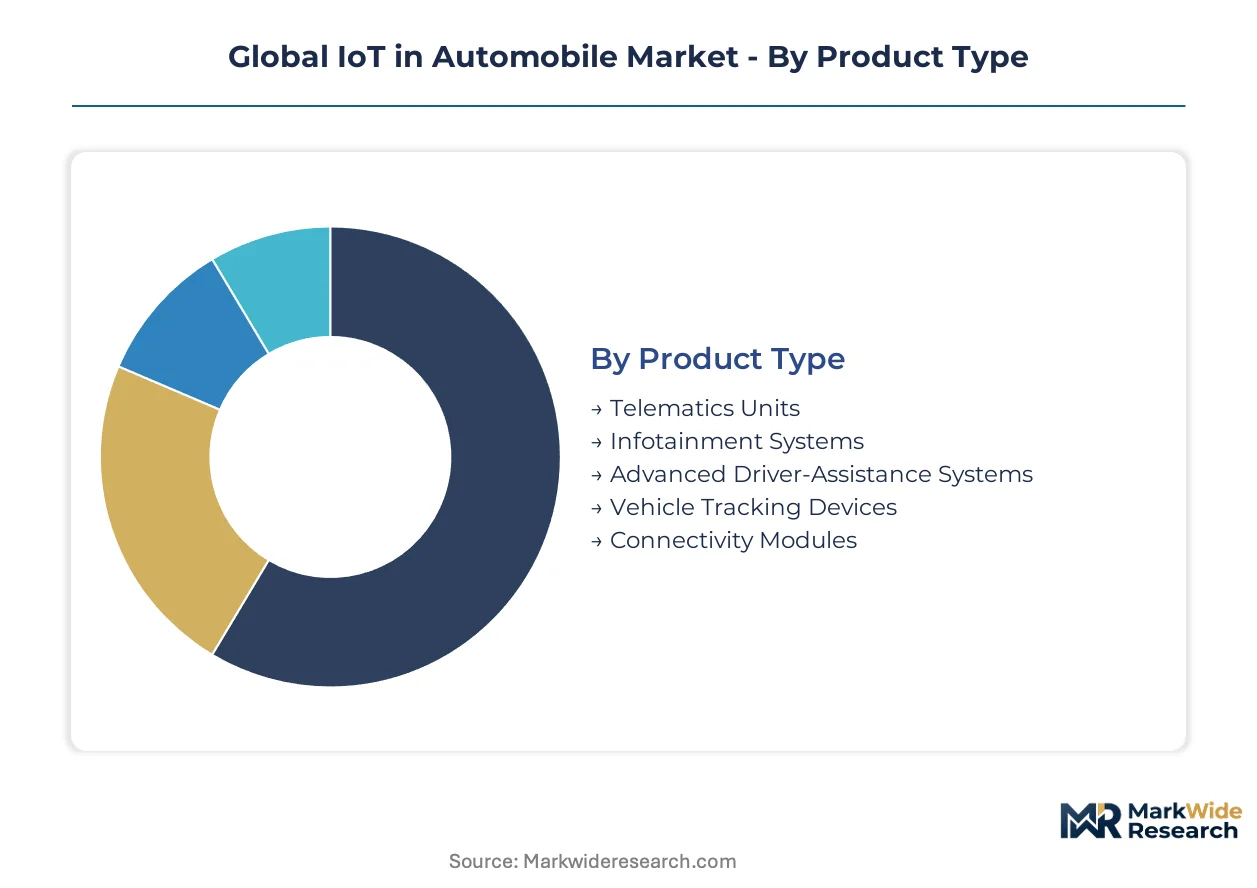
Automotive IoT segmentation reveals how hardware specialization, protocol diversity, and end-use economics fragment procurement patterns across vehicle programs. Understanding these dimensions clarifies where OEMs concentrate R&D versus where fleet operators drive specification requirements.
Product Type:
Use-case spectrum spans passive data logging to active vehicle control, with margin profiles diverging sharply between entertainment-centric and safety-critical domains.
- Telematics Units:Embedded gateway modules integrate cellular modems, GNSS receivers, and CAN bus interfaces for real-time vehicle telemetry transmission. Demand concentrates in German and US commercial fleets where UNECE WP.29 cybersecurity mandates force encrypted architecture upgrades.
- Infotainment Systems:Cockpit-integrated computing platforms deliver navigation, media streaming, and voice interaction through touchscreen and haptic interfaces. European and Chinese passenger OEMs prioritize these systems for subscription revenue generation and brand differentiation.
- Advanced Driver-Assistance Systems:Sensor fusion platforms combining radar, camera, and lidar inputs for automated emergency braking and lane-keeping assistance.
- Vehicle Tracking Devices:Standalone GPS-cellular units for stolen vehicle recovery and asset monitoring in rental and logistics fleets.
- Connectivity Modules:Compact radio units enabling V2X communication and cloud backhaul for distributed sensor networks.
Established volume favors Infotainment Systems; emerging adoption favors Telematics Units as regulatory compliance accelerates fleet retrofit cycles.
Technology:
Protocol selection hinges on latency tolerance, coverage requirements, and spectrum allocation regimes that vary across national regulators.
- Cellular Networks:LTE and 5G NR protocols deliver wide-area connectivity for over-the-air updates and cloud analytics with sub-100-millisecond latency achievable in urban deployments. German automotive clusters and Chinese MIIT certification programs drive specification convergence around C-V2X standards.
- Dedicated Short-Range Communications:IEEE 802.11p-based V2X enables direct vehicle-to-vehicle and vehicle-to-infrastructure messaging without cellular infrastructure dependency. US DOT pilot programs and European C-ITS corridors concentrate deployment investment.
- Bluetooth:Low-energy protocols for smartphone pairing and in-cabin device connectivity.
- Wi-Fi:High-throughput local networking for software updates and media streaming in depot environments.
- Satellite Communication:L-band and Ku-band links ensuring connectivity across remote freight corridors and maritime vehicle transport.
Cellular Networks capture dominant deployment scale; Dedicated Short-Range Communications gain regulatory preference for safety-critical autonomy functions.
Application:
Functional deployment separates cost-reduction imperatives in commercial logistics from risk-transfer mechanisms in consumer insurance markets.
- Fleet Management:Integrated platforms combining real-time location tracking, driver behavior analytics, and fuel consumption optimization for logistics operators. US trucking fleets and German freight corridors mandate these systems for regulatory compliance and insurance premium reduction.
- Predictive Maintenance:Machine learning models applied to powertrain and chassis sensor streams forecasting component failure before roadside breakdown. Indian commercial vehicle operators under PLI scheme incentives represent expanding demand concentration.
- Remote Diagnostics:Cloud-based fault code interpretation and repair guidance reducing dealership service visits.
- Usage-Based Insurance:Telematics-derived driving scores enabling dynamic premium pricing for individual motorists.
- Smart Parking:Sensor-guided space identification and automated payment integration reducing urban congestion.
Fleet Management commands current implementation scale; Predictive Maintenance demonstrates steepest expansion trajectory as sensor costs decline and analytics platforms mature.
End User:
Procurement authority distributes across vehicle lifecycle stages, from factory-integrated specifications to aftermarket retrofit demand.
- Vehicle Manufacturers:OEMs specifying embedded IoT architectures during platform development, balancing unit cost against feature monetization potential. Stuttgart and Detroit engineering clusters concentrate specification authority for global vehicle programs.
- Fleet Operators:Logistics and delivery companies mandating telematics visibility across mixed-asset pools, often overriding OEM defaults with third-party hardware. German postal and US long-haul trucking fleets drive standardization around open API platforms.
- Car Rental Services:Short-term mobility providers prioritizing stolen vehicle recovery and automated rental return verification.
- Logistics Companies:Supply chain operators integrating vehicle telematics with warehouse management and customer delivery notification systems.
- Aftermarket Providers:Independent installers retrofitting legacy vehicle populations with OBD-port and hardwired connectivity solutions.
Vehicle Manufacturers retain design-in control for new platforms; Fleet Operators exert growing procurement leverage through consolidated vendor negotiations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a substantial automotive IoT trade surplus through Tier-1 supplier exports, while the United States and China balance significant import dependence in semiconductor components against growing domestic telematics platform development.
United States
Long-haul trucking fleets and last-mile delivery operators mandate real-time asset visibility platforms across mixed-vehicle pools. NHTSA pending software transparency requirements are accelerating OEM investment in compliant data logging architectures. Detroit engineering clusters concentrate specification authority for connected vehicle programs targeting North American markets.
Germany
Commercial freight corridors and postal logistics networks drive concentrated demand for predictive maintenance and route optimization systems. EU AI Act algorithmic transparency mandates and UNECE WP.29 cybersecurity regulations reshape product roadmaps for Level 2+ automation programs. Stuttgart automotive clusters anchor cross-domain ECU development and integrated gateway solution testing.
China
Domestic EV manufacturers and ride-hailing platforms deploy connected vehicle infrastructure at scale for fleet optimization and autonomous driving data collection. MIIT connected-vehicle standards mandate encrypted architectures and localized data processing for type approval. Yangtze River Delta manufacturing bases concentrate telematics hardware production and V2X protocol certification.
India
Commercial vehicle operators under PLI scheme incentives accelerate digitization across freight corridors and logistics networks. Central government automotive electronics production-linked incentives reduce import dependence for gateway modules and connectivity hardware. Tamil Nadu and Gujarat industrial corridors host expanding testing facilities for fleet management platform localization.
Japan
Automotive OEMs integrate IoT architectures into zonal E/E designs for hybrid and electric vehicle platforms targeting domestic and export markets. METI standards for connected vehicle cybersecurity and data governance align with UNECE frameworks for multi-market certification. Nagoya engineering clusters specialize in sensor fusion platforms and edge-computing vision stacks.
Global IoT in Automobile Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of delivering hardware-software bundles across multiple vehicle domains. Tier-1 automotive suppliers and semiconductor specialists dominate specification authority, while software-defined vehicle startups challenge incumbent positions in analytics and cloud integration. Strategic archetypes include cross-domain ECU integrators, secure networking silicon providers, and edge-computing vision specialists. Dominant competitive moves encompass vertical integration into semiconductor fabrication partnerships and geographic expansion through regional certification laboratories.
Among Germany-based Tier-1 suppliers, Robert Bosch GmbH and Continental AG exemplify integrated gateway solution providers spanning powertrain, chassis, and cockpit control domains. NXP Semiconductors anchors the secure vehicle networking silicon archetype through specialized automotive-grade semiconductor portfolios. These three companies represent distinct competitive positions: full-stack system integration, component-level security specialization, and scalable multi-platform deployment capability.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| NXP Semiconductors |
| Intel Corporation |
| Texas Instruments |
| Harman International Industries |
| TomTom International |
| STMicroelectronics |
| Infineon Technologies |
| Continental AG |
| Others |
Supply & Pricing Matrix
Stuttgart automotive engineering clusters anchor Tier-1 supplier pricing power through concentrated gateway ECU production, compressing margins for downstream fleet operators seeking compliant telematics architectures under UNECE WP.29 mandates.
Pricing Analysis
Next-generation 5G-V2X modules command substantial premiums over legacy 4G telematics units, while economy-tier OBD-port retrofit devices face steep cost compression. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from logistics operators. Pricing pressure stems from semiconductor foundry capacity constraints in Taiwan and South Korea, forcing OEMs to absorb input cost volatility. Fleet operators exhibit highest price sensitivity for aftermarket retrofits, while vehicle manufacturers prioritize feature monetization over unit cost in factory-integrated specifications.
Supply Chain Analysis
Advanced node silicon feedstock draws from Taiwan Semiconductor Manufacturing and Samsung Foundry operations, with automotive-grade networking chips additionally sourced from NXP Semiconductors fabrication partnerships in Singapore and Germany. Raw material dependencies span silicon wafers, rare earth elements for magnet assemblies, and specialized substrates for high-temperature ECU operation. Single-source vulnerability concentrates in 7nm and 5nm automotive processor supply, where qualified alternative foundries remain limited. Distribution runs through Tier-1 system integrators bundling hardware, embedded software, and cloud connectivity into consolidated platform offerings for OEM direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats as UNECE WP.29 certification requirements and EU AI Act compliance timelines lock in incumbent supplier relationships through multi-year platform development cycles.
For Market Incumbents: Pre-empt margin erosion from software-defined vehicle startups by deepening embedded cybersecurity capabilities and securing exclusive semiconductor allocation agreements with Taiwan and South Korea foundries. Accelerate zonal E/E architecture consolidation to displace point-solution competitors in cockpit and chassis integration. For New Entrants and Emerging Players: Build out India commercial vehicle digitization as the most penetrable geography, targeting PLI scheme beneficiaries in Tamil Nadu and Gujarat freight corridors with localized predictive maintenance platforms. Pursue white-label partnerships with European aftermarket distributors to bypass OEM design-in barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors secure vehicle networking specialists with established UNECE certification track records and multi-OEM qualification status. Long-term viability hinges on algorithmic transparency capabilities for EU AI Act compliance. Monitor NHTSA software transparency rulemaking as the critical inflection signal for North American market access requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables subscription revenue streams decoupled from production cycles for Stuttgart and Detroit OEMs. |
| Battery Supply Agreement | Secures lithium-ion cell allocation for EV-integrated telematics power management systems. |
| Geographic Manufacturing Footprint | Establishes local assembly presence in India PLI corridors to capture freight digitization demand. |
| Platform Standardization | Reduces ECU variant complexity across multiple vehicle programs for German Tier-1 suppliers. |
| Charging Infrastructure Partnership | Integrates vehicle telematics with grid communication protocols for fleet energy optimization. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement directors, fleet management operators, and automotive semiconductor specialists and refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed suppliers, and UNECE regulatory submission records. Bottom-up unit economics triangulated with top-down market sizing across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling adoption curves for telematics units, infotainment systems, and ADAS platforms through vehicle production forecasts and fleet operator procurement surveys. CAGRs were derived from segment-level growth trajectory synthesis. Key inputs included cellular V2X protocol certification timelines, semiconductor foundry capacity expansion announcements, and regulatory compliance deadline clustering.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese telematics platform providers or accelerated EU AI Act enforcement would shift outcomes beyond modeled ranges. Cross-checking against vehicle registration data and fleet operator capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
Enterprise IoT Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market