
 IoT in BFSI Market | 2026-2036
IoT in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
IoT in BFSI Market Analysis
Retail banks are collapsing the historical dominance of investment firms as the primary buyer archetype for IoT-enabled infrastructure. Cisco Systems leverages its edge networking portfolio to anchor branch transformation projects across North American banking networks. IBM Corporation sustains deep vertical integration through its Watson IoT platform combined with cybersecurity services purpose-built for financial workloads. Microsoft Corporation competes aggressively via Azure IoT Hub deployments that integrate with existing enterprise banking software ecosystems.
IoT in BFSI encompasses the deployment of internet-connected sensors, edge devices, and analytics platforms within banking, financial services, and insurance operations to enable real-time data collection, automated decision-making, and predictive risk assessment. These systems typically operate on sub-100 millisecond latency thresholds for fraud detection and employ AES-256 encryption standards to protect transactional data streams across distributed branch networks. Security Solutions within the solution segment dominates procurement budgets as institutions confront escalating cyber threats against ATM fleets and mobile banking endpoints. Customer Engagement applications are expanding fastest among application categories, driven by beacon technology and biometric sensors that personalize in-branch experiences. Edge Computing technology is capturing disproportionate investment as banks seek to process sensitive transactions locally rather than routing all data through centralized cloud infrastructure.
The EU AI Act, GDPR, and PCI-DSS standards collectively constrain how European and multinational institutions architect IoT data pipelines, mandating algorithmic transparency for automated credit decisions and strict localization of biometric data storage. The SEC's cybersecurity disclosure rules and the Federal Reserve's operational resilience guidance are forcing US-based banks to document IoT device inventories and incident response protocols in regulatory filings. Stakeholders must monitor how fragmented compliance obligations across jurisdictions will influence platform standardization decisions and vendor consolidation trajectories.
Market Dynamics
Edge computing architectures are collapsing the centralized cloud dependency that historically governed financial IoT deployments, forcing institutions to reconfigure data sovereignty, latency requirements, and vendor relationships simultaneously.
Growth Catalysts
- EU AI Act transparency mandates:Automated credit decision systems must now maintain explainable algorithmic logs, driving demand for IoT sensor networks that capture granular behavioral data streams for audit trails.
- Branch automation imperatives:Retail banking networks are deploying beacon arrays and biometric terminals to collapse wait times and personalize service delivery at physical locations.
- Real-time fraud detection:Sub-100 millisecond latency thresholds for transaction verification are pulling edge infrastructure investment into ATM fleets and mobile banking endpoints.
Market Restraints
- GDPR biometric data localization:European institutions must maintain physical storage boundaries for fingerprint and facial recognition templates, fragmenting cloud architectures and raising compliance costs.
- Semiconductor supply concentration:Edge device manufacturing depends on concentrated foundry capacity in East Asia, exposing deployment timelines to geopolitical disruption risks.
- AES-256 encryption overhead:Distributed branch networks face computational bottlenecks when encrypting high-velocity transactional data streams across thousands of endpoints.
Strategic Opportunities
- Insurance telematics expansion:Usage-based auto and property policies are creating fresh demand for connected vehicle and smart home sensor integrations that feed dynamic risk pricing models.
- 5G network slicing:Mobile operators are offering isolated bandwidth partitions with guaranteed quality-of-service levels, enabling banks to run critical IoT workloads on shared infrastructure with deterministic performance.
- India's digital banking push:The country's central bank and SEBI are accelerating financial inclusion mandates that reward institutions deploying low-cost connected kiosks in underbanked rural districts.
Industry Challenges
- Legacy core banking integration:Mainframe-era transaction processing systems require expensive middleware layers to ingest real-time sensor feeds, stretching IT budgets and implementation timelines.
- PCI-DSS certification cycles:Connected payment terminals must complete lengthy security audits before deployment, slowing product refresh rates and freezing vendor selection decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT in BFSI Market |
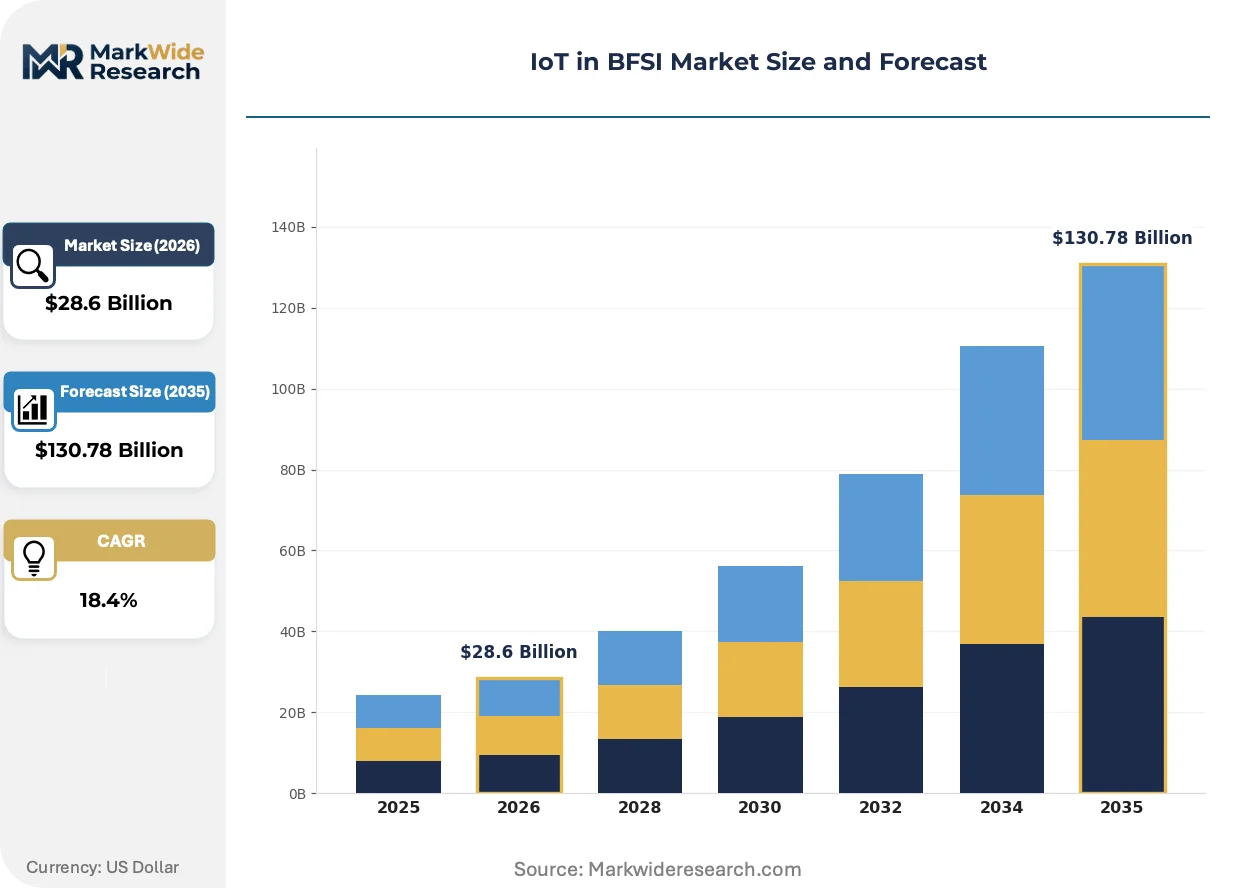
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Smart Devices, Data Analytics, Security Solutions, Connectivity Platforms End User: Retail Banks, Investment Firms, Insurance Companies, Payment Processors Technology: Cloud Computing, Edge Computing, Machine Learning, Blockchain Application: Fraud Detection, Customer Engagement, Asset Tracking, Risk Management |
| Companies Covered | IBM Corporation, Cisco Systems, Microsoft Corporation, Oracle Corporation, SAP SE, Capgemini SE, Accenture PLC, Software AG, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT in BFSI Market Emerging Trajectories
Financial institutions are abandoning monolithic technology stacks in favor of modular, API-first architectures that permit rapid substitution of sensing, compute, and analytics layers without core system overhaul.
Digital twin simulations of branch operations and ATM networks are supplanting traditional capacity planning methods that relied on historical transaction averages and static demographic models. Large retail banks in the United States are deploying these virtual replicas to test layout configurations, staffing algorithms, and sensor placements before physical capital commitment. The technology compresses deployment risk and accelerates payback periods on branch transformation investments.
CSRD sustainability disclosure requirements across the European Union are mandating granular energy consumption reporting for data center and edge computing operations. Financial institutions must now instrument power usage at the device level across distributed IoT deployments. Insurance underwriters and asset managers with significant EU exposure are restructuring their supplier qualification processes to prioritize vendors with certified carbon accounting capabilities.
Corporate treasury departments are unbundling hardware procurement from managed service contracts that previously locked institutions into single-vendor ecosystems. Buyers now separate sensor acquisition, connectivity provisioning, platform software, and operational support into distinct sourcing decisions. This fragmentation is most pronounced among mid-sized regional banks in Germany and France seeking to avoid cloud concentration risk while maintaining competitive feature parity.
IoT in BFSI Market Segmentation
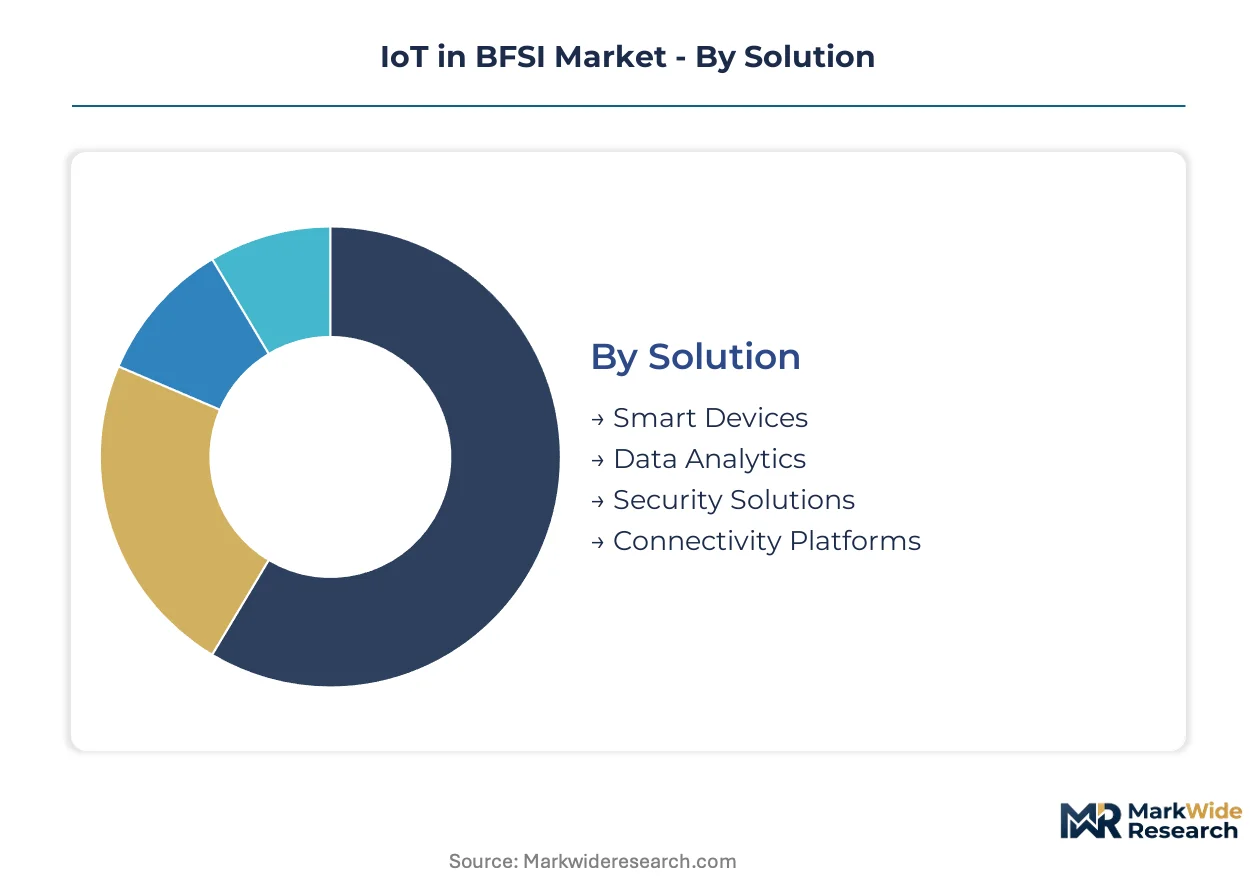
Segmentation in IoT in BFSI reveals how procurement priorities diverge across solution types, user archetypes, and deployment architectures. Understanding these fault lines helps vendors align product roadmaps with buyer willingness-to-pay and regulatory constraints.
Solution:
Channel mix varies sharply: Security Solutions and Data Analytics flow primarily through direct enterprise sales with professional services attach, while Smart Devices and Connectivity Platforms move increasingly through systems integrators and managed service providers.
- Security Solutions:These encompass endpoint protection, network segmentation, and encryption management for distributed ATM fleets and mobile banking infrastructure. Demand concentrates among retail banks in the United States confronting SEC cybersecurity disclosure mandates and escalating ransomware threats against branch networks.
- Data Analytics:Platforms ingest real-time sensor streams from customer touchpoints to enable predictive modeling and behavioral segmentation. Investment firms deploy these most aggressively to algorithmically identify trading anomalies and optimize portfolio risk exposure.
- Smart Devices:Biometric terminals, beacon arrays, and connected kiosks form the physical sensing layer.
- Connectivity Platforms:Cellular, Wi-Fi, and private 5G modules ensuring reliable data transmission.
Security Solutions dominates installed base. Data Analytics is where expansion concentrates.
End User:
Cost tier segmentation separates premium digital transformation budgets at money-center banks from constrained procurement cycles at regional institutions and specialized players.
- Retail Banks:Branch automation imperatives drive beacon deployments, biometric authentication rollouts, and ATM fleet modernization. These institutions command the largest absolute spending on IoT infrastructure as they seek to collapse physical wait times and personalize in-branch experiences.
- Insurance Companies:Usage-based policy models require connected vehicle telematics and smart home sensor integrations. European insurers face GDPR biometric localization requirements that fragment cloud architectures and raise compliance costs.
- Investment Firms:Latency-sensitive trading infrastructure and alternative data collection.
- Payment Processors:PCI-DSS certification cycles constrain connected terminal deployment velocity.
Retail Banks anchor volume procurement. Insurance Companies are climbing the fastest.
Technology:
Maturity curves separate established cloud deployments from emerging edge architectures that banks pilot for latency-sensitive workloads.
- Edge Computing:Localized processing nodes handle sub-100 millisecond fraud detection and biometric verification without routing sensitive data through centralized infrastructure. Retail banks in the United States invest disproportionately here to satisfy Federal Reserve operational resilience guidance.
- Machine Learning:Algorithmic models deployed on IoT data streams for anomaly detection and predictive maintenance. EU AI Act transparency mandates are forcing explainable AI architectures that maintain granular behavioral audit trails.
- Cloud Computing:Centralized data lakes and analytics platforms remain foundational.
- Blockchain:Distributed ledger integrations for transaction verification and identity management.
Cloud Computing maintains dominant share. Edge Computing is gaining share fastest.
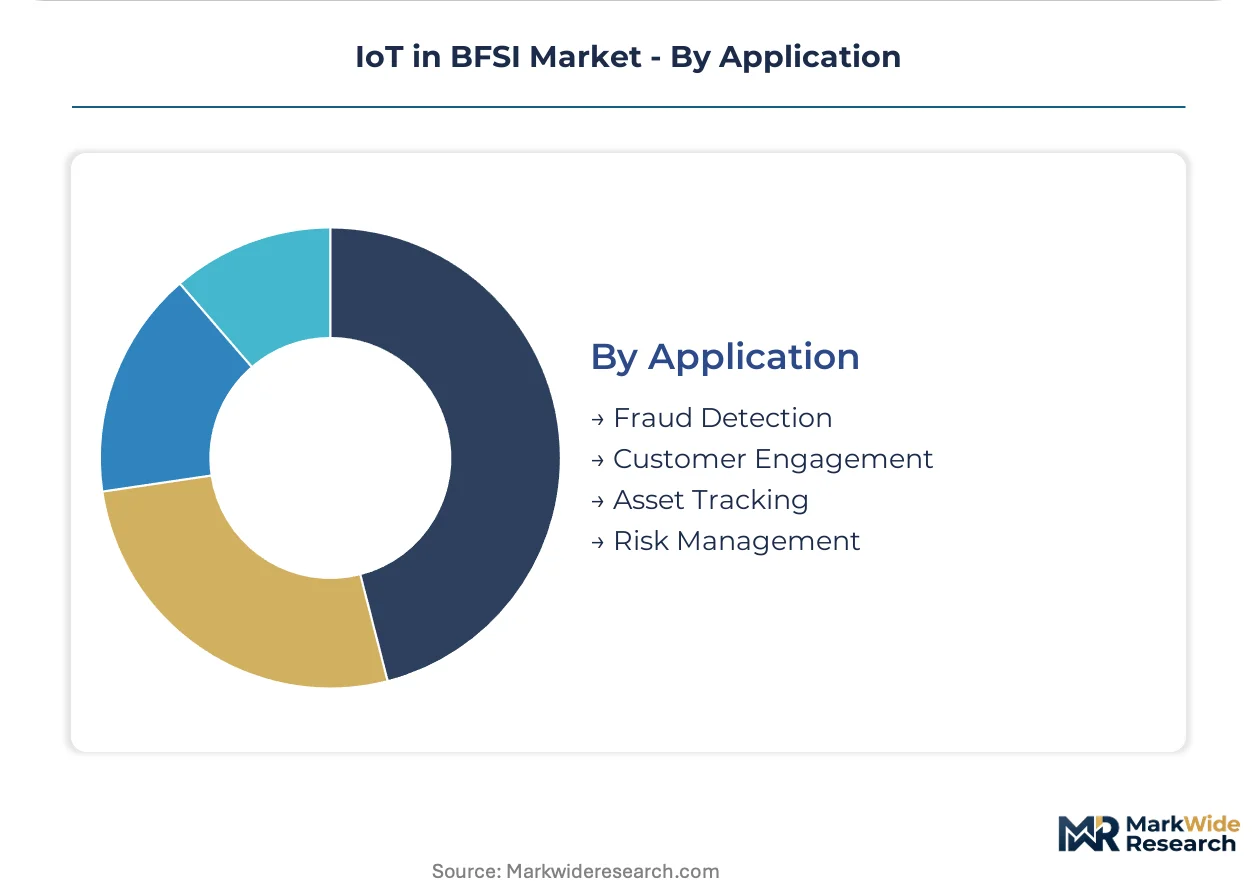
Application:
Customer type segmentation distinguishes compliance-driven procurement from revenue-generating experience investments.
- Fraud Detection:Real-time transaction monitoring systems operating at sub-100 millisecond latency thresholds across ATM fleets and mobile endpoints. Payment processors and retail banks deploy these most intensively to minimize chargeback exposure and regulatory penalties.
- Customer Engagement:Beacon technology and biometric sensors personalize in-branch experiences through proximity-triggered service offers and frictionless authentication. This application is expanding most quickly as branch networks compete with digital-native challengers.
- Asset Tracking:Location monitoring for high-value physical collateral and fleet management.
- Risk Management:Sensor-driven environmental and operational risk assessment for underwriting.
Fraud Detection dominates current deployment. Customer Engagement represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail banks in the United States command the largest absolute spending on IoT infrastructure, while insurance companies in Europe and digital banking initiatives in India concentrate emerging demand.
United States
Large banking networks drive branch automation and real-time fraud monitoring investments. The SEC's cybersecurity disclosure rules and Federal Reserve operational resilience guidance force documentation of IoT device inventories in regulatory filings. New York and Chicago anchor smart infrastructure deployments across money-center and regional bank headquarters.
Germany
Mid-sized regional banks unbundle hardware procurement from managed service contracts to avoid cloud concentration risk. The EU AI Act and GDPR mandate algorithmic transparency and biometric data localization, fragmenting cloud architectures. Frankfurt's financial district hosts edge computing pilots for latency-sensitive transaction processing.
India
The central bank and SEBI accelerate financial inclusion mandates rewarding institutions deploying low-cost connected kiosks in underbanked rural districts. RBI guidelines shape data localization requirements for payment systems. Mumbai and Bangalore concentrate fintech-led IoT innovation for branchless banking networks.
United Kingdom
Investment firms deploy data analytics platforms aggressively to algorithmically identify trading anomalies and optimize portfolio risk exposure. FCA operational resilience rules align with EU AI Act transparency expectations for automated decisions. The City of London and Edinburgh host alternative data collection infrastructure for latency-sensitive trading.
Japan
Insurance companies expand usage-based auto and property policies requiring connected vehicle and smart home sensor integrations. METI guidelines influence IoT security standards for financial services. Tokyo and Osaka anchor telematics platform development for dynamic risk pricing models.
IoT in BFSI Market Vendor Landscape
Player mix skews toward diversified technology conglomerates with established enterprise banking relationships. Market structure shows moderate consolidation around vendors offering integrated hardware-software-security stacks. Three archetypes dominate: edge networking specialists, cloud platform providers with financial services verticalization, and systems integrators with regulatory compliance expertise. Competitive moves center on strategic partnerships for 5G network slicing access and portfolio diversification into insurance telematics.
Within the cloud platform tier, Microsoft Corporation exemplifies the enterprise software ecosystem approach, while IBM Corporation occupies a position combining Watson IoT platform capabilities with cybersecurity services purpose-built for financial workloads. Cisco Systems represents the edge networking specialist archetype, anchoring branch transformation projects through hardware-centric deployments. These three entities illustrate how vendor selection increasingly separates sensor acquisition, connectivity provisioning, platform software, and operational support into distinct sourcing decisions.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Capgemini SE |
| Accenture PLC |
| Software AG |
| Intel Corporation |
| Others |
Supply Flow & Price Mechanics
Edge device substitution for centralized cloud infrastructure is simultaneously redrawing supply geography toward Taiwan and South Korea foundries while compressing pricing power for legacy connectivity platform vendors. This hardware migration forces procurement teams to rebalance cost-plus contract structures against geopolitical risk premiums that now factor into every sensor deployment decision.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate procurement for edge computing nodes and biometric terminals. Pricing stratifies across AES-256 certified security tiers, volume scale commitments, and after-sales managed service bundling. Cost compression in connectivity platforms is intensifying because mid-sized regional banks are unbundling hardware from service contracts. Payment processors exhibit the highest price sensitivity due to PCI-DSS certification overhead, while money-center banks prioritize latency performance over unit economics.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-Singapore trade lane and container availability at Busan anchor total landed cost calculations for edge device deployments. Manufacturing concentrates in Taiwan, South Korea, and Vietnam for sensor modules and processing units. Component supply draws from concentrated foundry capacity for advanced semiconductors, precision biometric sensors, and cellular connectivity chipsets. Single-source vulnerability in East Asian foundry networks poses structural risk. Distribution runs through systems integrators and managed service providers rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among mid-sized regional banks in Germany and France that now unbundle procurement decisions across four distinct vendor categories, fragmenting supplier pricing power that once rested with integrated platform providers.
For Market Incumbents: Shield core banking relationships by accelerating edge computing certification investments that satisfy Federal Reserve operational resilience guidance. Deepen in-house production of biometric sensor firmware to offset substitute pressure from modular API-first architectures. Channel control through exclusive 5G network slicing partnerships with mobile operators represents the critical defensive lever against cloud-native challengers. For New Entrants and Emerging Players: Lead with insurance telematics platforms for usage-based auto policies in Japan and India, where regulatory mandates are expanding fastest. The underbanked rural districts targeted by RBI financial inclusion programs offer the most penetrable geography. A direct-to-bank pilot program with low-cost connected kiosks bypasses incumbent systems integrator relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed edge networking specialists that accumulated debt during the cloud migration wave. Long-term viability hinges on 5G infrastructure deployment velocity and branch automation replacement cycles. Watch for SEBI and RBI joint guidance on rural banking technology standards as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Certification Investment | Federal Reserve guidance mandates documented device inventories for operational resilience compliance. |
| Biometric Data Localization Partnership | GDPR requirements force physical storage boundaries that fragment cloud architectures across EU member states. |
| 5G Network Slicing Agreement | Mobile operators offer isolated bandwidth partitions enabling deterministic performance for fraud detection workloads. |
| Insurance Telematics Platform Launch | METI guidelines in Japan and SEBI mandates in India expand usage-based policy addressable markets. |
| API-First Architecture Modularization | Corporate treasury departments now separate sensor acquisition from platform software sourcing decisions. |
Methodological Framework
Operator-level perspectives from branch transformation executives, IoT platform engineers, regulatory compliance officers, and procurement leads at retail banks anchored the qualitative base. These primary interviews combined with secondary validation from SEC cybersecurity disclosure filings, RBI circulars on data localization, EU AI Act regulatory texts, and hyperscaler IoT capex disclosures. Bottom-up deployment counts across ATM fleets and branch networks triangulated against top-down vendor revenue segmentation.
Sensitivity analysis tested forecast outputs against varying assumptions for edge computing adoption velocity, 5G infrastructure rollout timelines, and regulatory compliance cost inflation across the projection horizon. The analytical framework modeled solution type, end-user archetype, technology maturity tier, and application use case dimensions. CAGRs derived from fitted growth curves applied to annual deployment data. Industry-specific inputs included PCI-DSS certification cycle durations and semiconductor foundry capacity utilization rates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of GDPR biometric localization and EU AI Act transparency mandates would require recalibration. Forecasts reflect assumptions regarding continued East Asian foundry concentration and stable central bank financial inclusion policy trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
IoT Solutions Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
IoT in Automotive Market