
 Global Smart Wearable Market | 2026-2036
Global Smart Wearable Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Wearable Market Outlook
Edge AI inference on-device is reshaping how smart wearables process biometric data without cloud dependency. Apple Inc. leverages its custom silicon ecosystem to maintain tight hardware-software integration across wrist and ear-worn form factors. Samsung Electronics Co., Ltd. competes through vertical manufacturing scale that spans display panels, semiconductors, and finished devices. Garmin Ltd. specializes in GPS-dominant outdoor and aviation segments where positional accuracy commands premium positioning.
A smart wearable is a body-worn electronic device incorporating microelectromechanical sensors, low-power wireless chipsets, and rechargeable energy storage to capture, transmit, and display physiological or environmental data for consumer, clinical, or industrial decision-making. Smartwatch and Health Monitor categories lead current revenue contribution as FDA-cleared and CE-marked devices penetrate reimbursement channels. Fitness Tracker demand is accelerating fastest among corporate wellness programs where employers subsidize population-level metabolic screening. Bluetooth and GPS technologies anchor the connectivity layer, though NFC is gaining share in payment-authentication hybrid devices across European and Asian transit corridors.
FDA 510(k) clearance pathways and the EU Medical Device Regulation (MDR) are elevating clinical validation requirements for devices making diagnostic claims, effectively filtering out uncertified entrants from premium reimbursement tiers. The FCC in the United States governs radio frequency emissions and spectrum allocation for wearable transmitters, while China's NMPA and GB standards dictate electromagnetic compatibility and biocompatibility testing protocols for devices sold domestically. Stakeholders must monitor how divergent cybersecurity mandates across FDA, MDR, and China's SAMR frameworks will fragment certification costs and delay multi-region launch timelines for integrated health platforms.
Market Dynamics
Edge AI inference is compressing cloud dependency for biometric processing while FDA and EU MDR clearance pathways fragment certification timelines for multi-region health platforms.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Clinical-grade wearables meeting these requirements gain preferential reimbursement positioning in German and French digital health frameworks.
- Corporate wellness metabolic screening:Employers in the United States subsidize population-level fitness tracker deployments as preventive care cost containment.
- Bluetooth Low Energy 5.3:Extended range and reduced power draw enable continuous glucose monitoring patches with week-long battery cycles.
Market Restraints
- Lithium-polymer cell cost volatility:Raw material concentration in Chinese processing facilities exposes margin structures to supply quota fluctuations.
- CE marking technical documentation burdens:EU MDR clinical evidence requirements extend validation timelines for diagnostic-claim devices by 18-24 months.
- Smartphone-tethered functionality:Persistent dependency on paired handsets limits addressable populations without cellular-equipped base devices.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Incentive structures attract assembly migration for cost-optimized fitness tracker production serving domestic and export demand.
- NFC payment-authentication hybrids:Transit corridor deployments in Tokyo, London, and Singapore create hardware refresh cycles for multi-functional wrist-worn devices.
- Photoplethysmography plus impedance spectroscopy convergence:Combined optical and electrical sensing enables cuffless blood pressure estimation without inflatable components.
Industry Challenges
- FDA 510(k) predicate device identification:Novel sensor modalities struggle to locate acceptable equivalence comparisons, delaying clearance timelines.
- Biocompatibility testing protocol harmonization:Divergent ISO 10993 interpretations across notified bodies generate redundant evaluation costs.
- Legacy hospital EHR integration:HL7 FHIR implementation gaps force custom API development for clinical workflow embedding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Wearable Market |
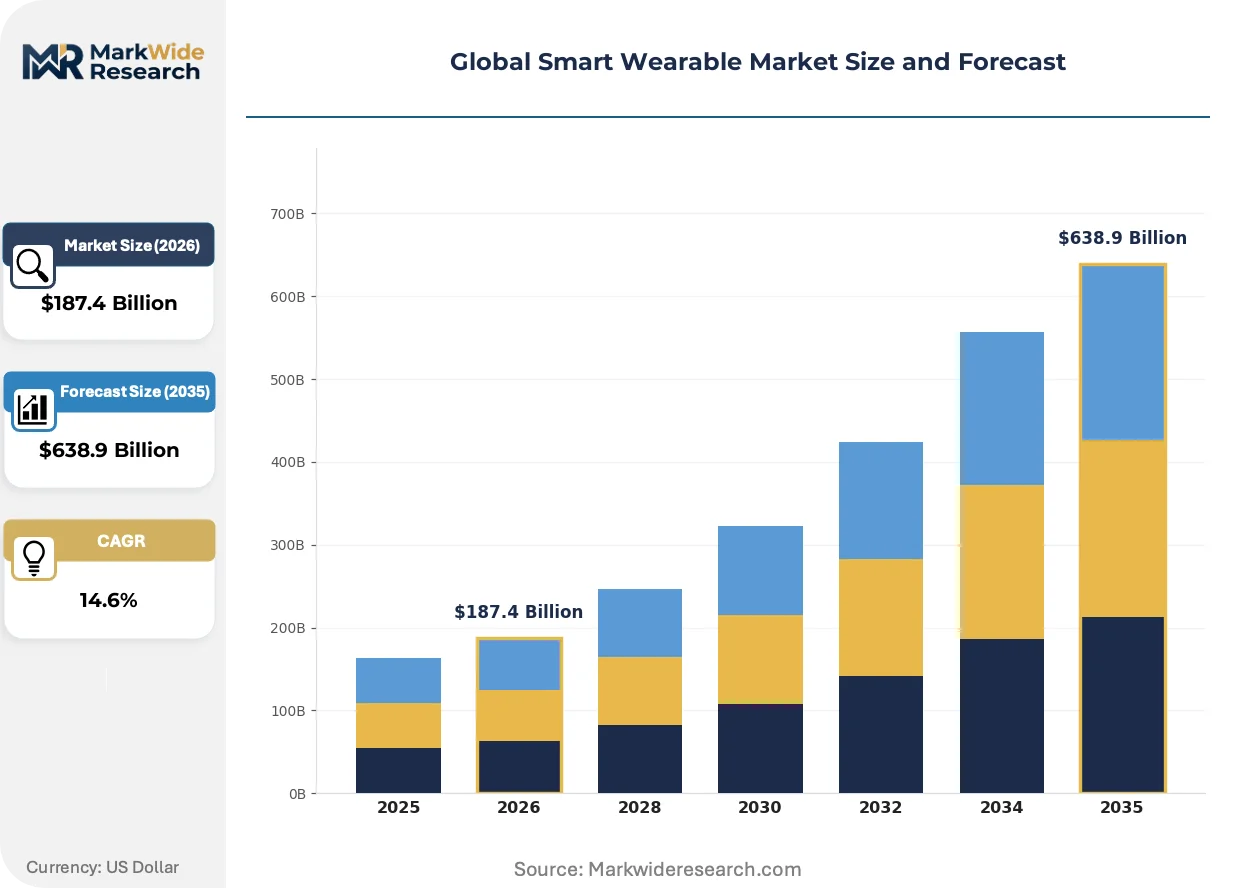
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatch, Fitness Tracker, Smart Glasses, Health Monitor End User: Consumers, Healthcare Professionals, Fitness Enthusiasts, Corporate Users Technology: Bluetooth, NFC, Wi-Fi, GPS Application: Remote Health Monitoring, Fitness Tracking, Navigation, Communication |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Garmin Ltd., Alphabet Inc., Huawei Technologies Co., Ltd., Xiaomi Corporation, Fossil Group Inc., Zepp Health Corporation, Oura Health Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Wearable Market Strategic Shifts
Continuous health monitoring is migrating from episodic clinic visits to ambient physiological sensing, rewiring how healthcare systems detect and intervene on chronic conditions.
Photoplethysmography arrays with multi-wavelength LEDs are rendering obsolete single-sensor heart rate modules in premium smartwatches. Healthcare professionals in the United States and Germany now specify optical configurations with green, red, and infrared channels for SpO2 and vascular stiffness estimation. Hospital procurement committees are compressing vendor qualification lists to exclude devices lacking multi-spectral capability.
The EU AI Act risk classification framework is elevating clinical validation requirements for health-adjacent algorithms. Devices making diagnostic claims must now submit technical documentation covering training data provenance and performance metrics across demographic subgroups. Wearable manufacturers targeting European reimbursement channels are restructuring quality management systems to embed algorithmic impact assessments prior to CE marking submission.
Subscription-based preventive health programs are displacing one-time hardware transactions in corporate benefits portfolios. Large employers in the United States now contract directly with wearable platforms for population-level metabolic screening, bundling device provisioning with coaching services. This procurement model concentrates buyer power among benefits administrators while marginalizing retail channel margins for standalone fitness tracker sales.
Global Smart Wearable Market Segmentation
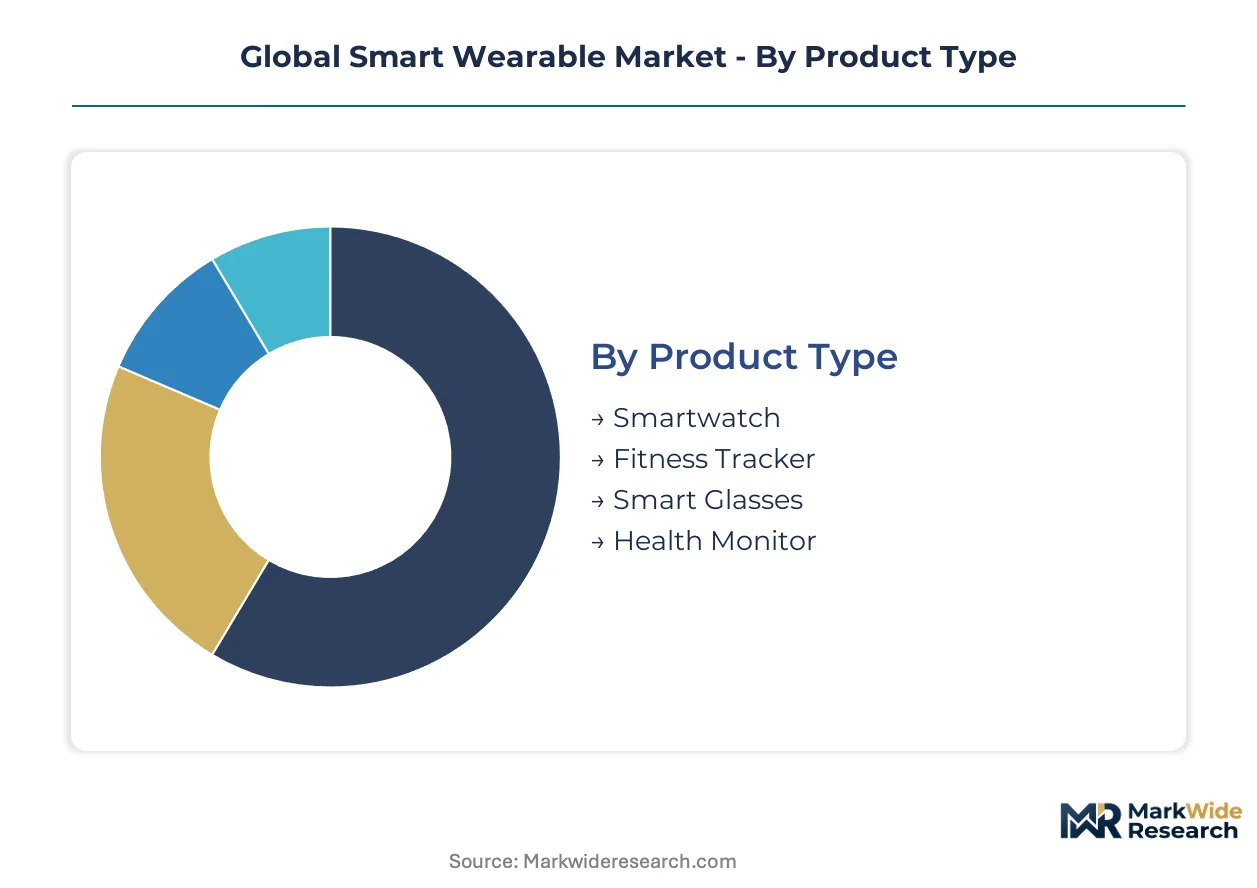
Segmentation in the smart wearable market reveals how hardware specifications, connectivity protocols, and user workflows determine reimbursement eligibility and procurement channels. Product architecture choices directly constrain which regulatory pathways manufacturers must navigate.
Product Type:
Mature wrist-worn form factors coexist with emerging head-mounted and patch-based configurations as clinical validation requirements intensify across all categories.
- Smartwatch:Multi-sensor wrist-worn platforms integrate photoplethysmography arrays, accelerometry, and capacitive touch interfaces for continuous biometric streaming. Demand concentrates among healthcare professionals in Germany and the United States where FDA 510(k) and EU MDR clearances unlock insurance reimbursement for diagnostic-grade heart rhythm monitoring.
- Health Monitor:Dedicated clinical devices prioritize measurement precision over general-purpose computing, employing medical-grade electrodes and validated algorithms for blood pressure or glucose estimation. Hospital procurement committees in China and France now specify these for remote patient monitoring programs.
- Fitness Tracker:Simplified sensor suites target calorie expenditure and step counting with minimal power draw. Corporate wellness administrators in the United States subsidize bulk deployments for metabolic screening populations.
- Smart Glasses:Optical waveguide displays and camera modules enable hands-free data visualization for industrial field technicians and surgeons.
Smartwatch retains volume leadership; Health Monitor holds the steepest expansion curve as clinical reimbursement pathways mature.
End User:
Procurement authority splits between individual consumers and institutional buyers with divergent validation requirements.
- Consumers:Individual purchasers prioritize industrial design and ecosystem compatibility over clinical certifications. Retail channel concentration in the United States and China drives hardware refresh cycles tied to smartphone upgrade patterns.
- Healthcare Professionals:Physicians and hospital systems demand FDA-cleared or CE-marked devices with documented clinical accuracy. German and French digital health frameworks now mandate algorithmic transparency documentation under EU AI Act risk classifications.
- Corporate Users:Benefits administrators negotiate population-level contracts bundling device provisioning with coaching services. United States employers leverage these arrangements for preventive care cost containment.
- Fitness Enthusiasts:Amateur athletes seek GPS precision and training load metrics for endurance sports preparation.
Consumers retain volume leadership; Healthcare Professionals are climbing the fastest as clinical-grade wearables penetrate reimbursement channels.
Technology:
Connectivity specifications determine power budgets, data throughput ceilings, and interoperability with hospital information systems.
- Bluetooth:Low-energy variants dominate wrist-worn devices for smartphone-tethered data synchronization. Bluetooth Low Energy 5.3 extended range enables continuous glucose monitoring patches with week-long battery cycles in United States and German diabetes management programs.
- GPS:Multi-constellation receivers provide positional accuracy for outdoor activity tracking and aviation applications. Garmin leverages this technology in specialized aviation and marine segments where signal reliability commands premium positioning.
- NFC:Contactless payment and transit authentication integration drives hardware refresh in Tokyo, London, and Singapore corridor deployments.
- Wi-Fi:Higher throughput supports standalone music streaming and firmware updates without smartphone intermediation.
Bluetooth retains volume leadership; NFC is gaining share fastest as payment-authentication hybrid devices proliferate across Asian and European transit networks.
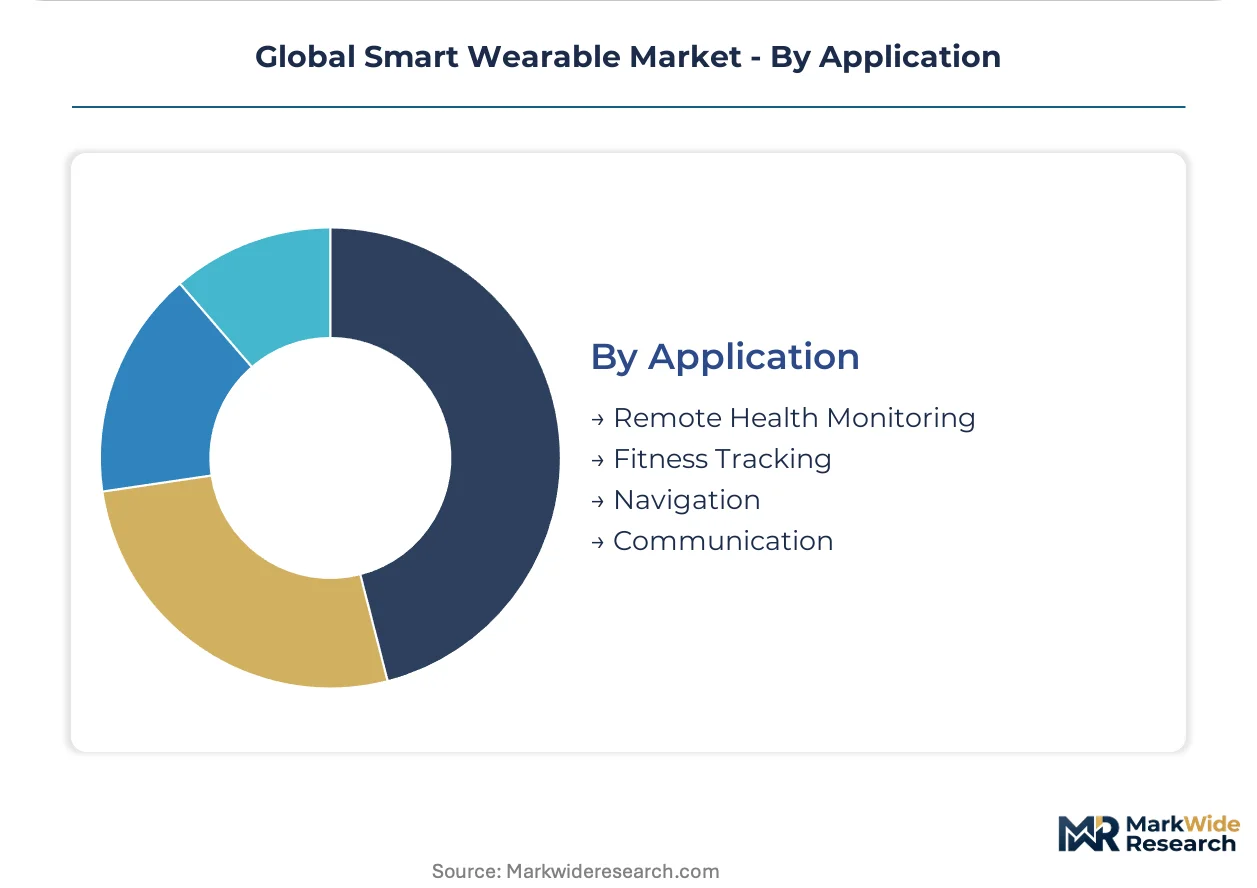
Application:
Use case specificity determines sensor configuration, algorithm training data requirements, and regulatory scrutiny intensity.
- Remote Health Monitoring:Continuous physiological streaming to clinical decision support systems requires FDA 510(k) or EU MDR clearance. United States hospital systems now embed these capabilities in chronic disease management workflows.
- Fitness Tracking:Caloric expenditure estimation and training load quantification serve corporate wellness and consumer athletic preparation. Chinese and Indian manufacturing scale has compressed hardware costs for this segment.
- Navigation:Positional accuracy for outdoor recreation and professional aviation demands multi-band GNSS reception and barometric altimetry.
- Communication:Voice calling and notification relay through wrist-worn or ear-worn devices reduces smartphone retrieval frequency.
Fitness Tracking retains volume leadership; Remote Health Monitoring exhibits the steepest expansion trajectory as reimbursement codes for digital therapeutics proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export cost-optimized fitness tracker assemblies to United States corporate wellness programs and European retail channels, while German and American firms dominate clinical-grade device shipments into hospital procurement systems worldwide.
United States
Employer-sponsored metabolic screening programs drive bulk fitness tracker procurement, with benefits administrators negotiating population-level contracts. FDA 510(k) clearance pathways for diagnostic-grade heart rhythm monitors unlock insurance reimbursement codes. The Boston-Cambridge corridor concentrates digital health startups developing clinical validation protocols for wearable algorithms.
Germany
Hospital procurement committees specify EU MDR-cleared devices with documented clinical accuracy for remote patient monitoring programs. The EU AI Act mandates algorithmic transparency documentation for health-adjacent algorithms seeking preferential reimbursement positioning. Berlin and Munich host notified bodies interpreting divergent ISO 10993 biocompatibility testing protocols.
China
Domestic manufacturing scale compresses hardware costs for fitness tracker exports serving Indian and Southeast Asian demand. NMPA and GB standards dictate electromagnetic compatibility and biocompatibility testing protocols for devices sold domestically. Shenzhen and Dongguan concentrate assembly operations for Bluetooth Low Energy modules and lithium-polymer cell integration.
India
PLI scheme incentive structures attract assembly migration for cost-optimized fitness tracker production serving domestic corporate wellness and export demand. The country's national electronics regulator enforces electromagnetic compatibility certification for wearable transmitters. Karnataka and Tamil Nadu industrial corridors host contract manufacturers scaling wrist-worn device output for Middle Eastern and African markets.
Japan
Transit corridor deployments in Tokyo drive hardware refresh cycles for NFC payment-authentication hybrid devices. METI standards govern radio frequency emissions and spectrum allocation for wearable transmitters in dense urban environments. The Osaka-Kobe manufacturing belt concentrates precision component fabrication for optical waveguide displays in smart glasses.
Global Smart Wearable Market Competitive Environment
On the supply side, the industry is bifurcated between consolidated technology ecosystems controlling silicon-to-software integration and fragmented specialists commanding premium positioning in narrow sensor modalities. Tier-one players leverage captive semiconductor design and operating system control to compress hardware-software margins. Tier-two specialists dominate GPS-dominant outdoor segments and clinical-grade health monitoring where measurement precision commands procurement specification. Dominant competitive moves include backward integration into custom chip design and strategic partnerships with hospital systems seeking EHR-embedded remote monitoring platforms.
Within the integrated ecosystem tier, Apple Inc. and Samsung Electronics Co., Ltd. exemplify hardware-software consolidation across wrist and ear-worn form factors, while Garmin Ltd. occupies a position among positioning-specialist fabricants where multi-constellation signal reliability anchors aviation and marine procurement decisions.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Garmin Ltd. |
| Alphabet Inc. |
| Huawei Technologies Co., Ltd. |
| Xiaomi Corporation |
| Fossil Group Inc. |
| Zepp Health Corporation |
| Oura Health Oy |
| Others |
Value Chain & Pricing Dynamics
Lithium-polymer cell processing in Chinese facilities concentrates upstream margin control, forcing downstream device manufacturers to absorb raw material quota volatility through inventory hedging or supplier financing renegotiation. This concentration feeds directly into tiered hardware margins where FDA-cleared clinical devices command premium positioning against commoditized fitness tracker assemblies.
Pricing Analysis
Current-generation photoplethysmography arrays with multi-wavelength LEDs price at substantial premiums over prior-generation single-sensor modules, while next-generation cuffless blood pressure estimation platforms await clinical validation before premium capture. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) certification tier and algorithmic transparency documentation depth. Cost compression in economy-tier fitness trackers intensifies as Indian PLI-subsidized assembly scales, with corporate wellness administrators exhibiting highest price sensitivity and hospital procurement committees least.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now characterize supplier financing arrangements for Bluetooth Low Energy module vendors serving tier-one device manufacturers. Component sourcing draws from China for lithium-polymer cells and display panels, Taiwan for semiconductor fabrication, and South Korea for advanced memory integration. Single-source vulnerability concentrates in Chinese rare earth processing for sensor magnet assemblies. Distribution runs through direct hospital procurement channels for clinical-grade devices and retail electronics chains for consumer fitness trackers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where FDA 510(k) clearance pathways and EU MDR certification entrenchment create substantial switching costs for hospital procurement systems locked into validated remote monitoring workflows.
For Market Incumbents: Harden algorithmic transparency documentation under EU AI Act risk classifications to preempt European reimbursement exclusion, while deepening backward integration into custom silicon design to compress hardware-software margin leakage against emerging sensor specialists. Channel control through exclusive hospital system partnerships anchors defensive positioning against platform-agnostic entrants. For New Entrants and Emerging Players: Pursue white-space opportunity in India's PLI-subsidized manufacturing corridor for cost-optimized fitness tracker exports serving Middle Eastern and African corporate wellness demand. The most penetrable segment lies in NFC payment-authentication hybrid devices for Asian transit corridors where hardware refresh cycles accelerate replacement velocity. Direct-to-employer benefits administrator contracting bypasses retail margin compression. For Investors and Strategic Acquirers: Capital is best deployed toward clinical-grade sensor specialists possessing FDA 510(k) predicate clearances and documented hospital EHR integration capabilities, as these assets compound defensibility across the analysis window. Watch for inflection signals in EU MDR notified body capacity expansion timelines, which would accelerate CE marking throughput for algorithm-heavy diagnostic platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks insurance reimbursement codes for diagnostic-grade heart rhythm monitoring in United States hospital systems. |
| EU MDR CE Marking Investment | Mandates algorithmic transparency documentation under EU AI Act risk classifications for German and French procurement eligibility. |
| Hospital System Partnership | Embeds remote patient monitoring capabilities into chronic disease management workflows through HL7 FHIR integration. |
| Custom Silicon Backward Integration | Compresses hardware-software margins through captive semiconductor design across wrist and ear-worn form factors. |
| PLI Scheme Manufacturing Migration | Captures cost-optimized assembly scale in Karnataka and Tamil Nadu corridors for export to Middle Eastern markets. |
Study Parameters
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, GPO contracts administrators, and wearable platform engineering leads, then refined through secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and customs trade records for lithium-polymer cell imports. Bottom-up demand modeling triangulated against top-down macroeconomic anchoring.
Demand-supply balance dynamics across the analysis window were assessed through segmented modeling by product architecture, connectivity protocol, end-user procurement authority, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating Bluetooth Low Energy 5.3 adoption trajectories, corporate wellness contract velocity, and clinical reimbursement code expansion patterns.
Sensitivities concentrate around lithium-polymer raw material quota fluctuations, EU MDR notified body capacity constraints, and FDA 510(k) predicate device availability for novel sensor modalities. Forecasts embed assumptions regarding algorithmic transparency mandate implementation timelines and digital health infrastructure buildout velocity. Macroeconomic contraction, regulatory divergence acceleration, or breakthrough non-invasive sensing technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Adult Smartwatch Market
Wearable Technology
US Pet Wearable Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Global Wearable Materials Market
Wearable Technology
Wearable Technology and IoT Wearable Device Market
Wearable Technology
Kids GPS Trackers and Wearables Market
Wearable Technology
Latin America Smartwatch Market
Wearable Technology
Wearable Computing Devices Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
Smart Band Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Pet Wearable Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
Wearable Camera Market