
 Dog Food and Snacks Market | 2026-2036
Dog Food and Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Food and Snacks Market Analysis
Consolidation among premium pet specialty retailers is restructuring how dog food and snacks reach end consumers, with multi-brand chains gaining leverage over single-store independents. Mars Petcare leverages its global manufacturing footprint to sustain cost advantages across wet and dry formats. Nestlé Purina PetCare anchors its position through veterinary channel partnerships and prescription diet specialization. Blue Buffalo differentiates via grain-free positioning and natural ingredient sourcing narratives.
Dog food and snacks encompass nutritionally formulated products manufactured through extrusion, retorting, or dehydration processes, with protein content, moisture levels, and digestibility coefficients serving as critical quality parameters for canine health maintenance. Dry kibble dominates volume due to shelf stability and cost efficiency, while soft chews and jerky formats capture expanding margin pools in the treats category. Meat-based ingredient formulations lead value contribution, though grain-free and organic segments attract disproportionate investment from manufacturers seeking premium positioning.
The FDA's Center for Veterinary Medicine enforces pet food safety under the Federal Food, Drug, and Cosmetic Act, while AAFCO establishes model regulations for nutritional adequacy claims adopted across US states. European manufacturers face additional compliance layers through EFSA feed additive evaluations and FEDIAF nutritional guidelines. Stakeholders must monitor evolving regulatory divergence between jurisdictions and anticipate how clean-label requirements will reshape ingredient sourcing and formulation investments.
Market Dynamics
Urban millennial pet owners in the United States, Brazil, and the United Kingdom are restructuring purchase patterns through premiumization demands, forcing manufacturers to reformulate around clean-label ingredient sourcing and veterinary-endorsed nutritional claims.
Growth Catalysts
- AAFCO Nutrient Profiles:The Association of American Feed Control Officials' updated model regulations for nutritional adequacy claims are elevating formulation standards across US states, creating compliance-driven demand for certified manufacturers.
- Pet Humanization in Brazil:Brazilian middle-class households are accelerating spending on meat-based formulations and soft chew formats as companion animal status shifts toward family member equivalence.
- Extrusion Process Advancements:High-moisture extrusion technology is enabling improved protein digestibility coefficients in dry kibble, satisfying veterinary channel requirements for clinical nutrition applications.
Market Restraints
- Animal Protein Input Volatility:Beef, poultry, and fish meal prices fluctuate with livestock commodity cycles, compressing margin pools for meat-first formulation strategies.
- Supply Concentration in Rendering:North American rendering facilities for meat and bone meal concentrate in Midwestern US processing corridors, creating geographic vulnerability to logistics disruptions.
- FDA Labeling Compliance Burden:The Food and Drug Administration's updated pet food labeling requirements impose reformulation and repackaging costs that disproportionately burden mid-tier regional producers.
Strategic Opportunities
- Insect Protein Regulatory Pathways:EFSA feed additive evaluations for black soldier fly and yellow mealworm proteins are opening novel ingredient sourcing corridors for sustainable positioning in European markets.
- Veterinary Telehealth Integration:Remote consultation platforms are creating direct-to-consumer prescription diet channels that bypass traditional retail intermediaries.
- Subscription Replenishment Models:Automated delivery systems for customized portion sizing are capturing recurring revenue streams from urban professional households in the United Kingdom.
Industry Challenges
- Formulation Chemist Scarcity:Veterinary nutrition expertise and palatability science specialization face talent pipeline gaps as human food and pharmaceutical sectors compete for identical skill profiles.
- Retort Equipment Capex Intensity:Wet food canning lines require stainless steel vessel investments that strain balance sheets for manufacturers expanding beyond dry kibble production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Food and Snacks Market |
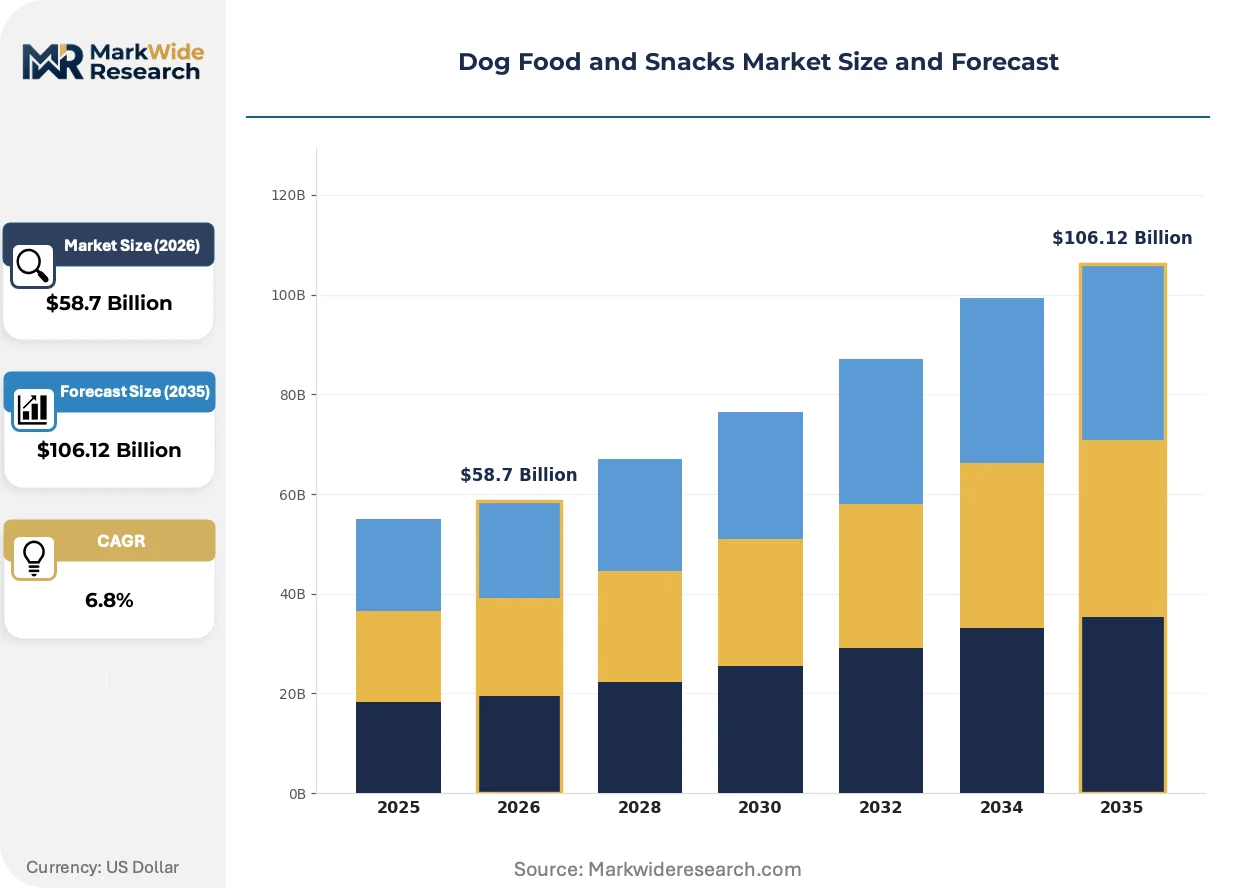
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Biscuits Ingredient Type: Meat-Based, Grain-Free, Organic, Vegetarian Form: Kibble, Canned, Jerky, Soft Chews Distribution Channel: Pet Specialty Stores, Supermarkets, Online Retail, Veterinarian Clinics |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare, Hill's Pet Nutrition, The J.M. Smucker Co., General Mills, Blue Buffalo, Diamond Pet Foods, Schell & Kampeter, Champion Petfoods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Food and Snacks Market Emerging Trajectories
Active reshaping of the dog food and snacks category stems from convergence between precision nutrition science and digital distribution infrastructure, with formulation transparency and supply chain traceability emerging as non-negotiable purchase determinants.
Cold-pressed manufacturing technology is integrating into premium dry food production, preserving heat-sensitive vitamins and enzymes that extrusion degrades. European specialty manufacturers and US direct-to-consumer startups are adopting these lower-temperature processing lines to support raw-adjacent positioning claims. The structural consequence is compressing shelf-stable nutrition quality gaps between conventional kibble and frozen raw alternatives.
The FDA's Center for Veterinary Medicine is intensifying enforcement of Salmonella and Listeria controls under the Federal Food, Drug, and Cosmetic Act, particularly for raw and dehydrated formats. This regulatory pressure is forcing raw pet food producers to implement high-pressure processing or HACCP-validated kill steps. Small-batch regional manufacturers face disproportionate compliance costs, accelerating consolidation toward scaled players with in-house microbiological testing laboratories.
Subscription-based replenishment is displacing episodic retail purchasing among millennial and Gen Z pet owners in urban United States and United Kingdom markets. Direct-to-consumer brands are capturing lifetime value through algorithmic portion calculations and automated reorder triggers. This channel shift concentrates customer data ownership with manufacturers, eroding traditional pet specialty retailer leverage over purchase decisions and brand discovery.
Dog Food and Snacks Market Segmentation
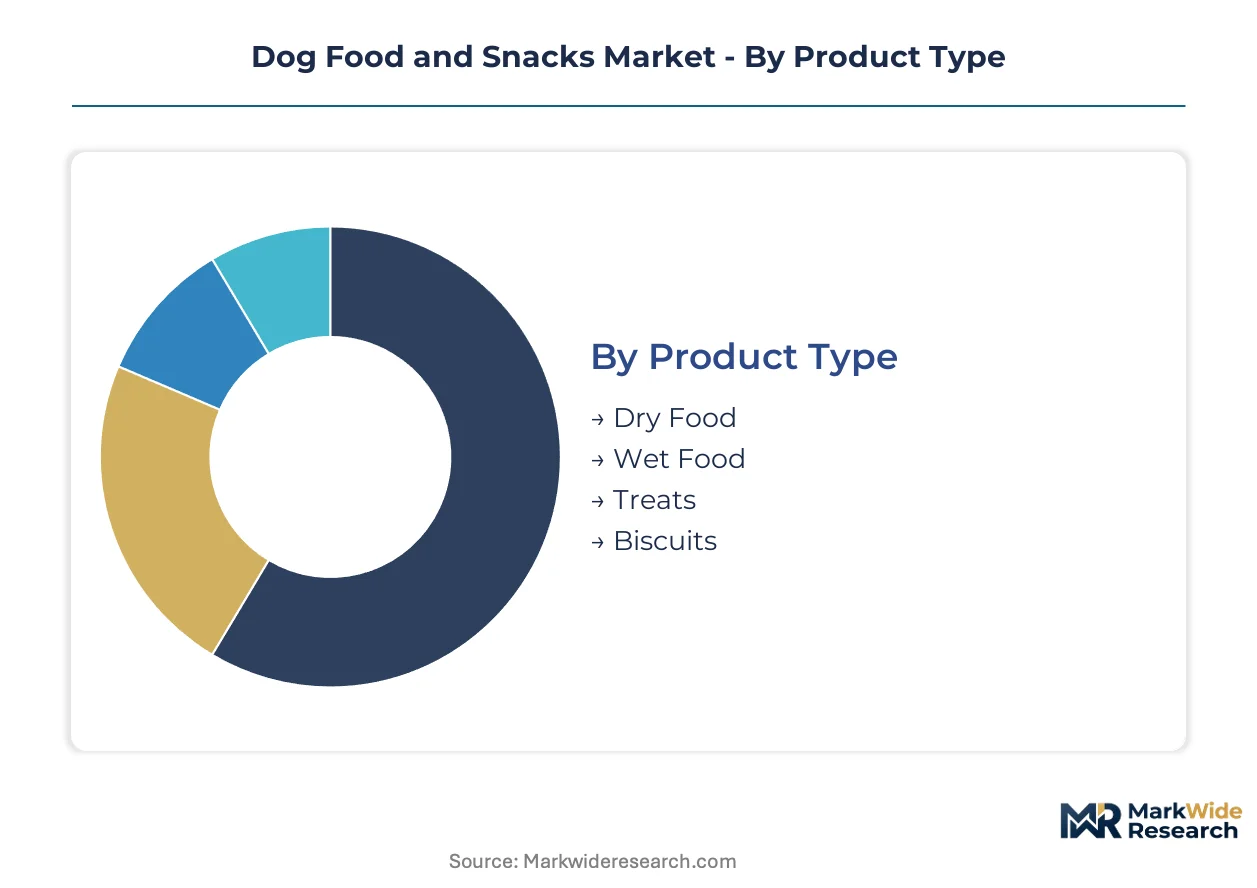
Segmentation in dog food and snacks reveals how pet owners trade off between nutritional science, convenience, and price. Purchase patterns diverge sharply across urban millennial households, veterinary-directed care, and mass-market retail channels.
Product Type:
Pet owners prioritize shelf stability and feeding convenience against moisture content and palatability when selecting product categories.
- Dry Food:Extruded kibble formulations deliver shelf-stable nutrition with cost efficiency. United States urban households favor this format for automated feeders and portion control systems.
- Wet Food:Retorted canned products achieve higher moisture content and protein digestibility. Veterinary clinics in Brazil prescribe these formulations for renal health management and senior dog nutrition protocols.
- Treats:Functional rewards and training aids with concentrated flavor profiles. Mid-tier manufacturers compete on palatability science and limited-ingredient positioning.
- Biscuits:Baked dental formulations targeting tartar reduction. United Kingdom pet specialty retailers stock these as add-on purchases to core nutrition sales.
Dry food leads on scale; wet food leads on momentum.
Ingredient Type:
Ingredient sourcing has become a primary trust signal, with certification claims and supply chain transparency driving basket composition.
- Meat-Based:Formulations prioritizing beef, poultry, or fish as first ingredients with specified protein digestibility coefficients. Brazilian middle-class households accelerate spending on these formulations as companion animal status shifts.
- Grain-Free:Potato, pea, and legume carbohydrate substitutes replacing corn and wheat. AAFCO nutrient profile compliance costs burden regional producers reformulating around FDA labeling requirements.
- Organic:USDA-certified or equivalent ingredient sourcing with prohibited synthetic additives. Premium urban households in the United Kingdom pay certification premiums for traceability guarantees.
- Vegetarian:Plant-protein formulations using soy, pea, or yeast concentrates. Niche positioning for owners with ethical constraints or protein-allergic dogs.
Meat-based formulations dominate volume; grain-free captures disproportionate investment flow.
Form:
Physical format determines manufacturing technology, packaging requirements, and margin structure across the value chain.
- Kibble:Extruded dry pieces with density-calibrated nutrient delivery. High-moisture extrusion advancements improve protein digestibility for clinical nutrition applications.
- Canned:Retorted wet products in steel or aluminum vessels. Stainless steel vessel capital intensity strains balance sheets for manufacturers expanding beyond dry production.
- Jerky:Dehydrated meat strips with extended shelf life and concentrated flavor. Soft chew formats capture expanding margin pools in the treats category.
- Soft Chews:Moist, pliable treats with functional additive integration. Cold-pressed manufacturing technology preserves heat-sensitive vitamins that extrusion degrades.
Kibble leads on manufacturing scale; soft chews lead on margin expansion.
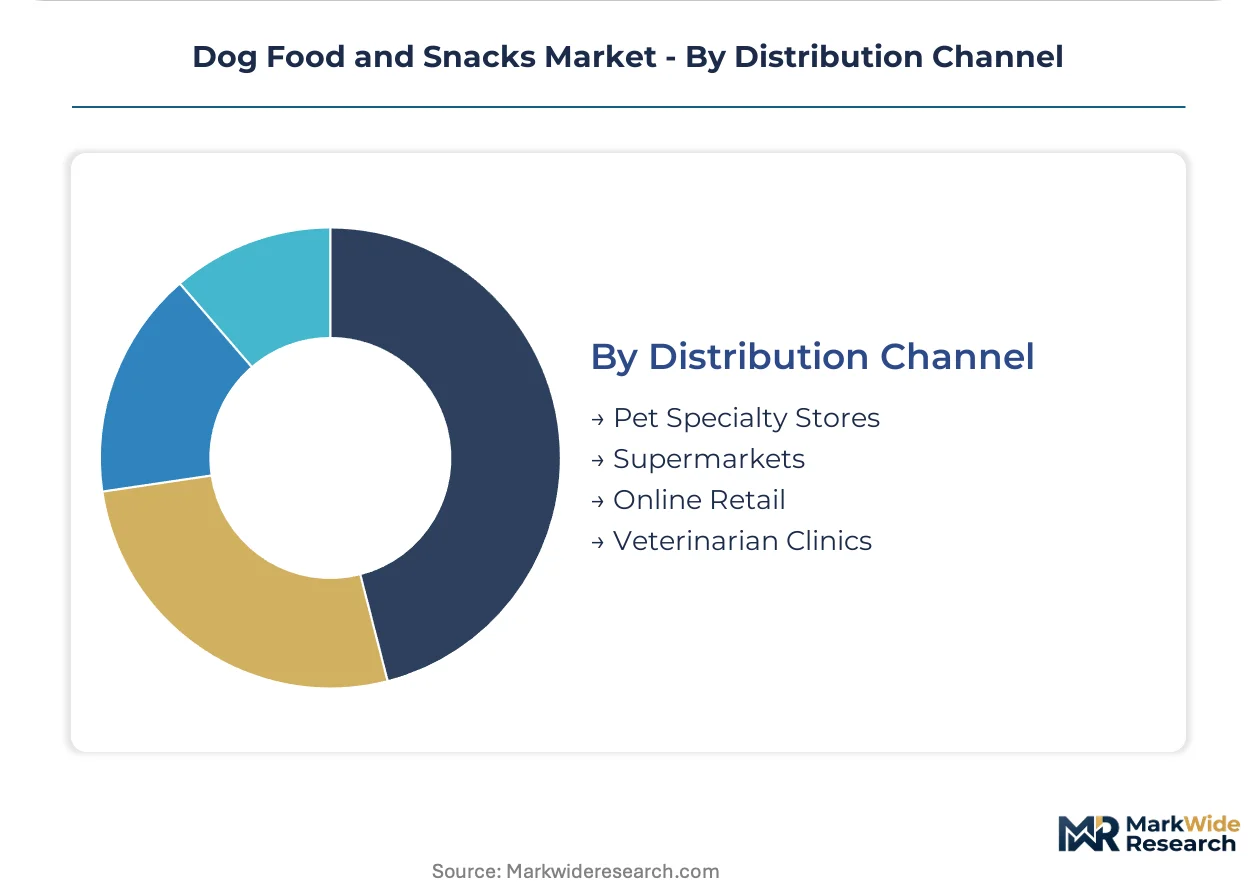
Distribution Channel:
Channel selection determines customer data ownership, brand discovery mechanics, and lifetime value capture for manufacturers.
- Pet Specialty Stores:Multi-brand chains with trained staff and premium assortment. Consolidation among these retailers is restructuring how products reach end consumers.
- Supermarkets:Mass-market placement with price-promotion dependency and limited shelf space for innovation. Volume concentration in standard kibble and biscuit formats.
- Online Retail:Direct-to-consumer platforms with algorithmic replenishment and subscription models. Automated delivery systems capture recurring revenue from urban professional households.
- Veterinarian Clinics:Prescription diet channels with clinical endorsement and therapeutic claims. Telehealth integration creates direct-to-consumer pathways bypassing traditional retail intermediaries.
Pet specialty stores lead on brand discovery; online retail leads on customer data ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian middle-class households accelerate spending on meat-based formulations while United Kingdom urban professionals shift toward subscription replenishment models, revealing divergent maturity patterns across developed and emerging markets.
United States
Urban millennial pet owners drive premiumization through clean-label ingredient sourcing and veterinary-endorsed nutritional claims. FDA Center for Veterinary Medicine enforces updated pet food labeling requirements under the Federal Food, Drug, and Cosmetic Act. Midwestern rendering corridors concentrate meat and bone meal processing, creating geographic vulnerability to logistics disruptions.
Brazil
Middle-class households elevate companion animal status toward family member equivalence, accelerating demand for soft chew formats and meat-first formulations. ANVISA regulates pet food safety and nutritional claims through federal sanitary surveillance frameworks. São Paulo anchors distribution infrastructure for national supply chain reach into southeastern population centers.
United Kingdom
Urban professional households capture recurring revenue through automated delivery systems with algorithmic portion calculations. FEDIAF nutritional guidelines complement domestic trading standards for pet food composition and labeling. Greater London concentrates direct-to-consumer brand headquarters and cold-pressed manufacturing technology adoption.
Germany
Specialty retailers consolidate multi-brand chains with trained staff and premium assortment positioning. EFSA feed additive evaluations open regulatory pathways for insect protein sourcing from black soldier fly and yellow mealworm. Bavaria hosts precision nutrition research clusters advancing high-moisture extrusion technology for clinical applications.
Japan
Aging pet demographics drive prescription diet demand through veterinary clinic channels with therapeutic claims. METI oversees feed safety and quality standards under the Act on Safety of Feed and Feed Additives. Tokyo-Osaka corridor concentrates premium import distribution and pet humanization trend adoption.
Dog Food and Snacks Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation patterns favor scaled manufacturers with in-house microbiological testing laboratories over small-batch regional producers facing disproportionate compliance costs. Three archetypes dominate: multinational consumer goods conglomerates with veterinary channel partnerships, premium natural-positioning specialists with grain-free narratives, and private-label manufacturers serving price-sensitive mass retail. Competitive intensity concentrates on M&A-driven portfolio diversification and direct-to-consumer channel capture through subscription infrastructure.
Among diversified conglomerates, Nestlé Purina PetCare and Mars Petcare occupy positions representing scale-driven veterinary channel integration and global manufacturing footprint leverage. Blue Buffalo exemplifies the premium specialist archetype through natural ingredient sourcing narratives. These three anchors illustrate how competitive positioning splits between clinical endorsement depth and clean-label consumer trust building.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare |
| Hill's Pet Nutrition |
| The J.M. Smucker Co. |
| General Mills |
| Blue Buffalo |
| Diamond Pet Foods |
| Schell & Kampeter |
| Champion Petfoods |
| Others |
Supply Flow & Price Mechanics
Captive rendering operations in Midwestern US processing corridors anchor cost structures for meat-first formulations while simultaneously constraining pricing flexibility for regional producers lacking backward integration into protein meal sourcing. This operational concentration forces mid-tier manufacturers to absorb livestock commodity cycle volatility or surrender margin to scaled competitors with in-house rendering assets.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for meat-based formulations as São Paulo infrastructure expansion reduces import dependency. Three-tier pricing structure across premium, standard, and economy levels segments urban millennial households from mass-market retail channels, with certification grade and brand premium serving as primary differentiation drivers. Cost compression in standard kibble is intensifying because Brazilian middle-class demand for soft chew formats redirects manufacturing investment toward higher-margin formats. Mass-market supermarket buyers exhibit highest price sensitivity; veterinary clinic channels demonstrate lowest sensitivity due to clinical endorsement lock-in.
Supply Chain Analysis
AAFCO nutrient profile certification gates supplier qualification for US market entry, forcing ingredient sourcing from approved rendering corridors. Protein inputs draw from Midwestern US, Brazilian São Paulo state, and German Bavarian clusters, with beef meal, poultry by-product meal, and fish oil serving as critical raw material dependencies. Single-source vulnerability concentrates in North American rendering facilities exposed to logistics disruptions. Distribution runs through pet specialty retail chains, direct-to-consumer subscription platforms, and veterinary clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dog food and snacks market functions as a regulatory compounder where FDA labeling requirement enforcement creates compliance-driven demand concentration among certified manufacturers capable of absorbing reformulation costs.
For Market Incumbents: Anticipate raw pet food segment consolidation by acquiring small-batch regional manufacturers facing disproportionate Salmonella enforcement costs. Scale in-house microbiological testing laboratories to defend against emerging direct-to-consumer brands capturing subscription replenishment revenue. Cold-pressed manufacturing technology represents the priority capability gap requiring capital deployment.
For New Entrants and Emerging Players: Subscription-based replenishment platforms offer the most penetrable white-space target among United Kingdom urban professional households seeking algorithmic portion control. Veterinary telehealth integration creates bypass opportunities around traditional retail intermediaries for prescription diet positioning. Cold-pressed manufacturing adoption supports raw-adjacent premium claims without frozen distribution infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for private-label manufacturers serving price-sensitive mass retail because supermarket channel consolidation concentrates volume among scaled suppliers with backward integration into rendering. Five-to-ten year viability hinges on regulatory divergence between FDA and EFSA pathways for novel protein approval. The signal to watch is EFSA feed additive evaluation acceleration for insect protein categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Manufacturing Adoption | Preserves heat-sensitive enzymes that extrusion degrades, supporting premium positioning claims. |
| Veterinary Telehealth Integration | Creates direct-to-consumer prescription diet channels bypassing traditional retail intermediaries. |
| Insect Protein Sourcing | EFSA feed additive evaluations open sustainable positioning corridors in European markets. |
| Subscription Replenishment Launch | Algorithmic portion calculations capture recurring revenue from urban professional households. |
| Backward Integration into Rendering | In-house protein meal production insulates margin from livestock commodity cycle volatility. |
Methodological Framework
Coverage spans the United States, Brazil, the United Kingdom, Germany, and Japan, with primary inputs from each market cluster combining formulation chemist interviews, pet specialty retail buyer conversations, veterinary nutrition specialist consultations, and rendering facility operations assessments. Secondary validation draws from FDA Center for Veterinary Medicine enforcement records, AAFCO model regulation updates, EFSA feed additive evaluation databases, and FEDIAF nutritional guideline publications. Bottom-up manufacturer capacity assessments triangulate against top-down household pet ownership expenditure tracking.
Granularity-level modeling segments by product type, ingredient sourcing category, physical form, and distribution channel across the analysis window, with urban millennial household archetypes and veterinary-directed care protocols serving as demand-side stratification dimensions. CAGRs derive from trajectory fitting against historical premiumization patterns and regulatory compliance cost absorption curves. Insect protein regulatory pathway timing and high-moisture extrusion technology diffusion rates inform scenario-weighted projections.
The model assumes a particular technology adoption path; alternative pathways for cold-pressed manufacturing scale-up would alter the outlook for premium dry food segment share. Forecasts reflect documented assumptions regarding FDA labeling compliance burden distribution and AAFCO nutrient profile adoption timing. A model refresh is warranted upon material change in EFSA feed additive evaluation velocity for novel protein categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Therapeutic Diet for Pet Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Pet Toys Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
UK Dog Food Market
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Dry Dog Food Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Dog Dental Chews Market
Pet Care Products
Smart Dog Collar Market