
 Brazil Pet Food Market | 2026-2036
Brazil Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Pet Food Market Analysis
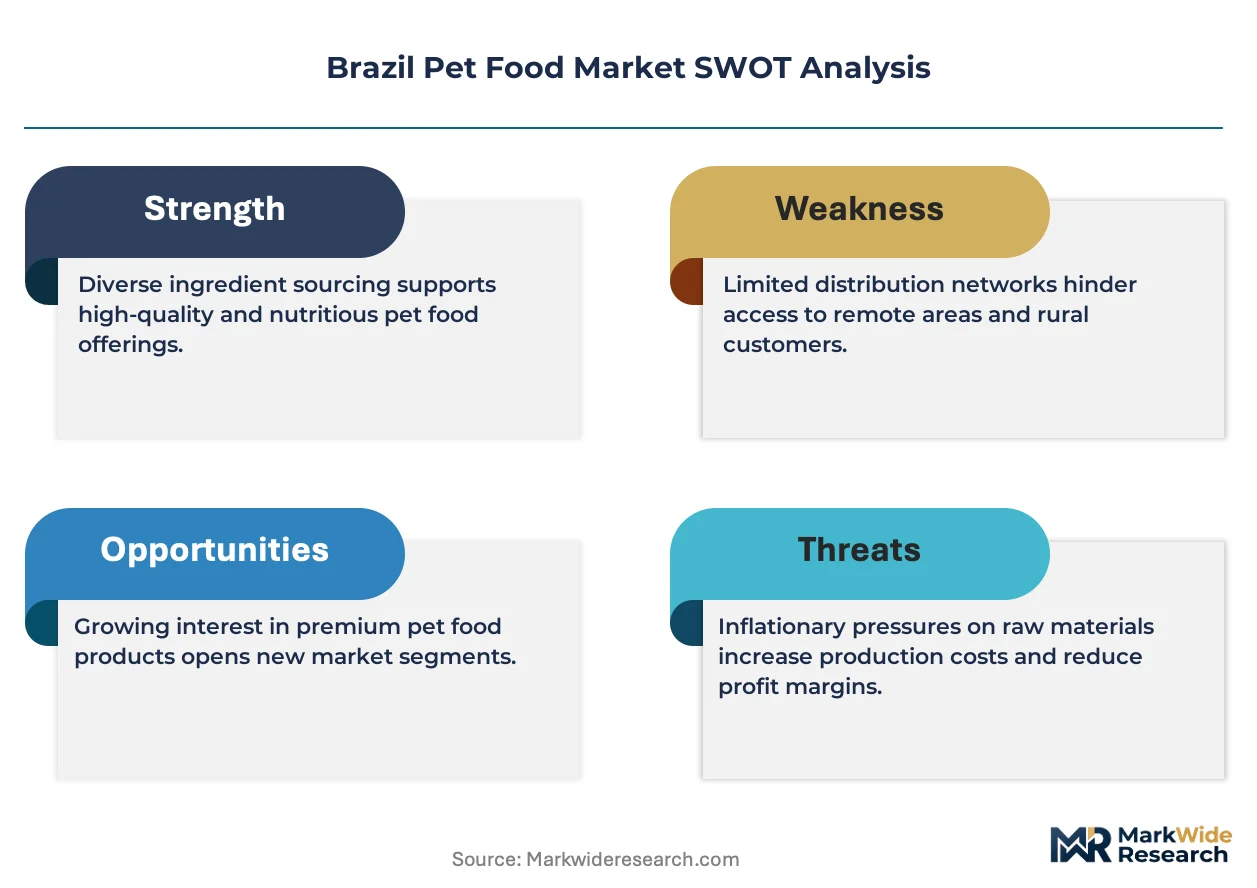
Premium nutrition tier is bifurcating the competitive landscape as Brazilian consumers trade up from economy formulations. Mars Incorporated leverages its R&D intensity to anchor science-backed therapeutic diets. Nestlé Purina differentiates through specialized wet food portfolios targeting aging pet demographics. Total Alimentos dominates regional manufacturing scale with integrated production facilities serving the Southeast corridor.
Brazil pet food comprises formulated nutritional products manufactured to AAFCO or European FEDIAF standards, incorporating specified protein minimums, fat content ranges, and vitamin premixes to deliver complete dietary sustenance for companion animals. Dry food retains the largest volume share due to shelf stability and lower per-kilogram logistics costs, while raw food segments attract margin-rich positioning among affluent urban households. Wet food competes on palatability and hydration benefits, particularly in tropical climates where moisture content aids renal health management.
ANVISA enforces mandatory ingredient disclosure and contaminant thresholds, while the Ministry of Agriculture (MAPA) monitors feed safety protocols through port-of-entry inspections and domestic facility audits. State-level environmental agencies in São Paulo and Minas Gerais impose rendering plant emission controls that elevate capital requirements for new entrants. Stakeholders must monitor pending federal legislation on pet food tax reclassification that could reshape channel economics and import competitiveness.
Market Dynamics
ANVISA's nutritional labeling overhaul is compressing formulation timelines and forcing manufacturers to revalidate product portfolios, while Southeast Brazil's logistics density concentrates competitive advantage among producers with integrated cold-chain infrastructure.
Growth Catalysts
- Humanization of pet diets:São Paulo's urban households are extending fresh-food preferences from their own plates to companion animal bowls, creating pull for refrigerated wet formats and refrigerated toppers.
- ANVISA disclosure mandates:The regulator's expanded ingredient transparency requirements are rewarding manufacturers with clean-label capabilities, accelerating shelf turnover for compliant SKUs in Rio de Janeiro retail channels.
- Minas Gerais rendering cluster:Concentrated rendering infrastructure in this state is supplying cost-competitive protein meals to formulators, anchoring regional production economics.
Market Restraints
- Soybean meal price volatility:Brazil's dependence on export-parity oilseed markets exposes domestic formulators to input cost swings that compress gross margins on economy-tier products.
- Southeast logistics chokepoints:Port congestion at Santos and highway bottlenecks around Belo Horizonte are extending lead times for imported vitamin premixes and specialty fats.
- MAPA facility audit backlog:The Ministry of Agriculture's inspection queue is delaying new plant certifications, freezing capacity expansion timelines for emerging competitors.
Strategic Opportunities
- Northeast corridor penetration:Recife and Salvador metropolitan zones show underdeveloped premium pet food penetration relative to household pet density, offering first-mover positioning for wet food specialists.
- Veterinary channel integration:Therapeutic diet dispensing through clinic networks is capturing margin-rich prescription flows that bypass conventional retail price competition.
- Amazon biome protein sourcing:Sustainable wild-caught fishmeal and insect protein cultivation in Pará and Amazonas could unlock differentiated supply narratives for export-facing brands.
Industry Challenges
- Formulation chemist scarcity:Brazilian universities produce limited graduates with combined nutrition science and regulatory compliance training, forcing manufacturers to recruit from pharmaceutical or human food sectors.
- Legacy ERP integration:Mid-tier producers running decades-old production scheduling systems face painful migrations to traceability-compliant platforms as ANVISA tightens lot-tracking requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Pet Food Market |
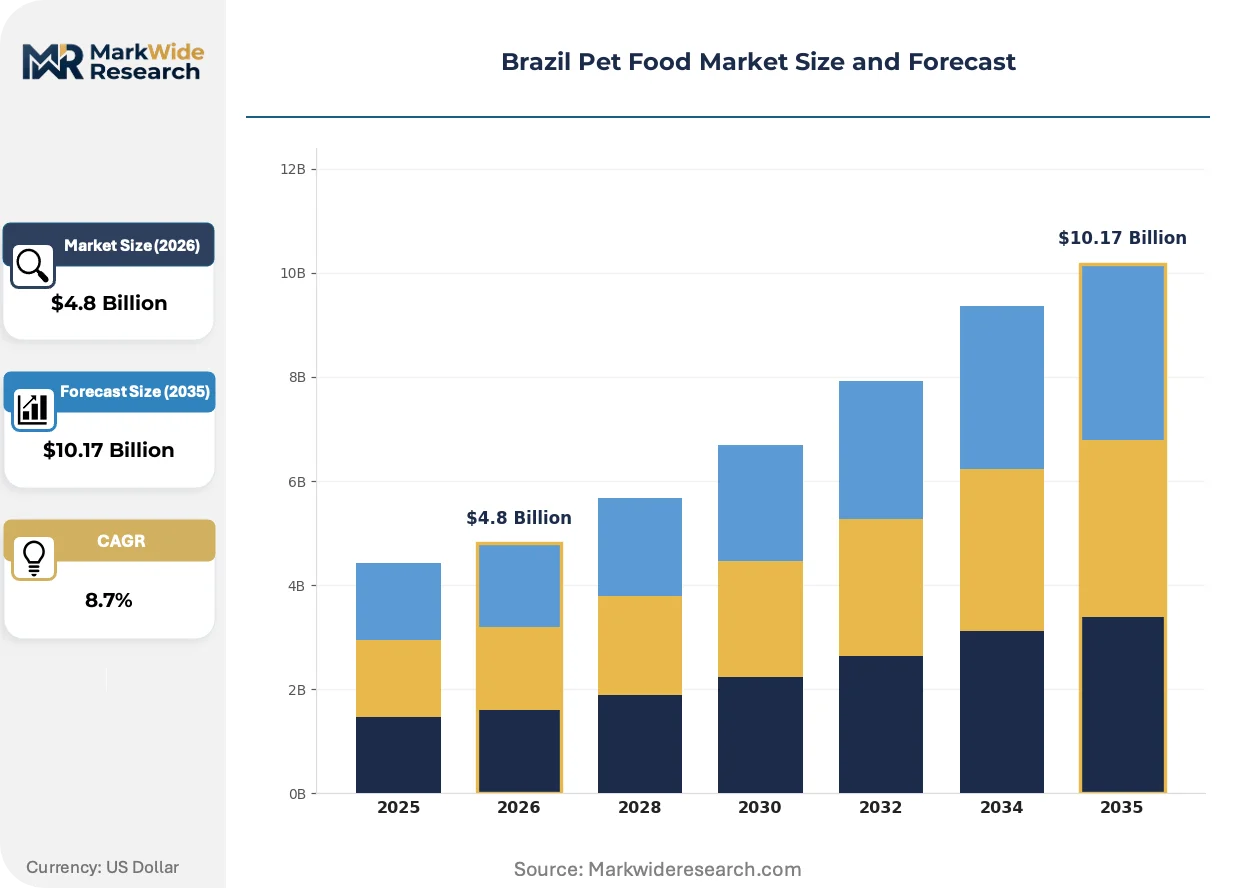
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food End User: Pet Owners, Veterinary Clinics, Retailers, Pet Services Distribution Channel: Online Stores, Specialty Pet Shops, Supermarkets, Wholesale Packaging Type: Bags, Cans, Pouches, Tubs |
| Companies Covered | Colgate-Palmolive Company, Adimax, Mars Incorporated, Royal Canin do Brasil, Total Alimentos, Nestlé Purina, PremieRpet, Vetnil, BRF Global, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Pet Food Market Emerging Trajectories
Reformulation activity is accelerating across Brazilian manufacturing facilities as protein diversification and processing technology investments reshape competitive capabilities.
Cold-pressed extrusion is supplanting conventional thermal processing in premium dry food lines, preserving heat-sensitive amino acid profiles that conventional extrusion degrades. São Paulo-based specialty manufacturers are adopting these systems to justify 40-60% price premiums over mass-market kibble. The technology is compressing shelf-space allocation for standard extrusion products in upscale retail channels.
ANVISA's contaminant threshold tightening for aflatoxin and heavy metals is forcing upstream testing investments that smaller compounders cannot absorb. The regulation is fragmenting the supplier base into certified-premium and uncertified-economy tiers. Wet food producers with in-house laboratory capabilities are capturing shelf space from importers lacking domestic testing infrastructure.
Veterinary recommendation is displacing self-directed purchasing for therapeutic and senior diet categories. Clinic-based dispensing programs in Rio de Janeiro and Curitiba are capturing recurring revenue streams that traditional pet specialty retailers cannot match. This pattern is most visible in renal and weight-management formulations where clinical monitoring justifies subscription-based fulfillment models.
Brazil Pet Food Market Segmentation
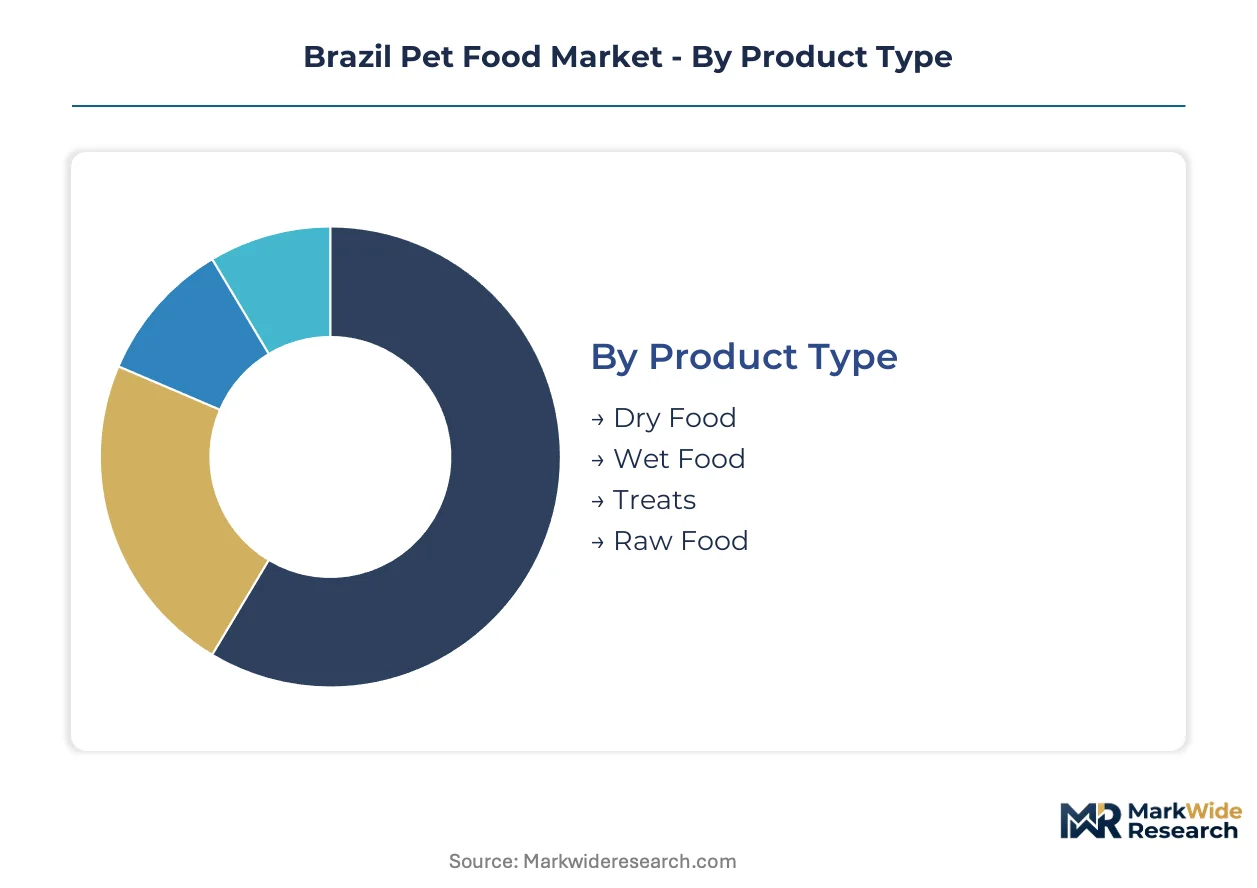
Brazil's pet food segmentation reveals how channel economics and regulatory compliance reshape competitive positioning across product tiers. Manufacturers must align formulation investments with the specific throughput requirements of veterinary dispensing versus mass retail.
Product Type:
Dry food dominates supermarket and wholesale channels through pallet-scale logistics efficiency, while wet food concentrates in specialty retail and clinic networks where margin capture justifies cold-chain handling.
- Dry Food:Extruded kibble formulations achieve 12-18 month shelf stability through controlled moisture reduction. São Paulo's supermarket chains allocate disproportionate shelf space to economy and standard dry SKUs, though cold-pressed premium variants are compressing conventional extrusion margins in affluent districts.
- Wet Food:Canned and pouched formulations with 75-85% moisture content address hydration needs in tropical climates. Rio de Janeiro and Belo Horizonte specialty retailers report accelerating turnover for single-serve wet formats as urban households trade up from dry-only feeding regimens.
- Treats:Functional dental and training reward segments.
- Raw Food:Refrigerated and frozen formats for premium urban households.
By volume, dry food leads. By growth pace, wet food is expanding most quickly.
End User:
Customer-type concentration determines pricing architecture, with veterinary clinics capturing prescription-tier margins unavailable to conventional retail channels.
- Pet Owners:Direct consumers purchasing through retail and digital channels.
- Veterinary Clinics:Therapeutic diet dispensing through Curitiba and Rio de Janeiro clinic networks is locking in recurring renal and weight-management subscriptions that bypass price competition. ANVISA's expanded labeling requirements favor manufacturers with in-house regulatory affairs capabilities.
- Retailers:Supermarket and specialty pet shop buyers negotiating slotting allowances and promotional support.
- Pet Services:Boarding facilities and groomers purchasing bulk economy formulations.
Veterinary clinics command the highest per-kilogram realization. Pet services operate on thinnest margins.
Distribution Channel:
Channel selection dictates working capital intensity, with online stores and wholesale demanding distinct inventory turnover profiles.
- Online Stores:Digital platforms with subscription fulfillment and home delivery logistics.
- Specialty Pet Shops:Curated assortments with staff recommendation driving premium conversion.
- Supermarkets:High-frequency traffic with promotional pricing pressure.
- Wholesale:Bulk distribution to smaller independent retailers and pet services.
Supermarkets move the largest absolute tonnage. Online stores are gaining share fastest.
Packaging Type:
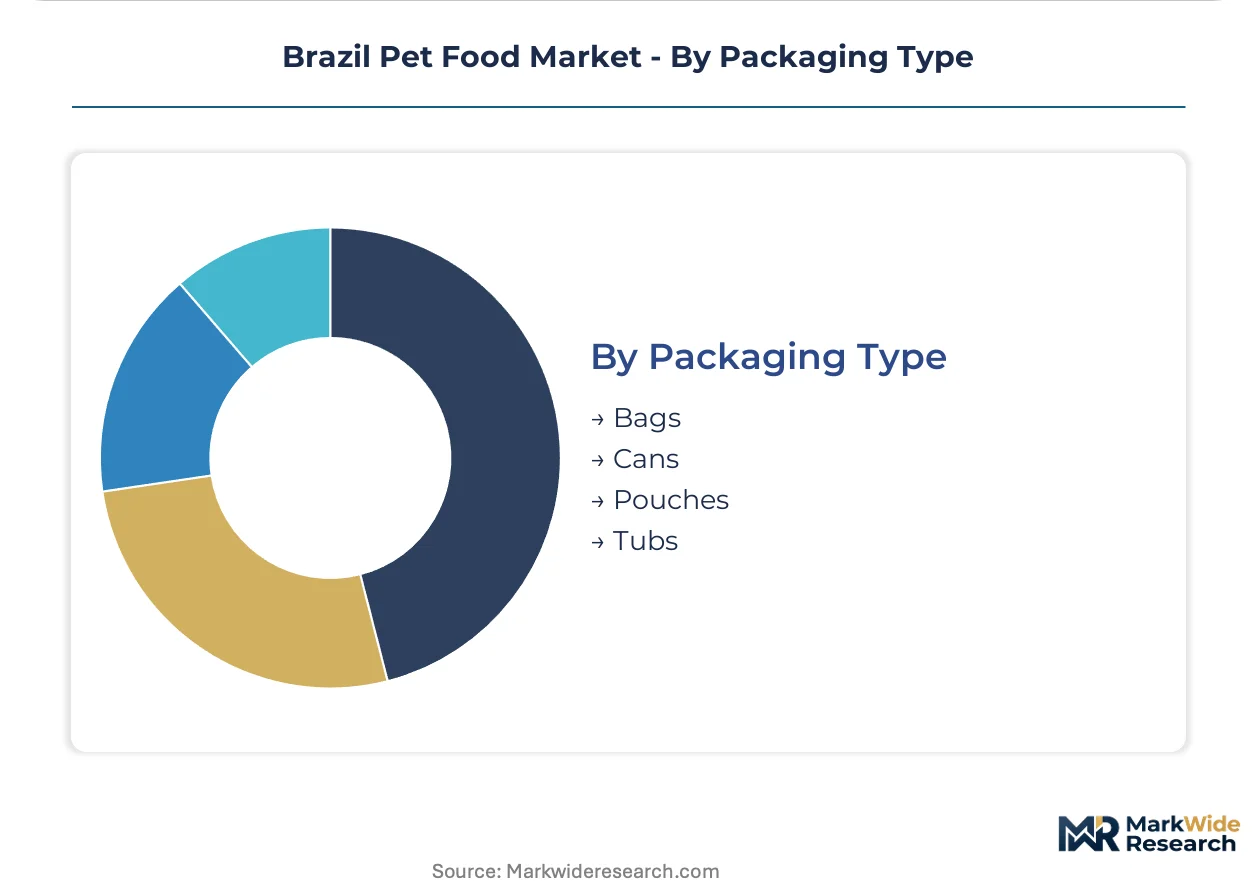
Packaging format selection interfaces directly with shelf-life requirements, portion control preferences, and recycling infrastructure availability.
- Bags:Multi-wall paper and plastic laminates for dry food bulk formats.
- Cans:Steel and aluminum containers for wet food sterilization. MAPA's facility audit requirements for canning operations create compliance barriers that concentrate supply among established Southeast manufacturers with integrated metal packaging partnerships.
- Pouches:Flexible retort and spouted formats for wet food convenience.
- Tubs:Refrigerated fresh food containers with modified atmosphere sealing.
Bags dominate tonnage. Pouches are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports formulated pet nutrition throughout Latin America, with São Paulo's manufacturing corridor supplying shelf-stable products to Argentine and Chilean retail channels while absorbing European vitamin premix imports through Santos port.
São Paulo
Metropolitan households drive premium wet food demand through specialty retail channels. ANVISA's labeling mandates accelerate compliance investments among formulators headquartered in the state. Cold-pressed extrusion facilities cluster in Greater São Paulo, supplying science-backed diets to veterinary clinic networks.
Minas Gerais
Integrated rendering infrastructure supplies cost-competitive protein meals to regional compounders. MAPA facility audits concentrate on Belo Horizonte-area canning operations, tightening certification timelines. The state's feed ingredient cluster anchors production economics for Southeast Brazil formulators.
Rio de Janeiro
Urban pet density supports accelerated turnover for single-serve wet formats in specialty retail. Port congestion at Santos delays imported specialty fat deliveries, extending formulation lead times. Clinic-based therapeutic diet dispensing captures recurring renal and weight-management subscriptions.
Rio Grande do Sul
Soybean meal price volatility exposes southern formulators to margin compression on economy-tier products. State environmental agencies impose rendering plant emission controls that elevate capital requirements. Porto Alegre's logistics position offers distribution advantages for Mercosur export flows.
Bahia
Underdeveloped premium penetration relative to household pet density creates first-mover positioning for wet food specialists. Salvador metropolitan retailers report accelerating trade-up from dry-only feeding regimens. Northeast corridor expansion depends on cold-chain infrastructure investments linking to Southeast supply hubs.
Brazil Pet Food Market Vendor Landscape
Listed leaders compete with private specialists across formulation capabilities and channel access. The vendor base organizes around three strategic tiers: multinational science-backed portfolios, regional manufacturing scale players, and domestic niche specialists. Archetypes include therapeutic diet innovators, integrated rendering-to-formulation operators, and private-label compounders serving price-sensitive segments. Competitive moves center on veterinary channel integration and cold-chain infrastructure expansion.
Among Brazil-based operators, Total Alimentos occupies a position exemplifying integrated manufacturing scale across the Southeast corridor. Mars Incorporated and Nestlé Purina represent the multinational science-backed tier, anchoring premium positioning through R&D intensity and therapeutic diet portfolios. Royal Canin do Brasil sits within the veterinary-specialist archetype, leveraging clinic-based dispensing networks.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Adimax |
| Mars Incorporated |
| Royal Canin do Brasil |
| Total Alimentos |
| Nestlé Purina |
| PremieRpet |
| Vetnil |
| BRF Global |
| Others |
Supply Flow & Price Mechanics
Insect protein meal substitution for conventional fishmeal and poultry byproducts is redrawing procurement geography across Pará and Amazonas while compressing feedstock cost curves for premium-tier formulators. This input shift simultaneously loosens Southeast rendering dependency and enables price repositioning for sustainable-positioned brands in São Paulo specialty channels.
Pricing Analysis
Cold-pressed extrusion technology commands 40-60% premiums over conventional thermal processing, anchoring a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade (ANVISA compliance tier) and volume scale, with clinic-dispensed therapeutic diets capturing the highest realization. Pricing pressure stems from soybean meal export-parity volatility squeezing economy-tier margins. Pet services and bulk wholesale buyers exhibit greatest price sensitivity; veterinary clinic subscribers show lowest.
Supply Chain Analysis
Strategic stockpiling of vitamin premixes and specialty fats dominates over just-in-time approaches given Santos port congestion and MAPA audit delays. Supply concentrates in Brazil, Argentina, and the United States for protein meals and premix inputs. The chain draws from Minas Gerais rendering clusters, European vitamin suppliers, and domestic soybean processors. Single-source vulnerability runs through Southeast logistics chokepoints. Distribution runs through integrated cold-chain networks serving veterinary and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary clinic dispensing platforms are consolidating prescription-tier purchasing power, creating ecosystem lock-in that rewards interoperable formulation-to-clinic data systems. This interoperability shift elevates platform economics above standalone product competition.
For Market Incumbents: Shield premium positioning by deepening backward integration into Minas Gerais rendering infrastructure and accelerating ANVISA clean-label certification across portfolios. Cold-chain capacity additions in Belo Horizonte and Curitiba defend against Northeast corridor challengers. R&D intensity in renal and weight-management therapeutics preserves clinic network exclusivity.
For New Entrants and Emerging Players: ANVISA fast-track certification for aflatoxin-compliant wet food unlocks shelf space in Rio de Janeiro specialty retail currently denied to import-dependent competitors. Salvador and Recife metropolitan zones offer underpenetrated premium wet food white space. Direct-to-clinic sampling programs bypass supermarket slotting allowance barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed regional compounders holding MAPA-certified canning capacity but lacking veterinary channel integration. Five-to-ten-year viability hinges on cold-chain infrastructure ownership rather than toll manufacturing relationships. Monitor ANVISA tax reclassification legislation as inflection signal for import-competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Integration | Clinic dispensing networks in Rio de Janeiro capture recurring prescription revenue streams. |
| Cold-Chain Infrastructure Expansion | Refrigerated logistics investments unlock Northeast corridor penetration from Southeast supply hubs. |
| ANVISA Compliance Certification | Clean-label certification accelerates shelf turnover in São Paulo specialty retail channels. |
| Protein Source Diversification | Amazon biome insect cultivation reduces Southeast rendering dependency for premium formulators. |
| Therapeutic Diet R&D Investment | Renal and weight-management formulations lock in veterinary recommendation and subscription fulfillment. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with formulation chemists, veterinary clinic procurement managers, specialty retail category buyers, and MAPA regulatory affairs officers; and secondary validation through ANVISA disclosure filings, MAPA facility audit records, customs trade data, and Southeast logistics operator capacity disclosures. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates from retail audit databases.
Across the modeling period, projections incorporate product type segmentation by moisture content and processing technology, end-user concentration by channel margin capture, and distribution format by working capital intensity. CAGRs derive from elasticity-adjusted demand curves incorporating household pet density trends and urbanization rates. Forecast inputs include ANVISA regulatory timeline probabilities and cold-chain infrastructure deployment schedules.
Decision-makers should treat outputs as directional under stable regulatory enforcement and intact Southeast logistics capacity assumptions; material deviation would warrant model refresh. Revision becomes warranted when ANVISA tax reclassification legislation crosses implementation thresholds or when Northeast cold-chain investment commitments accelerate beyond baseline projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
Raw Pet Food Market
Pet Care Products
Cat Furniture and Scratchers Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Aquarium Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Dog Vitamins Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Fish Based Pet Food Market