
 China Cat Litter Market | 2026-2036
China Cat Litter Market Size, Share, and Industry Trends Forecast 2026-2036
China Cat Litter Market Insights
Asset-light leasing models for bentonite mining equipment are narrowing capital barriers for new entrants in the China cat litter sector. Purrinlitter leverages its captive sodium bentonite reserves in Inner Mongolia to control raw material costs. Haisen Huachong Pet Products sustains a diversified product portfolio spanning clumping and crystal formulations. Kejie Supply Chain anchors its competitiveness through integrated logistics coverage across eastern China.
Cat litter comprises granular absorbents engineered from clay minerals, silica gel, or plant fibers, typically sized to 0.5-4.0 mm particles for optimal feline paw acceptance and odor entrapment via ion exchange or physical adsorption mechanisms. Clumping formulations dominate volume flows due to superior waste segregation and reduced replacement frequency. Crystal segments command premium shelf positioning based on extended change intervals and lower dust emissions. Biodegradable alternatives are gaining traction among urban households seeking compostable disposal pathways aligned with municipal waste sorting mandates.
SAMR enforces labeling transparency for pet product composition claims, while GB standards specify heavy metal limits in clay-based absorbents, and MEE oversight of mining permits constrains bentonite extraction expansion. These frameworks elevate compliance costs for smaller manufacturers while creating compliance-based differentiation for scaled operators. Stakeholders must monitor evolving municipal composting infrastructure and its compatibility with flushable and biodegradable litter claims.
Market Dynamics
GB standards for heavy metal limits in clay-based absorbents are compressing margins for smaller bentonite processors while rewarding scaled operators with captive mining assets and in-house testing laboratories.
Growth Catalysts
- Urban pet ownership density:Shanghai and Beijing households now average 1.2 cats per dwelling, concentrating demand within the Yangtze River Delta urban corridor where disposable incomes support premium absorbent purchases.
- MEE mining permit constraints:Environmental oversight tightening bentonite extraction expansion is eliminating marginal producers and consolidating supply around Inner Mongolia reserve holders with compliance infrastructure.
- SAMR labeling transparency mandates:Composition disclosure requirements for pet product claims are accelerating consumer education and shifting preference toward verifiable material sourcing.
Market Restraints
- Bentonite input cost volatility:Sodium-rich clay deposits face transport cost inflation from Inner Mongolia to eastern manufacturing clusters, squeezing processors without rail siding access.
- Substitution threat from silica gel:Crystal formulations with extended change intervals are capturing shelf space in multi-brand pet stores, pressuring traditional clumping clay volume.
- Technical limitation in compostability:Municipal waste sorting infrastructure in tier-two cities lacks industrial composting capacity compatible with biodegradable litter disposal claims.
Strategic Opportunities
- Underpenetrated tier-three urbanization:Chongqing and Chengdu pet retail footprints remain 40% below Shanghai density, creating whitespace for distribution network expansion.
- Dual carbon goals alignment:National carbon neutrality targets are channeling subsidies toward plant-fiber absorbent R&D and low-emission production processes.
- Veterinary clinic channel emergence:Cat health specialists are becoming recommendation gatekeepers for dust-minimizing formulations targeting feline respiratory sensitivity.
Industry Challenges
- Certification timeline compression:GB standard revision cycles are accelerating, forcing manufacturers to retest heavy metal content and reformulate binders on 18-month windows.
- Supply chain reconfiguration friction:Asset-light leasing models for mining equipment reduce capital barriers but fragment quality control across multiple bentonite source nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cat Litter Market |
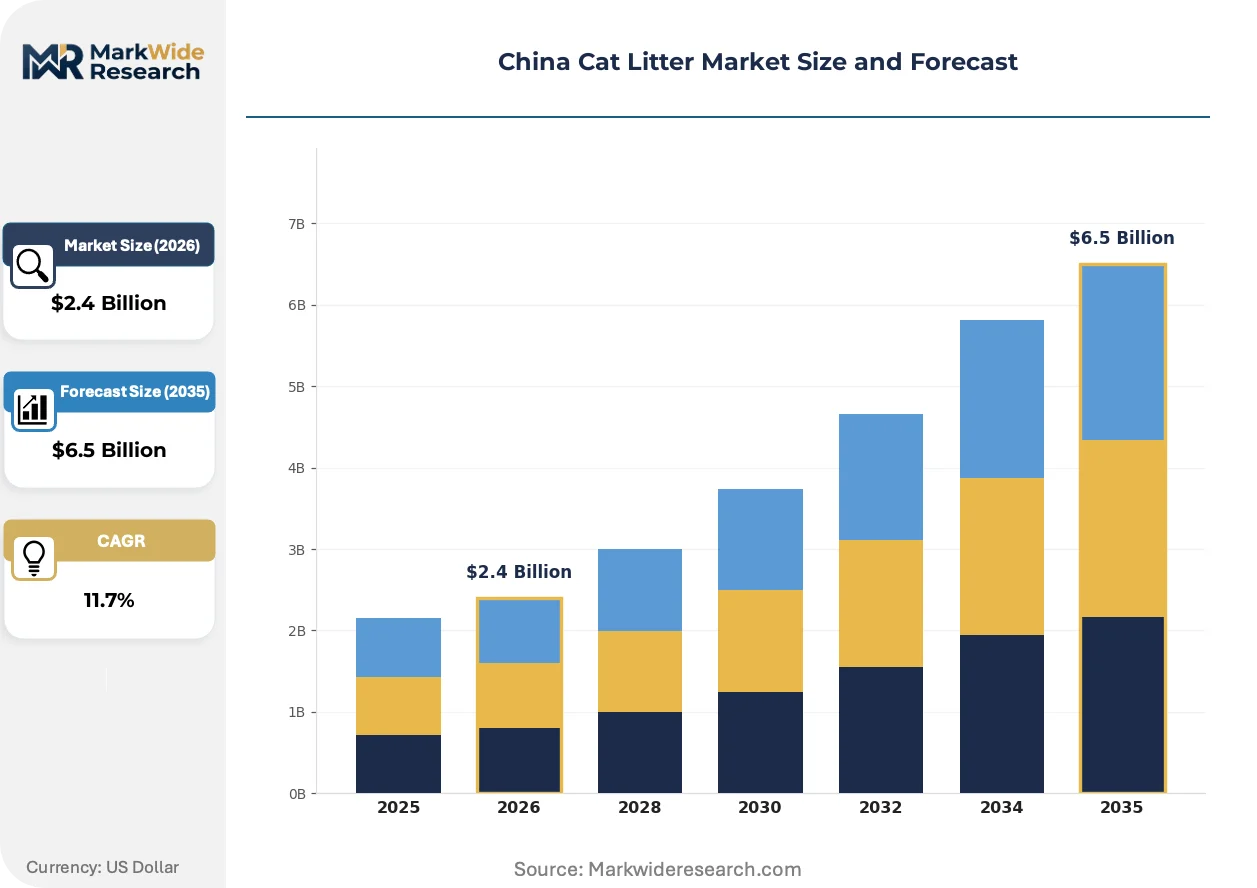
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clumping, Non-Clumping, Crystal, Biodegradable Material: Sodium Bentonite, Clay, Corn, Recycled Paper Distribution Channel: Online Retail, Supermarkets, Pet Stores, Wholesale Customer Type: Households, Breeders, Pet Shelters, Veterinary Clinics |
| Companies Covered | Purrinlitter, Haisen Huachong Pet Products, Ningcheng County Chong'ai Pet Products, Kejie Supply Chain, Shandong Haifang International Trade, Petstar, Yantai Qianyuan Pet Products, Dalian Shenglin Northeast of China Products, Haisen Pet Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cat Litter Market Trends and Innovations
Material science advances and regulatory disclosure mandates are converging to reshape competitive advantage around verifiable supply chain transparency rather than brand recognition alone.
Smart litter monitoring systems embedding moisture and ammonia sensors are digitizing waste management routines for urban households. Premium apartment dwellers in Shanghai and Shenzhen are adopting connected trays that transmit fill-level data to mobile applications. This connectivity layer is digitizing replenishment timing and shifting purchasing from periodic retail trips to subscription-based auto-replenishment models.
SAMR enforcement of pet product composition claims is tightening material traceability requirements across the absorbent supply chain. Processors must now document bentonite mine origin and heavy metal testing protocols for each production batch. Clumping clay manufacturers with captive Inner Mongolia reserves are responding by integrating blockchain-verified sourcing documentation into packaging QR codes.
Multi-brand pet stores are consolidating shelf space around three to four core suppliers with comprehensive SKU coverage across clumping, crystal, and biodegradable formats. Independent specialty retailers in Beijing and Guangzhou are losing bargaining power as chain buyers demand volume rebates and exclusive formulation rights. This channel concentration is most visible in the Yangtze River Delta, where municipal waste sorting mandates have simultaneously elevated consumer interest in compostable disposal pathways.
China Cat Litter Market Segmentation
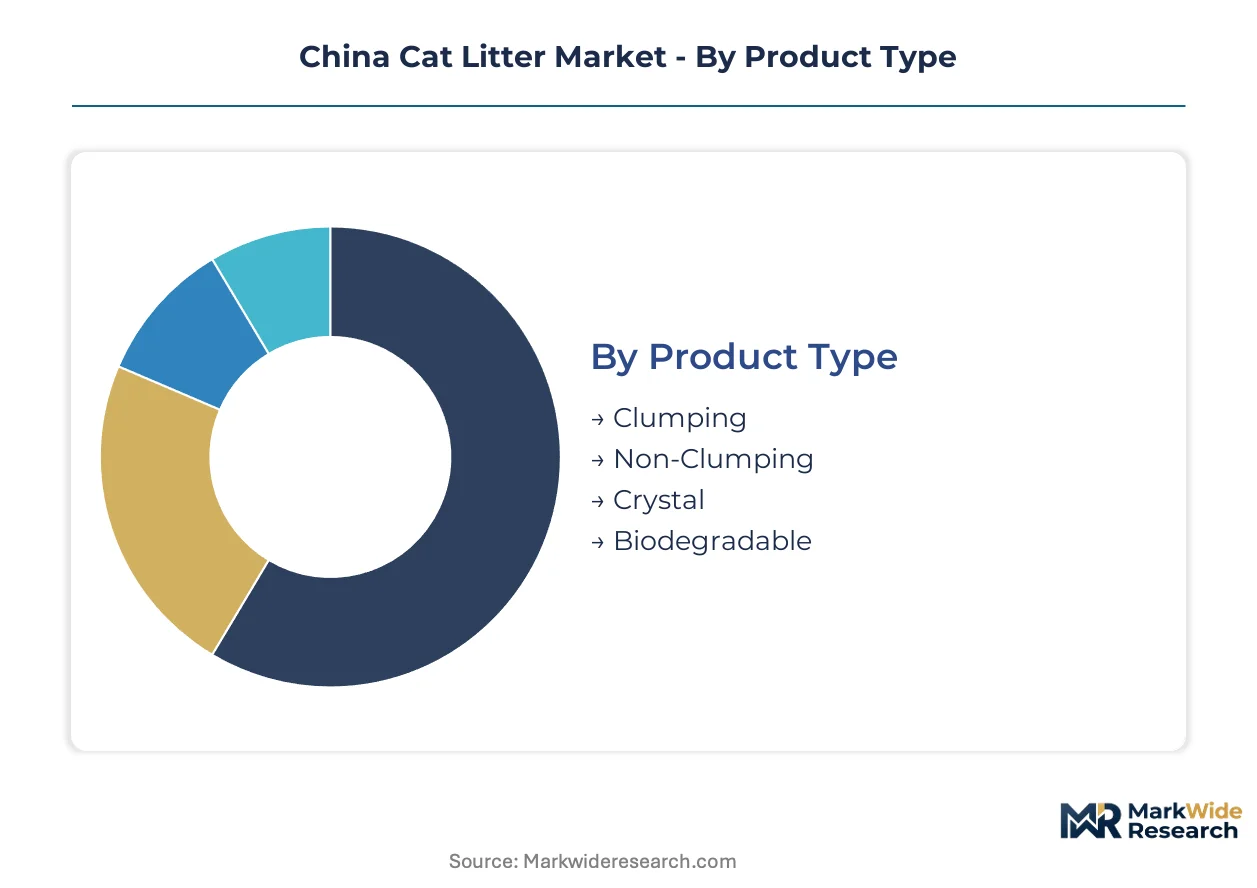
Granular segmentation reveals how China's cat litter market stratifies across formulation chemistry, raw material sourcing, channel economics, and end-use concentration. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Cost tier differentiation separates premium convenience from economy maintenance burden, with formulation chemistry directly determining household willingness-to-pay and replacement frequency.
- Clumping:Sodium bentonite-based formulations create solid waste aggregates through colloidal hydration, enabling selective scooping and reduced full-box changes. Shanghai and Beijing apartment dwellers with limited storage space prioritize this segment for waste segregation efficiency and odor containment in confined living environments.
- Crystal:Silica gel microspheres adsorb moisture through surface capillary action, extending change intervals to 3-4 weeks versus 1-2 weeks for clay alternatives. Multi-brand pet stores in the Yangtze River Delta urban corridor allocate premium shelf positioning to this segment based on lower dust emissions and reduced respiratory irritation for sensitive feline populations.
- Non-Clumping:Traditional clay absorbents require complete box replacement, maintaining economy positioning for price-sensitive households in tier-three cities with established disposal routines.
- Biodegradable:Plant-fiber and compressed corn formulations align with municipal waste sorting mandates in Shanghai, Shenzhen, and Hangzhou, though composting infrastructure gaps limit full value realization.
Clumping holds installed capacity. Crystal is rotating up the share rankings.
Material:
Supply concentration around captive mineral reserves versus agricultural byproduct sourcing creates divergent margin stability and GB standards compliance exposure across material inputs.
- Sodium Bentonite:High-swelling clay from Inner Mongolia deposits delivers superior liquid absorption and clump integrity through montmorillonite lattice expansion. Purrinlitter and other reserve holders leverage captive mining assets to control input costs while maintaining in-house heavy metal testing protocols required by tightening GB standards.
- Clay:Non-swelling calcium bentonite and attapulgite alternatives occupy economy tiers with reduced performance specifications but lower transport cost sensitivity for processors without rail siding access to northern reserves.
- Corn:Processed agricultural byproducts from Shandong and Henan grain belts offer compostable disposal pathways, though moisture sensitivity and pest attraction constrain shelf life without synthetic additives.
- Recycled Paper:Pulp-based absorbents target veterinary clinic channels with dust-minimizing properties for post-surgical and respiratory-sensitive feline patients.
Sodium bentonite commands upstream control. Corn is climbing the fastest on dual carbon goals alignment.
Distribution Channel:
Channel selection determines customer acquisition economics and inventory velocity, with digital platforms fragmenting traditional retail gatekeeper power in tier-one cities.
- Online Retail:Tmall, JD.com, and Douyin commerce enable direct-to-household replenishment with subscription auto-replenishment models gaining traction among Shanghai and Shenzhen premium apartment dwellers using connected litter monitoring systems.
- Supermarkets:Carrefour, RT-Mart, and domestic chains maintain economy-tier SKU depth for mass-market penetration, though shelf space compression favors suppliers with comprehensive format coverage across clumping and crystal lines.
- Pet Stores:Multi-brand chains in Beijing and Guangzhou consolidate bargaining power around volume rebates and exclusive formulation rights, squeezing independent specialty retailers.
- Wholesale:Bulk procurement serves breeder operations and pet shelter networks with palletized delivery and extended payment terms.
Online retail holds installed capacity. Pet stores are rotating up the share rankings.
Customer Type:
Volume concentration and price sensitivity separate fragmented household demand from institutional procurement with specialized performance requirements.
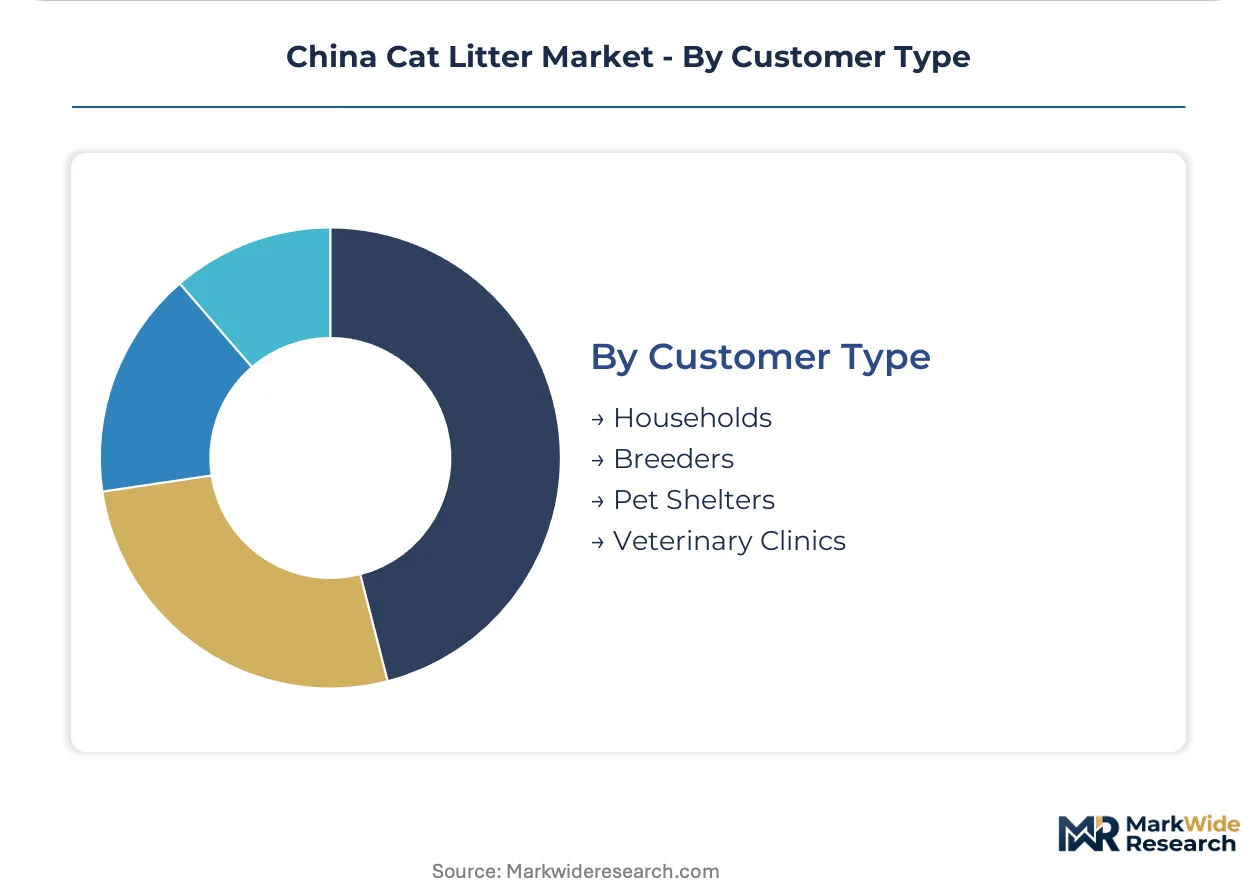
- Households:Urban pet owners in the Yangtze River Delta urban corridor drive premium absorbent purchases, with Shanghai households averaging 1.2 cats per dwelling and prioritizing odor control and convenience features.
- Breeders:Commercial cattery operations in Guangdong and Sichuan provinces require bulk formulations with consistent quality control and disease prevention properties, creating stable offtake for established suppliers.
- Pet Shelters:Municipal and private rescue facilities prioritize economy-tier non-clumping clay for cost containment across high-turnover animal populations.
- Veterinary Clinics:Cat health specialists in Beijing and Shanghai are becoming recommendation gatekeepers for dust-minimizing formulations, channeling premium purchases toward silica gel and recycled paper alternatives for respiratory-sensitive patients.
Households hold installed capacity. Veterinary clinics are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's cat litter trade flows reflect a net export surplus concentrated in Inner Mongolia's bentonite belt, with coastal manufacturing clusters serving both domestic Yangtze River Delta demand and cross-border shipments to Southeast Asian markets.
Shanghai
Shanghai households average 1.2 cats per dwelling, the highest urban density in China, while municipal waste sorting mandates under local environmental bureaus accelerate compostable litter trials. Premium apartment complexes in Pudong and Xuhui districts host the densest penetration of smart litter monitoring systems.
Beijing
Beijing's veterinary clinic channel is emerging as a recommendation gatekeeper for dust-minimizing formulations, with SAMR labeling transparency mandates enforced most stringently in capital-region retail inspections. Multi-brand pet store chains in Chaoyang and Haidian districts consolidate shelf space around three to four core suppliers.
Guangdong Province
Commercial cattery operations in Guangzhou and Shenzhen drive bulk procurement of consistent-quality formulations, with MEE mining permit constraints pushing processors to source bentonite via rail from northern reserves rather than local deposits. The Pearl River Delta's pet retail footprint remains 40% below Shanghai density.
Sichuan-Chongqing
Chongqing and Chengdu represent underpenetrated whitespace with expanding middle-class pet ownership, though tier-three urbanization lags in distribution network coverage. Local processors face transport cost inflation from Inner Mongolia without rail siding access to eastern manufacturing clusters.
Shandong Province
Shandong's grain belt supplies processed corn byproducts for biodegradable formulations aligned with national dual carbon goals, while Qingdao and Yantai ports facilitate export logistics for bentonite-based absorbents. Provincial environmental regulations enforce GB standards for heavy metal limits in clay-based products.
China Cat Litter Market Competitive Landscape
On the supply side, the industry is consolidating around reserve holders with captive mining assets and in-house testing laboratories, while smaller bentonite processors face margin compression from compliance cost escalation. Three strategic archetypes dominate: Inner Mongolia-based reserve owners controlling upstream sodium bentonite supply, eastern Chinese manufacturers with integrated logistics coverage across coastal demand clusters, and diversified formulators spanning clumping, crystal, and biodegradable product lines. Competitive moves center on M&A activity targeting compliant mining permits and strategic partnerships with multi-brand pet store chains for exclusive formulation rights.
Among reserve-backed operators, Purrinlitter exemplifies the captive-mining archetype through its Inner Mongolia sodium bentonite holdings. Haisen Huachong Pet Products occupies a diversified-formulator position spanning multiple chemistry types. Kejie Supply Chain anchors the integrated-logistics tier with eastern China distribution coverage. These three company structures represent the prevailing competitive configurations shaping procurement patterns and shelf-space negotiations in the Yangtze River Delta urban corridor.
| Leading Market Players |
|---|
| Purrinlitter |
| Haisen Huachong Pet Products |
| Ningcheng County Chong'ai Pet Products |
| Kejie Supply Chain |
| Shandong Haifang International Trade |
| Petstar |
| Yantai Qianyuan Pet Products |
| Dalian Shenglin Northeast of China Products |
| Haisen Pet Technology |
| Others |
Pricing and Supply Chain Analysis
Inner Mongolia's sodium bentonite reserve concentration hands pricing power to captive mine operators while fragmenting margin pools among rail-dependent processors in eastern manufacturing clusters. MEE mining permit constraints amplify this asymmetry by eliminating marginal producers and consolidating supply around compliant reserve holders with in-house testing laboratories.
Pricing Analysis
Multi-brand pet store chains anchor a three-tier pricing structure across premium, standard, and economy levels, with crystal silica gel formulations commanding shelf premiums based on extended change intervals and GB heavy metal certification tiers. Price differentiation stems from material sourcing transparency and veterinary clinic endorsement, with subscription auto-replenishment models softening pricing in tier-one cities while transport cost inflation squeezes rail-disconnected processors. Economy-tier non-clumping clay faces the steepest price sensitivity among tier-three urban households.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian export markets dominates supply chain risk planning as coastal manufacturing clusters serve cross-border shipments. Sodium bentonite draws from Inner Mongolia deposits, silica gel microspheres from coastal chemical processors, and corn fiber from Shandong grain belts. Single-source vulnerability concentrates around MEE-permitted mining assets, with distribution running through integrated logistics operators covering the Yangtze River Delta urban corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as municipal waste sorting mandates splinter demand across compostable, clumping, and crystal formulations, creating niche positioning openings for specialized suppliers.
For Market Incumbents: Build captive reserve moats through MEE-compliant mining permit acquisition and blockchain-verified sourcing documentation. Secure exclusive formulation rights with consolidating multi-brand pet store chains to lock shelf space against silica gel substitution. Add in-house heavy metal testing capacity to compress certification timelines as GB standard revision cycles accelerate. For New Entrants and Emerging Players: Tier-three cities in the Sichuan-Chongqing corridor represent the most penetrable entry point, with pet retail footprints running 40% below Shanghai density and local processors lacking rail siding access. Target veterinary clinic recommendation channels for dust-minimizing formulations, leveraging SAMR labeling transparency mandates to differentiate against opaque incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with diversified formulators spanning clumping, crystal, and biodegradable lines but lacking captive mineral reserves. Five-to-ten year viability hinges on dual carbon goals alignment and municipal composting infrastructure buildout. Monitor tier-two city industrial composting capacity as the inflection signal for biodegradable litter value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | MEE permit holders control sodium bentonite input costs against transport inflation. |
| Blockchain Sourcing Documentation | SAMR transparency mandates reward verifiable supply chain disclosure with shelf access. |
| Veterinary Clinic Channel Partnership | Cat health specialists channel premium purchases toward dust-minimizing silica gel formulations. |
| Subscription Auto-Replenishment Launch | Smart litter monitoring systems digitize replenishment timing for Shanghai apartment dwellers. |
| Dual Carbon R&D Investment | National carbon neutrality targets channel subsidies toward plant-fiber absorbent development. |
Research Methodology
The analysis maps clumping clay, crystal silica gel, and biodegradable fiber sub-sectors, each validated through plant managers at bentonite processors, procurement leads at multi-brand pet store chains, and distribution channel partners across eastern China. Primary interviews with MEE regional enforcement officers and SAMR labeling compliance specialists combined with secondary validation from customs trade data, GB standards documentation, and municipal waste bureau publications. Bottom-up SKU-level volume builds triangulated against top-down regional household pet ownership density estimates.
Assumptions held fixed include MEE mining permit issuance rates and municipal composting infrastructure deployment timelines, while variables tested included silica gel substitution elasticity and veterinary clinic channel penetration rates. Segmentation dimensions modeled span formulation chemistry, material sourcing, distribution channel, and customer type across the projection horizon. CAGRs derived from installed base replacement cycles and premium tier adoption curves, with forecast inputs including Yangtze River Delta urban corridor disposable income trajectories and tier-three city distribution network expansion rates.
Macroeconomic conditions sit as an overlay; deviation in household pet ownership density or transport cost inflation from Inner Mongolia would shift the trajectory. Forecasts reflect documented assumptions around SAMR enforcement stringency and GB standard revision timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Vegan Pet Food Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Global Kennel Software Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Organic and Natural Dog Foods Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Italy Pet Food Market
Pet Care Products
Dog Litter Boxes Market
Pet Care Products
Kitten Milk Replacer and Formula Market