
 Smart Toys Market | 2026-2036
Smart Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Toys Market Intelligence
Chinese electronics manufacturers is broadening output of sensor-integrated toy components for international brands. LEGO Group anchors its smart toy portfolio through in-house production of programmable block systems with embedded Bluetooth modules. Hasbro competes across voice-activated and app-connected product lines, while VTech Holdings dominates the educational tablet segment with proprietary content ecosystems and age-tiered software.
Smart toys are physical play products incorporating microprocessors, wireless connectivity protocols, and embedded sensors to enable responsive, adaptive, or programmable behavior. These products typically integrate Bluetooth Low Energy for device pairing, capacitive touch surfaces, and rechargeable lithium-polymer cells to deliver interactive experiences that adjust to user inputs. Interactive robots and programmable blocks command premium positioning due to complex mechatronics and higher BOM costs. Educational tablets and voice-activated toys are gaining volume traction as parents prioritize screen-time management and literacy development over passive entertainment.
The US Consumer Product Safety Commission and FCC impose RF exposure and small-parts safety standards that constrain antenna design and battery enclosure geometry for connected toys. The EU AI Act and GDPR impose algorithmic transparency and parental consent requirements that increase compliance overhead for voice recognition and adaptive learning features. Stakeholders must monitor evolving interoperability mandates and data localization rules that could fragment platform architectures and content licensing across jurisdictions.
Market Dynamics
STEM curriculum mandates in primary education systems are accelerating institutional procurement of programmable learning hardware, while parental data-privacy concerns are forcing redesigns of voice-capture architectures in consumer-facing products.
Growth Catalysts
- GDPR Article 8 parental consent frameworks:Clear data governance rules in the European Union are enabling compliant product launches by reducing legal uncertainty for voice-activated toy developers.
- Bluetooth Low Energy 5.3 integration:Lower power consumption and improved broadcast capabilities are extending battery life in sensor-embedded play products, reducing replacement friction for caregivers.
- German Kita expansion programs:Municipal investment in early childhood education facilities is creating concentrated demand for educational tablets and interactive robotics in institutional procurement channels.
Market Restraints
- Lithium-polymer cell supply concentration:Battery cell manufacturing clusters in East Asia create single-source dependency risks for toy brands seeking localized production.
- FCC RF exposure testing timelines:Extended certification cycles for wireless-enabled children's products delay product launches and compress selling seasons.
- EU AI Act algorithmic transparency requirements:Documentation burdens for adaptive learning features increase development overhead and reduce feature iteration velocity.
Strategic Opportunities
- Rural Chinese county-level education bureaus:Underpenetrated distribution in third and fourth-tier cities offers volume expansion for affordable programmable block systems.
- ISO/IEC 27001 data security certification:Emerging institutional procurement filters favor vendors with demonstrable information security management systems.
- Generative AI content pipelines:Convergence of large language models with embedded edge processors enables personalized storytelling without cloud dependency.
Industry Challenges
- Mechatronics engineering talent scarcity:Shortage of professionals combining mechanical design, firmware development, and child-safety expertise constrains product complexity scaling.
- CE marking MDR transition timelines:Evolving medical device regulation boundaries for therapeutic play products create classification uncertainty and compliance cost volatility.
- Cross-platform content licensing fragmentation:Proprietary software ecosystems limit interoperability and increase customer switching costs for educational content.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Toys Market |
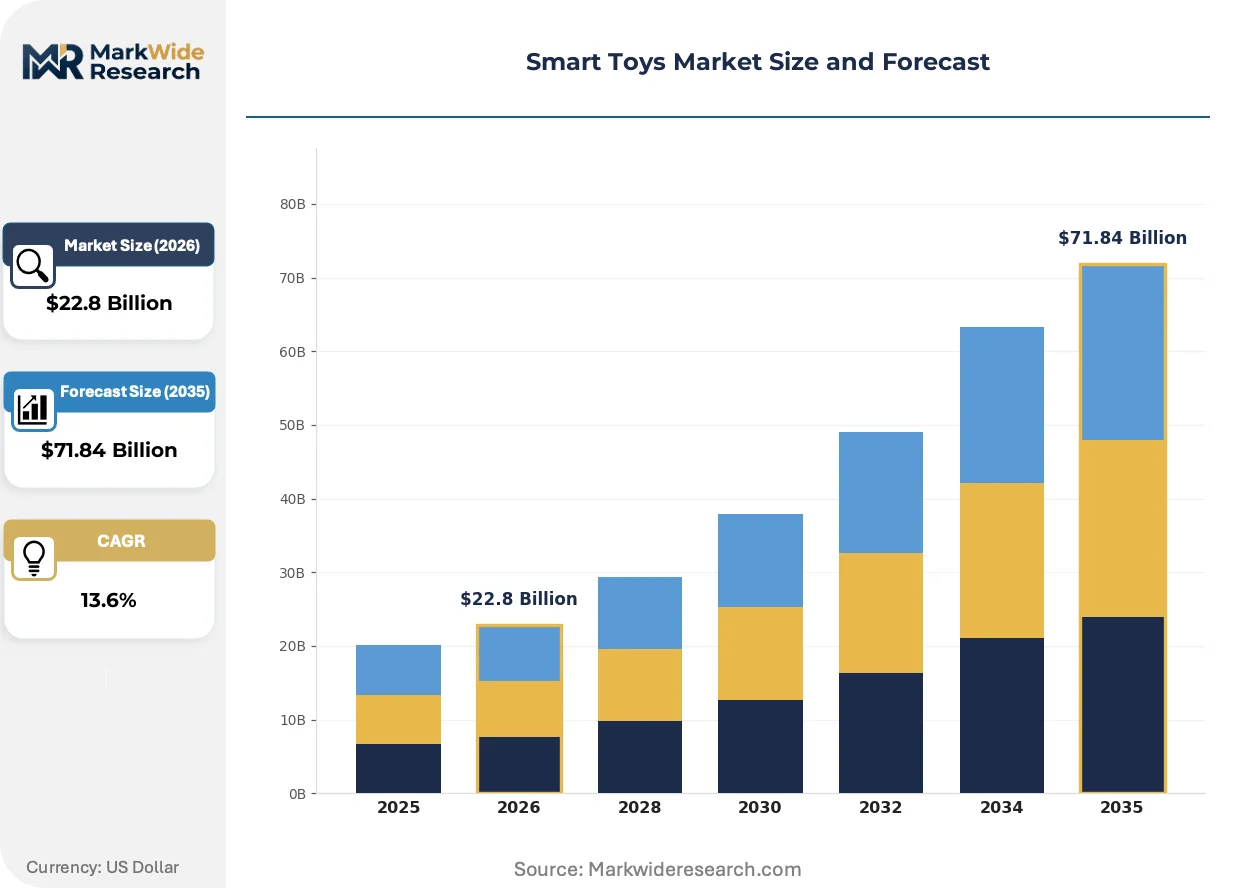
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $71.84 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Robots, Educational Tablets, Programmable Blocks, Augmented Reality Toys, Voice-Activated Toys Technology: Artificial Intelligence, Bluetooth Connectivity, Motion Sensors, Touchscreen Interface, Voice Recognition Application: Early Learning, Language Development, STEM Education, Creative Play, Social Skills Enhancement End User: Preschool Children, Elementary Students, Special Needs Learners, Gift Buyers, Educational Institutions |
| Companies Covered | Spin Master, Bandai Namco, LEGO Group, UBTECH Robotics, Sphero, Mattel, VTech Holdings, LeapFrog Enterprises, Hasbro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Toys Market Strategic Shifts & Innovations
Hardware abstraction layers and standardized sensor interfaces are decoupling mechanical design from software development, enabling faster product iteration cycles and opening entry points for specialized component suppliers.
Edge AI inference chips with sub-watt power envelopes are modularizing voice recognition and gesture detection capabilities. Toy manufacturers in Shenzhen and Dongguan are integrating these system-in-package solutions into mid-tier product lines within six-month development windows. This compression is collapsing the traditional premium-mass market feature gap and forcing faster refresh cycles across price tiers.
The EU AI Act's risk classification system for biometric identification in children's products is triggering hardware architecture redesigns. Manufacturers are relocating voice processing from cloud endpoints to on-device neural accelerators to minimize data transmission. Educational tablet and interactive robot segments are absorbing the highest compliance costs, with some vendors suspending adaptive personalization features pending legal clarity.
Institutional procurement through education technology distributors is displacing traditional retail channels for programmable learning systems. German state-level education ministries and US school district consortia are consolidating purchasing through approved vendor lists, favoring suppliers with dedicated K-12 sales operations and localized curriculum alignment. This channel concentration is most pronounced in STEM-focused districts in Bavaria and Texas.
Smart Toys Market Segmentation
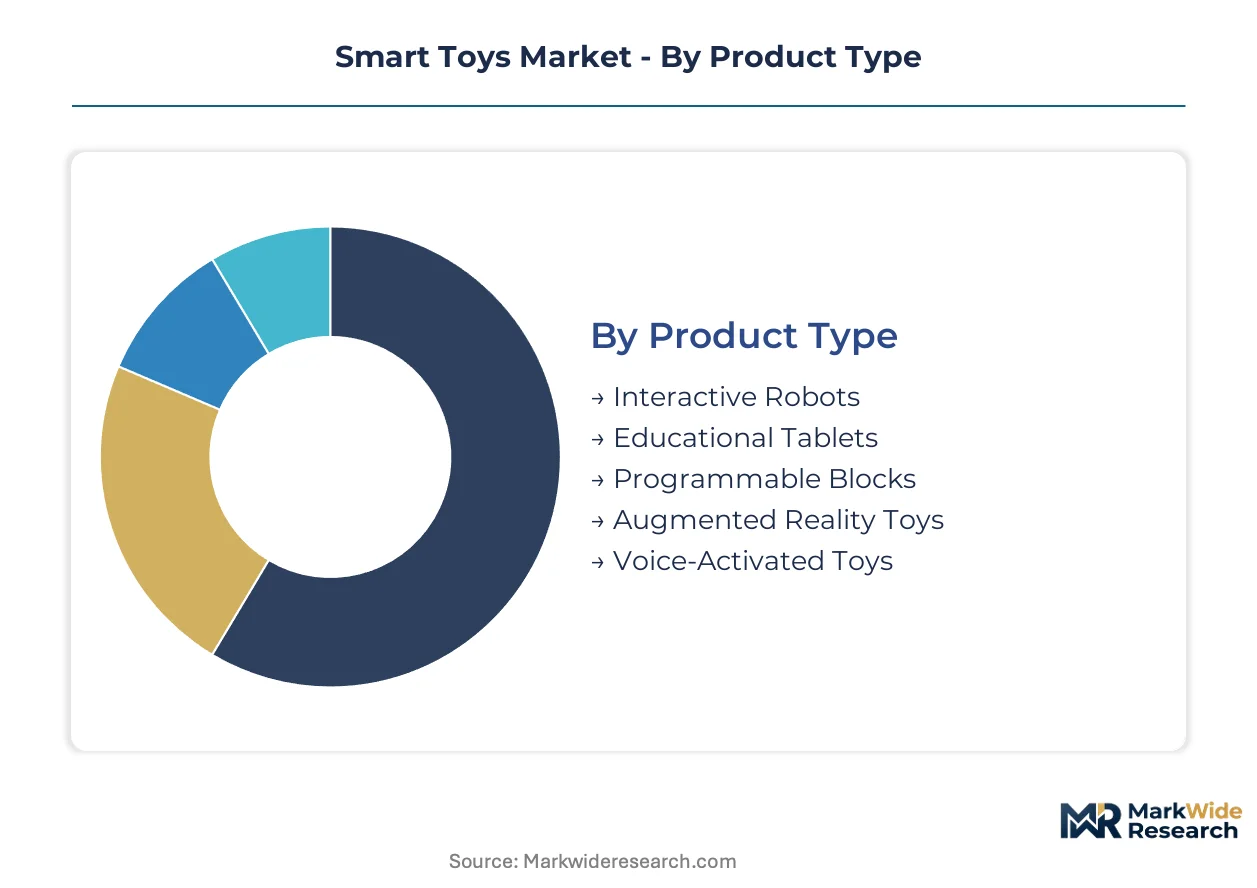
Smart toys demand diverges sharply across use cases, with institutional procurement favoring programmable durability while gift purchases prioritize immediate engagement. Component sourcing strategies and firmware development cycles vary dramatically by segment, creating distinct competitive ecosystems.
Product Type:
Supply concentration clusters around mechatronics-intensive formats where Shenzhen and Dongguan manufacturers dominate subassembly production.
- Interactive Robots:Complex servo motors, gesture-recognition arrays, and rechargeable lithium-polymer cells deliver responsive locomotion. Demand concentrates in German Kita expansion programs and Texas STEM districts where institutional buyers prioritize curriculum alignment over unit cost.
- Educational Tablets:Proprietary content ecosystems run on ARM-based processors with capacitive multitouch displays. China county-level education bureaus and US school district consortia drive volume procurement through approved vendor lists.
- Programmable Blocks:Embedded Bluetooth modules enable drag-and-drop coding interfaces. VTech Holdings and LEGO Group anchor this segment through captive silicon sourcing.
- Augmented Reality Toys:Camera-based spatial mapping overlays digital content onto physical play surfaces. Higher BOM costs limit penetration outside premium gift channels.
- Voice-Activated Toys:Cloud-dependent natural language processing faces EU AI Act compliance redesigns. Hasbro competes here with app-connected product lines requiring parental consent architectures.
Today's leader: Educational Tablets. Tomorrow's challenger: Interactive Robots.
Technology:
Cost tier stratification separates premium neural accelerators from commodity connectivity stacks, with margin compression most severe in mature wireless protocols.
- Artificial Intelligence:Edge inference chips with sub-watt power envelopes enable on-device personalization without GDPR-triggering data transmission. German and French regulators favor this architecture under algorithmic transparency mandates.
- Bluetooth Connectivity:BLE 5.3 integration extends battery life through lower duty cycles. Dongguan manufacturers achieve six-month product development windows using standardized sensor interfaces.
- Motion Sensors:Accelerometer-gyroscope fusion enables gesture-controlled interaction. Capacitive and infrared variants serve different price tiers.
- Touchscreen Interface:Multi-layer capacitive stacks dominate educational tablets. FCC RF exposure testing timelines constrain antenna placement near display edges.
- Voice Recognition:Cloud-to-edge migration accelerates under EU AI Act biometric risk classifications. Documentation burdens reduce feature iteration velocity for adaptive learning functions.
Today's leader: Bluetooth Connectivity. Tomorrow's challenger: Artificial Intelligence.
Application:
Volume concentrates in curriculum-mandated categories where institutional procurement displaces retail distribution.
- STEM Education:Programmable hardware aligns with Bavaria and Texas state curriculum standards. Municipal investment in early childhood facilities creates concentrated demand through education technology distributors.
- Early Learning:Age-tiered software with parental control interfaces targets screen-time management priorities. German Kita programs and US preschool chains drive recurring content licensing revenue.
- Language Development:Phonetic recognition engines support literacy acquisition in multilingual households. GDPR Article 8 consent frameworks enable compliant European launches.
- Creative Play:Open-ended construction systems with digital augmentation bridge physical and virtual engagement. Higher price elasticity constrains mass-market penetration.
- Social Skills Enhancement:Therapeutic play applications face CE marking MDR transition uncertainty. Classification volatility increases compliance cost exposure.
STEM Education holds the steepest expansion trajectory. Early Learning defends the largest installed base.
End User:
Customer type determines channel strategy, with institutional buyers demanding ISO/IEC 27001 certification absent from consumer gift purchases.
- Preschool Children:Durability standards and choke-hazard compliance dominate hardware design. US Consumer Product Safety Commission small-parts testing constrains battery enclosure geometry.
- Elementary Students:Curriculum-aligned content and progress tracking satisfy parental and educator priorities simultaneously. School district consortia consolidate purchasing power.
- Special Needs Learners:Adaptive interfaces and therapeutic classification requirements create regulatory complexity. MDR boundaries remain unresolved for sensory-stimulation products.
- Gift Buyers:Price-point sensitivity and immediate gratification drive seasonal purchasing patterns. Voice-activated formats dominate holiday retail.
- Educational Institutions:Procurement runs through approved vendor lists with localized curriculum alignment requirements. ISO/IEC 27001 data security certification filters vendor eligibility.
Today's leader: Educational Institutions. Tomorrow's challenger: Elementary Students.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate voice-processing architectures to jurisdictions with clearer algorithmic transparency frameworks. Compliance cost differentials between the EU AI Act and US state-level privacy patchworks drive hardware redesign decisions.
United States
Texas STEM districts and California parent-tech coalitions generate concentrated institutional and consumer demand for programmable learning systems. The FCC imposes RF exposure testing timelines that compress selling seasons for Bluetooth-enabled products. Shenzhen manufacturers route final assembly through Los Angeles-Long Beach logistics clusters to satisfy West Coast retail replenishment cycles.
Germany
Bavarian Kita expansion programs and North Rhine-Westphalia education ministries anchor European institutional procurement volume. GDPR Article 8 parental consent frameworks enable compliant voice-activated product launches by reducing legal uncertainty. Berlin-Brandenburg hosts compliance advisory clusters serving toy brands navigating EU AI Act algorithmic documentation requirements.
China
County-level education bureaus in third and fourth-tier cities generate underpenetrated demand for affordable programmable block systems. MIIT oversees GB standards for wireless connectivity in children's products. Dongguan and Shenzhen manufacturing clusters achieve six-month development windows for sensor-integrated toy components through standardized hardware abstraction layers.
Japan
METI promotes STEM curriculum integration in primary education, creating institutional demand for interactive robotics. The country's national data protection framework imposes consent requirements for voice-capture features in children's products. Kanto region electronics assemblers specialize in compact mechatronics subsystems for premium robot formats.
United Kingdom
London and Southeast England parent-tech early adopters prioritize screen-time management features in educational tablets. The national data regulator enforces children's data protection standards that constrain cloud-dependent voice architectures. Midlands distribution hubs consolidate procurement for school district consortia seeking ISO/IEC 27001-certified vendors.
Smart Toys Market Key Industry Players
Chinese producers anchor the component and subassembly tier; European and North American specialists hold premium branded positions. The vendor base stratifies across captive silicon sourcing, proprietary content ecosystems, and modular hardware platforms. Three archetypes dominate: vertically integrated toy conglomerates with in-house programmable systems, education-technology pure-plays with curriculum-aligned software, and contract manufacturers supplying sensor modules to international brands. Competitive moves center on backward integration into Bluetooth module sourcing and strategic partnerships with education technology distributors.
Within the vertically integrated tier, LEGO Group and Hasbro occupy positions defined by in-house production capabilities and multi-format portfolios. VTech Holdings exemplifies the education-technology archetype through proprietary content ecosystems. These three companies represent distinct strategic postures: programmable hardware captivity, voice-activated and app-connected diversification, and age-tiered software specialization.
| Leading Market Players |
|---|
| Spin Master |
| Bandai Namco |
| LEGO Group |
| UBTECH Robotics |
| Sphero |
| Mattel |
| VTech Holdings |
| LeapFrog Enterprises |
| Hasbro |
| Others |
Cost & Logistics Intelligence
Lithium-polymer cell costs from Dongguan and Shenzhen manufacturing clusters cascade through three distinct pricing tiers, with premium interactive robots absorbing complex mechatronics premiums while educational tablets compete on volume-scaled component sourcing.
Pricing Analysis
Distributor margins in the education technology channel compress consumer-facing price points, while direct-to-OEM procurement for institutional buyers unlocks volume discounts tied to ISO/IEC 27001 certification status. Price differentiation hinges on BLE module integration complexity and FCC pre-certification completion, with voice-activated formats facing EU AI Act compliance cost pass-through. Pricing pressure stems from six-month development window compression in Shenzhen, eroding feature premiums across mid-tier programmable blocks. Gift buyers exhibit highest price sensitivity during compressed holiday selling seasons, whereas German Kita procurement demonstrates lowest elasticity due to curriculum-mandated specifications.
Supply Chain Analysis
CE marking and FCC RF exposure qualification gates constrain supplier eligibility, with only certified Dongguan subassembly houses qualifying for premium robot servo motor contracts. Supply concentrates in China, South Korea, and Japan for edge AI inference chips, lithium-polymer cells, and capacitive touch stacks respectively. Raw material dependencies include rare earth magnets for servo motors, cobalt-intensive cathode formulations, and multi-layer ceramic capacitors. Single-source vulnerability persists in neural accelerator system-in-package sourcing from Taiwan semiconductor foundries. Distribution runs through Los Angeles-Long Beach logistics clusters for West Coast retail replenishment and education technology distributors for institutional procurement in Bavaria and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU AI Act compliance costs and US state-level privacy fragmentation creates production relocation incentives, with algorithmic transparency documentation burdens in Berlin-Brandenburg running substantially above Texas regulatory overhead.
For Market Incumbents: Cement captive silicon sourcing positions through backward integration into Bluetooth module design, insulating margin structures from Dongguan component cost volatility. Defend against education-technology pure-plays by accelerating ISO/IEC 27001 certification across product portfolios to maintain approved vendor list eligibility in German state procurement. Prioritize firmware development velocity through hardware abstraction layer standardization to match six-month iteration cycles threatening premium positioning. For New Entrants and Emerging Players: Rural Chinese county-level education bureaus in third and fourth-tier cities represent the most penetrable volume opportunity, with underdistributed programmable block demand exceeding local supplier capacity. Target this archetype through MIIT GB standards-compliant hardware paired with simplified Mandarin curriculum alignment. Pursue direct-to-institution sales models bypassing traditional retail margin stacks, leveraging provincial education technology distributor relationships for channel access. For Investors and Strategic Acquirers: Roll-up economics work for modular hardware platform specialists because proprietary content ecosystem fragmentation creates customer switching cost capture opportunities across acquired portfolios. Long-term viability centers on edge AI inference capability integration as cloud-dependent architectures face regulatory obsolescence. Acquisition targets should demonstrate sub-watt neural accelerator integration roadmaps and established K-12 distributor relationships. Watch for EU AI Act enforcement precedent clarifying algorithmic documentation thresholds as the inflection signal for adaptive learning feature viability.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Processor Integration | On-device voice processing satisfies GDPR Article 8 and EU AI Act biometric risk classifications without cloud dependency. |
| ISO/IEC 27001 Certification Investment | Data security management certification filters vendor eligibility for German Kita and US school district consortia procurement. |
| Hardware Abstraction Layer Standardization | Decoupled mechanical and software design accelerates product iteration cycles for Dongguan six-month development windows. |
| Education Technology Distributor Partnership | Approved vendor list access concentrates institutional volume through Bavarian and Texas STEM procurement channels. |
| Curriculum-Aligned Content Development | Localized software ecosystems defend against proprietary platform switching costs in elementary student segments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with toy manufacturer product managers, education technology distributor procurement leads, FCC certification consultants, and German Kita facility directors with secondary validation against MIIT GB standards filings, US Consumer Product Safety Commission recall databases, EU AI Act implementation guidance documents, and Shenzhen customs export records. Bottom-up component demand modeling and top-down macroeconomic scenario triangulation anchored volume estimates.
Historical reference periods spanning pre-pandemic baseline through recent regulatory implementation phases established the forecast window anchor points. The analytical framework modeled product type, technology stack, application use case, and end-user archetype dimensions across the projection horizon. CAGRs derived from segment-level adoption curve analysis incorporating BLE 5.3 penetration rates, STEM curriculum mandate expansion timelines, and lithium-polymer cell cost trajectories. Edge AI chip pricing elasticity and institutional procurement cycle seasonality informed scenario boundaries.
Underlying measurement precision varies by segment; educational tablets and programmable blocks carry tighter precision than therapeutic play applications facing CE marking MDR classification uncertainty. Forecasts reflect documented assumptions regarding EU AI Act enforcement intensity, German Kita expansion funding continuity, and Shenzhen manufacturing cluster output stability. Deviation in FCC RF exposure testing timeline extensions or lithium-polymer supply concentration disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Children Entertainment Centers Market
Toys and Games
Model Train Market
Toys and Games
Blind Box Toys Market
Toys and Games
Kid's Microphone Market
Toys and Games
Games and Puzzles Market
Toys and Games
Kids Toys Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
Autonomous Robot Toys Market
Toys and Games
Global Educational Toy Market
Toys and Games
Inflatable Toys Market
Toys and Games
Toy Collectibles Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Snooker Tables Market
Toys and Games
Coaster Market
Toys and Games
Pre-School Games and Toys Market