
 Animal-Based Pet Protein Market | 2026-2036
Animal-Based Pet Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Animal-Based Pet Protein Market Outlook
Subscription-based fresh pet food delivery is restructuring how animal-based protein reaches end consumers, shifting volume from retail shelves to direct-to-consumer replenishment models. Mars Petcare leverages its global manufacturing footprint to sustain cost advantages in wet food production. Nestle Purina Petcare anchors North American distribution through veterinary clinic partnerships and mass retail penetration. Champion Petfoods specializes in premium freeze-dried and raw formulations, occupying the highest price tier with biologically appropriate positioning.
Animal-based pet protein encompasses rendered meat meals, fresh muscle tissue, organ meats, and hydrolyzed animal proteins formulated to deliver complete amino acid profiles for companion animal nutrition. These ingredients typically undergo extrusion, retorting, or freeze-drying to achieve shelf stability while preserving protein digestibility coefficients above 80 percent for canine and feline metabolic needs. Dry food remains the volume backbone due to manufacturing scale and logistics efficiency, though raw and high-protein formulation types are expanding fastest as owners prioritize species-appropriate diets. Wet food commands disproportionate margin pools because of higher meat inclusion rates and premium positioning in veterinarian clinics and specialty stores.
FDA Center for Veterinary Medicine oversight of pet food safety, combined with AAFCO model feed regulations and state-level agriculture department enforcement, creates a layered compliance environment that elevates barriers for new entrants. The USDA and FSIS maintain jurisdiction over certain slaughter byproducts entering pet food supply chains, affecting raw material availability and traceability requirements. Stakeholders must monitor evolving state legislation on raw pet food retail and the interplay between online channel growth and veterinary endorsement requirements.
Market Dynamics
Subscription-based fresh pet food delivery is restructuring how animal-based protein reaches end consumers, shifting volume from retail shelves to direct-to-consumer replenishment models. This channel migration compresses traditional distributor margins while demanding cold-chain logistics capabilities that renderers and meat processors must now build.
Growth Catalysts
- AAFCO Nutritional Adequacy Protocols:Tightening label claims for raw and high-protein formulations in the United States are forcing manufacturers to invest in third-party testing infrastructure, which elevates product credibility among discerning urban millennial pet owners.
- Freeze-Drying Technology:Advances in commercial freeze-drying equipment are lowering per-unit processing costs for premium biologically appropriate formulations, expanding addressable market tiers beyond ultra-premium early adopters.
- Metropolitan Pet Ownership Concentration:Dense urban clusters in the United States with high disposable income levels are generating sufficient order density to justify last-mile cold-chain investments by direct-to-consumer protein suppliers.
Market Restraints
- Rendered Meat Meal Input Volatility:Fluctuating availability of slaughter byproducts from USDA-inspected facilities creates raw material uncertainty for extruded dry food manufacturers dependent on cost-stable protein meals.
- Veterinary Clinic Distribution Concentration:Wet food margin pools concentrate disproportionately in veterinarian clinic channels controlled by Nestle Purina and Mars Petcare, limiting shelf access for emerging premium entrants without established veterinary salesforces.
- Raw Pet Food State Legislation:Fragmented state-level agriculture department enforcement across the United States creates compliance complexity for direct-to-consumer raw protein shippers operating across multiple jurisdictions.
Strategic Opportunities
- Underpenetrated Suburban Markets:Secondary metropolitan statistical areas in the United States with rising pet ownership rates lack sufficient cold-chain infrastructure, presenting first-mover advantages for regional fulfillment hub deployment.
- Hydrolyzed Protein Therapeutic Applications:Veterinary dermatology and gastrointestinal prescription diets represent an emerging application segment where AAFCO-compliant hydrolyzed animal proteins command premium pricing through clinic-exclusive distribution.
- Biologically Appropriate Positioning:Champion Petfoods' freeze-dried and raw formulation expertise demonstrates viable white space at the highest price tier, where organ meat and fresh muscle tissue inclusion rates differentiate from commodity extruded products.
Industry Challenges
- Cold-Chain Capex Intensity:Direct-to-consumer fresh protein delivery requires refrigerated warehousing and specialized last-mile fleet investments that strain capital reserves of mid-tier manufacturers without Mars Petcare's global manufacturing footprint.
- Digestibility Certification Timelines:AAFCO feeding trial protocols and third-party protein digestibility coefficient verification create extended product development cycles that delay raw and high-protein formulation launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal-Based Pet Protein Market |
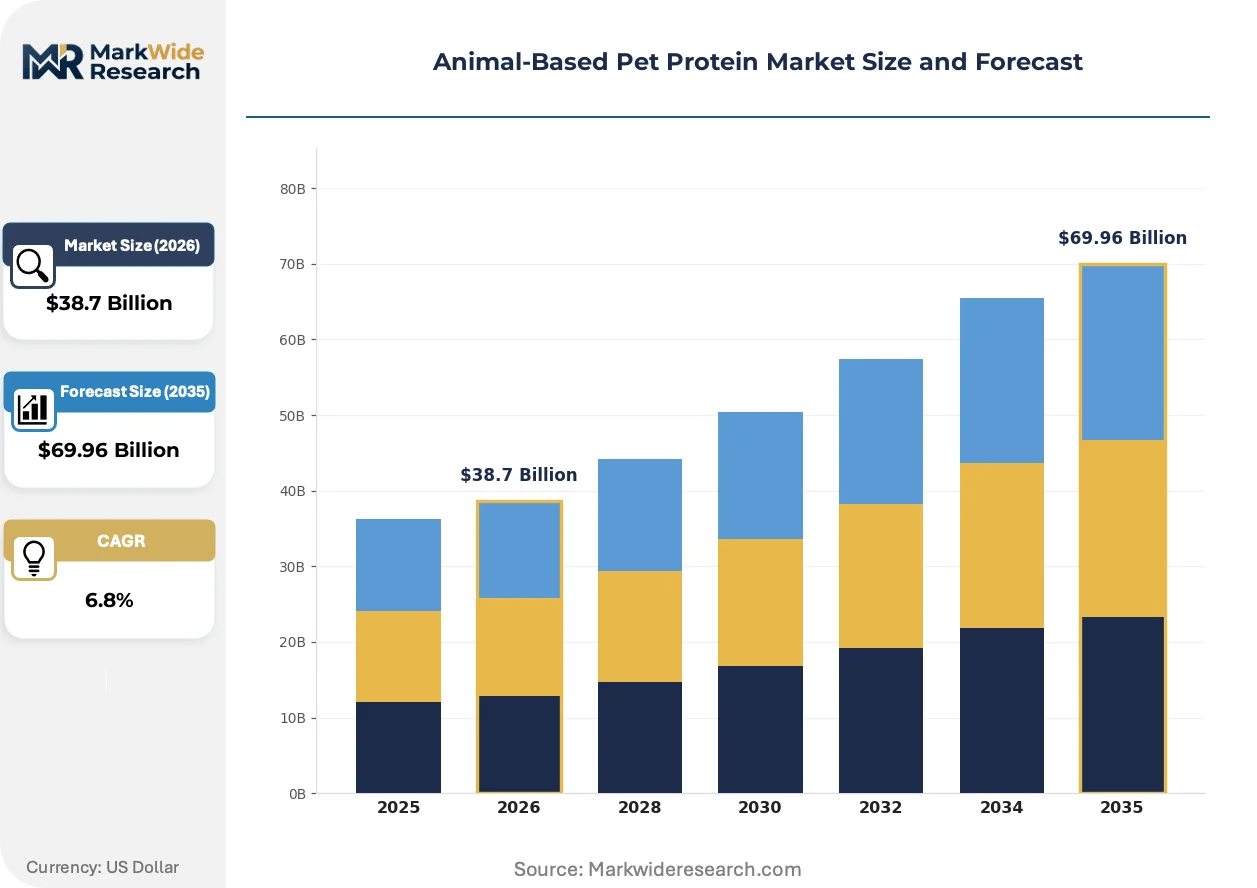
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Formulation Type: Grain-Free, High-Protein, Organic, Raw Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Veterinarian Clinics Target Species: Dogs, Cats, Birds, Exotic Pets |
| Companies Covered | Nestle Purina Petcare, Mars Petcare, Hill's Pet Nutrition, Blue Buffalo, Champion Petfoods, Diamond Pet Foods, Wellness Pet Company, Stella & Chewy’s, Merrick Pet Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal-Based Pet Protein Market Strategic Shifts
Fresh pet food subscription services are compressing traditional retail distribution layers while simultaneously elevating transparency requirements around protein sourcing and processing methods. This dual pressure is forcing ingredient suppliers and finished goods manufacturers to rebuild operational architectures around traceability and direct fulfillment.
High-pressure processing (HPP) technology is decentralizing pathogen control in raw pet food manufacturing. Premium subscription services in the United States are adopting HPP at accelerating rates to achieve FDA Center for Veterinary Medicine safety standards without thermal degradation of amino acid profiles. This cold-pasteurization approach is decentralizing production geography by enabling smaller regional facilities to operate without retort infrastructure.
EU Green Deal sustainability reporting requirements under the Corporate Sustainability Reporting Directive are extending supply chain due diligence obligations to pet food importers sourcing animal proteins from third countries. European manufacturers must now document livestock origin, feed conversion ratios, and slaughter byproduct traceability across their protein supply networks. Wet food producers with complex multi-source supply chains face disproportionate compliance burden compared to single-source freeze-dried specialists.
Urban millennial pet owners are consolidating purchase decisions around subscription replenishment models that eliminate retail intermediary markups. Direct-to-consumer channels in United States metropolitan areas are displacing mass retail and specialty store volume for fresh and raw protein formulations. This behavioral shift concentrates demand forecasting risk with manufacturers while transferring inventory carrying costs from retailers to protein suppliers operating captive fulfillment networks.
Animal-Based Pet Protein Market Segmentation
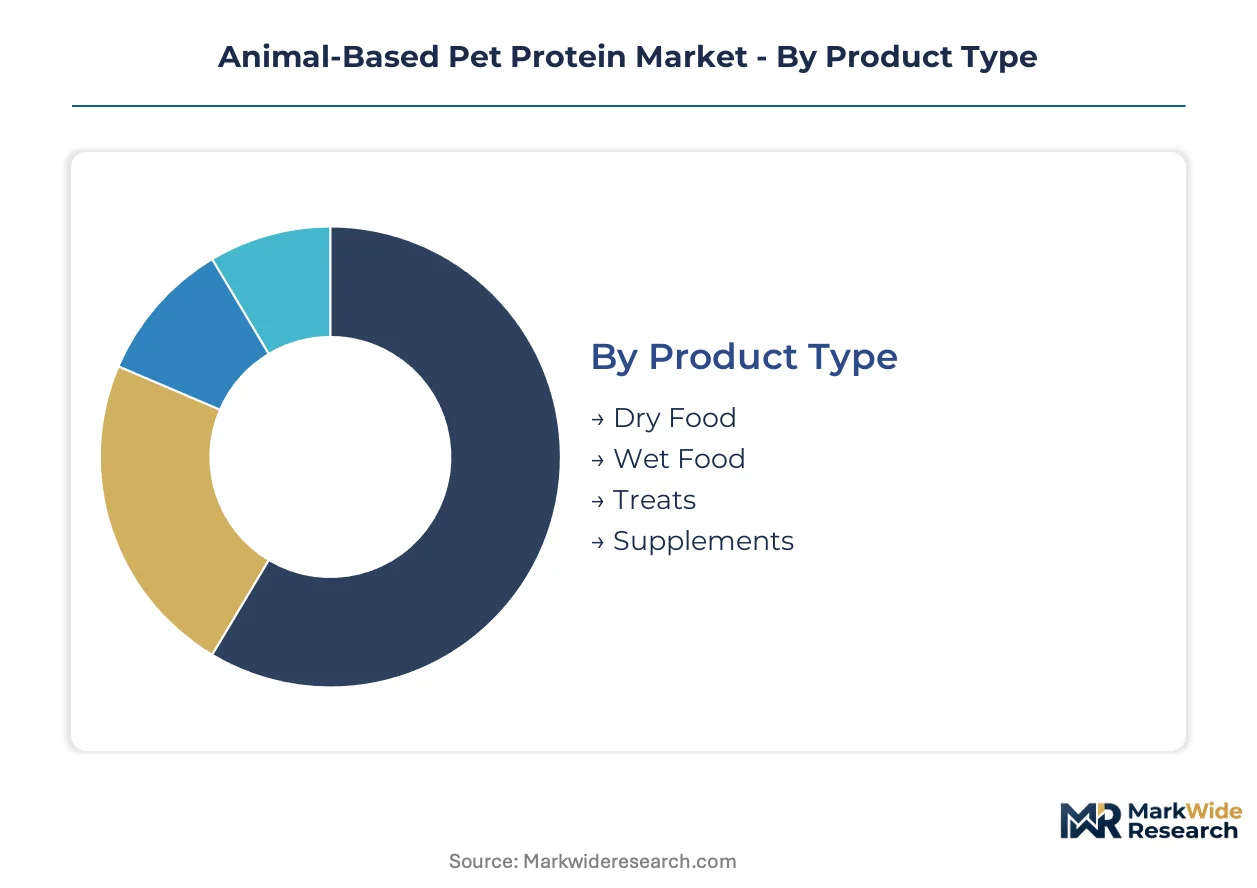
Segmentation in animal-based pet protein markets reveals how regulatory burden, formulation complexity, and channel economics concentrate margin pools. Each dimension exposes distinct barriers to entry and competitive positioning strategies.
Product Type:
Dry food formulations carry lighter AAFCO feeding trial requirements than raw alternatives, while wet food demands stricter pathogen controls under FDA Center for Veterinary Medicine guidelines.
- Dry Food:Extruded kibble formulations using rendered meat meals achieve manufacturing scale advantages through continuous production lines. Demand concentrates in suburban United States households prioritizing shelf stability and cost efficiency, though AAFCO protein digestibility coefficient verification adds compliance overhead.
- Wet Food:Retorted cans and pouches with higher fresh muscle tissue inclusion command premium positioning in veterinary clinic channels. Metropolitan United States markets with elevated disposable income levels generate sufficient volume to justify specialized retort infrastructure investments.
- Treats:Freeze-dried liver and organ meat snacks occupy impulse purchase occasions with lighter regulatory scrutiny than complete diets.
- Supplements:Hydrolyzed protein powders and amino acid boosters target therapeutic applications requiring veterinary endorsement.
Dry food sits at the top of the volume ranking, with raw-adjacent wet formulations climbing the fastest.
Formulation Type:
Cost tier stratification separates commodity extruded products from biologically appropriate positioning at premium price levels.
- Grain-Free:Potato and legume-based carbohydrate substitutes respond to canine dilated cardiomyopathy concerns flagged by FDA veterinary alerts. United States metropolitan markets with veterinary-influenced purchase decisions show concentration here.
- High-Protein:Formulations exceeding AAFCO minimum crude protein thresholds by 40-60 percent target athletic and working dog segments. Raw and freeze-dried delivery formats in dense urban clusters justify cold-chain infrastructure deployment.
- Organic:USDA Organic certification requirements for livestock sourcing limit supplier pools and elevate input costs.
- Raw:Unprocessed muscle tissue and organ meat blends face fragmented state-level agriculture department enforcement across United States jurisdictions.
High-protein formulations capture the steepest expansion trajectory, while organic certification requirements constrain volume growth.
Distribution Channel:
Channel selection determines margin retention, with direct-to-consumer models capturing intermediary markups at the cost of logistics complexity.
- Online Retail:Subscription replenishment platforms eliminate retail intermediary margins while demanding captive cold-chain fulfillment networks. United States metropolitan statistical areas with sufficient order density support regional hub economics.
- Specialty Stores:Independent pet retailers provide shelf access for freeze-dried and biologically appropriate brands without veterinary salesforce requirements.
- Supermarkets:Mass retail penetration favors Mars Petcare and Nestle Purina scale advantages in dry food volume.
- Veterinarian Clinics:Prescription diet distribution concentrates wet food margin pools behind established veterinary sales relationships.
Online retail is gaining share fastest, though veterinarian clinics retain the highest margin per unit.
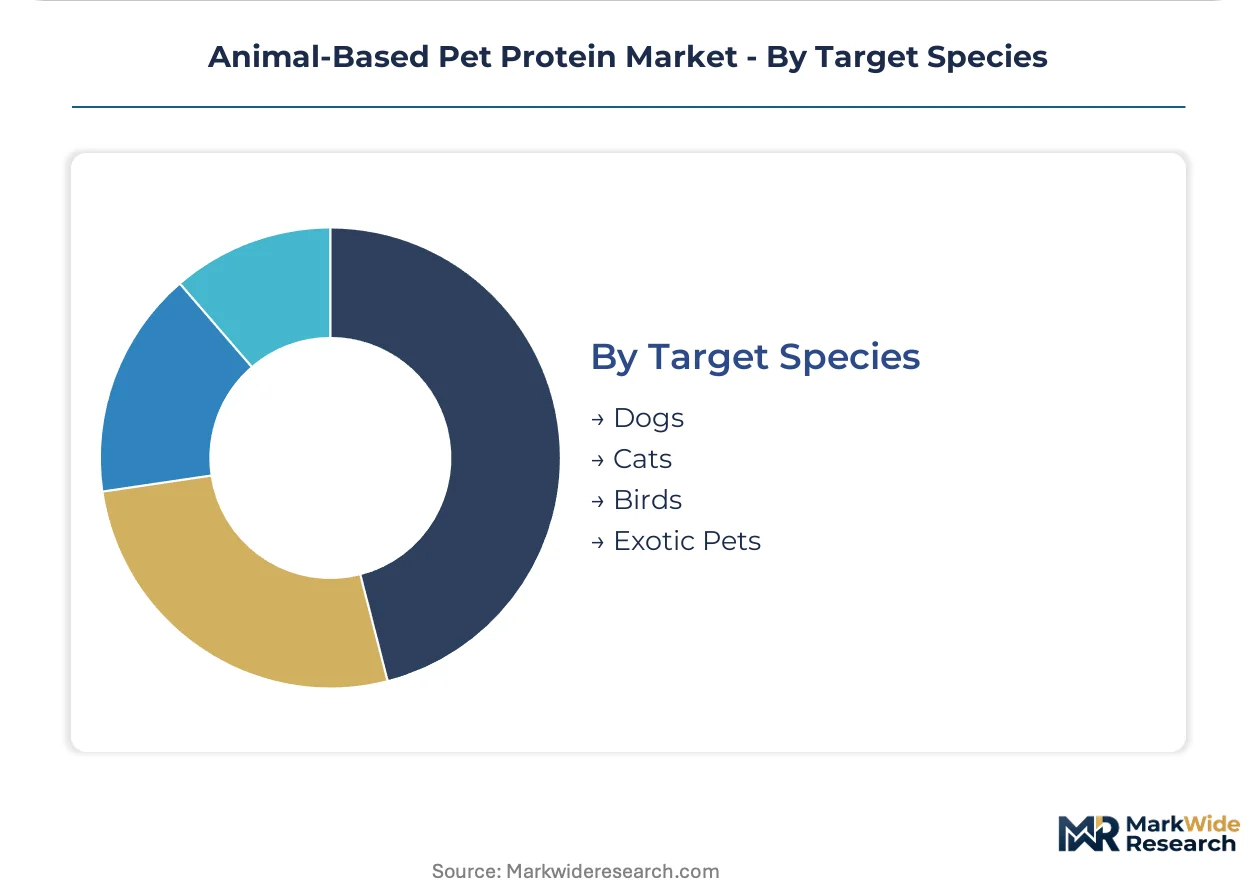
Target Species:
Species-specific metabolic requirements drive formulation differentiation in amino acid profiling and digestibility certification.
- Dogs:Omnivorous digestive physiology accommodates broader protein source flexibility than obligate carnivores. United States household penetration exceeds feline ownership, anchoring volume concentration.
- Cats:Taurine and arachidonic acid requirements mandate higher organ meat inclusion rates, elevating input costs and justifying premium positioning.
- Birds:Seed and insect protein alternatives limit addressable market for mammalian-derived formulations.
- Exotic Pets:Reptile and small mammal segments require species-specific amino acid profiles with limited manufacturing scale.
Dog formulations dominate volume, with cat-specific recipes expanding most quickly on per-unit value metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are steering animal-based pet protein manufacturing toward jurisdictions with streamlined veterinary oversight and lower cold-chain compliance burdens. Production migration patterns track closely to where AAFCO-equivalent standards impose lighter documentation requirements on raw material traceability.
United States
Metropolitan demand clusters in New York, Los Angeles, and Chicago sustain subscription-based fresh protein delivery models requiring dense last-mile order economics. FDA Center for Veterinary Medicine enforcement of raw pet food safety standards elevates capital requirements for new entrants. Texas and Nebraska host rendering facilities supplying meat meal inputs to extruded dry food manufacturers serving suburban mass retail channels.
Germany
EU Green Deal sustainability reporting obligations under CSRD extend supply chain due diligence to pet food importers sourcing rendered proteins from third countries. EFSA nutritional adequacy guidelines for companion animals create compliance parity with AAFCO standards, reducing regulatory arbitrage opportunities. The North Rhine-Westphalia industrial corridor concentrates wet food retort capacity serving veterinary clinic distribution across the Benelux region.
China
SAMR food safety regulations for imported pet food ingredients mandate registration of overseas manufacturing facilities, constraining raw material sourcing flexibility for domestic formulators. Yangtze River Delta processing hubs supply hydrolyzed protein ingredients to therapeutic diet manufacturers targeting East Asian veterinary markets. Shanghai cold-chain logistics providers are building regional fulfillment capabilities for fresh subscription services.
United Kingdom
Post-Brexit divergence from EU feed hygiene regulations creates parallel compliance tracks for animal protein imports from Ireland and continental Europe. London and Southeast England concentrate direct-to-consumer fresh pet food subscription density sufficient to justify dedicated refrigerated warehousing. The Midlands host rendering operations supplying meat meals to dry food extrusion plants serving mass retail distribution.
Canada
Health Canada and CFIA joint oversight of pet food safety aligns closely with FDA protocols, facilitating cross-border supply chain integration with United States manufacturers. Ontario and Quebec veterinary clinic networks distribute prescription diets incorporating hydrolyzed proteins for dermatological applications. Prairie province rendering facilities supply cost-stable meat meal inputs to extruded food producers competing on price in North American mass retail.
Animal-Based Pet Protein Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with veterinary clinic channels concentrating around established salesforce relationships while direct-to-consumer models elevate transparency requirements over scale advantages. The market exhibits tiered consolidation: multinational CPG conglomerates anchor mass retail and clinic distribution, mid-tier regional players serve specialty retail, and venture-backed subscription specialists capture urban premium demand. Three archetypes dominate—vertically integrated render-to-retail operators, ingredient-focused contract manufacturers, and digitally native fresh food platforms. Capacity expansion in freeze-drying equipment and strategic partnerships with cold-chain logistics providers constitute the primary competitive moves reshaping positioning.
Among the multinational CPG anchors, Nestle Purina Petcare and Mars Petcare exemplify scale-driven consolidation across veterinary clinic and mass retail channels. Champion Petfoods occupies a position within the premium biologically appropriate tier, demonstrating viable positioning through freeze-dried and raw formulation specialization. These three entities represent distinct strategic postures: the first two leverage global manufacturing footprints and established distribution relationships, while the third anchors ultra-premium pricing through ingredient transparency and species-appropriate nutritional positioning.
| Leading Market Players |
|---|
| Nestle Purina Petcare |
| Mars Petcare |
| Hill's Pet Nutrition |
| Blue Buffalo |
| Champion Petfoods |
| Diamond Pet Foods |
| Wellness Pet Company |
| Stella & Chewy's |
| Merrick Pet Care |
| Others |
Value Chain & Pricing Dynamics
Urban millennial subscription buyers in United States metropolitan clusters anchor pricing power toward direct-to-consumer replenishment models that eliminate retail intermediary markups. This buyer concentration compresses traditional distributor margins while elevating transparency premiums for traceable protein sourcing.
Pricing Analysis
Capacity additions in freeze-drying equipment across North American processing hubs are reshaping price floors for premium biologically appropriate formulations. Three-tier pricing structure across premium, standard, and economy levels separates subscription fresh delivery from veterinary clinic wet food and mass retail dry kibble. Cost compression in economy extruded segments is intensifying because rendered meat meal input volatility strains cost-stable formulation. Mass retail suburban households exhibit highest price sensitivity, while veterinary clinic prescription diet buyers demonstrate lowest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from FDA Center for Veterinary Medicine and AAFCO compliance requirements force manufacturers to qualify multiple rendering facilities and protein meal suppliers. Geographic supply concentration centers on United States, Canada, and Germany, with Nebraska and Texas rendering operations feeding North American dry food extrusion. Raw material dependencies rest on USDA-inspected slaughter byproducts, hydrolyzed protein isolates, and freeze-dried organ meats. Single-source vulnerability in cold-chain logistics infrastructure poses structural risk for direct-to-consumer fresh protein shippers. Distribution runs through veterinary clinic networks, mass retail shelves, and captive subscription fulfillment hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal-based pet protein functions as a stable compounder underpinned by irreversible humanization trends in companion animal nutrition that sustain premiumization across economic cycles.
For Market Incumbents: Hedge against subscription channel displacement by acquiring regional cold-chain logistics capabilities or partnering with last-mile refrigerated fleet operators. Mars Petcare and Nestle Purina should deepen backward integration into rendering assets to secure cost-stable protein meal inputs against USDA facility availability fluctuations. Freeze-drying capacity expansion in underpenetrated suburban markets offers defensive positioning against venture-backed fresh food platforms. For New Entrants and Emerging Players: Capture white space in hydrolyzed protein therapeutic applications for veterinary dermatology and gastrointestinal prescription diets, where AAFCO-compliant formulations command clinic-exclusive premium positioning. Secondary metropolitan statistical areas in the United States with rising pet ownership rates and insufficient cold-chain infrastructure represent the most penetrable geography. Deploy regional fulfillment hub economics ahead of national scale to justify last-mile investments. For Investors and Strategic Acquirers: Pet food CPG conglomerates with stagnant core portfolios are the most active acquirer in this space, seeking growth vectors through premium freeze-dried and raw formulation specialists. Mid-tier manufacturers with captive freeze-drying assets and established AAFCO feeding trial infrastructure represent the optimal acquisition target archetype. Watch for inflection in state-level raw pet food legislation enforcement intensity as signal for direct-to-consumer regulatory risk recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Lowers per-unit processing costs for Champion Petfoods-tier biologically appropriate positioning. |
| Cold-Chain Logistics Partnership | Enables Stella & Chewy's archetype entrants to match Mars Petcare last-mile capabilities. |
| Veterinary Clinic Distribution Lock | Secures prescription diet margin pools behind Hill's Pet Nutrition-style salesforce relationships. |
| AAFCO Feeding Trial Investment | Accelerates third-party protein digestibility certification timelines for raw formulation launches. |
| Subscription Platform Integration | Consolidates urban millennial demand into captive replenishment models displacing retail volume. |
Study Parameters
Multiple input streams — executive interviews with pet food manufacturing leadership, regulatory affairs specialists at FDA Center for Veterinary Medicine, veterinary clinic procurement directors, and subscription platform operations heads — were reconciled against AAFCO model feed regulations, USDA FSIS slaughter byproduct traceability records, and SEC 10-K disclosures from publicly traded CPG parents. Secondary validation drew from customs data on rendered protein imports, Nielsen retail audit figures, and state agriculture department enforcement records. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Data-stream reconciliation across product type, formulation complexity, distribution channel, and target species dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from trajectory analysis of subscription penetration curves, freeze-drying equipment deployment rates, and metropolitan pet ownership density correlations. Industry-specific forecast inputs included AAFCO nutritional adequacy protocol adoption timelines and cold-chain infrastructure investment flows.
Raw pet food state legislation fragmentation, rendered meat meal input volatility, and veterinary clinic channel consolidation are the dominant revision risks to modeled projections. Deviation in FDA enforcement intensity for high-pressure processing safety standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Cat Accessories Market
Pet Care Products
Cat Collar Market
Pet Care Products
US and Mexico Cat Litter Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Vegan Pet Food Market
Pet Care Products
Pet Food Pulverizer Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
North America Pet Food Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
Dog Dental Chews Market
Pet Care Products
Dog Hats Market
Pet Care Products
Dog Clippers Market