
 Southeast Asia Pet Care Market | 2026-2036
Southeast Asia Pet Care Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Pet Care Market Analytics
The EU Green Deal is rebalancing ingredient sourcing requirements for Southeast Asian pet food exporters, forcing reformulation toward sustainable protein inputs. Mars Petcare leverages its integrated supply chain to preempt compliance costs across Thai manufacturing facilities. Nestlé Purina PetCare anchors its regional R&D hub in Bangkok to localize palatability standards for tropical climates. Perfect Companion Group differentiates through vertical control over aquaculture byproducts used in premium formulations.
Pet care encompasses nutrition, hygiene maintenance, accessory provisioning, and health services for companion animals, with dry kibble formulations typically containing 18-32% crude protein derived from poultry, fish, or plant meals to meet FEDIAF nutritional adequacy profiles. The primary commercial purpose centers on extending animal longevity while aligning owner expenditure with humanization-driven quality expectations. Dog Food dominates absolute spend across the region, though Pet Grooming records the fastest expansion as salon culture penetrates Indonesian and Vietnamese cities. Veterinary Clinics capture disproportionate margin pools through prescription diet tie-ins, while Online Retail erodes traditional Pet Shops in metro areas.
Thailand's FDA-equivalent food and drug administration, Malaysia's Department of Veterinary Services, and Vietnam's Ministry of Agriculture and Rural Development collectively enforce feed safety, import quarantine, and labeling standards that determine market access for foreign brands. These frameworks elevate compliance costs for small domestic producers while advantaging multinationals with dedicated regulatory affairs teams. Stakeholders must monitor evolving ASEAN harmonization talks on pet food mutual recognition, as divergent national regimes currently fragment regional scale economies.
Market Dynamics
Urban pet humanization across Bangkok, Ho Chi Minh City, and Jakarta is compressing product lifecycles and forcing manufacturers to synchronize innovation cadences with veterinary channel requirements rather than traditional retail replenishment cycles.
Growth Catalysts
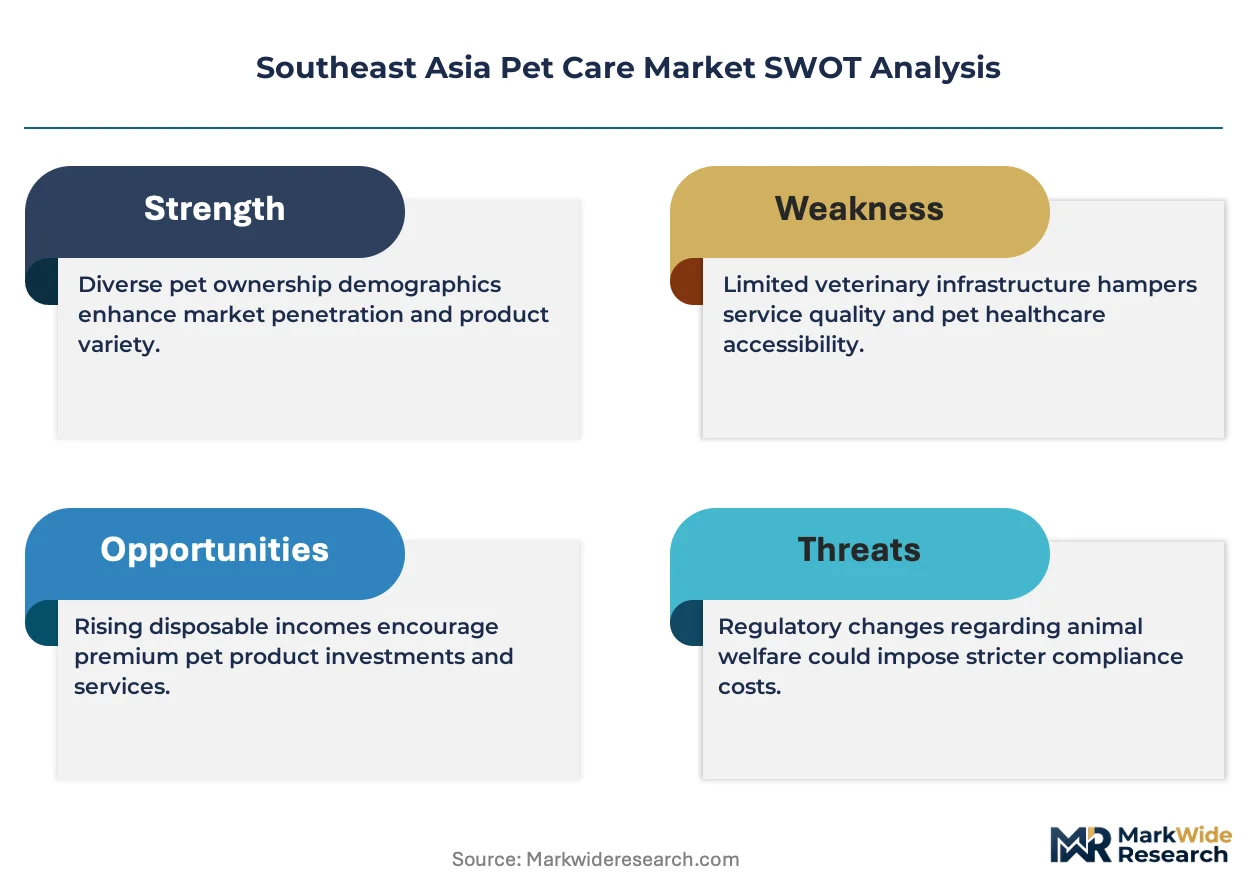
- EU Green Deal due diligence:Extended supply chain accountability requirements are accelerating sustainable protein sourcing investments among Thai and Vietnamese exporters seeking continued European market access.
- Metro corridor density:Bangkok's veterinary service concentration and pet salon infrastructure create self-reinforcing spending ecosystems that pull adjacent provincial demand toward premium tiers.
- Insect protein processing:Black soldier fly larvae cultivation facilities in Thailand and Malaysia are reducing reliance on imported fishmeal while meeting FEDIAF amino acid profiles.
Market Restraints
- Fishmeal price volatility:Peruvian anchovy quota fluctuations transmit directly into Southeast Asian premium kibble cost structures, compressing margin predictability for mid-tier producers.
- Regulatory fragmentation:Divergent national feed safety regimes across Thailand's FDA-equivalent, Malaysia's Department of Veterinary Services, and Vietnam's Ministry of Agriculture prevent regional scale economies in formulation and labeling.
- Veterinary channel gatekeeping:Prescription diet authorization requirements in Thailand and Malaysia restrict direct consumer access to therapeutic nutrition, limiting brand building opportunities.
Strategic Opportunities
- Indonesian archipelago penetration:Surabaya and Bandung secondary cities remain underserved by premium grooming chains and specialized veterinary diagnostics, offering first-mover positioning.
- Telehealth-veterinary convergence:Remote consultation platforms are integrating with subscription nutrition deliveries, creating recurring revenue architectures that bypass traditional retail slotting fees.
- ASEAN mutual recognition:Pending harmonization talks on pet food standards would collapse compliance duplication costs and enable centralized manufacturing with multi-country distribution.
Industry Challenges
- Regulatory affairs talent scarcity:Specialized expertise in navigating Thailand's FDA-equivalent feed registration and Vietnam's import quarantine protocols commands premium compensation, constraining smaller domestic competitors.
- Cold chain reconfiguration:Raw and fresh pet food segments require temperature-controlled logistics investments that legacy dry kibble distributors lack, forcing parallel infrastructure buildouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Pet Care Market |
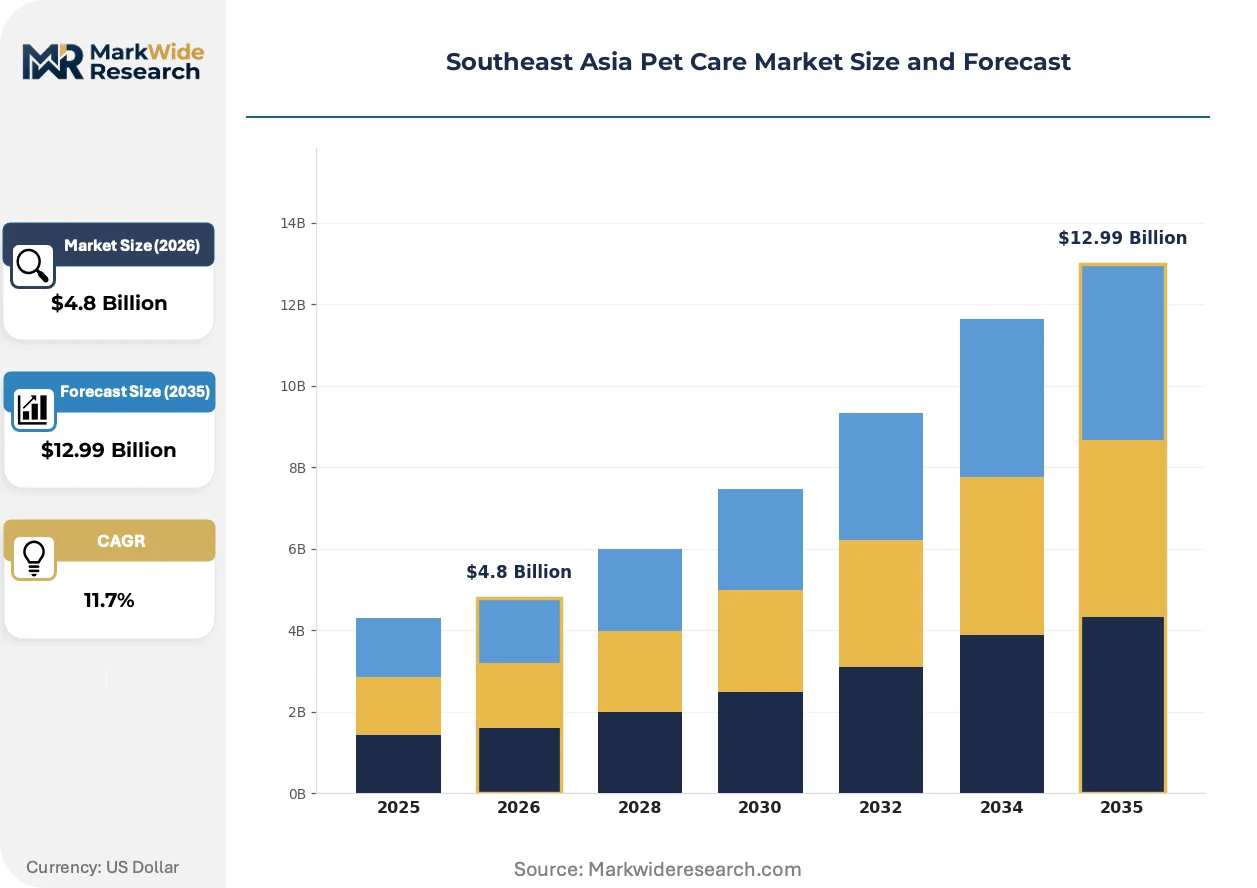
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dog Food, Cat Food, Pet Grooming, Pet Accessories Distribution Channel: Online Retail, Supermarkets, Pet Shops, Veterinary Clinics Customer Type: Pet Owners, Breeders, Pet Rescuers, Veterinarians Service Type: Grooming Services, Training Services, Veterinary Services, Boarding Services |
| Companies Covered | Perfect Companion Group, Charoen Pokphand Group, Mars Petcare, Tropical Canning Corp Sdn Bhd, Powerpets Food Sdn Bhd, Nestlé Purina PetCare, i-Tail Corporation, Betagro Pet Business, Hill's Pet Nutrition, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Pet Care Market Evolving Landscape
Digital channel migration and protein source diversification are simultaneously compressing traditional retail margins and opening formulation pathways previously blocked by cost or supply constraints.
Precision fermentation for cultivated meat proteins is integrating into pilot-scale Thai manufacturing facilities, enabling allergen-free formulations that bypass conventional livestock supply constraints. Bangkok-based R&D centers are validating palatability and digestibility profiles specific to tropical heat stress conditions. This technology is integrating upstream into ingredient supply agreements, locking in multi-year offtake structures that preempt spot market volatility.
Thailand's FDA-equivalent has tightened residual antibiotic screening in imported animal proteins, forcing exporters to document farm-level veterinary protocols through blockchain-traceable supply chains. Malaysian and Vietnamese regulators are observing this precedent for potential domestic adoption. Premium therapeutic diet manufacturers face the steepest compliance burden, as their protein concentration levels amplify detection sensitivity requirements.
Subscription-based replenishment models are displacing episodic pet shop purchasing among Bangkok and Singapore metropolitan households, compressing customer acquisition costs while extending lifetime value metrics. Automated reorder algorithms tied to consumption tracking apps are reducing stockout frequency and brand switching. This behavioral shift concentrates most visibly among dual-income households in Vietnam's Hanoi and Ho Chi Minh City corridors, where time scarcity overrides price sensitivity in channel selection.
Southeast Asia Pet Care Market Segmentation
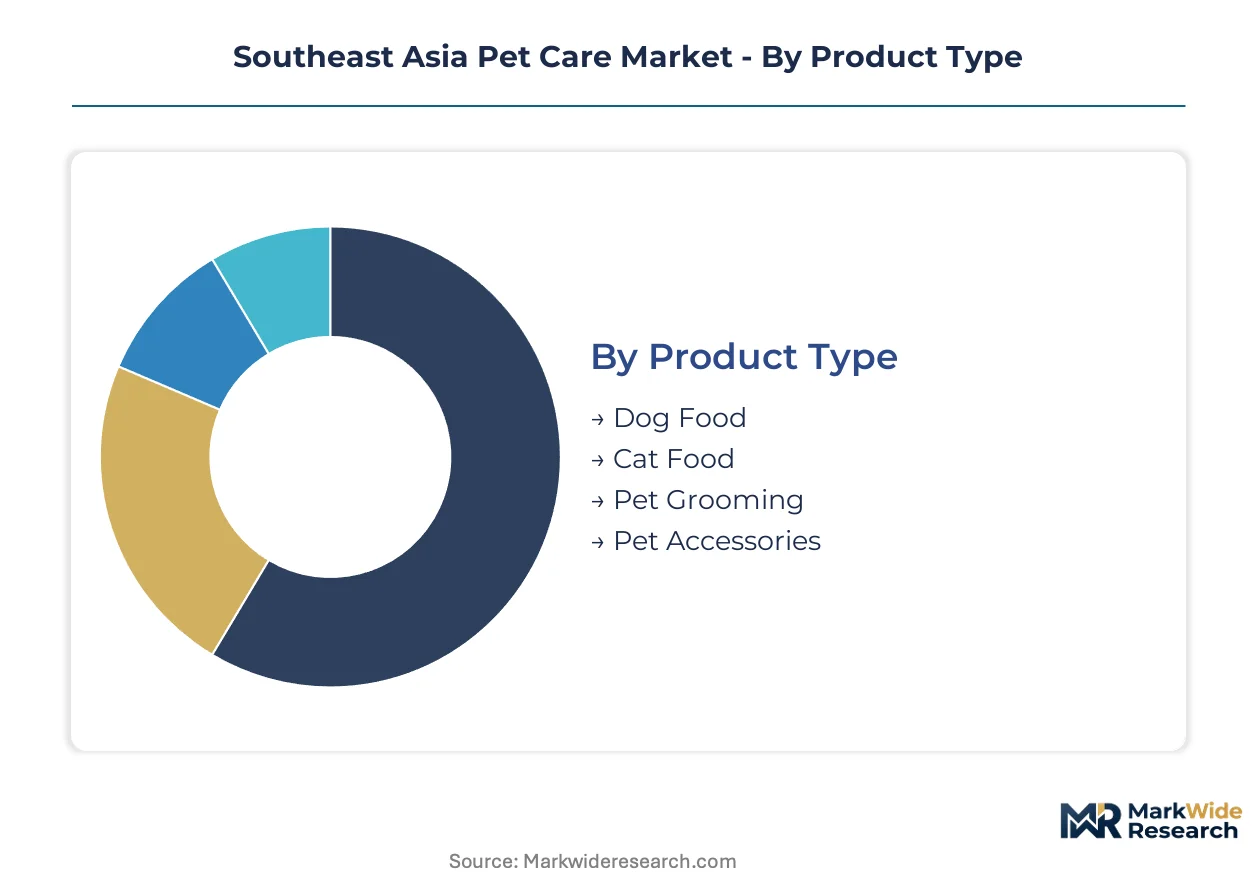
Southeast Asian pet care procurement patterns fragment across four distinct classification axes. Regulatory burden intensity varies dramatically by product type and channel, determining margin capture and compliance investment thresholds for market participants.
Product Type:
Dry kibble formulations require Thailand FDA-equivalent feed registration and FEDIAF nutritional adequacy certification, while grooming consumables face lighter cosmetic-grade oversight. Wet food and fresh formats trigger additional cold chain documentation under Vietnamese and Malaysian import protocols.
- Dog Food:Dry and wet formulations typically contain 18-32% crude protein from poultry, fish, or plant meals. Bangkok's metropolitan corridor generates the region's highest per-capita canine nutrition spend, driven by veterinary prescription diet tie-ins and salon culture cross-selling.
- Cat Food:Higher moisture content and taurine fortification requirements distinguish feline formulations from canine equivalents. Premium freeze-dried and raw segments concentrate in Singapore and Bangkok households with above-median disposable income, though cold chain infrastructure gaps limit provincial penetration.
- Pet Grooming:Shampoos, conditioners, and dental wipes fall under cosmetic rather than feed safety frameworks, reducing registration timelines.
- Pet Accessories:Collars, bedding, and interactive toys face minimal regulatory barriers beyond general product safety standards.
Leading the category by volume: Dog Food. Growing fastest: Pet Grooming.
Distribution Channel:
Channel selection determines customer acquisition economics and brand control intensity. Veterinary clinics and online platforms command divergent margin structures but share above-average customer lifetime value profiles.
- Online Retail:Subscription algorithms and automated replenishment compress stockout frequency among Bangkok and Hanoi dual-income households. Platform commission rates of 15-25% erode manufacturer margins compared to direct veterinary channels.
- Supermarkets:Mass-market kibble and basic accessories dominate shelf space, with slotting fees favoring Mars Petcare and Nestlé Purina scale economies. Ho Chi Minh City and Jakarta hypermarket clusters serve provincial traders restocking independent pet shops.
- Pet Shops:Independent retailers in Surabaya and Bandung secondary cities retain grooming service bundling advantages.
- Veterinary Clinics:Prescription diet authorization requirements in Thailand and Malaysia restrict direct consumer access, creating gatekeeper margin pools.
Volume leadership: Supermarkets. Steepest expansion trajectory: Online Retail.
Customer Type:
Procurement sophistication and price sensitivity diverge sharply across owner categories, with veterinarians and breeders demanding batch-traceable documentation absent from mass-market transactions.
- Pet Owners:Urban millennials in Bangkok and Vietnam's major corridors drive premium tier migration, prioritizing humanization-aligned ingredient transparency over unit cost minimization.
- Breeders:Commercial kennel operations in Thailand's Central Plains and Vietnam's Mekong Delta require volume-discounted therapeutic nutrition with documented antibiotic-free supply chains.
- Pet Rescuers:Non-profit shelters prioritize cost-efficient bulk kibble procurement with basic nutritional adequacy.
- Veterinarians:Clinic owners source prescription diets through exclusive distribution agreements, capturing margin share from manufacturer rebates.
Revenue concentration: Pet Owners. Fastest-expanding procurement sophistication: Veterinarians.
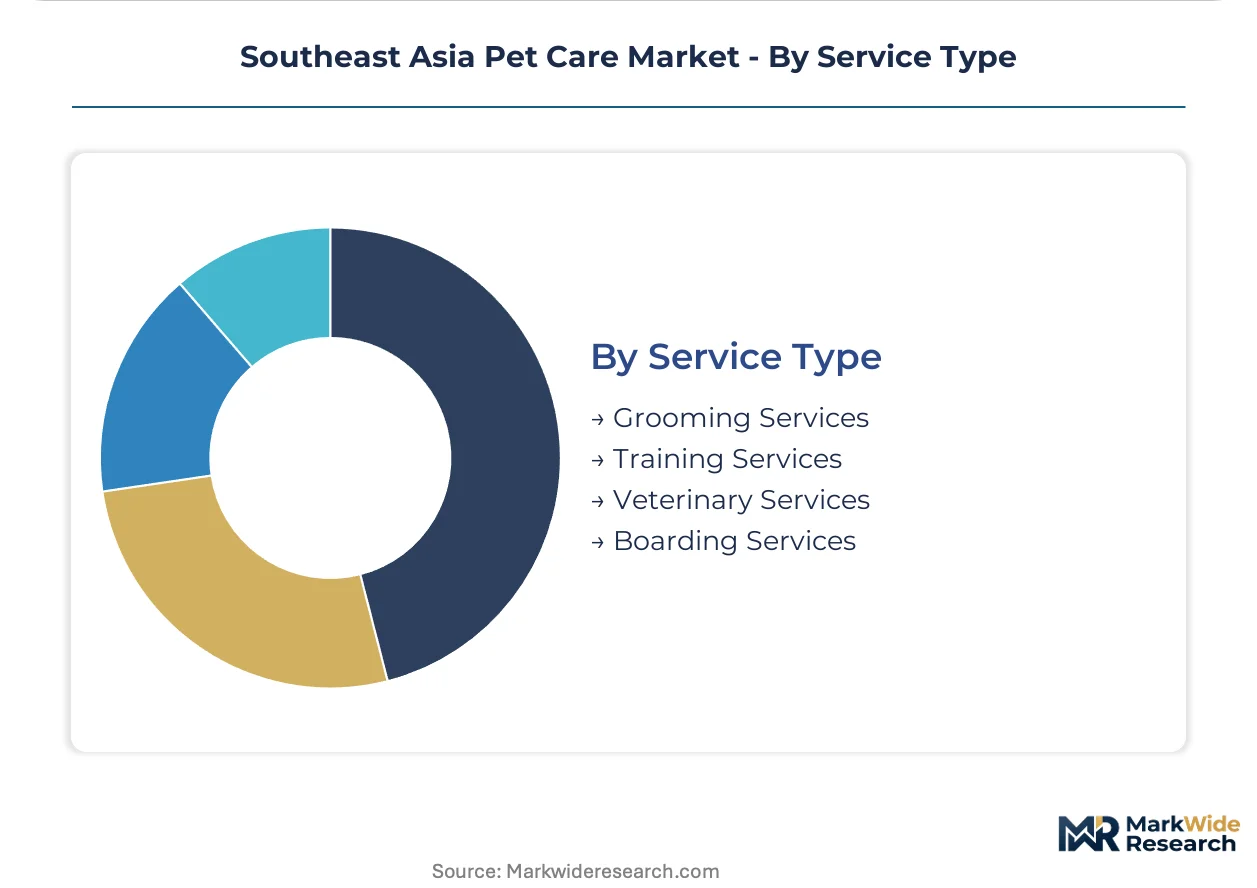
Service Type:
Service delivery intensity correlates with urban density and disposable income thresholds, with veterinary and grooming infrastructure clustering in metropolitan corridors.
- Grooming Services:Salon culture penetration in Indonesian and Vietnamese cities drives fastest segment expansion, with mobile van formats addressing Jakarta's traffic-constrained pet owners.
- Training Services:Obedience and behavioral modification concentrate in Bangkok and Singapore, where apartment-dwelling dog owners face breed restriction compliance pressures.
- Veterinary Services:Diagnostic and surgical capacity concentrates in Thailand's Bangkok metropolitan corridor, pulling adjacent provincial demand.
- Boarding Services:Premium pet hotel formats emerge in Ho Chi Minh City and Kuala Lumpur, targeting travel-frequency dual-income households.
Current revenue leader: Veterinary Services. Gaining share fastest: Grooming Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok's metropolitan corridor anchors regional pet care demand through veterinary service density and salon infrastructure that pulls adjacent provincial spending toward premium tiers.
Thailand
Urban millennials in Bangkok and Chiang Mai drive premium pet food migration, prioritizing humanization-aligned ingredient transparency. The country's FDA-equivalent enforces residual antibiotic screening in imported animal proteins through blockchain-traceable documentation requirements. Manufacturing clusters in Pathum Thani and Ayutthaya provinces host precision fermentation pilot facilities for allergen-free protein formulations.
Vietnam
Dual-income households in Hanoi and Ho Chi Minh City corridors accelerate subscription-based replenishment adoption, compressing customer acquisition costs for digital-native brands. The Ministry of Agriculture and Rural Development maintains import quarantine protocols that elevate compliance costs for foreign entrants. Mekong Delta commercial kennel operations demand volume-discounted therapeutic nutrition with documented antibiotic-free supply chains.
Indonesia
Surabaya and Bandung secondary cities remain underserved by premium grooming chains and specialized veterinary diagnostics, offering first-mover positioning for expansion-minded operators. General product safety standards govern pet accessories with lighter oversight than feed safety frameworks. Jakarta's traffic-constrained pet owners increasingly favor mobile van grooming formats over fixed-location salons.
Malaysia
The Department of Veterinary Services enforces prescription diet authorization requirements that restrict direct consumer access to therapeutic nutrition. Penang and Johor Bahru manufacturing zones process black soldier fly larvae for sustainable protein inputs that reduce fishmeal dependence. Kuala Lumpur's premium pet hotel formats target travel-frequency dual-income households with boarding service differentiation.
Singapore
Above-median disposable income households concentrate demand for premium freeze-dried and raw cat food segments, though cold chain infrastructure gaps limit re-export potential to provincial markets. The city-state's regulatory alignment with EU standards facilitates transshipment of Green Deal-compliant products to regional markets. Veterinary diagnostic capacity in the central region pulls cross-border demand from southern Malaysian pet owners.
Southeast Asia Pet Care Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance capabilities and cold chain infrastructure ownership. The vendor base stratifies into three tiers: multinationals with dedicated regulatory affairs teams, domestic producers with aquaculture byproduct integration, and regional distributors lacking formulation control. Strategic archetypes include vertically integrated nutrition manufacturers, veterinary channel gatekeepers, and digital-native subscription platforms. Dominant competitive moves encompass sustainable protein sourcing investments and telehealth-veterinary convergence partnerships.
Among Thailand-based integrated producers, Perfect Companion Group and Charoen Pokphand Group exemplify backward integration strategies through captive aquaculture byproduct supply. Mars Petcare occupies a position representing multinational scale advantages in preemptive EU Green Deal compliance across Thai manufacturing facilities. Nestlé Purina PetCare anchors the R&D-intensive tier through its Bangkok-based regional innovation hub. These three entities collectively represent divergent pathways to margin defense: vertical control, regulatory anticipation, and tropical climate localization.
| Leading Market Players |
|---|
| Perfect Companion Group |
| Charoen Pokphand Group |
| Mars Petcare |
| Tropical Canning Corp Sdn Bhd |
| Powerpets Food Sdn Bhd |
| Nestlé Purina PetCare |
| i-Tail Corporation |
| Betagro Pet Business |
| Hill's Pet Nutrition |
| Others |
Value Network & Pricing Analysis
Captive aquaculture byproduct sourcing among Thai integrated producers anchors both input cost predictability and premium-tier pricing power against spot-market-dependent competitors. This backward integration into fishmeal alternatives insulates margin structures from Peruvian anchovy quota volatility while enabling FEDIAF-compliant formulation premiums.
Pricing Analysis
Veterinary prescription authorization in Thailand and Malaysia anchors value-based pricing for therapeutic nutrition tiers. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-traceable antibiotic-free formulations from commodity kibble, with cold chain freshness commanding additional premiums. Cost compression in mid-tier dry kibble is intensifying because of platform commission rates and fishmeal spot volatility. Commercial kennel operations in Vietnam's Mekong Delta exhibit highest price sensitivity, while Bangkok metropolitan dual-income households show least elasticity for humanization-aligned products.
Supply Chain Analysis
Black soldier fly larvae supply rests on Malaysian and Thai cultivation facility investments, reducing historical dependence on Peruvian and Chilean fishmeal imports. Protein inputs draw from aquaculture byproduct streams, insect meal processing, and precision fermentation pilot outputs. Single-source vulnerability concentrates in EU-sourced specialty enzymes for palatability enhancement. Distribution runs through veterinary clinic gatekeepers for therapeutic tiers, with subscription platforms eroding traditional pet shop replenishment cycles in metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology is displacing conventional livestock protein sourcing, creating formulation differentiation that legacy fishmeal-dependent producers cannot match without capital-intensive facility retrofits.
For Market Incumbents: Deepen regulatory affairs capabilities to preempt ASEAN mutual recognition harmonization, securing first-mover formulation approvals across Thailand, Vietnam, and Malaysia. Lock in multi-year offtake agreements with black soldier fly larvae processors to substitute volatile fishmeal positions. Invest in cold chain infrastructure ownership before subscription-based fresh food competitors capture Bangkok and Ho Chi Minh City metropolitan demand.
For New Entrants and Emerging Players: EU Green Deal due diligence requirements in Europe open a window for Southeast Asian exporters with pre-certified sustainable protein supply chains to capture displaced market share from non-compliant competitors. Target Surabaya and Bandung grooming service gaps with mobile van formats that bypass Jakarta's fixed-location salon saturation. Enter through telehealth-veterinary convergence partnerships that bundle remote consultation with subscription nutrition deliveries, bypassing retail slotting fee barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational nutrition platforms seeking ASEAN manufacturing footholds and regulatory compliance capabilities. Five-to-ten year viability favors vertically integrated producers with captive aquaculture or insect protein supply, not pure-brand distributors. Watch for ASEAN pet food mutual recognition treaty ratification as the inflection signal that collapses compliance duplication costs and enables centralized regional manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Protein Sourcing Investment | Black soldier fly larvae cultivation reduces fishmeal dependence while meeting EU Green Deal due diligence requirements for export access. |
| Telehealth-Veterinary Platform Partnership | Remote consultation integration with subscription nutrition creates recurring revenue architectures that bypass traditional retail slotting fees. |
| Cold Chain Infrastructure Buildout | Temperature-controlled logistics ownership enables raw and fresh pet food penetration in Bangkok and Ho Chi Minh City metro corridors. |
| Regulatory Affairs Capability Expansion | Dedicated teams navigating Thailand's FDA-equivalent and Vietnam's import quarantine protocols accelerate multi-country market entry timelines. |
| ASEAN Harmonization Prepositioning | Centralized manufacturing readiness captures scale economies once mutual recognition protocols collapse national compliance duplication. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across veterinary clinic owners, pet food formulation scientists, aquaculture byproduct processors, regulatory affairs specialists at multinational manufacturers, and subscription platform operators. FEDIAF nutritional guidelines, Thailand FDA-equivalent feed registration databases, Vietnam Ministry of Agriculture import quarantine protocols, and Malaysian Department of Veterinary Services prescription authorization records provided compliance benchmarking. Bottom-up demand modeling across metropolitan corridors triangulated against top-down manufacturing capacity assessments.
Country-level granularity captured Thailand, Vietnam, Indonesia, Malaysia, and Singapore as distinct regulatory and demand environments, with product type segmentation spanning dry kibble, wet food, fresh formats, and grooming consumables. Distribution channel modeling separated veterinary clinic, online retail, supermarket, and independent pet shop economics. CAGRs derived from volume trajectory analysis across the projection horizon, incorporating pet humanization index correlations and disposable income elasticity coefficients specific to urban millennial demographic clusters.
Caveats apply where ASEAN mutual recognition treaty delays, fishmeal spot price spikes, or cold chain infrastructure gaps could materially shift the outlook. Forecasts reflect assumptions about regulatory stability and protein input substitution rates. A small set of named triggers—Peruvian anchovy quota revisions, EU Green Deal enforcement intensity, and ASEAN harmonization treaty ratification—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Organic Dog Food Market
Pet Care Products
UK Pet Grooming Market
Pet Care Products
Dog Clippers Market
Pet Care Products
Pet Collar Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
South Africa Pet Food Market
Pet Care Products
Pet Waste Removal Services Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Pet Hair Brush Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
Poland Pet Food Market