
 Europe Cat Food Market | 2026-2036
Europe Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cat Food Market Insights
Market Dynamics
Insect protein is recalibrating cost structures across mid-tier formulations as manufacturers offset volatile poultry and fish meal prices. Mars Petcare leverages its vertically integrated supply chain to secure alternative protein streams at scale. Nestlé Purina PetCare anchors its competitive stance through deep R&D investment in palatability science. Royal Canin dominates the veterinary-prescribed segment through clinic-exclusive distribution protocols.
Product and Segment Structure
Europe cat food encompasses nutritionally complete and complementary formulations manufactured to FEDIAF nutritional guidelines, with dry kibble typically containing 6-10% moisture and wet food ranging 75-85% moisture content to support feline hydration requirements. Wet food commands the premium margin pool as households trade up toward perceived freshness and urinary health benefits. Grain-free ingredient positioning differentiates mid-market entrants despite ongoing EFSA scrutiny of legume-heavy formulations. Online retail channels are capturing volume from supermarkets as subscription models reduce customer acquisition costs for direct-to-consumer specialists.
Regulatory Environment
The EU Green Deal and REACH framework mandate recycled content thresholds in pet food packaging, while EFSA oversight governs novel protein safety assessments and feed additive approvals. These regulations elevate compliance costs for smaller compounders while creating barrier advantages for scaled operators with dedicated regulatory affairs functions. Stakeholders must monitor FEDIAF guideline revisions and emerging national extended producer responsibility schemes as these will determine which packaging formats and protein sources remain commercially viable.
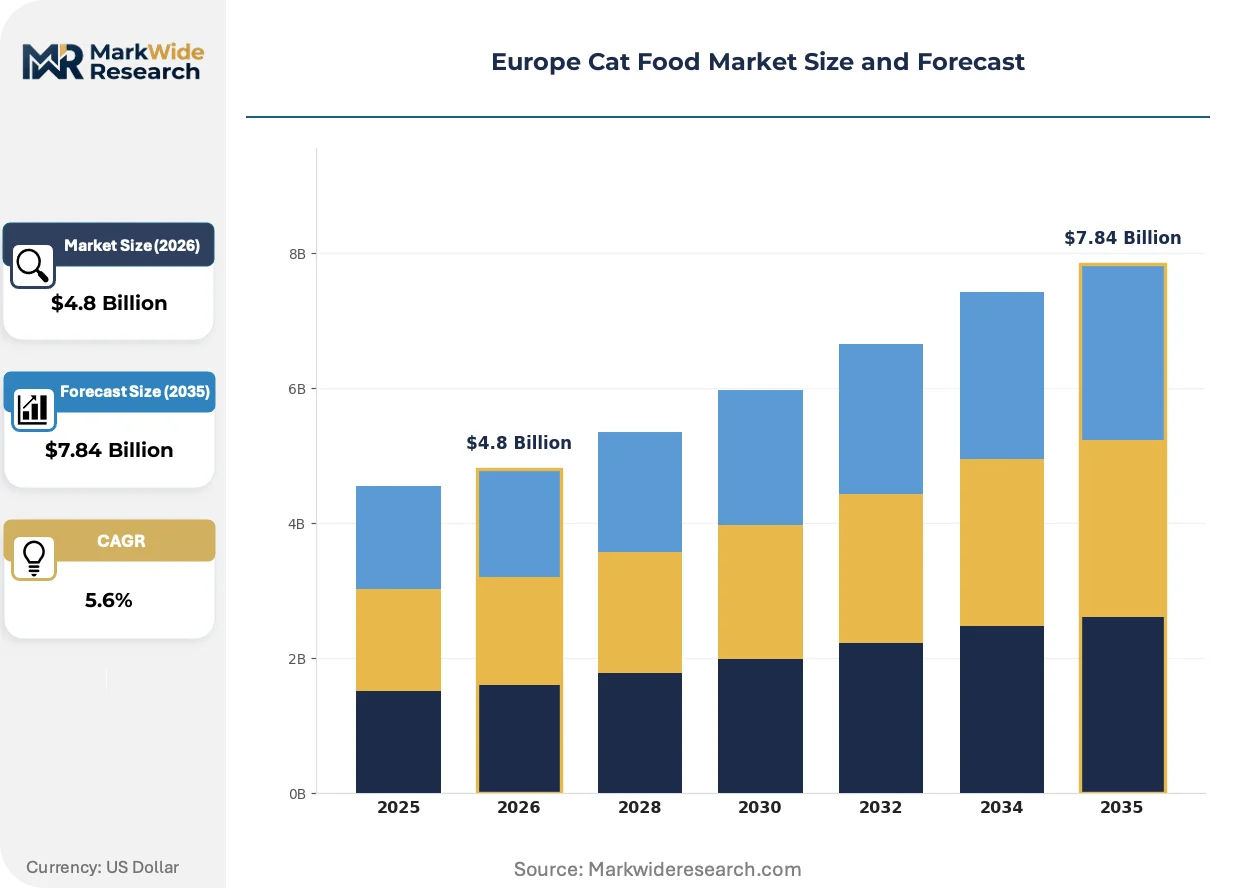
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing packaging formats while insect protein scale-up redraws raw material sourcing economics across mid-tier formulations.
Growth Catalysts
- REACH recycled content mandates:Packaging recyclability thresholds under EU chemicals law force format innovation, advantaging converters with thermoforming capabilities and rPET supply partnerships.
- Veterinary channel endorsement:Clinic-exclusive distribution protocols for therapeutic diets deepen household trust in prescription nutrition, locking in recurring purchase cycles through professional authority.
- Urban household density:Apartment-dwelling cat ownership rates in Paris, Berlin, and Milan concentrate demand for odor-controlled, portion-sized wet food formats with extended ambient stability.
Market Restraints
- Fish meal price volatility:Peruvian anchovy quota fluctuations and El Niño disruptions transmit directly into formulation costs, compressing margins for seafood-positioned brands without forward contracting discipline.
- EFSA novel protein approval timelines:Safety assessment protocols for insect and cultured protein sources extend 18-36 months, freezing commercial rollout for biotech entrants awaiting feed additive authorizations.
- Supermarket shelf space contraction:Discounter consolidation in Germany and France reduces facings for mid-market brands, forcing slotting fee inflation or delisting risk.
Strategic Opportunities
- Poland and Romania underpenetration:Specialist retail and veterinary network gaps in these markets create first-mover terrain for subscription-direct models with localized fulfillment infrastructure.
- Extended producer responsibility schemes:National packaging fee differentials in Italy and Spain reward lightweight, mono-material pouches over multi-layer laminates, favoring retortable polyethylene innovations.
- Digital-native subscription platforms:Algorithm-driven replenishment and tele-vet integration capture lifetime value from millennial adopters disintermediating traditional retail discovery.
Industry Challenges
- FEDIAF nutritional compliance expertise:Guideline revisions on carbohydrate thresholds and taurine bioavailability require reformulation cycles that strain R&D bandwidth at sub-scale compounders.
- Cold chain reconfiguration for fresh formats:Refrigerated last-mile logistics for raw and gently cooked products demand capex in temperature-controlled fulfillment that generalist distributors resist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cat Food Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Snacks Ingredient Type: Meat-Based, Fish-Based, Grain-Free, Vegetarian Distribution Channel: Online Retail, Supermarkets, Pet Specialty Stores, Wholesale Customer Type: Households, Breeders, Shelters, Veterinarians |
| Companies Covered | Mars Petcare, Nestlé Purina PetCare, Hill's Pet Nutrition, Royal Canin, Blue Buffalo, Affinity Petcare, United Petfood, Monge & C. S.p.A., Deuerer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cat Food Market Trends and Innovations
Protein source diversification and packaging chemistry innovation are converging to redefine cost structures and sustainability positioning across European cat food manufacturing.
Insect protein cultivation is consolidating as a viable poultry meal substitute, with black soldier fly larvae and yellow mealworm meals achieving amino acid profiles matching conventional inputs. Dutch and Belgian vertical farming operators are securing offtake agreements with mid-tier manufacturers seeking price hedges against volatile fish and poultry commodity cycles. This consolidation is compressing the cost gap between sustainable and conventional formulations, enabling mass-market positioning previously reserved for premium tiers.
The EU F-Gas Regulation and Packaging and Packaging Waste Directive are accelerating mono-material recyclable pouch development, banning perfluorinated compounds and mandating extended producer responsibility fee structures. Thermoformers and converters with rPET and polyethylene retort capabilities are capturing volume from multi-layer laminate incumbents facing redesign costs. Wet food producers with veterinary and specialist retail exposure are most affected, responding with lightweight, transparent barrier films that maintain shelf stability while meeting sorting infrastructure compatibility.
Subscription-direct purchasing is displacing supermarket stock-up behavior among urban households with single-cat or indoor-only profiles. Automated replenishment algorithms tied to consumption tracking apps reduce churn for digital-native specialists while eroding impulse purchase opportunities for brick-and-mortar retailers. This behavioral shift is most visible in UK and Nordic markets, where pet insurance integration and tele-vet diagnostics deepen platform stickiness beyond transactional commodity supply.
Europe Cat Food Market Segmentation
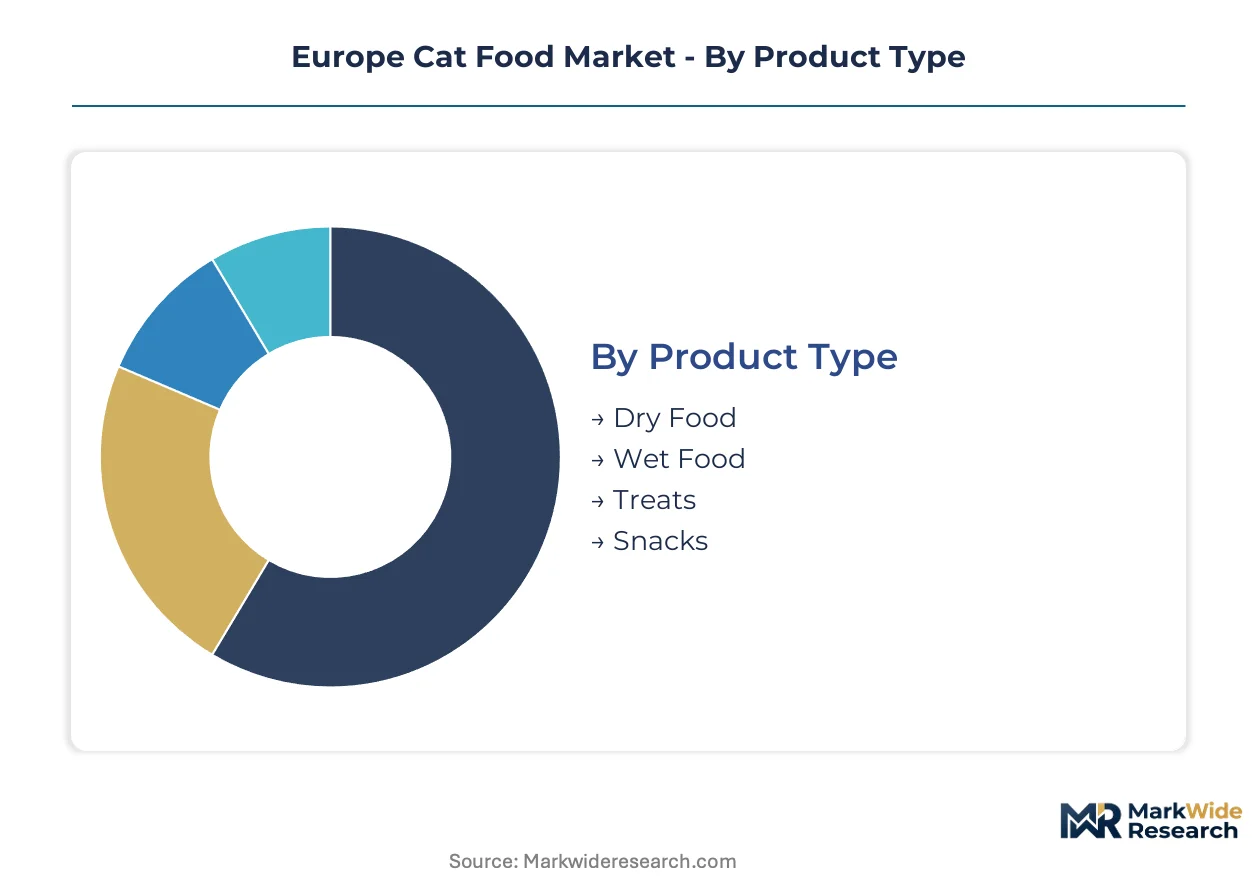
Segmentation in the Europe cat food market reveals how regulatory burdens, distribution economics, and protein sourcing strategies concentrate value across distinct customer and product configurations. Understanding these divides exposes where EFSA oversight, REACH compliance costs, and channel power reshape competitive viability.
Product Type:
EFSA nutritional completeness claims and FEDIAF guideline adherence requirements vary sharply across moisture formats, with wet food facing stricter retort processing validation and dry kibble subject to extended shelf-stability testing protocols.
- Dry Food:Kibble formulations with 6-10% moisture content rely on extrusion technology and lipid coating systems to deliver caloric density in shelf-stable formats. Demand concentrates in German and French suburban households with multi-cat portfolios where portion economics override freshness positioning, though EFSA scrutiny of carbohydrate thresholds and taurine bioavailability is forcing reformulation cycles that strain smaller compounders.
- Wet Food:Canned and pouch formats with 75-85% moisture content address feline hydration requirements through high-meat inclusion recipes. Paris, Berlin, and Milan apartment-dwelling owners drive demand for odor-controlled, portion-sized formats with extended ambient stability, while EU Green Deal packaging mandates and F-Gas Regulation compliance are compressing multi-layer laminate formats toward mono-material recyclable alternatives.
- Treats:Functional and indulgent reward formats with targeted nutrient dosing for dental or hairball management.
- Snacks:Air-dried or freeze-dried protein pieces positioned between meals with minimal processing claims.
Leading the category by volume: Dry Food. Growing fastest: Wet Food.
Ingredient Type:
Raw material cost volatility and novel protein approval timelines segment sourcing strategies between established commodity streams and emerging sustainable alternatives awaiting EFSA safety assessments.
- Meat-Based:Poultry, beef, and pork-derived formulations dominate complete nutrition portfolios with established supply chains. Breeders and veterinary channels in Italy and Spain anchor demand for specified-meat recipes with traceability documentation, though volatile poultry meal prices are driving mid-tier manufacturers toward black soldier fly larvae offtake agreements with Dutch vertical farming operators.
- Grain-Free:Legume and tuber-based carbohydrate substitutes positioned for digestive sensitivity claims. UK and Nordic households with indoor-only cats concentrate demand despite ongoing EFSA scrutiny of pulse-heavy formulations and potential dilated cardiomyopathy associations.
- Fish-Based:Peruvian anchovy and North Atlantic whitefish meals delivering omega-3 fatty acid profiles.
- Vegetarian:Plant-protein complete diets targeting ethical positioning with synthetic taurine supplementation.
Meat-Based captures the largest revenue pool. Grain-Free is climbing the fastest amid fresh-format subscription growth.
Distribution Channel:
Customer acquisition economics and last-mile infrastructure requirements stratify channel power between high-touch specialty networks and algorithm-driven direct platforms.
- Online Retail:Subscription-direct models with automated replenishment algorithms and tele-vet integration capture lifetime value from millennial adopters disintermediating traditional retail discovery. UK and Nordic markets show deepest penetration where pet insurance integration deepens platform stickiness beyond transactional supply.
- Pet Specialty Stores:Staff-assisted consultation environments with veterinary endorsement networks and therapeutic diet access. France and Germany concentrate specialist retail density, with clinic-exclusive distribution protocols for prescription nutrition locking in recurring purchase cycles through professional authority.
- Supermarkets:Mass-market stock-up behavior with impulse purchase dynamics and slotting fee economics.
- Wholesale:Volume supply to breeders, shelters, and multi-outlet veterinary chains with pallet-scale logistics.
Pet Specialty Stores lead by margin contribution. Online Retail is expanding most quickly as subscription models reduce customer acquisition costs.
Customer Type:
Volume concentration and nutritional specification intensity vary across ownership structures from individual household decision-making to institutional procurement with regulatory documentation requirements.
- Households:Individual owners making discretionary purchasing decisions across single-cat and multi-cat portfolios. Urban density in Paris, Berlin, and Milan drives premium wet food adoption with portion-controlled formats, while REACH recycled content mandates are reshaping packaging preferences toward transparent barrier films compatible with municipal sorting infrastructure.
- Veterinarians:Clinic-exclusive therapeutic diet dispensing with prescription protocols and recurring monitoring relationships. Royal Canin dominates this segment through FEDIAF-compliant formulation expertise and professional channel access that mid-market brands cannot replicate without dedicated regulatory affairs functions.
- Breeders:Volume purchasers with kitten development and reproductive nutrition specifications.
- Shelters:Cost-optimized complete nutrition procurement with bulk dry food preference and donation-dependent budgets.
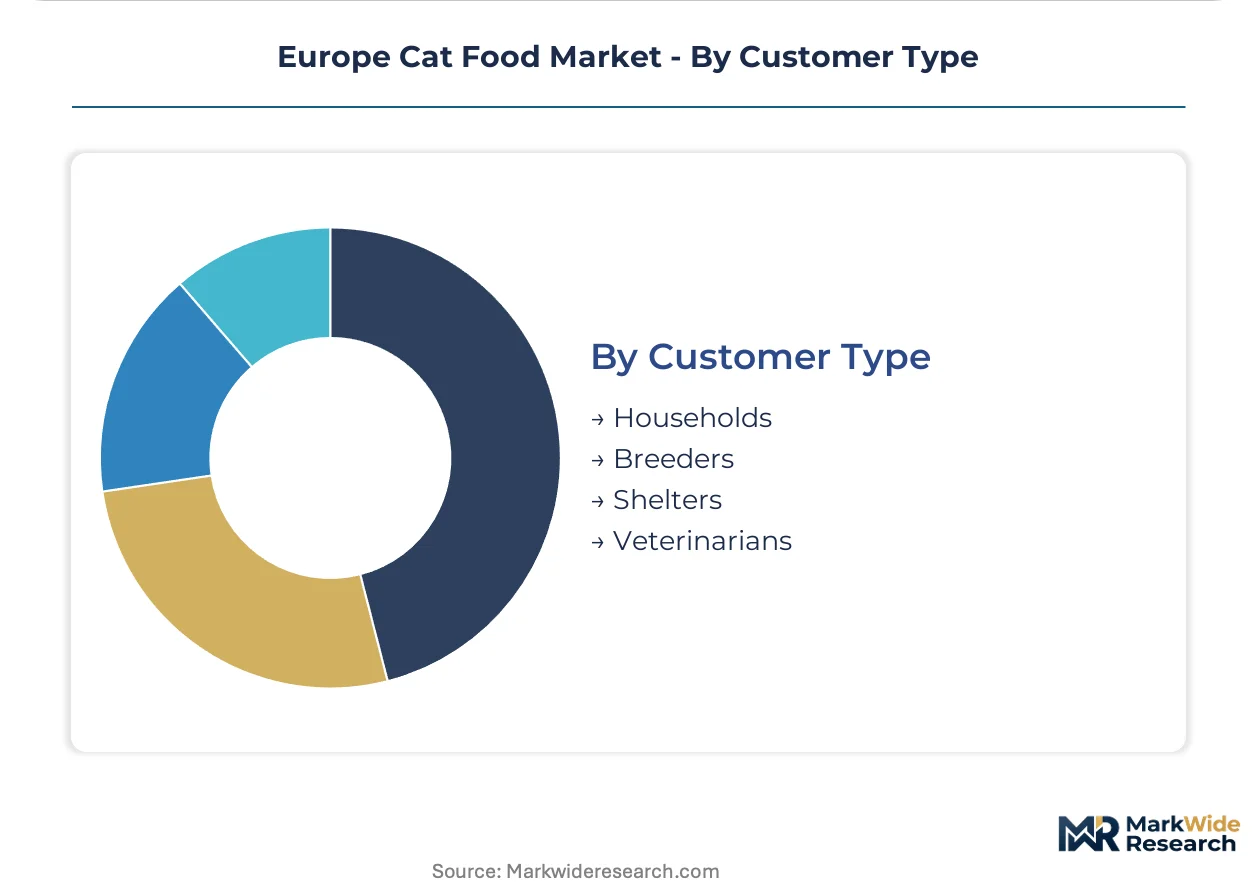
Households dominate absolute volume. Veterinarians command the highest per-kilogram pricing power through prescription authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban cat ownership density concentrates premium wet food demand across metropolitan France, Germany, and Italy, while Poland and Romania present underpenetrated terrain for direct-to-consumer subscription models.
Germany
Multi-cat suburban households in North Rhine-Westphalia and Bavaria drive dry kibble volume through portion economics and cost-conscious stock-up behavior. The EU Green Deal packaging mandates and national extended producer responsibility schemes force rapid format innovation toward mono-material recyclable pouches. Berlin's specialist retail density anchors clinic-exclusive therapeutic diet distribution, locking in recurring purchase cycles through veterinary authority.
France
Paris apartment-dwelling owners concentrate demand for odor-controlled, portion-sized wet food formats with extended ambient stability. REACH recycled content thresholds reshape packaging preferences toward transparent barrier films compatible with municipal sorting infrastructure. The Île-de-France region hosts dense veterinary endorsement networks that channel prescription nutrition through clinic-exclusive protocols.
Italy
Breeders and veterinary channels in Lombardy and Emilia-Romagna anchor demand for specified-meat recipes with traceability documentation. National packaging fee differentials reward lightweight, mono-material pouches over multi-layer laminates, favoring retortable polyethylene innovations. Milan's urban density accelerates premium wet food adoption among indoor-only cat households seeking perceived freshness benefits.
United Kingdom
Millennial adopters in Greater London and the Southeast disintermediate traditional retail discovery through algorithm-driven subscription platforms with tele-vet integration. EFSA scrutiny of grain-free legume-heavy formulations pressures reformulation cycles despite ongoing consumer preference for digestive sensitivity claims. Pet insurance integration deepens platform stickiness beyond transactional commodity supply in this market.
Poland
Specialist retail and veterinary network gaps in Warsaw and Kraków create first-mover terrain for subscription-direct models with localized fulfillment infrastructure. FEDIAF nutritional guideline revisions on carbohydrate thresholds strain R&D bandwidth at sub-scale compounders serving this emerging market. Dutch insect protein operators are securing offtake agreements with regional distributors seeking price hedges against volatile poultry commodity cycles.
Europe Cat Food Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational CPG conglomerates commanding veterinary and specialist retail channels while private-label compounders serve discounter and wholesale volumes. The market structure tiers across premium therapeutic positioning, mid-tier sustainable alternatives, and economy dry kibble procurement. Three archetypes dominate: vertically integrated nutrition science leaders, regional private-label manufacturers with thermoforming capabilities, and digital-native subscription specialists with captive fulfillment infrastructure. Competitive moves center on alternative protein supply security and mono-material packaging format patents.
Among the vertically integrated nutrition science leaders, Mars Petcare and Nestlé Purina PetCare exemplify archetypes with captive supply chain control and deep R&D investment in palatability science. Royal Canin occupies a distinct position within the veterinary-prescribed segment through clinic-exclusive distribution protocols that mid-market brands cannot replicate without dedicated regulatory affairs functions. These three entities anchor the competitive structure by representing scale-driven, science-backed, and channel-captive strategic positions respectively.
| Leading Market Players |
|---|
| Mars Petcare |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| Royal Canin |
| Blue Buffalo |
| Affinity Petcare |
| United Petfood |
| Monge & C. S.p.A. |
| Deuerer |
| Others |
Pricing and Supply Chain Analysis
Urban millennial adopters in UK and Nordic markets anchor demand for subscription-direct models, locking in three-tier pricing stratification across premium therapeutic, mid-tier sustainable, and economy dry kibble tiers. Their algorithm-driven replenishment behavior concentrates purchasing power with digital-native platforms that bypass traditional retail slotting economics.
Pricing Analysis
Volume-margin splits separate veterinary-exclusive therapeutic diets commanding per-kilogram premiums from mass-market dry kibble where portion economics dominate multi-cat households. Price differentiation rests on FEDIAF guideline compliance certification and veterinary endorsement authority. Cost compression in mid-tier formulations is intensifying as insect protein scale-up pressures conventional poultry meal positioning. Discounter-consolidated supermarket channels exhibit highest price sensitivity, while clinic-exclusive prescription nutrition maintains lowest elasticity through professional trust lock-in.
Supply Chain Analysis
Workforce availability constraints in Dutch and Belgian vertical farming clusters are accelerating automation investment for black soldier fly larvae cultivation. Raw material sourcing concentrates in the Netherlands, Belgium, and France for insect protein, with Peru and North Atlantic fisheries anchoring fish meal dependencies. Single-source vulnerability runs through Peruvian anchovy quota fluctuations transmitting directly into formulation costs. Distribution feeds from specialist retail and veterinary networks in France and Germany, with subscription-direct platforms capturing last-mile volume in UK and Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European cat food manufacturing is becoming a vertical-integration race where captive insect protein supply and mono-material packaging capabilities determine who captures margin from REACH compliance costs and EFSA approval timelines.
For Market Incumbents: Cement clinic-exclusive distribution protocols through deeper veterinary endorsement network penetration, defending against digital-native subscription platforms with tele-vet integration. Lock in black soldier fly larvae offtake agreements with Dutch and Belgian operators before mid-tier competitors secure scale pricing.
For New Entrants and Emerging Players: Launch via subscription-direct models with localized fulfillment infrastructure in Poland and Romania, where specialist retail and veterinary network gaps create first-mover terrain. Target urban single-cat households in Warsaw and Kraków with portion-controlled wet food formats and algorithm-driven replenishment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional private-label manufacturers with thermoforming capabilities and rPET supply partnerships in Italy and Spain, where national packaging fee differentials reward lightweight mono-material innovation. Watch EFSA novel protein approval timelines as the inflection signal for biotech entrant viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Insect Protein Supply Agreement | Secures price hedging against volatile Peruvian anchovy and poultry meal commodity cycles for mid-tier formulations. |
| Mono-Material Pouch Development | Meets EU Green Deal and F-Gas Regulation mandates while capturing extended producer responsibility fee advantages in Italy. |
| Veterinary Channel Expansion | Locks in recurring prescription nutrition purchase cycles through clinic-exclusive distribution protocols in France and Germany. |
| Subscription-Direct Platform Launch | Reduces customer acquisition costs through algorithm-driven replenishment and tele-vet integration in UK and Nordic markets. |
| Regional Fulfillment Infrastructure | Enables first-mover positioning in underpenetrated Poland and Romania markets with localized distribution networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across brand managers at multinational CPG conglomerates, category buyers at French and German specialist retailers, regulatory affairs leads at compounders navigating EFSA novel protein approvals, and supply planners at Dutch insect protein operators. FEDIAF nutritional guidelines, REACH compliance documentation, EFSA safety assessments, and EU Green Deal implementation reports provided secondary validation. Bottom-up volume builds across moisture formats and ingredient types reconciled with top-down value estimates from retail audit data.
Data-stream reconciliation combined historical trajectory analysis with forward projection modeling across the analysis window. Segmentation dimensions included product type, ingredient sourcing strategy, distribution channel economics, and customer procurement authority. CAGRs derived from trend extrapolation adjusted for regulatory inflection points and protein substitution elasticity. Insect protein scale-up curves and mono-material packaging adoption rates served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for cultured protein commercialization or biodegradable barrier films would alter the outlook. Forecasts reflect assumptions around EFSA approval timelines, REACH recycled content threshold enforcement, and urban household density trends. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Clothing Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Dog Shampoo Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
Pet Accessories Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Global Kennel Software Market
Pet Care Products
Cat Massage Comb Market
Pet Care Products
South America Dog Food Market
Pet Care Products
China Pet Food Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Dog Pen Market