
 Dog Litter Boxes Market | 2026-2036
Dog Litter Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Litter Boxes Market Insights
Enclosed-system and odor-control specification tiers is unwinding price competition at the low end of the dog litter box category. Omega Paw leverages its proprietary roll-and-clean mechanical design to sustain strong positioning in the traditional box segment without electronics. PetSafe anchors the mid-market with programmable self-cleaning units that appeal to working pet owners seeking automated waste management. Whisker differentiates through app-connected litter systems that extend its brand from feline into canine applications.
A dog litter box is a contained receptacle designed for indoor canine waste elimination, typically constructed from high-density polyethylene or polypropylene with antimicrobial additives, featuring raised sides to prevent spillage and removable trays for substrate replacement. Its primary commercial purpose is to enable urban and multi-story dwelling residents to maintain pet hygiene without outdoor access. Self-cleaning systems capture the largest margin pool due to motorization and sensor technology, while biodegradable material variants represent the fastest-growing structural segment as sustainability mandates intensify across European and North American retail channels. Traditional plastic boxes remain volume-dominant but face margin compression from commoditization and import competition.
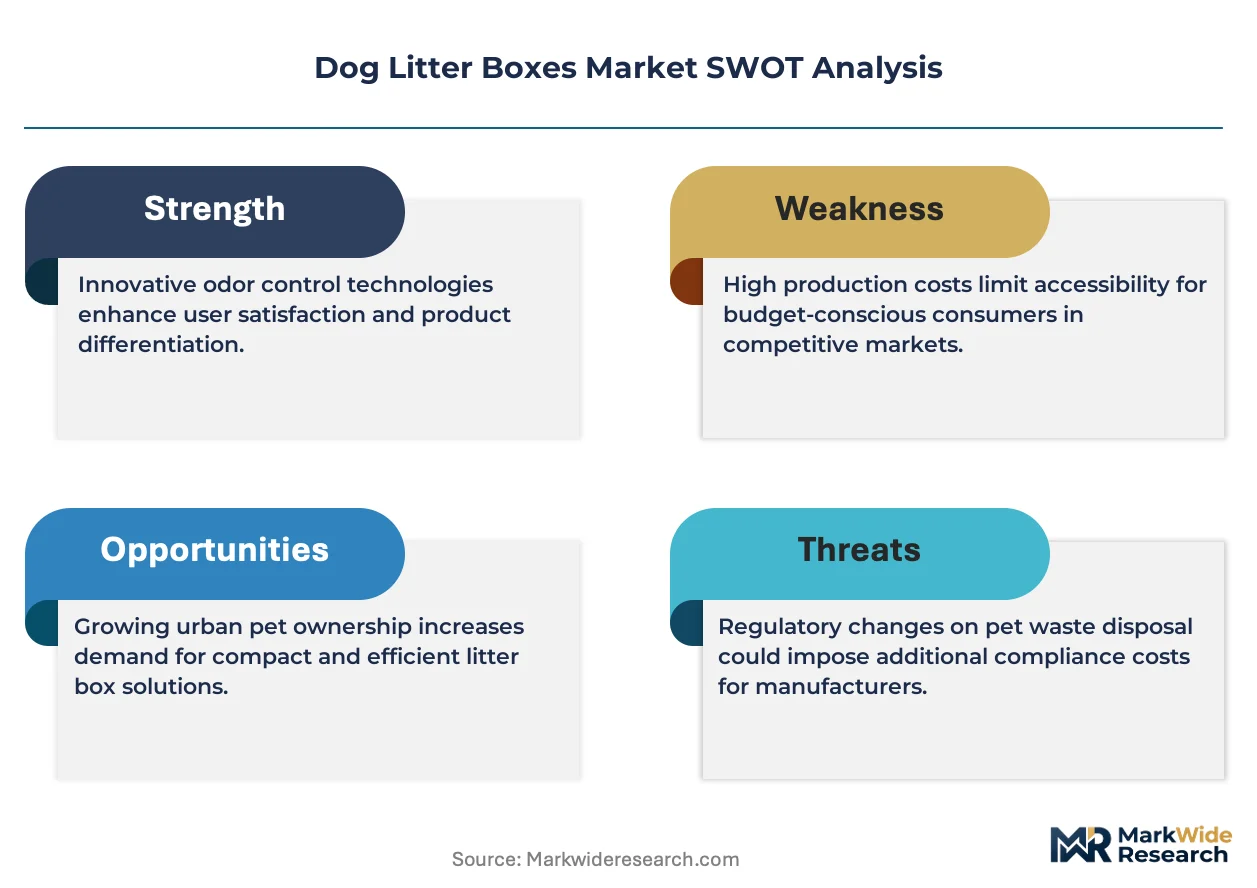
The United States EPA regulates pet waste disposal in multi-unit residential settings, while California's Proposition 65 imposes labeling requirements on plastic components with chemical additives. The European Union's REACH framework restricts phthalates and heavy metals in polymer formulations, directly shaping supplier qualification criteria for brands seeking CE-marked distribution. Stakeholders must monitor evolving state-level extended producer responsibility proposals and biodegradable certification standards to determine material sourcing strategies and geographic manufacturing placement.
Market Dynamics
Urban densification is compressing outdoor pet access across metropolitan cores, forcing manufacturers to engineer odor-sealed mechanical systems that satisfy apartment lease restrictions and municipal waste codes without balcony or yard dependency.
Growth Catalysts
- EPA Pet Waste Guidelines:United States multi-unit housing regulations now mandate contained disposal systems, accelerating landlord acceptance of indoor canine sanitation solutions.
- Biodegradable Substrates:Cornstarch and bamboo fiber formulations are displacing clay and silica in premium disposable trays as sustainability credentials influence millennial purchase decisions.
- Tokyo Metropolitan Density:Japan's vertical residential construction and shrinking household footprints create concentrated demand for space-efficient, stackable litter systems.
Market Restraints
- Polypropylene Price Volatility:Feedstock fluctuations in Gulf Coast petrochemical corridors compress margins on injection-molded traditional boxes.
- REACH Compliance Burden:ECHA's expanding restricted substance list forces reformulation of antimicrobial additives, extending European product launch timelines.
- Artificial Turf Substitution:Outdoor balcony patches with drainage systems capture price-sensitive urban buyers seeking lower total cost of ownership.
Strategic Opportunities
- Subscription Tray Services:Direct-to-consumer replenishment models bypass retail markup and capture recurring revenue from convenience-oriented pet owners.
- Senior Canine Mobility:Low-entry, orthopedic-accessible designs address the underpenetrated geriatric dog segment in aging Western populations.
- EU Green Deal Procurement:Public sector veterinary and shelter purchasing mandates favor cradle-to-cradle certified products, creating preferential channel access.
Industry Challenges
- Sensor Calibration Expertise:Self-cleaning motorization requires firmware engineers with pet behavior algorithm experience, a scarce talent pool concentrated in consumer robotics hubs.
- Interoperability Friction:Proprietary app ecosystems from rival manufacturers block unified smart home integration, frustrating tech-forward buyers seeking single-dashboard control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Litter Boxes Market |
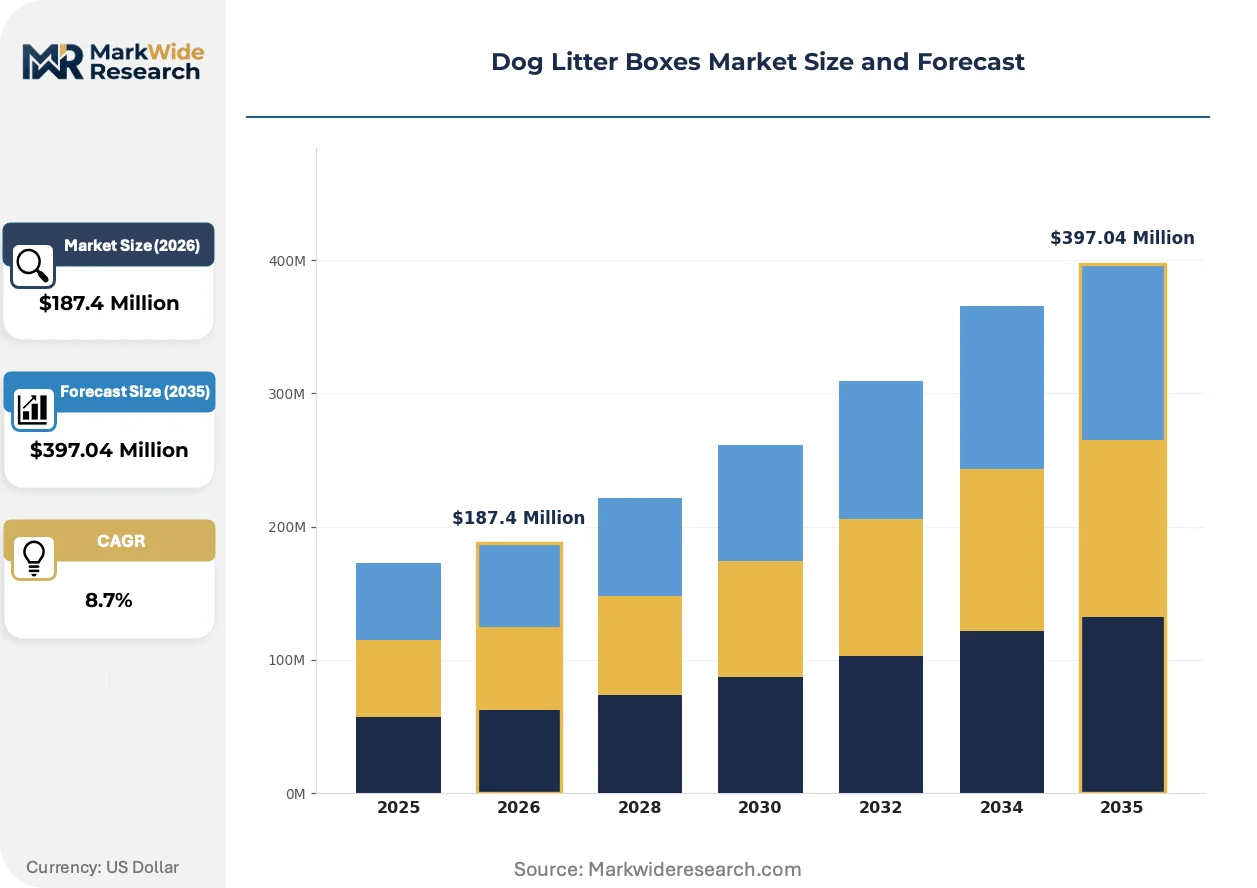
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Cleaning, Traditional Box, Disposable Tray, Enclosed Litter Box Material: Plastic, Metal, Wood, Biodegradable Feature: Odor Control, Non-Slip Base, Easy Clean, Eco-Friendly End User: Pet Owners, Dog Groomers, Veterinary Clinics, Pet Retailers |
| Companies Covered | Omega Paw, PetSafe, Whisker, Petkit, Church and Dwight, Spectrum Brands, Automated Pet Care Products, PetNovations, Our Pet's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Litter Boxes Market Trends and Innovations
Electromechanical waste separation is migrating from luxury tier to mass-market price points, while regulatory pressure on plastic additives accelerates material science investment. Subscription commerce and AI-powered odor prediction are converging to reshape ownership economics.
Ultraviolet-C LED sterilization modules are miniaturizing to fit within compact litter hoods without ventilation ducting. Urban apartment dwellers in Seoul and Singapore are adopting these units fastest, prioritizing pathogen reduction in humid climates. The technology is miniaturizing cost structures previously requiring hospital-grade equipment, compressing the premium tier's price floor.
California's Proposition 65 enforcement against phthalate-containing plastics is forcing reformulation of flexible litter box components. Manufacturers serving the United States market must now source alternative plasticizers or face labeling penalties that degrade shelf appeal. The regulation is accelerating migration to bio-based polymers in West Coast distribution channels first.
Millennial and Gen Z pet owners are unbundling after-sales service from hardware purchase, rejecting extended warranties in favor of pay-per-use repair networks. Independent mobile technicians in New York and Los Angeles now offer same-day motor replacement for self-cleaning units. This behavior is most visible in coastal United States metros where gig-economy service density supports on-demand maintenance.
Dog Litter Boxes Market Segmentation
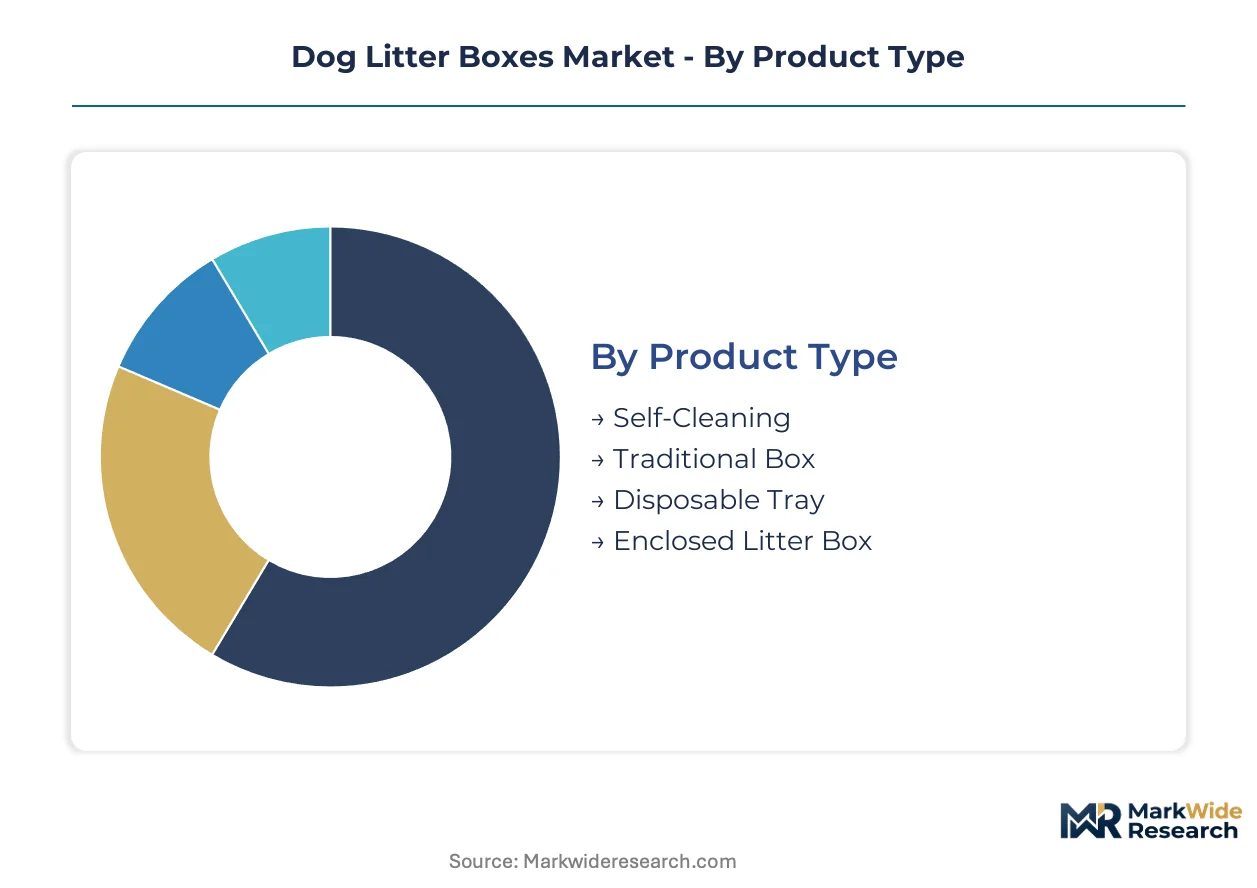
Dog litter box manufacturers face divergent substitution threats across product architectures, with balcony turf patches and outdoor walking services eroding low-technology segments while automation defends premium tiers. Material selection and feature bundling determine margin sustainability as regulatory pressure intensifies on polymer formulations.
Product Type:
Artificial turf balcony systems and on-demand dog walking apps exert the strongest substitution pressure on passive containment designs, forcing mechanical differentiation to justify indoor hardware investment.
- Self-Cleaning:Motorized raking or conveyor systems with infrared waste detection and sealed waste compartments command the highest price tier. Demand concentrates in Tokyo, Seoul, and New York metropolitan districts where apartment lease restrictions prohibit balcony installations and dual-income households prioritize automation over manual maintenance.
- Traditional Box:Static polyethylene or polypropylene containers with raised sides and removable trays face acute price compression from import competition and turf substitution. Volume remains dominant in secondary United States cities and European provincial markets where outdoor access persists but weather intermittency drives supplemental indoor use.
- Disposable Tray:Pre-filled substrate cartridges with collapsible frames target travel and temporary housing scenarios. Airlines and extended-stay hotel chains in Japan represent concentrated procurement channels.
- Enclosed Litter Box:Hooded designs with carbon-filtered ventilation ports address odor-sensitive multi-unit dwellings. German and Dutch housing associations specify these units in pet-friendly lease addenda.
Traditional Box anchors the volume base while Self-Cleaning gains share at the steepest rate.
Material:
Cost tier stratification separates commodity polymer supply from certified bio-based alternatives, with regulatory compliance costs widening the price spread between virgin plastic and sustainable formulations.
- Plastic:High-density polyethylene and polypropylene dominate injection-molded production, with antimicrobial additive packages now mandatory for United States retail placement. California Proposition 65 enforcement against phthalate plasticizers accelerates reformulation costs for West Coast distribution.
- Biodegradable:Cornstarch, bamboo fiber, and mycelium-based composites satisfy EU Green Deal procurement criteria and millennial sustainability preferences. European shelter and veterinary institutional buyers in France, Germany, and the Netherlands mandate cradle-to-cradle certification.
- Metal:Powder-coated stainless steel variants target veterinary and grooming professional segments requiring sterilization compatibility. Premium positioning in Japanese and South Korean commercial channels.
- Wood:Sealed bamboo or reclaimed timber constructions appeal to design-conscious residential buyers in Scandinavian and Pacific Northwest markets. Moisture resistance limitations constrain mass-market penetration.
Plastic commands the installed base while Biodegradable climbs the fastest amid regulatory tailwinds.
Feature:
Application context determines feature prioritization, with urban apartment dwellers weighting odor containment above all other attributes while commercial users emphasize durability and sanitization.
- Odor Control:Activated carbon filters, zeolite crystals, and enzymatic spray integration represent the primary purchase determinant for high-density housing residents. Singapore and Hong Kong buyers demonstrate willingness-to-pay premiums exceeding other feature categories.
- Eco-Friendly:Recycled content certification and end-of-life compostability align with corporate sustainability mandates and consumer value signaling. European retail buyers increasingly require environmental product declarations.
- Easy Clean:Smooth interior surfaces, rounded corners, and dishwasher-safe tray components reduce maintenance friction for elderly and mobility-limited pet owners. Aging Western populations drive specification in this attribute.
- Non-Slip Base:Rubberized feet and weighted bottom panels prevent displacement on hard flooring surfaces. Standard inclusion in mid-tier and above across all major markets.
Odor Control defends the decision hierarchy while Eco-Friendly attributes expand most quickly in channel requirements.
End User:
Customer type segmentation reveals divergent procurement patterns, with individual pet owners driving unit volume and institutional buyers determining specification standards that cascade to consumer tiers.
- Pet Owners:Individual residential buyers purchasing through retail, direct-to-consumer, or veterinary recommendation channels. Millennial and Gen Z cohorts in United States coastal metros demonstrate highest subscription service attachment rates.
- Veterinary Clinics:Professional sourcing of hospital-grade, sterilizable units for post-surgical and boarding applications. Influential in breed-specific recommendations that shape consumer purchase decisions.
- Pet Retailers:Curated assortment buyers balancing inventory turns against margin preservation. Independent specialty stores in Germany and Japan maintain stronger influence over premium tier placement than mass merchants.
- Dog Groomers:Commercial durability requirements with high-frequency sanitization protocols. Concentrated demand in South Korean and Australian urban service corridors.
Pet Owners generate the volume foundation while Veterinary Clinics establish the specification benchmarks that shape upstream product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injection-molding capacity clusters along the Gulf Coast petrochemical corridor and in Guangdong province shape global supply availability for polyethylene and polypropylene components. Distribution networks radiate from these hubs to serve dense metropolitan demand centers where apartment dwelling restricts outdoor pet access.
United States
Millennial and Gen Z pet owners in New York and Los Angeles drive subscription-based disposable tray adoption. EPA pet waste guidelines for multi-unit housing accelerate landlord acceptance of contained indoor systems. California's Proposition 65 enforcement against phthalate plasticizers forces reformulation of flexible components for West Coast distribution channels.
Japan
Vertical residential construction in Tokyo and shrinking household footprints concentrate demand for space-efficient, stackable litter systems. METI guidelines on household waste separation influence product design for municipal collection compatibility. Osaka-based retailers curate premium automated units for dual-income apartment dwellers seeking maintenance-free solutions.
Germany
EU Green Deal procurement mandates at veterinary and shelter institutions favor cradle-to-cradle certified biodegradable products. ECHA's REACH framework restricts phthalates and heavy metals in polymer formulations, extending product launch timelines. The Rhine-Ruhr industrial corridor hosts compounders supplying bio-based alternatives to domestic manufacturers.
South Korea
Seoul's high-rise density and humid climate accelerate adoption of UV-C sterilization modules for pathogen control. MFDS guidelines on antimicrobial claims shape marketing claims for treated plastic surfaces. Busan-Ulsan petrochemical complexes supply specialized polymer grades to domestic molding operations serving the premium segment.
Netherlands
Dutch housing associations specify enclosed, carbon-filtered units in pet-friendly lease addenda for Amsterdam and Rotterdam multi-unit stock. EU circular economy directives drive demand for compostable tray liners in municipal procurement. The Randstad logistics hub enables rapid replenishment cycles for direct-to-consumer subscription services.
Dog Litter Boxes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with automated system specialists commanding premium positioning while commodity molders defend volume tiers. The vendor base separates into three strategic camps: electromechanical innovators with firmware capabilities, traditional plastics processors with scale economics, and biodegradable material specialists with sustainability credentials. Dominant competitive moves include portfolio diversification into subscription services and strategic partnerships with petrochemical compounders for compliant material sourcing.
Within the electromechanical tier, Omega Paw and PetSafe exemplify divergent approaches to automation—one leveraging proprietary mechanical design without electronics, the other anchoring programmable self-cleaning functionality. Whisker occupies a position spanning both premium automation and smart home connectivity, extending brand equity from adjacent pet care categories. These three players collectively represent the competitive frontier where sensor calibration expertise and app ecosystem development determine margin capture.
| Leading Market Players |
|---|
| Omega Paw |
| PetSafe |
| Whisker |
| Petkit |
| Church and Dwight |
| Spectrum Brands |
| Automated Pet Care Products |
| PetNovations |
| Our Pet's |
| Others |
Pricing and Supply Chain Analysis
Ninety-day injection-molding tool lead times from Guangdong province tether pricing power to resin availability and port clearance velocity, compressing margins on traditional boxes while electromechanical tiers capture premium markups through firmware scarcity.
Pricing Analysis
EPA pet waste guidelines dictate the pricing tier structure across the United States multi-unit housing channel, separating self-cleaning motorized systems from passive containment on certification compliance rather than feature count alone. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensor sophistication, antimicrobial additive packages, and subscription service bundling. Cost compression in traditional polyethylene boxes intensifies because import competition from Southeast Asian molders erodes domestic manufacturer margins. Price-sensitive secondary city buyers in the United States interior favor economy passive boxes, while least-sensitive Tokyo and Seoul apartment dwellers absorb premiums for UV-C sterilization and app connectivity.
Supply Chain Analysis
Container availability on the Shanghai–Los Angeles trade lane determines inbound cost volatility for antimicrobial additive packages and motorization components sourced from East Asian electronics corridors. Manufacturing concentrates in China, South Korea, and the United States Gulf Coast, with Guangdong injection molders feeding commodity box volume and Busan-Ulsan petrochemical complexes supplying specialized polymer grades for premium segments. Raw material dependencies center on polypropylene resin, high-density polyethylene, and cornstarch biopolymer feedstocks. Single-source vulnerability in precision sensor modules creates chokepoint exposure for electromechanical tier producers. Distribution runs through Amazon–Chewy direct-to-consumer platforms and Petco–PetSmart retail networks, with veterinary clinic channels commanding higher service attach rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription commerce and AI-powered odor prediction are converging to reshape ownership economics, with regulatory pressure on plastic additives accelerating material science investment as the defining inflection.
For Market Incumbents: Fortify firmware development capabilities through captive engineering hires in Seoul and Shenzhen robotics hubs, defending against Whisker and Petkit's app ecosystem expansion. Secure backward integration into bio-based polymer compounding to offset REACH reformulation costs and California Proposition 65 labeling penalties that degrade West Coast shelf appeal. For New Entrants and Emerging Players: Differentiate on geriatric canine accessibility designs targeting aging Western populations, where low-entry orthopedic specifications remain underpenetrated. Penetrate EU veterinary and shelter procurement channels through cradle-to-cradle certification, leveraging Green Deal mandates as a go-to-market wedge against incumbent plastic-dependent portfolios. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified petrochemical conglomerates with non-core consumer polymer divisions lacking sustainability credentials. Long-term viability hinges on subscription recurring revenue attachment and bio-based material transition completion. Watch biodegradable certification standard harmonization between EU and North American retail channels as the signal for accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Tray Service Launch | Direct-to-consumer replenishment bypasses retail markup and captures recurring revenue from millennial pet owners. |
| Bio-Based Polymer Backward Integration | In-house compounding of cornstarch and bamboo fiber formulations secures REACH compliance and Green Deal procurement access. |
| UV-C Sterilization Module Miniaturization | Compact pathogen control units penetrate Seoul and Singapore humid-climate apartments without ventilation infrastructure. |
| Senior Canine Accessibility Line Extension | Low-entry orthopedic designs address underpenetrated geriatric segment in aging Japan and Western Europe populations. |
| Smart Home Platform Integration Partnership | API unification with Amazon Alexa and Google Home reduces interoperability friction frustrating tech-forward buyers. |
Research Methodology
Operator-level perspectives from injection-molding plant managers, petrochemical procurement leads at downstream OEMs, veterinary clinic purchasing committees, and direct-to-consumer channel sales heads anchored the qualitative base. Primary interview insights combined with customs records, EPA enforcement disclosures, ECHA restricted substance notifications, and SEC 10-K segment disclosures for diversified pet care conglomerates. Bottom-up unit economics triangulated against top-down retail audit data from Nielsen and Circana.
Sensitivity analysis tested forecast robustness across polypropylene price volatility scenarios and biodegradable substrate adoption curves throughout the projection horizon. Segmentation dimensions modeled include product architecture, material certification tier, feature bundling, and end-user procurement channel. CAGRs derived from regression against urban densification indices and pet ownership penetration rates, with sensor cost decline curves and regulatory timeline assumptions as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained EPA guideline enforcement or accelerated EU Green Deal procurement expansion would require recalibration. Forecasts reflect documented assumptions on resin price stabilization and biodegradable certification harmonization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Robotic Pets Market
Pet Care Products
Pet Oral Care Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
United Kingdom Cat Litter Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Inflatable Pet Collars Market
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
Pet Grooming Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Dog Harness Market
Pet Care Products
Pet GPS Tracker Market
Pet Care Products
Italy Pet Food Market
Pet Care Products
Pet Lodging Market
Pet Care Products
UAE Dog Food Market