
 Pet Jerky Treat Market | 2026-2036
Pet Jerky Treat Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Jerky Treat Market Analytics
Multi-source protein procurement is recalibrating how manufacturers secure raw materials for jerky production. Nestlé Purina PetCare leverages vertically integrated supply chains to control chicken and beef sourcing quality from farm to finished treat. Mars Petcare anchors its position through global manufacturing scale that spans multiple protein species and regional taste preferences. Blue Buffalo differentiates via grain-free formulations that command shelf space in premium retail channels.
Pet jerky treats are dehydrated meat strips, typically dried at temperatures between 140°F and 180°F to achieve moisture content below 20 percent, preserving protein integrity while inhibiting microbial growth. These products serve as high-value training incentives and nutritional supplements in companion animal diets. Chicken jerky retains the largest revenue share due to lower raw material costs and broad palatability across dog breeds, while grain-free ingredient positioning captures the fastest-growing consumer segment as pet owners avoid corn, wheat, and soy fillers. Online retail distribution is expanding fastest among channels, though specialty pet shops still command the highest margin pools through personalized merchandising and veterinary endorsement.
The FDA enforces strict pathogen standards under the Food Safety Modernization Act's preventive controls for animal food, requiring hazard analysis and supply chain verification from jerky manufacturers. The USDA inspects meat processing facilities that supply raw materials, while state agriculture departments conduct additional label and ingredient audits. AAFCO nutrient profiles further constrain formulation choices by defining complete and balanced standards. Stakeholders must monitor evolving state-level raw feeding restrictions and traceability mandates that could reshape supplier qualification requirements.
Market Dynamics
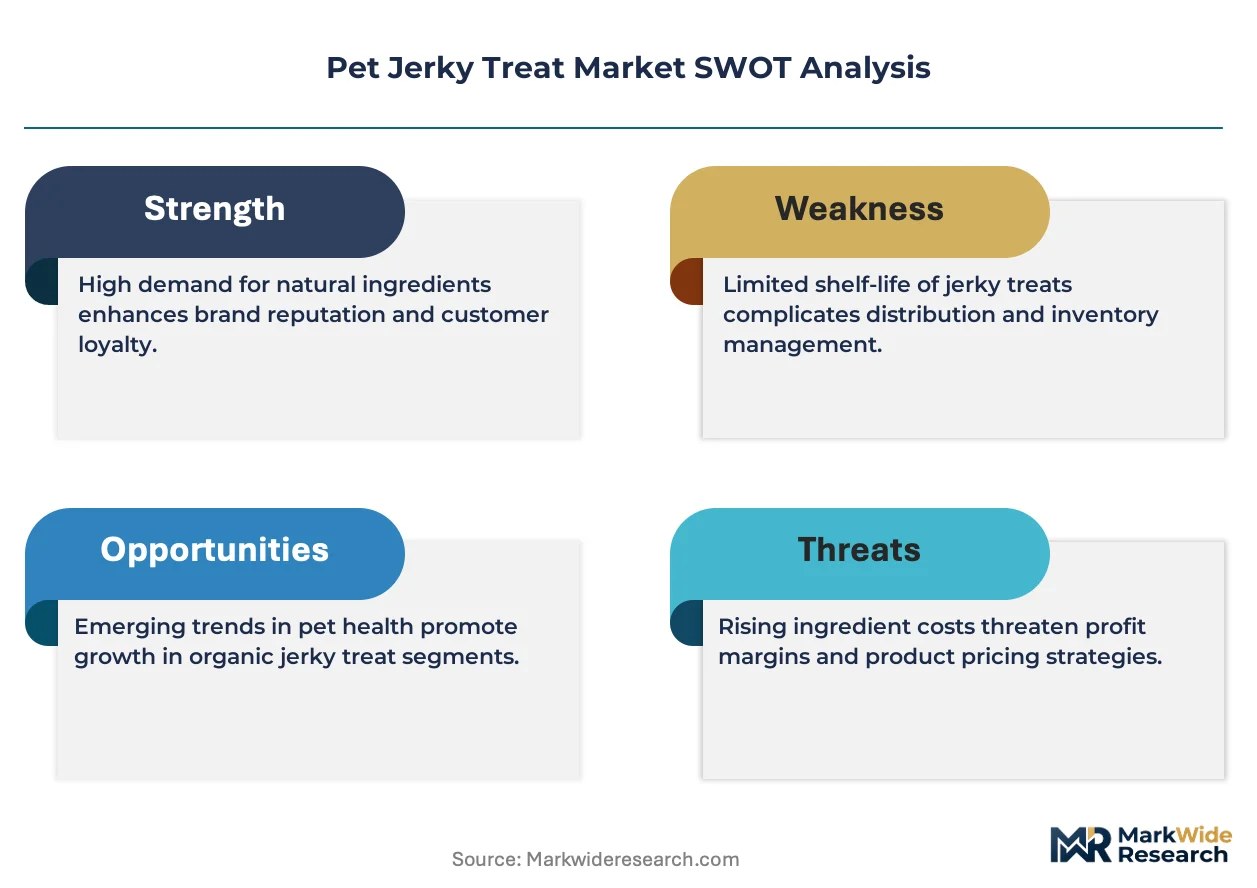
Millennial pet ownership patterns are compressing product development cycles as manufacturers race to match human-grade ingredient expectations with shelf-stable formats. The FDA's Food Safety Modernization Act preventive controls mandate hazard analysis protocols that smaller producers struggle to implement without capital restructuring.
Growth Catalysts
- FSMA Preventive Controls:The FDA's mandatory hazard analysis and risk-based preventive controls for animal food create compliance barriers that favor scaled manufacturers with dedicated food safety teams.
- E-commerce channel expansion:Online retail penetration accelerates category access for specialty and grain-free formulations previously confined to premium pet retail chains.
- Humanization of pet diets:Pet owners increasingly apply clean-label and limited-ingredient standards from their own food choices to companion animal nutrition.
Market Restraints
- Protein input cost volatility:Chicken and beef commodity price swings directly compress margins for single-protein jerky lines without hedging mechanisms.
- Supply concentration risk:Domestic sourcing of human-grade meat raw materials concentrates in Midwestern USDA-inspected facilities vulnerable to regional disease outbreaks.
- Moisture specification technical limits:Dehydration temperatures above 180°F degrade protein digestibility while sub-140°F processing risks incomplete pathogen reduction.
Strategic Opportunities
- Novel protein expansion:Duck, rabbit, and venison jerky formats address allergy-sensitive dog populations underserved by chicken-dominant assortments.
- Veterinary endorsement channel:Clinic-based dispensing of therapeutic jerky treats creates prescriptive positioning distinct from mass retail.
- Subscription direct-to-consumer models:Auto-replenishment platforms capture recurring revenue while bypassing slotting fee structures of specialty pet retail.
Industry Challenges
- Food safety certification timelines:Third-party audit requirements for Safe Quality Food (SQF) or BRCGS certification delay new facility commissioning by 12-18 months.
- Legacy equipment retrofit costs:Metal detection and X-ray inspection system upgrades to meet foreign object control standards strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Jerky Treat Market |
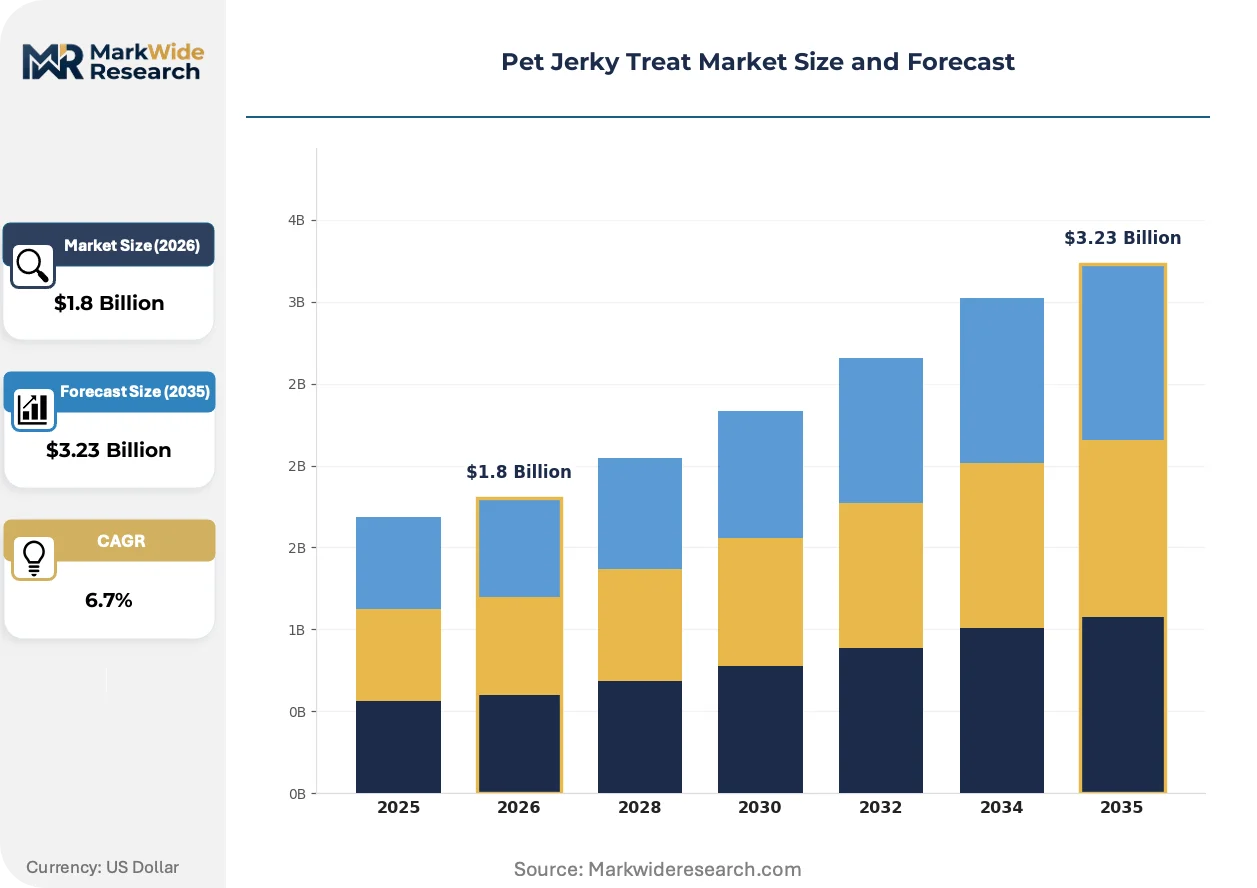
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken Jerky, Beef Jerky, Pork Jerky, Turkey Jerky Ingredient Type: Natural, Organic, Grain-Free, Gluten-Free Packaging Type: Pouches, Tubs, Boxes, Ziplock Bags Distribution Channel: Online Retail, Supermarkets, Pet Stores, Specialty Shops |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare, Blue Buffalo, Spectrum Brands, Hill's Pet Nutrition, Wellness Pet, Zuke's, Plato Pet Treats, Wholesome Pride, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Jerky Treat Market Evolving Landscape
Dehydration technology advances and regulatory digitization are compressing traditional manufacturing timelines while reshaping how quality assurance integrates with production workflows.
Low-temperature air-drying systems operating below 160°F are unifying pathogen reduction with nutrient retention in ways conventional oven dehydration cannot match. Premium manufacturers deploy these systems to produce jerky qualifying for raw or minimally processed positioning without frozen distribution requirements. The technology is unifying previously separate product categories—shelf-stable and refrigerated—into single manufacturing footprints.
The FDA's Food Safety Modernization Act mandates supply chain verification records that trace ingredients from farm to finished treat. Domestic manufacturers must document supplier approval processes, foreign supplier verification, and corrective action protocols in electronic formats accessible to inspectors. Small and mid-sized producers face disproportionate documentation burdens relative to their revenue bases.
Subscription-based replenishment is displacing episodic retail purchasing among urban millennial pet owners. Chewy and Amazon's Subscribe & Save programs capture recurring jerky orders previously routed through Petco or independent pet boutiques. California and New York metropolitan areas exhibit the highest subscription penetration, with grain-free and limited-ingredient SKUs overrepresented in auto-ship assortments.
Pet Jerky Treat Market Segmentation
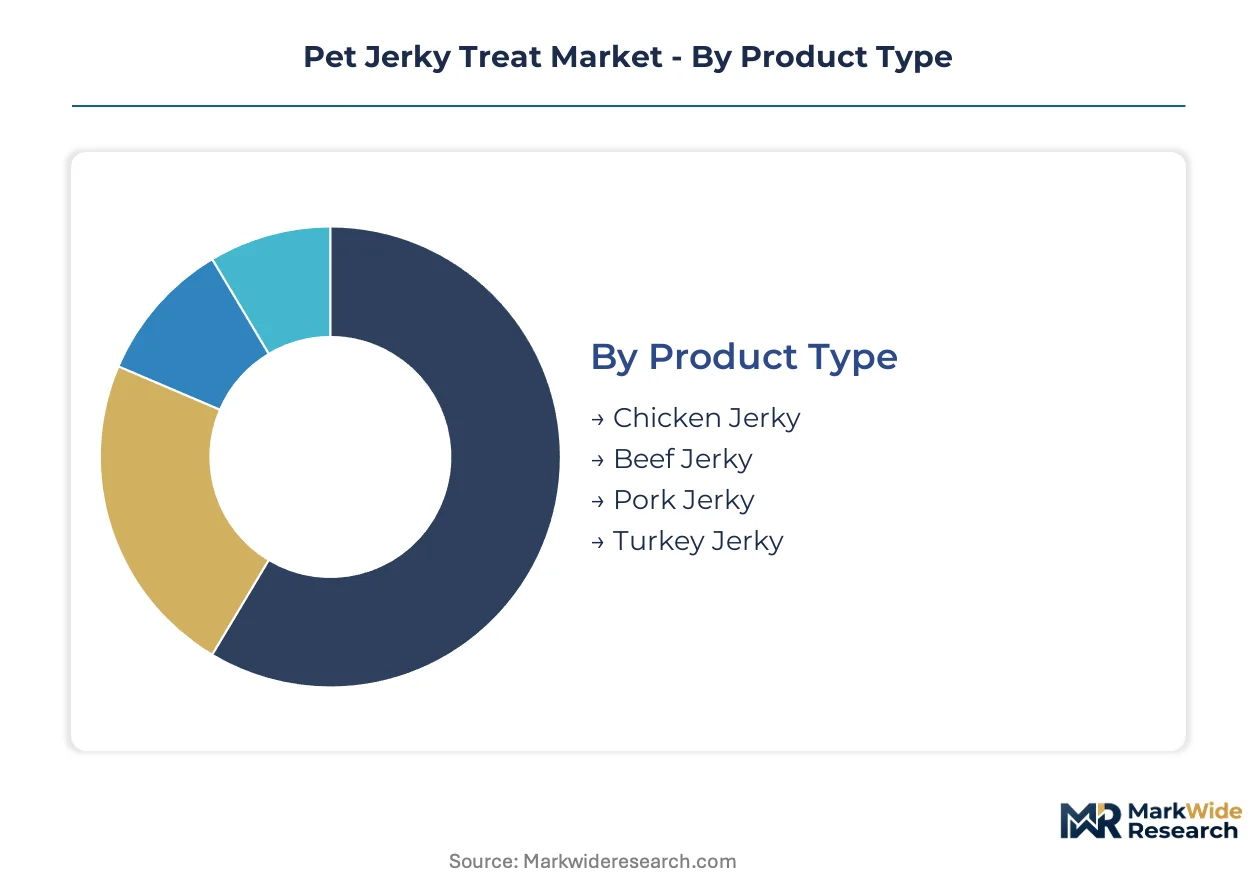
Pet jerky treat segmentation reveals how protein sourcing, ingredient positioning, and channel access stratify purchasing decisions across owner demographics. Manufacturers align formulation and packaging investments with distinct buyer willingness-to-pay thresholds.
Product Type:
Protein species selection drives raw material cost structures and palatability profiles that shape manufacturer portfolio priorities.
- Chicken Jerky:Dehydrated poultry strips processed at 140°F to 180°F retain amino acid integrity while achieving sub-20% moisture content for shelf stability. Midwestern USDA-inspected facilities supply the bulk of raw material, with volume concentrating in mass retail channels serving price-sensitive multi-dog households.
- Beef Jerky:Bovine muscle strips command premium positioning through higher protein density and longer chewing duration that satisfies large-breed dogs. Demand clusters in specialty pet retail and veterinary clinic dispensing, where owners prioritize dental benefits and satiety over per-ounce cost.
- Pork Jerky:Lean pork loin strips offer intermediate pricing between chicken and beef with distinct flavor profiles for rotational feeding protocols.
- Turkey Jerky:Lower-fat poultry alternative targets weight-management formulations and allergy-sensitive dogs requiring novel protein rotation.
Volume sits with Chicken Jerky; growth tilts toward Turkey Jerky.
Ingredient Type:
Clean-label positioning separates premium shelf placement from commoditized mass-market competition.
- Natural:Minimally processed formulations without artificial preservatives, colors, or flavors capture mainstream premium demand. The FDA's Food Safety Modernization Act preventive controls elevate manufacturing costs for natural-positioned lines, squeezing mid-tier producers lacking dedicated food safety infrastructure.
- Grain-Free:Formulations excluding corn, wheat, and soy fillers align with humanization trends among millennial pet owners applying their own dietary restrictions to companion animals. E-commerce subscription channels overrepresent grain-free SKUs in auto-ship assortments.
- Organic:USDA Organic certification requires certified organic protein sourcing and processing aids, limiting supplier pools and extending lead times.
- Gluten-Free:Niche positioning addresses celiac-sensitive owner households rather than documented canine gluten intolerance.
Margin pools concentrate in Grain-Free; certification burdens favor Natural for mid-cap producers.
Packaging Type:
Format selection balances shelf visibility, portion control, and resealability against per-unit packaging cost.
- Pouches:Flexible laminated films with high-impact graphics dominate impulse purchase environments. Stand-up pouch formats command end-cap placement in Petco and PetSmart while minimizing shipping cube for e-commerce fulfillment.
- Ziplock Bags:Resealable polyethylene structures preserve freshness across multi-week consumption cycles for large-format purchases. Value-oriented retailers and warehouse clubs specify ziplock configurations for bulk SKUs.
- Tubs:Rigid polyethylene containers protect fragile jerky strips from crushing in transit, supporting premium gift and veterinary dispensing channels.
- Boxes:Paperboard secondary packaging enables pallet display efficiency and subscription box integration for direct-to-consumer brands.
Unit economics favor Pouches; subscription growth elevates Boxes.
Distribution Channel:
Channel selection determines margin capture, customer data access, and brand positioning latitude.
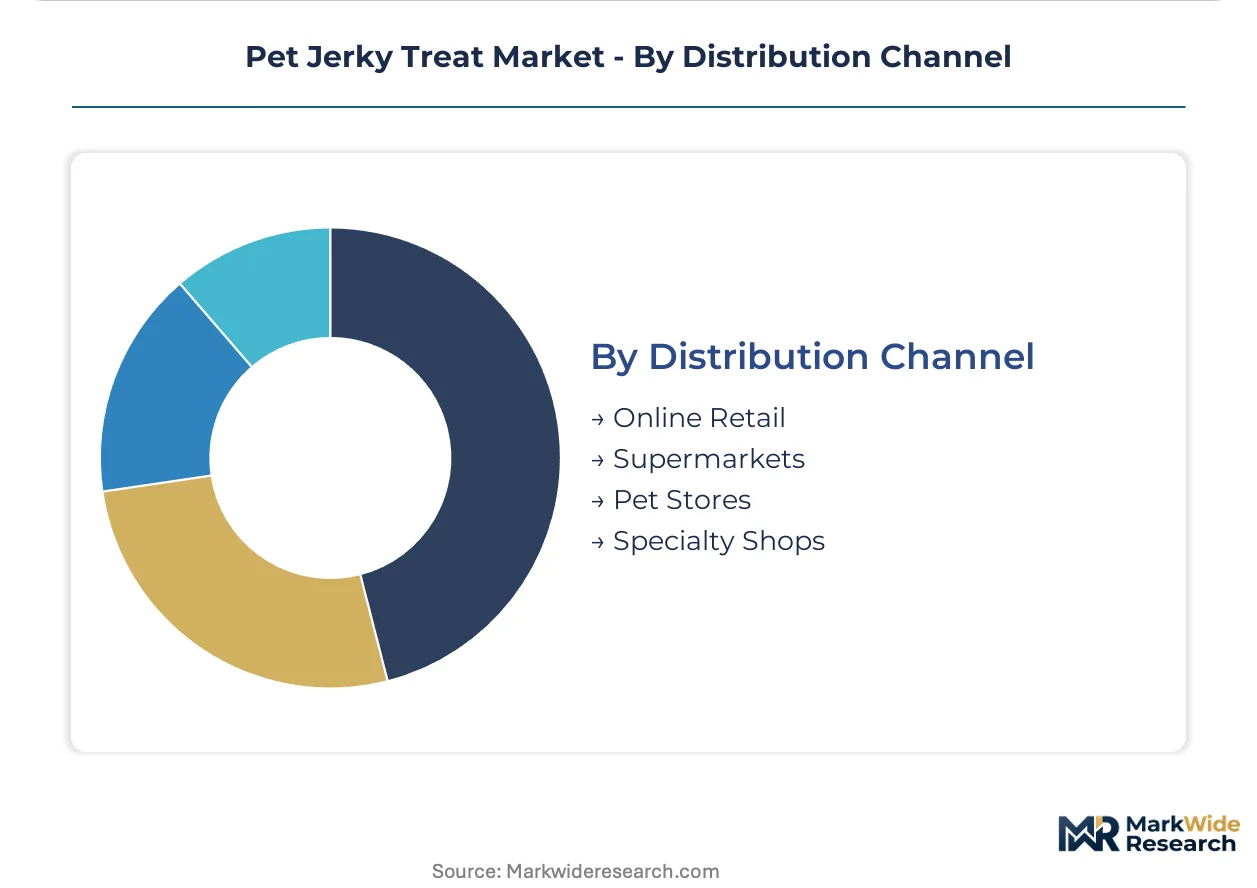
- Online Retail:Chewy and Amazon's Subscribe & Save platforms capture recurring replenishment previously routed through brick-and-mortar. Auto-ship algorithms surface grain-free and limited-ingredient SKUs based on purchase history, reducing customer acquisition costs for specialty formulations.
- Pet Stores:Petco, PetSmart, and independent boutiques provide tactile product evaluation and staff recommendation that converts premium-price acceptance. Slotting fees and promotional calendars strain emerging brand cash flows.
- Specialty Shops:Independent retailers and veterinary clinic dispensing command highest margins through personalized merchandising and prescriptive positioning.
- Supermarkets:Mass grocery placement extends reach to incidental pet owners with lower category engagement and price elasticity.
Recurring revenue concentrates in Online Retail; margin rate peaks in Specialty Shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial pet ownership concentrates in the United States, where e-commerce penetration and specialty retail chains accelerate category expansion. Regulatory compliance costs under the FDA's Food Safety Modernization Act reshape manufacturing footprints across major producing nations.
United States
Subscription auto-replenishment through Chewy and Amazon Subscribe & Save captures recurring revenue from urban millennial pet owners in California and New York metropolitan areas. The FDA enforces preventive controls for animal food under FSMA, requiring hazard analysis and supply chain verification from all jerky manufacturers. Midwestern USDA-inspected meat processing facilities in Iowa and Nebraska supply the bulk of chicken and beef raw materials for domestic production.
Germany
Premium pet retail chains and veterinary clinic dispensing channels command the highest margin pools for grain-free and limited-ingredient jerky formulations. EFSA guidelines on feed hygiene and traceability constrain supplier qualification requirements for imported protein sources. Industrial clusters in Bavaria and North Rhine-Westphalia host specialized pet food manufacturers investing in low-temperature dehydration systems.
China
Rapid urbanization in Shanghai and Beijing metro areas expands the addressable market for premium companion animal nutrition. SAMR and national food safety standards under GB requirements elevate manufacturing compliance costs for domestic producers. Yangtze River Delta manufacturing zones concentrate contract dehydration capacity serving both domestic consumption and export markets.
United Kingdom
Independent pet boutiques in London and Southeast England provide tactile product evaluation and staff recommendation for premium-positioned jerky lines. Post-Brexit import regulations and FSA enforcement of feed hygiene standards reshape EU supplier relationships. Midlands-based manufacturers leverage legacy meat processing infrastructure to enter the pet treat value chain.
Japan
Aging pet populations in Tokyo and Osaka metropolitan areas drive demand for functional jerky treats with dental and joint health positioning. METI and PMDA oversight of pet food manufacturing ensures stringent quality assurance protocols. Kanto region production facilities specialize in small-batch air-dried formats for the premium gift market.
Pet Jerky Treat Market Competitive Landscape
Backward integration into protein sourcing dominates the current landscape as manufacturers seek supply security and quality control. The vendor base stratifies across multinational conglomerates with captive raw material networks, mid-tier specialists with regional manufacturing scale, and emerging direct-to-consumer brands leveraging subscription platforms. Three archetypes define competitive positioning: vertically integrated protein controllers, formulation innovators in grain-free segments, and digital-native challengers bypassing traditional retail slotting structures. M&A activity and capacity expansion in low-temperature dehydration technology represent the dominant competitive moves reshaping manufacturing footprints.
Within the multinational tier, Nestlé Purina PetCare and Mars Petcare occupy positions anchored by global manufacturing scale spanning multiple protein species and regional taste preferences. Blue Buffalo exemplifies the formulation innovation archetype through grain-free positioning that commands premium shelf space in specialty retail channels. These three companies represent distinct strategic approaches to the tension between regulatory compliance scale and consumer demand for clean-label ingredient transparency.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare |
| Blue Buffalo |
| Spectrum Brands |
| Hill's Pet Nutrition |
| Wellness Pet |
| Zuke's |
| Plato Pet Treats |
| Wholesome Pride |
| Others |
Value Network & Pricing Analysis
Family-owned Midwestern meat processors anchor raw material supply for domestic jerky manufacturers, compressing pricing power at the mid-tier as FDA compliance costs favor scaled operators with dedicated food safety infrastructure. This ownership concentration in Iowa and Nebraska feedlots limits supplier diversification while elevating procurement leverage for vertically integrated conglomerates.
Pricing Analysis
Volume concentrates in mass-market chicken jerky while margin pools sit with grain-free and novel-protein formulations. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-dispensed therapeutic lines from specialty retail grain-free SKUs and mass-market single-protein strips. Pricing pressure stems from FSMA-mandated preventive controls that smaller producers cannot absorb without capital restructuring. Multi-dog households in mass retail channels exhibit highest price sensitivity; millennial subscribers to auto-replenishment platforms show lowest elasticity for limited-ingredient positioning.
Supply Chain Analysis
Chicken and beef raw material supply rests on Midwestern USDA-inspected facilities in Iowa, Nebraska, and Kansas, with secondary sourcing from Brazilian and Australian bovine operations for premium beef lines. Dehydration equipment, laminated packaging films, and pathogen detection systems constitute critical input dependencies. Single-source vulnerability in domestic human-grade meat processing creates concentration risk during regional disease outbreaks. Distribution runs through e-commerce fulfillment centers, specialty pet retail chains, and veterinary clinic dispensing networks in descending volume order.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as FDA Food Safety Modernization Act compliance costs force capital-constrained mid-tier producers toward distressed exits. Preventive controls mandates and third-party audit timelines are the dominant pressures accelerating this consolidation play.
For Market Incumbents: Extend backward integration into captive poultry and beef sourcing to insulate margin structures from commodity volatility. Nestlé Purina and Mars Petcare demonstrate how farm-to-finished-treat control neutralizes supply disruption risks. Add low-temperature dehydration capacity in FDA-inspected Midwestern facilities to capture raw-positioning growth without frozen distribution overhead. For New Entrants and Emerging Players: Begin with subscription direct-to-consumer models targeting urban millennial households in California and New York metropolitan areas, where auto-replenishment penetration exceeds specialty retail conversion. Novel protein formats—duck, rabbit, venison—offer the most penetrable white space given allergy-sensitive dog populations underserved by chicken-dominant incumbents. Veterinary endorsement partnerships provide prescriptive positioning distinct from mass retail slotting fee structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with existing SQF or BRCGS certification but strained balance sheets from legacy equipment retrofit costs. Five-to-ten year viability hinges on e-commerce channel access and grain-free formulation capabilities rather than mass retail footprint. Monitor state-level raw feeding restriction legislation as the critical inflection signal for supplier qualification requirements and facility location economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Sourcing | Captive supply from Iowa and Nebraska feedlots neutralizes commodity volatility for scaled manufacturers. |
| Low-Temperature Dehydration Capacity Expansion | Sub-160°F air-drying systems unify pathogen reduction with raw-positioning claims in single manufacturing footprints. |
| Subscription Direct-to-Consumer Launch | Chewy and Amazon Subscribe & Save algorithms reduce customer acquisition costs for grain-free specialty formulations. |
| Veterinary Endorsement Partnership | Clinic-based dispensing creates prescriptive positioning with margin premiums above mass retail channels. |
| Novel Protein Portfolio Diversification | Duck, rabbit, and venison SKUs address allergy-sensitive populations underserved by chicken-dominant assortments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pet food manufacturing executives, FDA compliance officers, specialty pet retail category buyers, and veterinary clinic dispensing managers. Bottom-up modeling triangulated against top-down industry association estimates validated volume and value outputs. Secondary sources included FDA FSMA enforcement records, USDA meat processing facility inspection data, AAFCO nutrient profile documentation, and e-commerce platform SKU assortment tracking.
Granularity-level modeling disaggregated volume and value across protein species, ingredient positioning, packaging format, and distribution channel dimensions throughout the forecast period. CAGRs derived from regression analysis against pet ownership demographics, e-commerce penetration curves, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated FSMA implementation timelines, subscription auto-replenishment adoption rates, and low-temperature dehydration technology diffusion patterns.
Protein commodity price shocks, regulatory enforcement intensity variations, and subscription platform algorithm changes are the dominant revision risks to modeled outputs. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Toy Dog Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Dog Bathing Systems Market
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Global Pet Companion Robots Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Smart Dog Collar Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Pet Accessories Market
Pet Care Products
Herbal Pet Shampoo Market
Pet Care Products
Mobile Pet Care Market
Pet Care Products
Europe Farrier Products Market