
 Global Smart Commute Market | 2026-2036
Global Smart Commute Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Commute Market Foresight
Lithium-ion battery chemistry is realigning cost structures across electric scooter and e-bike fleets, trimming per-vehicle operating expenditure and extending service lifecycles. Uber Technologies Inc. leverages its global driver network to integrate shared mobility with public transit APIs in multiple metropolitan corridors. Siemens AG anchors rail-to-microtransit connectivity through its digital platform deployments in European and Asian urban centers. BlaBlaCar differentiates through long-distance carpooling algorithms that optimize vehicle occupancy rates across intercity routes.
Smart commute systems integrate IoT sensors, AI algorithms, and GPS tracking into unified mobility platforms that dynamically match travelers with available transport modes based on real-time congestion, pricing, and carbon intensity parameters. These systems primarily serve to reduce single-occupancy vehicle dependence while cutting employer-subsidized parking costs and Scope 3 emissions liabilities. Ride sharing and e-bikes currently dominate trip volume in mature deployments, though autonomous shuttles represent the fastest-growing segment as pilot programs scale from controlled campuses to mixed-traffic public roads. Corporate offices command the deepest margin pools among end users, given their willingness to underwrite subscription-based commute benefits and their need for ESG-compliant workforce transport reporting.
The EU Green Deal and F-Gas Regulation shape vehicle electrification timelines and refrigerant choices in climate-controlled shuttle cabins across European deployments, while the EPA tailpipe standards and FAA urban air mobility frameworks influence technology roadmaps in the United States. China's MIIT dual carbon goals and GB standards for connected vehicle data security add compliance layers for platform operators seeking access to Shenzhen and Shanghai transit ecosystems. Stakeholders must weigh regulatory fragmentation against the cost of building modular platforms that can adapt certification, data sovereignty, and emissions reporting requirements without engineering redundancy.
Market Dynamics
Corporate ESG reporting mandates are compressing Scope 3 emissions liabilities into quantifiable commute subsidies, forcing employers to underwrite multimodal transit benefits rather than expand parking infrastructure. This structural shift redirects capital from fixed assets to subscription-based mobility platforms.
Growth Catalysts
- EU Green Deal transport decarbonization:Mandates accelerate electric scooter and e-bike infrastructure deployment across German, Dutch, and Danish urban cores.
- AI-powered fleet management:Corporate offices deploy predictive algorithms to optimize shuttle routing and reduce per-employee transit expenditure.
- Berlin-Munich corridor concentration:Integrated multimodal platforms connecting rail, shared mobility, and corporate networks demonstrate scalable deployment models.
Market Restraints
- Lithium-ion supply concentration:Battery cell manufacturing clusters in East Asia create input cost volatility and geopolitical exposure for fleet operators.
- F-Gas Regulation compliance:Climate-controlled shuttle cabins face refrigerant retrofit costs and certification delays across European deployments.
- Autonomous shuttle technical limitation:Edge-case handling in mixed-traffic environments constrains pilot-to-production scaling timelines.
Strategic Opportunities
- Underpenetrated Indian metro corridors:Bengaluru, Hyderabad, and Pune lack integrated first-last mile connectivity despite expanding corporate campus clusters.
- GB standards convergence:China's MIIT dual carbon goals and connected vehicle data security rules create compliant platform entry points for foreign operators.
- IoT-GPS-AI technology convergence:Unified sensor stacks enable real-time carbon intensity tracking for employer ESG disclosure automation.
Industry Challenges
- Embedded systems integration:Legacy transit agency IT infrastructure resists API connectivity with private mobility platforms.
- Data sovereignty compliance:Fragmented local storage mandates across Shenzhen, Shanghai, and Beijing transit ecosystems multiply engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Commute Market |
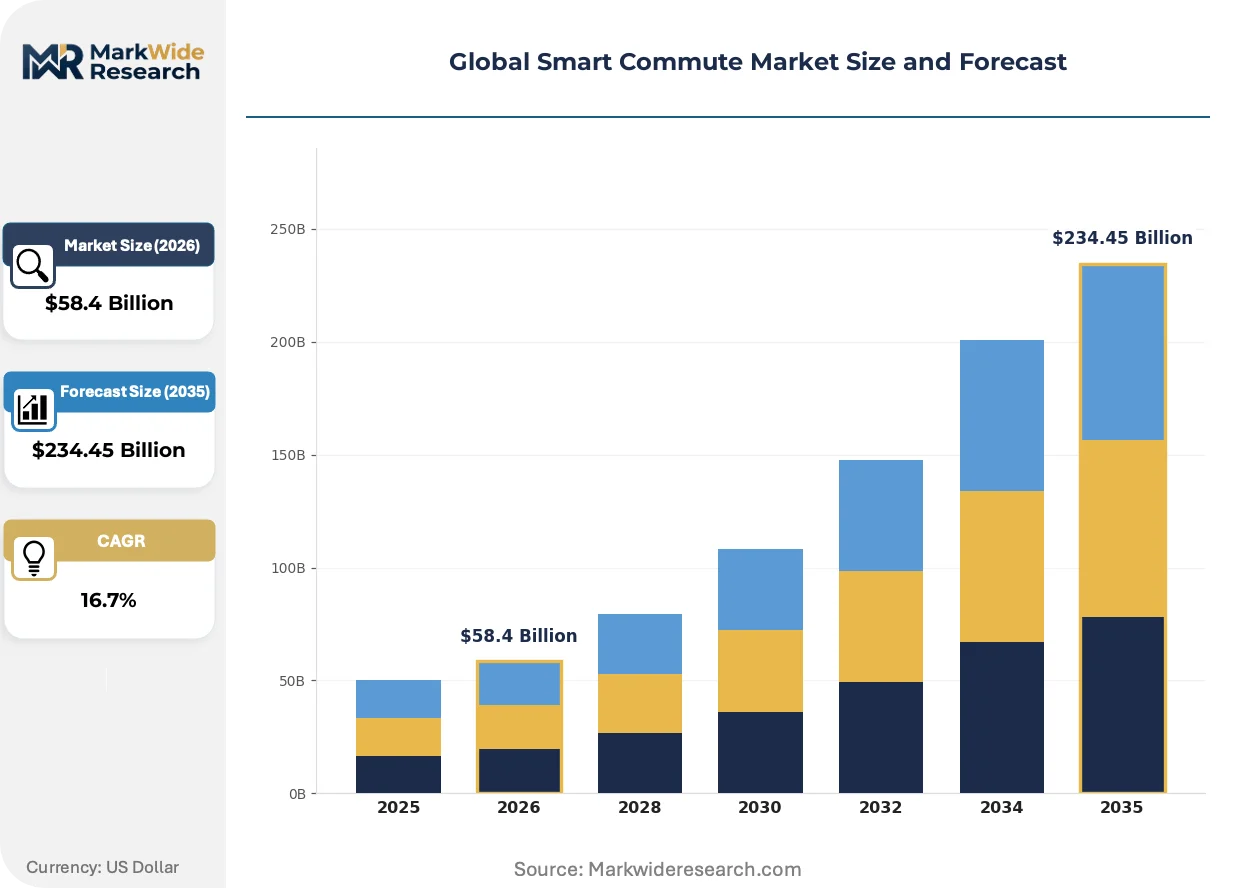
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $234.45 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Mode of Transport: E-Bikes, Ride Sharing, Autonomous Shuttles, Electric Scooters, Carpooling Technology: IoT Sensors, AI Algorithms, GPS Tracking, Mobile Apps, Big Data Analytics End User: Corporate Offices, Educational Institutions, Government Entities, Manufacturing Facilities, Entertainment Venues Deployment: Cloud Platforms, On-Premise Systems, Hybrid Solutions, Edge Computing |
| Companies Covered | Uber Technologies Inc., BlaBlaCar, Lyft Inc., Cisco Systems, Siemens AG, Cubic Transportation Systems, Moovit, Quick Ride, Turo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Commute Market Shifts & Advancements
Smart commute platforms are absorbing adjacent technologies into unified mobility stacks, collapsing the distinction between trip planning, payment, and emissions accounting into single-interface experiences for corporate subscribers.
Solid-state battery chemistry is absorbing thermal management complexity from electric scooter and e-bike fleets, trimming cooling hardware mass and extending cycle life. European micromobility operators are retrofitting existing fleets with pilot cell batches. This absorption of energy density improvements is compressing total cost of ownership calculations against internal combustion alternatives.
EPA tailpipe standards and FAA urban air mobility frameworks are bifurcating technology roadmaps in the United States, with shuttle operators optimizing for zero-emission zones while aerial mobility ventures pursue separate certification tracks. California Air Resources Board mandates are accelerating electric conversion timelines for corporate shuttle contracts. Fleet managers are responding by segmenting procurement between ground-based electrification and vertical takeoff reservation.
Employer procurement of commute benefits is consolidating around subscription models that bundle multiple transport modes into single per-employee charges. Traditional parking concession contracts are losing share to mobility-as-a-service platforms in London, Singapore, and Toronto financial districts. Corporate real estate managers in these cities are repurposing structured parking for last-mile logistics hubs.
Global Smart Commute Market Segmentation
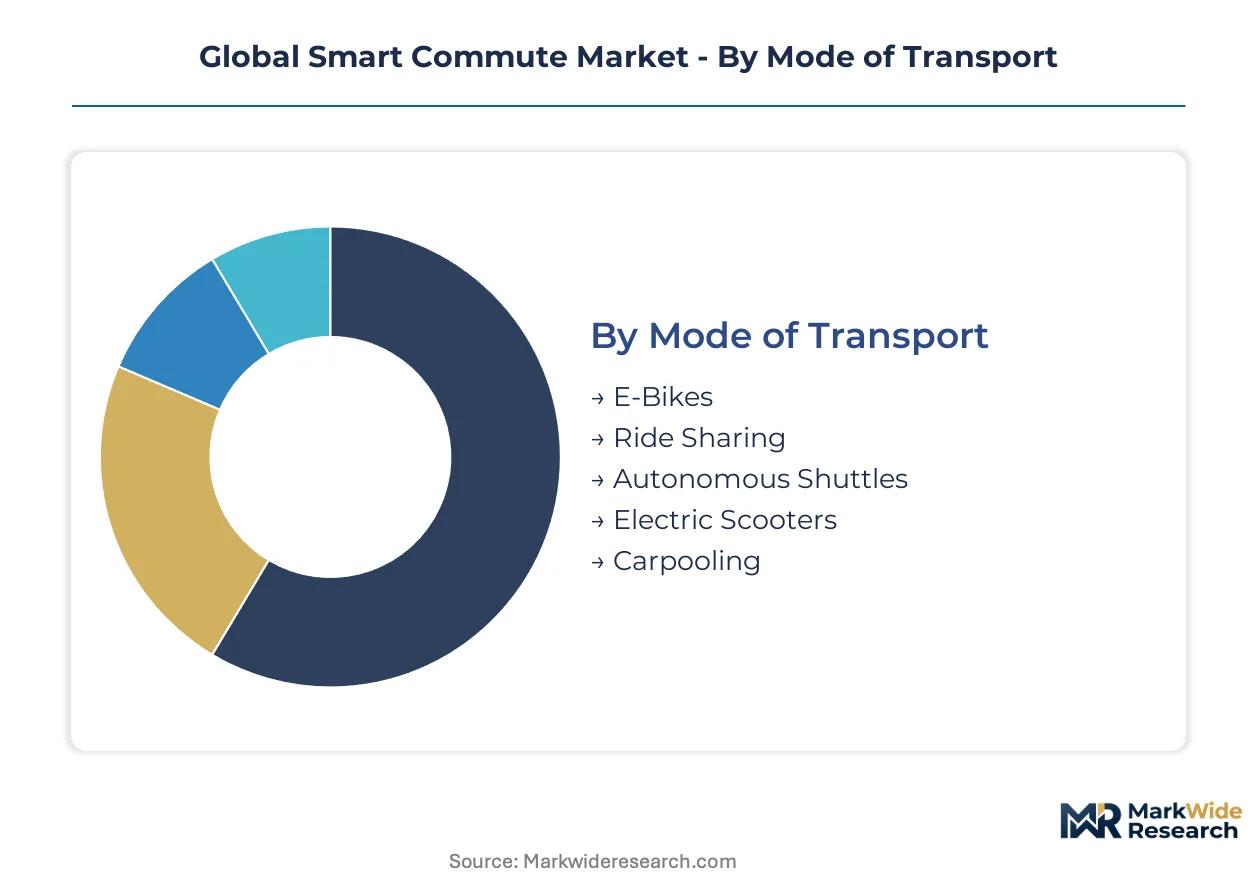
Smart commute platforms segment across hardware, software, and service layers that demand distinct capital commitments and partnership structures. Fleet operators and platform developers allocate resources differently depending on which transport modes, sensor stacks, and deployment architectures they prioritize.
Mode of Transport:
Capital intensity varies sharply across vehicle types, with autonomous hardware and battery-electric drivetrains commanding the heaviest upfront investment.
- Autonomous Shuttles:LiDAR arrays, redundant compute stacks, and regulatory certification cycles push per-unit deployment costs into six-figure ranges. German operators in Berlin and Munich absorb these outlays through municipal pilot contracts that defray validation expenses.
- E-Bikes:Mid-drive motor systems and removable battery packs balance acquisition cost against daily utilization rates. Dutch fleet operators concentrate procurement in this segment to exploit flat urban topography and established cycling infrastructure.
- Ride Sharing:Driver incentives and dynamic pricing engines dominate opex rather than capex, though platform development demands sustained engineering investment.
- Electric Scooters:Swappable battery architectures reduce downtime but multiply field service complexity across distributed charging networks.
- Carpooling:Algorithmic matching platforms require minimal physical asset ownership, concentrating spend on user acquisition and trust-verification systems.
Ride sharing absorbs the bulk of installed capacity; autonomous shuttles are expanding most quickly.
Technology:
Stack composition determines whether platforms build proprietary systems or license modular components from specialized vendors.
- AI Algorithms:Predictive demand forecasting and dynamic routing optimization differentiate mature platforms from commodity aggregators. Corporate offices in Singapore and Toronto pay premium subscription rates for commute-time prediction accuracy that feeds ESG reporting dashboards.
- IoT Sensors:Vehicle-mounted accelerometers, battery monitors, and environmental detectors generate telemetry streams that feed predictive maintenance models. Fleet operators in Shenzhen integrate these with GB standards-compliant data architectures to satisfy MIIT security mandates.
- GPS Tracking:Real-time positioning underpins geofencing, theft recovery, and usage-based billing across all shared mobility modes.
- Mobile Apps:Unified interfaces collapse trip planning, payment, and emissions accounting into single-touch experiences for corporate subscribers.
- Big Data Analytics:Aggregate pattern recognition informs network expansion decisions and regulatory compliance documentation.
Mobile apps absorb the bulk of installed capacity; AI algorithms are climbing the fastest.
End User:
Procurement sophistication and contract scale diverge substantially across organizational buyer types.
- Corporate Offices:Subscription-based commute benefits bundled with parking replacement programs command the deepest margin pools. London financial district employers underwrite multimodal platforms to satisfy CSRD-aligned Scope 3 disclosure requirements.
- Government Entities:Public transit agency tenders emphasize interoperability with legacy fixed-route systems and open data standards compliance.
- Educational Institutions:Campus shuttle networks prioritize safety certification and predictable scheduling over real-time optimization.
- Manufacturing Facilities:Shift-work alignment and perimeter security integration shape platform specifications for industrial workforce transport.
- Entertainment Venues:Event-driven demand spikes require surge-capable fleet partnerships rather than dedicated infrastructure.
Corporate offices absorb the bulk of installed capacity; government entities are gaining share fastest.
Deployment:
Architecture choices trade operational control against scalability and compliance overhead.
- Cloud Platforms:Elastic compute resources support rapid geographic expansion without regional data center construction. Operators targeting Indian metro corridors favor this model to sidestep fragmented local infrastructure requirements.
- On-Premise Systems:Air-gapped deployments satisfy data sovereignty mandates in defense and critical infrastructure sectors.
- Hybrid Solutions:Tiered processing splits sensitive user data on local servers while pushing analytics workloads to public cloud environments.
- Edge Computing:Vehicle-embedded inference engines enable sub-second decision-making for collision avoidance and traffic adaptation.
Cloud platforms absorb the bulk of installed capacity; edge computing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise zones in Singapore and Shenzhen concentrate smart commute platform deployment through tax-advantaged infrastructure bonds. These special economic corridors attract fleet operators seeking regulatory clarity and data localization compliance.
United States
Corporate campuses in Austin and Seattle underwrite subscription mobility benefits to satisfy CSRD-aligned Scope 3 disclosure requirements. EPA tailpipe standards and FAA urban air mobility frameworks bifurcate technology roadmaps between ground electrification and aerial certification tracks. California Air Resources Board mandates accelerate electric conversion timelines for Bay Area shuttle contracts.
Germany
Berlin and Munich build integrated multimodal platforms connecting rail, shared mobility, and corporate shuttle networks. EU Green Deal transport decarbonization mandates and F-Gas Regulation compliance requirements shape vehicle electrification timelines and refrigerant choices in climate-controlled cabins. KBA certification processes validate autonomous shuttle pilots in Bavarian urban cores.
China
Shenzhen and Shanghai transit ecosystems demand GB standards-compliant data architectures from platform operators seeking market entry. MIIT dual carbon goals and connected vehicle data security rules add compliance layers for foreign and domestic operators. Yangtze River Delta corporate campuses absorb the deepest subscription volumes for bundled multimodal benefits.
India
Bengaluru, Hyderabad, and Pune lack integrated first-last mile connectivity despite expanding corporate campus clusters. BIS certification requirements and state-level electric vehicle policies create fragmented procurement environments for fleet operators. Maharashtra and Karnataka subsidize charging infrastructure through public-private partnership frameworks.
United Kingdom
London financial district employers repurpose structured parking for last-mile logistics hubs as mobility-as-a-service platforms displace traditional parking concessions. CSRD-aligned ESG reporting mandates compress Scope 3 emissions liabilities into quantifiable commute subsidies. TfL open data standards enable API connectivity between private platforms and legacy transit infrastructure.
Global Smart Commute Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform developers commanding premium valuations against hardware fabricators. The vendor base concentrates around three strategic archetypes: mobility-as-a-service aggregators, rail-to-microtransit integrators, and long-distance carpooling algorithm specialists. M&A activity clusters around API connectivity assets and predictive routing engines. Geographic expansion into underpenetrated Indian metro corridors represents the dominant organic growth vector.
Among mobility-as-a-service aggregators, Uber Technologies Inc. and Lyft Inc. exemplify the scale-driven archetype through global driver network leverage and public transit API integration. Siemens AG anchors the rail-to-microtransit connectivity tier through digital platform deployments in European and Asian urban centers. BlaBlaCar occupies a distinct position within long-distance carpooling optimization, with algorithmic matching engines maximizing vehicle occupancy rates across intercity routes. These three players represent divergent strategic postures within a structurally fragmented competitive environment.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| BlaBlaCar |
| Lyft Inc. |
| Cisco Systems |
| Siemens AG |
| Cubic Transportation Systems |
| Moovit |
| Quick Ride |
| Turo |
| Others |
Supply & Pricing Matrix
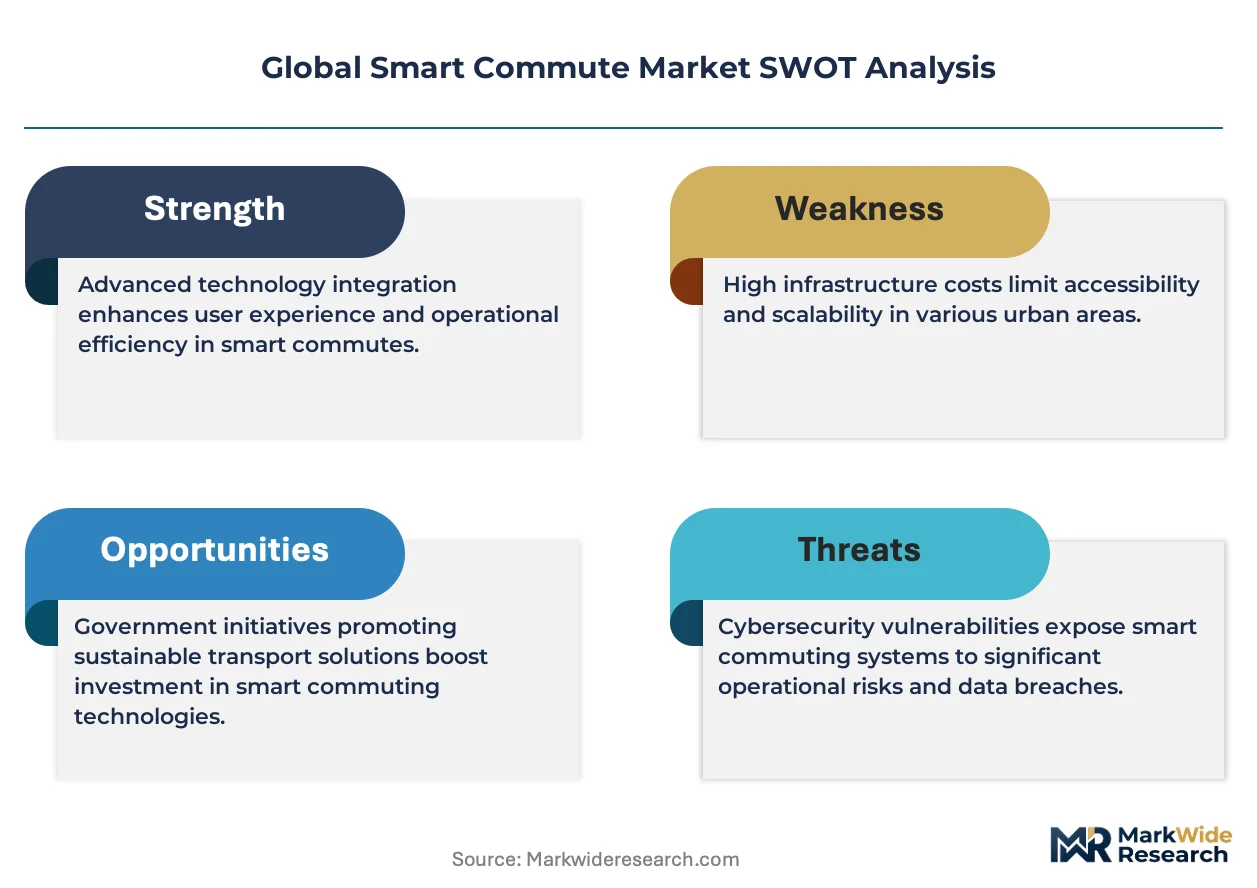
EU Green Deal transport decarbonization mandates gate qualified supply for fleet operators seeking premium-tier pricing access, as compliance-certified battery-electric drivetrains and F-Gas Regulation-compliant climate systems command subscription premiums from corporate buyers while excluding non-compliant hardware from tender eligibility.
Pricing Analysis
Lead-time compression commands premium pricing in autonomous shuttle procurement, with German municipal pilot contracts absorbing six-figure per-unit costs for accelerated KBA certification timelines while spot-market electric scooter inventory trades at discounted rates. Three-tier pricing structure across premium, standard, and economy levels separates ESG-compliant bundled subscriptions from single-mode transactional rides. Cost compression in micromobility hardware intensifies as Chinese cell manufacturers expand capacity. Corporate offices exhibit lowest price sensitivity given CSRD-aligned disclosure requirements, while individual commuters drive economy-tier volume.
Supply Chain Analysis
Reverse-logistics networks for swappable battery refurbishment and end-of-life LiDAR component recovery are emerging as cost centers for fleet operators managing distributed charging infrastructure and autonomous hardware refresh cycles. Lithium-ion cell manufacturing concentrates in China, South Korea, and Japan, with solid-state chemistry pilot batches sourced from European specialty suppliers. Cobalt and nickel feedstocks draw from Indonesian processing hubs and Chilean extraction operations. Single-source vulnerability in rare earth magnet supply for mid-drive e-bike motors threatens Dutch fleet procurement timelines. Distribution runs through regional hub-and-spoke models anchored by Shenzhen and Rotterdam logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform operators with proven API connectivity assets, as corporate procurement standardization forces subscale aggregators into distressed exits or acquisition targets.
For Market Incumbents: Deploy predictive routing engine investments to deepen switching costs among corporate subscribers, insulating against emerging mobility-as-a-service entrants targeting parking replacement contracts. Acquire specialized IoT sensor stacks to internalize telemetry analytics rather than licensing from third-party vendors. Anchor defensive positioning in Berlin-Munich corridor deployments where integrated multimodal platforms demonstrate scalable replication models. For New Entrants and Emerging Players: EU Green Deal transport decarbonization in Germany opens a window for battery-electric shuttle operators to capture municipal pilot contracts ahead of incumbent fleet electrification retrofits. Target underpenetrated Indian metro corridors in Bengaluru and Hyderabad where first-last mile connectivity gaps persist despite expanding corporate campus clusters. Pursue white-label platform licensing to real estate developers repurposing structured parking for last-mile logistics hubs. For Investors and Strategic Acquirers: KBA certification completion for autonomous shuttle pilots is the leading indicator that German operators are approaching production-scale deployment viability. Frame long-term positioning around 5-10 year subscription revenue visibility from corporate ESG mandates rather than transactional ride volume. Prioritize acquisition targets with proven GB standards-compliant data architectures enabling China market entry. Monitor MIIT dual carbon goal enforcement intensity as signal for foreign operator access windows.| Strategic Initiative | Industry Significance |
|---|---|
| API Connectivity Acquisition | Consolidates trip planning, payment, and emissions accounting into unified interfaces for corporate subscribers. |
| Solid-State Battery Pilot Deployment | European micromobility operators absorb thermal management complexity reduction and extended cycle life advantages. |
| GB Standards Compliance Investment | Unlocks platform entry into Shenzhen and Shanghai transit ecosystems under MIIT dual carbon frameworks. |
| Predictive Routing Engine Development | Corporate offices in Singapore and Toronto pay premium rates for commute-time accuracy feeding ESG dashboards. |
| Reverse-Logistics Network Buildout | Swappable battery refurbishment and LiDAR recovery reduce total cost of ownership across distributed fleets. |
Research Methodology
Independent corroboration across fleet operator procurement directors, municipal transit agency technology leads, corporate real estate sustainability officers, and micromobility platform engineers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU tender documentation, MIIT policy releases, and customs trade data for lithium-ion cell imports. Bottom-up deployment counts and top-down subscription revenue estimates triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume expansion from price evolution across mode of transport, technology stack, end user archetype, and deployment architecture dimensions. Modeled segments include autonomous shuttles, e-bikes, ride sharing, electric scooters, and carpooling modalities. CAGRs derive from logistic diffusion curves fitted to pilot program scaling timelines and corporate subscription penetration rates. Forecast inputs incorporate EU Green Deal enforcement trajectories, EPA tailpipe standard stringency assumptions, and solid-state battery cost reduction curves.
The model assumes a particular technology adoption path; alternative pathways for autonomous shuttle edge-case handling would alter the outlook toward extended pilot phases and delayed mixed-traffic deployment. Forecasts reflect assumptions regarding KBA certification timelines, BIS standard convergence in India, and corporate ESG reporting mandate expansion. Practitioners should monitor F-Gas Regulation refrigerant retrofit cost trajectories and lithium-ion supply concentration shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Smart Bus Shelters Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Road Profile Laser Sensor Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
Smart Fleet Management Market