
 Smart Package Lockers Market | 2026-2036
Smart Package Lockers Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Package Lockers Market Insights
REACH compliance is hardening the cost-of-entry calculus for smart locker manufacturers targeting European markets. Ricoh leverages its document-management heritage to anchor control over enterprise locker deployments in Japan and select Western markets. Quadient specializes in modular hardware configurations that sustain margin pools across logistics and property-management verticals. Cleveron competes through Estonian engineering efficiency, dominating automated pickup tower designs for grocery and retail chains.
Smart package lockers are electromechanical storage systems featuring steel-reinforced compartments, IoT-connected controllers, and multi-factor access protocols designed for unattended parcel exchange in commercial and residential environments. Wall-mounted lockers occupy the largest installed base in European apartment corridors and Japanese convenience stores, while modular locker systems represent the fastest-expanding category as property managers retrofit aging buildings and logistics hubs demand scalable capacity. RFID and QR code scanning technologies lead transaction volumes, though biometric authentication is gaining traction in corporate offices where security protocols restrict anonymous access.
The EU F-Gas Regulation and CE marking requirements shape thermal management and electrical safety standards for locker installations across member states, while the FCC governs wireless communication modules in US deployments. Japan's METI promotes IoT interoperability frameworks that ease cross-platform locker integration for domestic logistics providers. Stakeholders must monitor evolving cybersecurity mandates for connected infrastructure, as data-protection authorities in multiple jurisdictions tighten oversight of biometric credential storage and parcel-tracking databases.
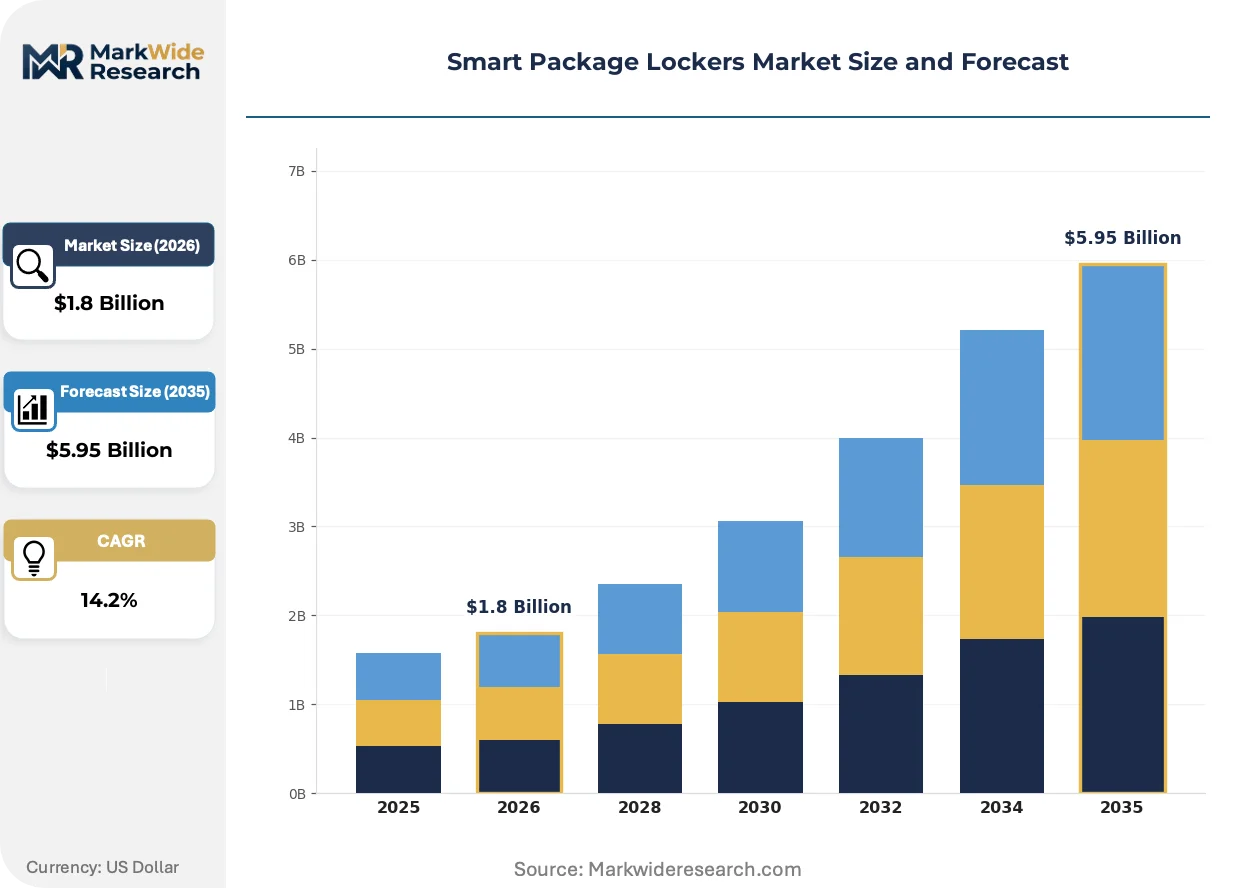
Market Dynamics
The EU Green Deal is compressing capital allocation timelines for locker manufacturers, forcing simultaneous redesigns of thermal management systems and material sourcing to meet binding carbon-intensity thresholds.
Growth Catalysts
- E-commerce last-mile consolidation:Major logistics platforms in Germany and Japan are deploying automated pickup infrastructure to reduce per-delivery costs in dense urban corridors.
- REACH compliance:The EU's chemical safety framework is standardizing material specifications across member states, creating regulatory clarity that accelerates cross-border procurement.
- IoT controller miniaturization:Embedded sensor arrays and edge-computing modules are enabling real-time compartment monitoring without dedicated facility infrastructure.
Market Restraints
- Steel alloy price volatility:Electromechanical locker frames rely on cold-rolled steel grades subject to energy-cost-driven input swings.
- Controller chipset concentration:Taiwan and South Korea fabs dominate IoT module supply, exposing manufacturers to single-source disruption risk.
- F-Gas thermal constraints:The EU F-Gas Regulation limits refrigerant options for temperature-controlled locker compartments, complicating pharmaceutical and grocery applications.
Strategic Opportunities
- Indian urban logistics:Tier-2 and Tier-3 cities lack parcel infrastructure density, creating first-mover positioning for modular locker networks.
- Biometric-credential convergence:Fingerprint and facial-recognition modules are merging with existing access-control systems in corporate office deployments.
- Japan METI interoperability:The ministry's IoT framework mandates cross-platform data standards, reducing integration friction for multi-vendor locker fleets.
Industry Challenges
- Cybersecurity credential storage:GDPR and emerging biometric data regulations require encrypted local processing architectures that extend development cycles.
- Legacy building retrofit compatibility:Aging electrical infrastructure in European residential blocks limits power availability for connected locker banks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Package Lockers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted Lockers, Free-Standing Lockers, Modular Lockers, Parcel Drop Boxes Technology: RFID, Biometric Authentication, QR Code Scanning, NFC, Bluetooth Connectivity Application: Last-Mile Delivery, Corporate Offices, Residential Complexes, Public Spaces, Educational Institutions End User: Logistics Providers, Property Managers, Delivery Services, E-Commerce Platforms |
| Companies Covered | Ricoh, Pitney Bowes, Quadient, InPost, Cleveron, TZ Limited, KEBA, LUXER Corporation, ASSA ABLOY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Package Lockers Market Trends and Innovations
Edge-computing architectures and biometric authentication modules are redefining locker system design priorities, shifting competitive advantage toward software-integrated hardware stacks.
Embedded solar-battery controllers are decentralizing power requirements for outdoor locker installations. Logistics operators in Australia and the southwestern United States are piloting off-grid units to avoid electrical permitting delays. This architecture is decentralizing deployment velocity in regions with constrained utility infrastructure.
The EU AI Act is imposing risk-classification requirements on biometric authentication systems. Locker manufacturers must now document algorithmic decision pathways for facial-recognition access modules. High-security corporate deployments in France and Germany are accelerating compliance investments ahead of enforcement deadlines.
Subscription-based hardware procurement is replacing outright purchase models among European property managers. Facility operators prefer operational-expense structures that bundle maintenance and software updates. This shift is most pronounced in German residential retrofit projects where capital budgets remain constrained.
Smart Package Lockers Market Segmentation
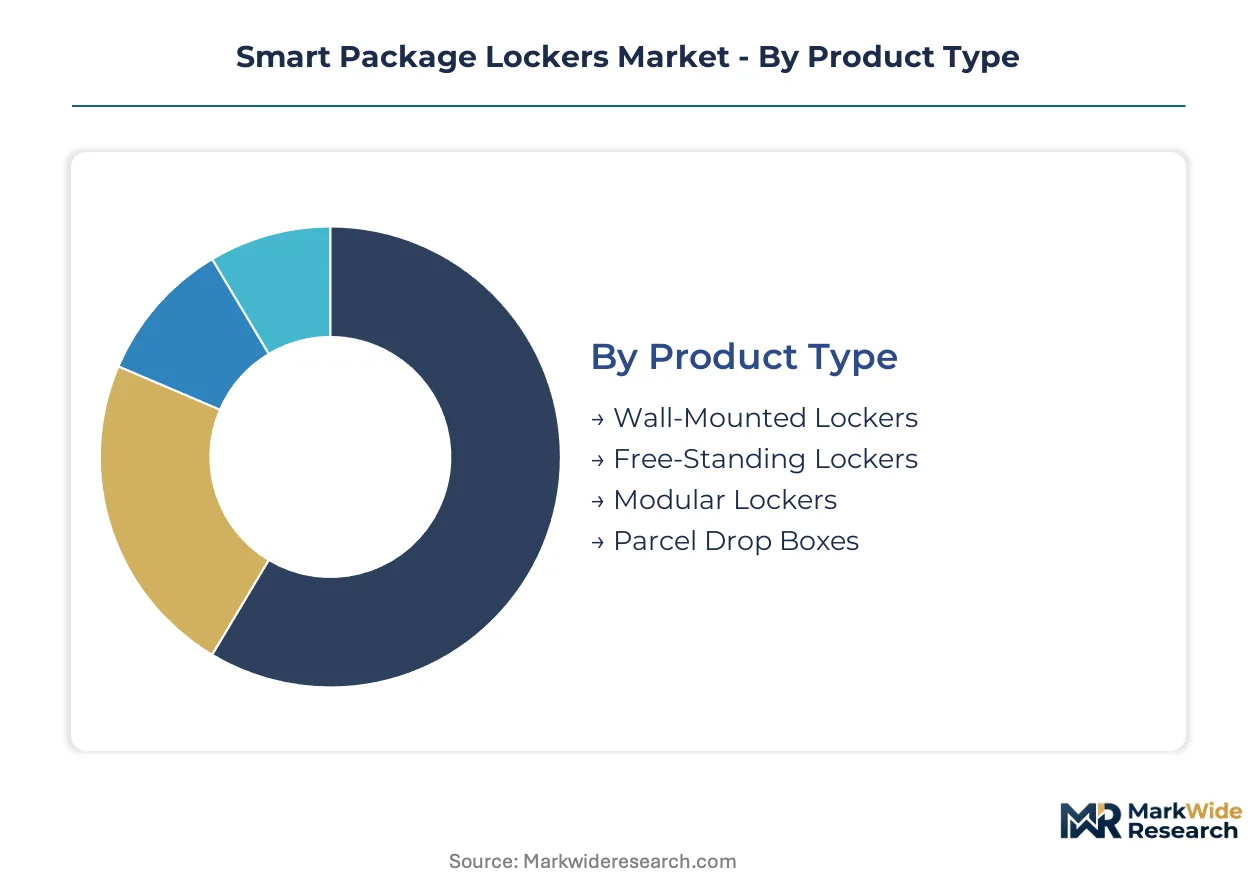
Segmentation in the smart package lockers market reveals how hardware specifications, access technologies, and deployment contexts shape procurement decisions. Supply chain configuration varies sharply across these dimensions, with electromechanical component sourcing and software integration requirements diverging by segment.
Product Type:
Steel frame fabrication and controller module sourcing concentrate differently across locker form factors, with wall-mounted designs leveraging standardized sheet-metal supply chains while modular systems demand flexible electromechanical architectures.
- Wall-Mounted Lockers:Steel-reinforced compartments affixed to vertical surfaces in corridors and convenience stores. German apartment buildings and Japanese retail chains drive installed base concentration, constrained by legacy electrical infrastructure in aging European residential blocks.
- Free-Standing Lockers:Self-supporting units with integrated power and network connectivity. Australian logistics operators and US southwestern deployments favor these for off-grid solar-battery configurations, bypassing utility permitting delays.
- Modular Lockers:Scalable compartment arrays with interchangeable electromechanical controllers. Property managers retrofitting aging buildings and logistics hubs seeking capacity expansion drive procurement.
- Parcel Drop Boxes:Single-access deposit units without retrieval capability. E-commerce platforms deploy these for customer returns in high-foot-traffic retail environments.
Wall-mounted lockers absorb the bulk of installed capacity; modular lockers are expanding most quickly.
Technology:
Authentication module procurement patterns reflect semiconductor supply concentration, with RFID and QR controllers sourcing from Taiwan and South Korea fabs while biometric systems require specialized edge-computing chipsets.
- RFID:Radio-frequency identification tags enabling contactless compartment access. Transaction volumes concentrate in logistics networks across Germany and Japan, where established last-mile infrastructure favors proven authentication protocols.
- Biometric Authentication:Fingerprint and facial-recognition modules with encrypted local processing. Corporate offices in France and Germany accelerate deployments ahead of EU AI Act enforcement deadlines for algorithmic decision documentation.
- QR Code Scanning:Optical recognition of matrix barcodes via smartphone cameras. E-commerce platforms favor this low-friction method for consumer-facing installations.
- NFC:Near-field communication protocols for tap-to-open access. Property management verticals integrate these with existing building access control systems.
- Bluetooth Connectivity:Proximity-based unlocking via paired mobile devices. Pilots in Indian Tier-2 cities test this for markets lacking dense parcel infrastructure.
RFID and QR code scanning dominate transaction volumes; biometric authentication climbs the fastest as security protocols tighten in corporate deployments.
Application:
Deployment context determines power availability, network connectivity requirements, and regulatory exposure, with public installations facing stricter cybersecurity mandates than controlled private environments.
- Last-Mile Delivery:Unattended parcel exchange points for courier handoffs. Dense urban corridors in Germany and Japan anchor demand, with logistics platforms deploying automated pickup infrastructure to reduce per-delivery costs.
- Corporate Offices:Secure package reception for enterprise tenants. GDPR and emerging biometric data regulations force encrypted local processing architectures that extend development cycles for this segment.
- Residential Complexes:Multi-tenant installations in apartment buildings. European retrofit projects favor subscription-based hardware procurement over capital purchase.
- Public Spaces:Transit hubs, parks, and municipal locations with high anonymity risk. Data-protection authorities tighten oversight of parcel-tracking databases in these deployments.
- Educational Institutions:Campus-wide networks serving student populations. Network security requirements vary by national education data frameworks.
Last-mile delivery absorbs the bulk of installed capacity; corporate offices gain share fastest on security premium differentiation.
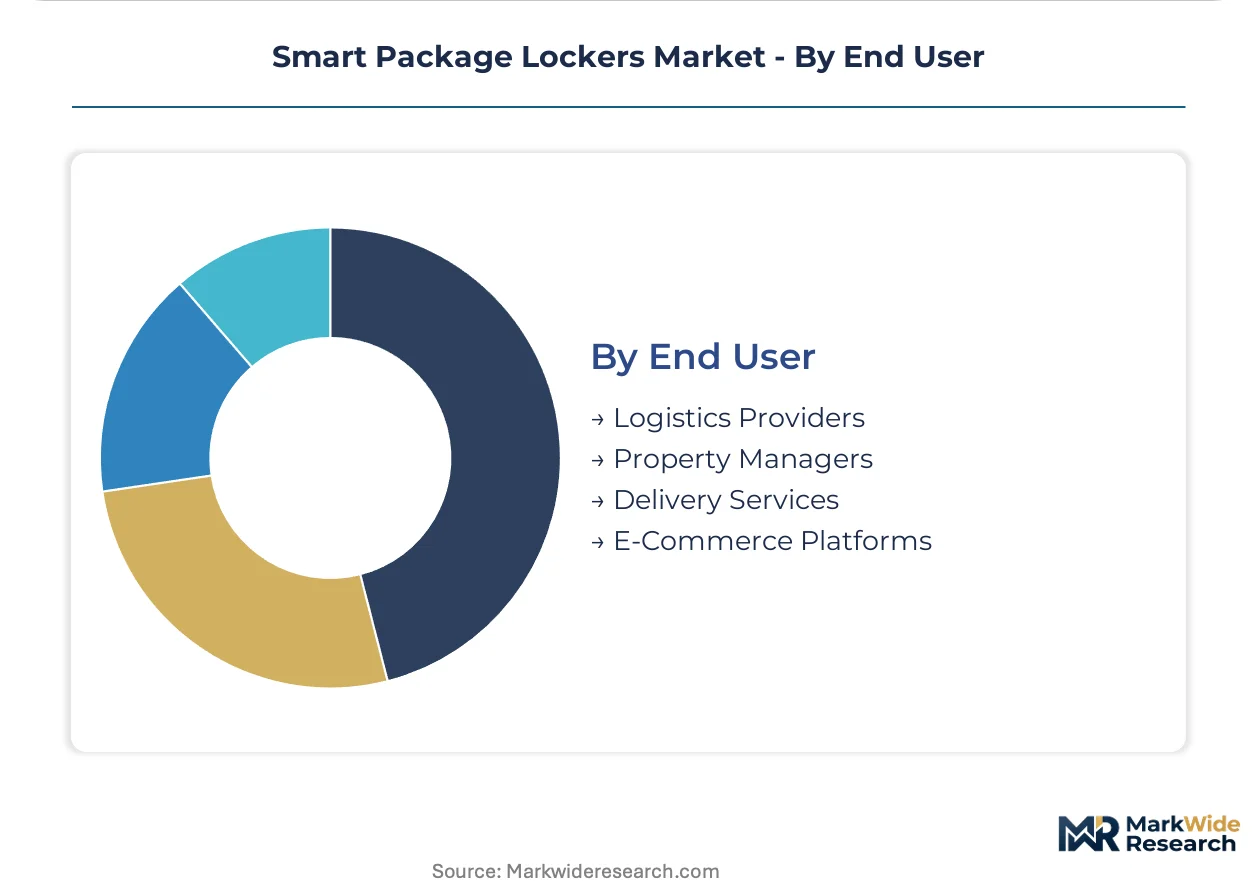
End User:
Procurement authority and budget structure diverge sharply, with logistics providers optimizing for throughput velocity while property managers prioritize operational-expense flexibility.
- Logistics Providers:Courier companies and postal operators managing high-volume parcel flows. DHL and Japan Post network expansions concentrate demand in automated pickup infrastructure.
- Property Managers:Facility operators maintaining multi-tenant buildings. German residential retrofit projects show pronounced preference for subscription models bundling maintenance and software updates.
- Delivery Services:Third-party courier platforms without owned locker networks. These users access shared infrastructure through platform agreements.
- E-Commerce Platforms:Online retailers deploying proprietary pickup networks. Amazon and regional platforms expand smart locker deployments to streamline fulfillment.
Logistics providers absorb the bulk of installed capacity; property managers are expanding most quickly on subscription-model conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German free-trade zones and Japanese special economic districts concentrate smart locker manufacturing capacity, drawing component suppliers into clustered logistics corridors that reduce procurement lead times for electromechanical assemblies.
Germany
Dense urban logistics networks in Berlin and Hamburg drive automated parcel infrastructure deployment, with DHL and Deutsche Post expanding locker density to reduce last-mile delivery costs. REACH compliance and the EU F-Gas Regulation standardize material specifications and thermal management requirements across member states. The Rhine-Ruhr industrial corridor hosts steel fabrication clusters supplying cold-rolled frame components to locker assemblers.
Japan
Convenience store chains and residential tower complexes anchor wall-mounted locker installations in Tokyo and Osaka metropolitan zones. METI's IoT interoperability frameworks mandate cross-platform data standards that reduce integration friction for multi-vendor fleets. The Kanto region concentrates controller module engineering firms serving domestic logistics providers.
United States
Southwestern logistics operators pilot solar-battery locker configurations to bypass utility permitting delays in Arizona and Nevada desert corridors. FCC wireless communication regulations govern IoT module certifications for connected compartment systems. The Dallas-Fort Worth metroplex emerges as a distribution hub for modular locker deployments serving e-commerce fulfillment networks.
India
Tier-2 and Tier-3 cities including Pune, Jaipur, and Kochi lack parcel infrastructure density, creating first-mover positioning for modular locker networks. BIS certification requirements and the PLI scheme for electronics manufacturing shape local assembly incentives. The Maharashtra industrial belt attracts component suppliers targeting domestic logistics modernization.
Australia
Off-grid solar locker pilots in Queensland and Western Australia address constrained utility infrastructure in remote mining and agricultural logistics corridors. The TGA and national cybersecurity frameworks influence data-protection standards for connected parcel tracking. Sydney and Melbourne anchor urban last-mile consolidation projects for courier platform operators.
Smart Package Lockers Market Competitive Landscape
German and Japanese producers anchor one tier; Estonian and Australian specialists hold differentiated positions in automated pickup tower and off-grid configurations. The vendor base concentrates around three strategic archetypes: diversified office-technology conglomerates repurposing document-management infrastructure, pure-play locker engineering firms optimizing electromechanical efficiency, and security-hardware manufacturers extending into parcel access control. Competitive dynamics center on M&A activity consolidating controller chipset supply chains and strategic partnerships between locker assemblers and logistics platforms securing dedicated deployment volumes.
Within the diversified conglomerate tier, Ricoh and Pitney Bowes occupy positions shaped by legacy document-management infrastructure that translates into enterprise locker control systems. Quadient represents the modular hardware specialist archetype, with configurations sustaining margin pools across property-management and logistics verticals. Cleveron anchors the engineering-efficiency segment, exemplifying automated pickup tower designs optimized for grocery and retail chain deployments.
| Leading Market Players |
|---|
| Ricoh |
| Pitney Bowes |
| Quadient |
| InPost |
| Cleveron |
| TZ Limited |
| KEBA |
| LUXER Corporation |
| ASSA ABLOY |
| Others |
Pricing and Supply Chain Analysis
Cold-rolled steel price indices cascade through smart locker manufacturing tiers, compressing margins for economy-grade wall-mounted units while premium modular systems with embedded IoT controllers absorb volatility through subscription pricing structures. German logistics providers and Japanese convenience store chains face divergent procurement timelines that stratify cost structures across the value chain.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate expedited modular locker deliveries from standard-batch wall-mounted configurations. Three-tier pricing structure across premium, standard, and economy levels reflects controller chipset certification tiers and steel gauge specifications. Pricing pressure stems from Taiwan fab capacity constraints tightening IoT module availability. Property managers in German residential retrofit projects exhibit highest price sensitivity through subscription-model negotiations, while corporate security buyers in France and Germany prioritize biometric authentication premiums.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor, Kanto industrial belt, and Dallas-Fort Worth metroplex anchor hub-and-spoke fulfillment patterns for electromechanical assemblies. Controller module fabrication concentrates in Taiwan and South Korea, with steel frame sourcing anchored in German and Chinese cold-rolled mills. Single-source vulnerability in Taiwan semiconductor fabs threatens IoT chipset continuity. Distribution runs through logistics provider procurement consortiums and property management group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric authentication modules are displacing legacy RFID and QR code systems in corporate office deployments, compressing competitive windows for hardware-only vendors. This technology-transition phase demands repositioning across incumbent, entrant, and investor archetypes.
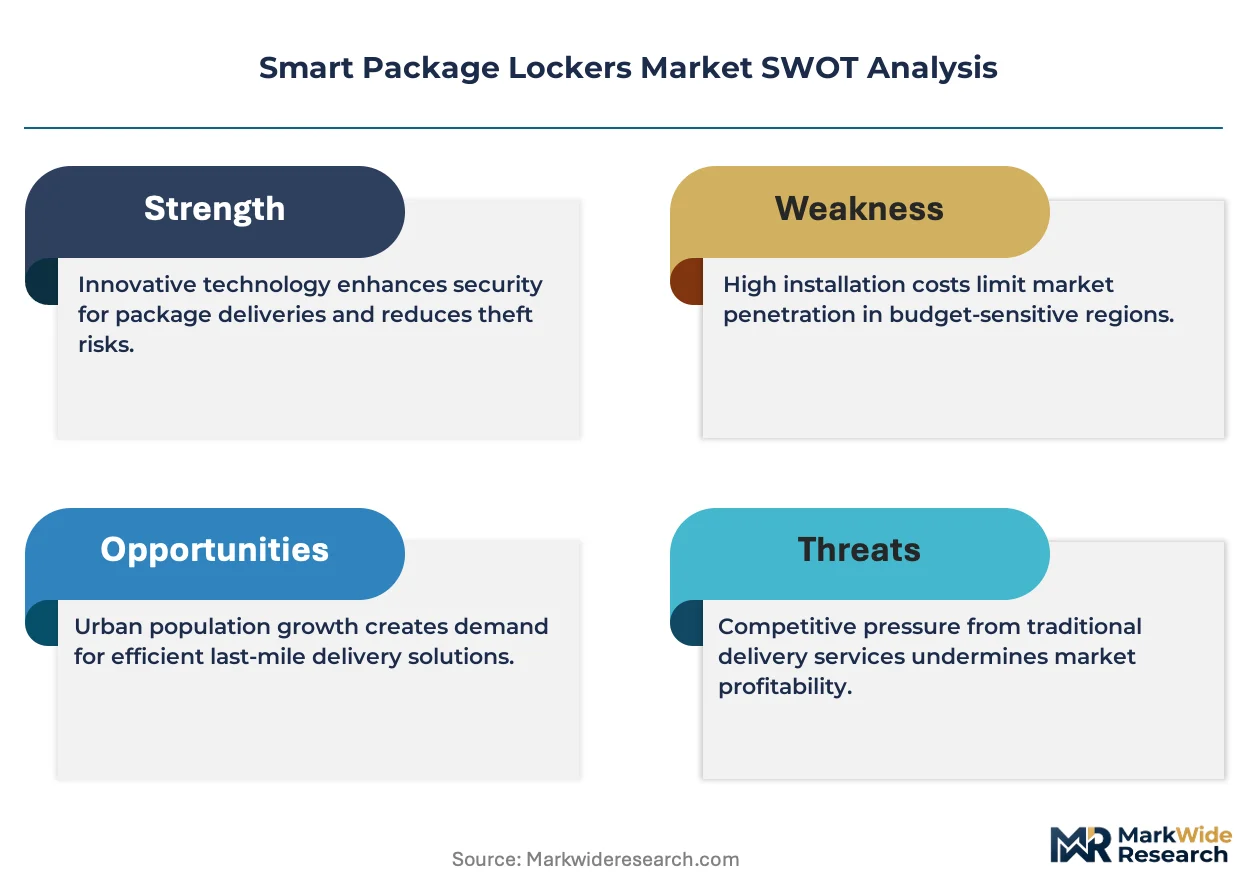
For Market Incumbents: Anticipate margin compression in wall-mounted locker categories as modular systems capture property management subscription conversions. Defensive consolidation through captive controller chipset supply and REACH certification pre-positioning in German manufacturing clusters offsets emerging Estonian engineering competitors. Prioritize METI interoperability compliance in Japanese deployments to lock in convenience store channel control. For New Entrants and Emerging Players: Direct-to-property-manager SaaS platforms offer lowest customer acquisition friction in Indian Tier-2 and Tier-3 city expansions. White-space concentration in off-grid solar-battery configurations for Australian mining corridors and southwestern US desert logistics presents first-mover positioning. Target modular locker retrofits in aging European residential blocks through subscription-based operational expense structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor diversified office-technology conglomerates with document-management heritage in Japanese and Western European markets. Long-term viability across the analysis window hinges on software-integrated hardware stack differentiation. Watch biometric authentication compliance investment rates ahead of EU AI Act enforcement as inflection indicator for premium segment capture.| Strategic Initiative | Industry Significance |
|---|---|
| Controller Chipset Supply Agreement | Secures Taiwan and South Korea fab allocation against single-source disruption risk. |
| Biometric Authentication Module Launch | Captures GDPR-compliant corporate office premium ahead of EU AI Act deadlines. |
| Solar-Battery Off-Grid Configuration | Bypasses utility permitting delays in Australian and southwestern US deployments. |
| Subscription Model Conversion | Aligns with German property manager preference for operational expense structures. |
| METI Interoperability Certification | Reduces integration friction for multi-vendor locker fleets in Japanese logistics networks. |
Research Methodology
Document review covered customs and trade data, SEC filings, and EU regulatory submissions, complemented by interviews with logistics procurement directors, property management facility heads, smart locker engineering leads, and IoT controller chipset suppliers. Secondary validation drew from FCC certification databases, METI interoperability framework documents, and BIS electronics manufacturing scheme disclosures. Bottom-up unit deployment estimates and top-down logistics infrastructure spending patterns were triangulated to anchor market sizing.
Cross-referencing historical deployment trajectories against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, access technology, deployment context, and end-user procurement authority. CAGRs were derived from logistics automation investment correlations and e-commerce fulfillment density metrics. Industry-specific forecast inputs incorporated REACH compliance cost pass-through rates and solar-battery controller adoption curves in off-grid pilot regions.
Inputs from logistics provider capital expenditure disclosures and property management procurement databases were available through the study window; gaps in biometric authentication algorithmic decision pathway documentation introduce uncertainty bands around corporate office segment projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart Shade Device Market
Smart City Technology
E-Governance Market
Smart City Technology
Smart Signaling Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Smart Communities Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
City Data Platform Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
Global Smart Ticketing Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Smart City Framework Market