
 Mining Collectors Market | 2026-2036
Mining Collectors Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Collectors Market Outlook
Xanthate-based formulations are recalibrating product economics across the Mining Collectors Market as miners seek alternatives with lower aquatic toxicity profiles. Senmin International Limited leverages its integrated manufacturing footprint across Southern Africa to sustain cost advantages in bulk xanthate supply. Coogee Chemicals Pty Limited anchors its position through specialized dithiophosphate production tailored to Australian base metal flotation circuits. SNF FloMin Inc. competes on global logistics scale, operating regional blending facilities that reduce lead times for remote mining camps.
Mining collectors are surface-active chemical reagents, typically organosulfur compounds with carbon chain lengths of C2-C6, designed to render target minerals hydrophobic for froth flotation separation. Their primary industrial purpose is to selectively bind valuable sulfide minerals—copper, lead, zinc, nickel—onto air bubbles, enabling concentration from run-of-mine ore grades below one percent metal content. Handheld collectors and portable devices occupy the mature end of the product spectrum, serving artisanal and small-scale geological surveying where price sensitivity constrains margins. Automated systems represent the fastest-expanding segment, integrating optical and electromagnetic sensor arrays for real-time ore characterization that reduces reagent overconsumption. Industrial collectors dominate absolute volume, though margin pools increasingly concentrate in technology-integrated platforms that combine capacitive detection with predictive dosage algorithms.
Chile's SMA enforces water quality standards that directly restrict xanthate discharge limits in copper concentrators, while Australia's Department of Climate Change, Energy, the Environment and Water mandates progressive rehabilitation bonds tied to chemical management plans. ISO 14001 environmental management certification now functions as a de facto market access requirement for collector suppliers to tier-one mining companies. Stakeholders must monitor regulatory divergence between jurisdictions that reward early formulation transitions versus those that grandfather existing chemical permits.
Market Dynamics
Declining ore grades across Chile's Atacama copper belt and Australia's Pilbara region are forcing concentrators to process more rock per unit metal, directly inflating collector consumption per ton of output. This geological pressure intersects with tightening effluent rules to reshape reagent selection criteria.
Growth Catalysts
- Chile's SMA water discharge mandates:Copper concentrators in the Andean watershed must cut xanthate residuals, creating pull for biodegradable dithiophosphate and thionocarbamate alternatives that command premium positioning.
- Sensor-based flotation optimization:Automated systems integrating optical and electromagnetic arrays enable real-time reagent dosage adjustments, reducing overconsumption while maintaining recovery rates in low-grade circuits.
- Peru's copper expansion pipeline:New concentrator projects in the southern copper belt are specifying collectors with lower aquatic toxicity profiles from commissioning, bypassing legacy chemical transitions.
Market Restraints
- Carbon disulfide price volatility:Xanthate synthesis depends on this petrochemical feedstock, exposing margins to crude oil and sulfur market swings that suppliers cannot fully hedge.
- Chinese reagent manufacturing concentration:Bulk xanthate supply chains route through Shandong and Jiangsu provinces, creating single-point vulnerability for non-integrated buyers during export license suspensions.
- Biodegradable alternative performance gaps:Thionocarbamates struggle to match xanthate selectivity for complex polymetallic ores, limiting substitution in lead-zinc-silver circuits.
Strategic Opportunities
- Kazakhstan's untapped base metal reserves:The Kounrad and Bozshakol copper operations are modernizing Soviet-era concentrators, opening demand for collectors compatible with high-salinity process water.
- EU Green Deal chemical taxonomy alignment:Collectors certified under REACH Article 57 SVHC exemption pathways gain preferential access to European smelter offtake contracts.
- Predictive dosage algorithms:Machine learning models trained on historical flotation data are converging with capacitive sensors to enable closed-loop reagent control that cuts consumption.
Industry Challenges
- Flotation chemist skill scarcity:Experienced operators who can diagnose froth stability issues across varying ore mineralogies are retiring faster than training programs replace them.
- ISO 14001 certification timelines:Supplier audits for environmental management systems now stretch 14-18 months, delaying market access to tier-one mining houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Collectors Market |
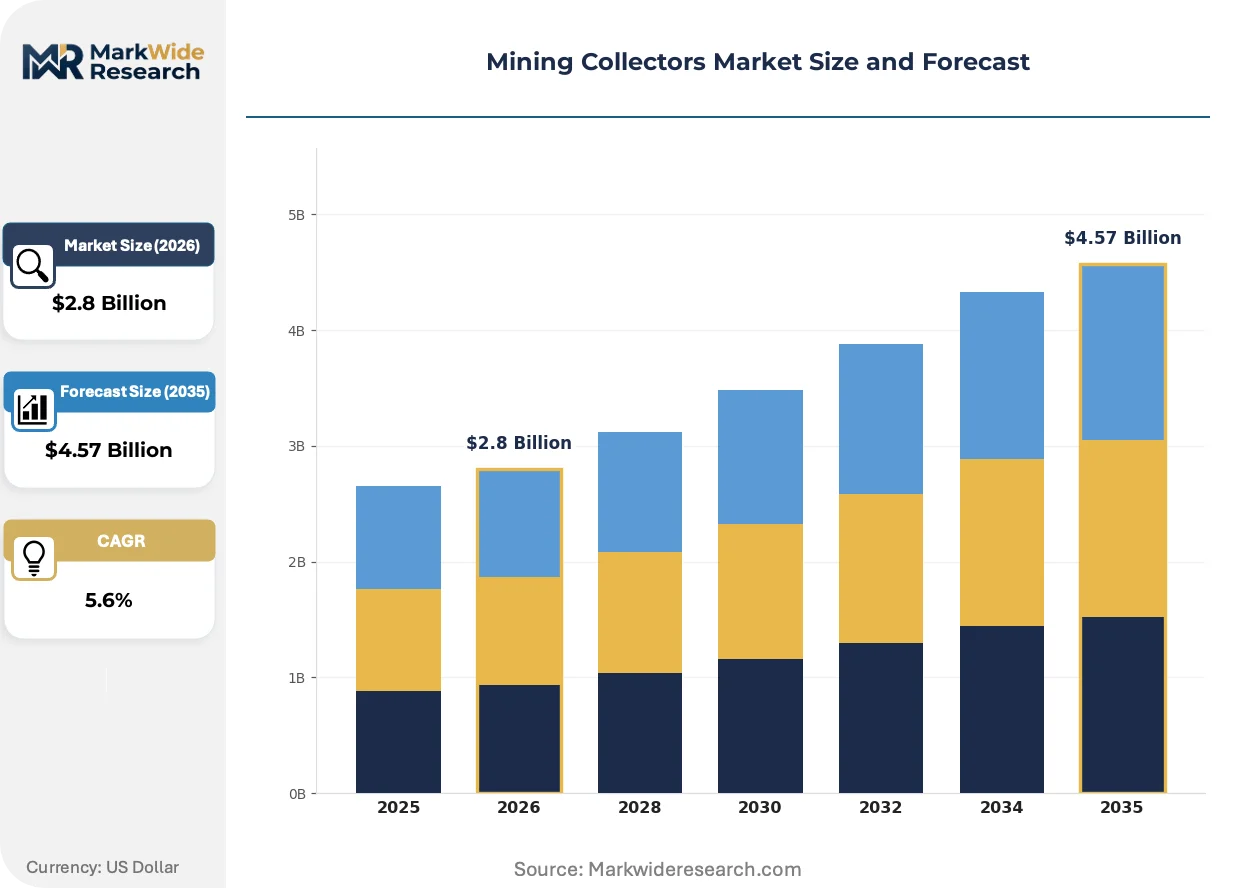
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Collectors, Industrial Collectors, Automated Systems, Portable Devices Technology: Electromagnetic, Capacitive, Optical, Acoustic Application: Metal Detection, Geological Surveying, Mineral Exploration, Environmental Monitoring End User: Mining Companies, Research Institutions, Environmental Agencies, Contractors |
| Companies Covered | Senmin International Limited, Coogee Chemicals Pty Limited, SNF FloMin Inc., Orica Ltd, CTC Mining, Vanderbilt Chemicals, LLC, Tieling Flotation Reagents Co., Ltd, QiXia TongDa Flotation Reagent Co., Limited, Celtic Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Collectors Market Strategic Shifts
Reagent formulation chemistry and digital process control are converging to redefine collector performance metrics beyond traditional grade-recovery curves. Suppliers now compete on environmental persistence and dosage precision rather than bulk commodity pricing.
Thionocarbamate collectors are absorbing market share in copper-molybdenum separation circuits where selectivity against iron sulfides determines economic viability. Codelco's Andina and El Teniente divisions have completed retrofits to these chemistries. The technology is absorbing capital that would otherwise flow to additional rougher flotation capacity, effectively substituting chemistry for mechanical volume.
Australia's Department of Climate Change, Energy, the Environment and Water now mandates progressive rehabilitation bonds tied to chemical management plans, forcing concentrators to document collector fate in tailings streams. This policy compresses the approved reagent list for new project approvals. Western Australian gold operations are responding by pre-qualifying collectors against aquatic toxicity benchmarks before pilot plant testing.
Buyers in Chile's mining sector are consolidating reagent procurement under corporate sustainability officers who evaluate total cost of environmental compliance alongside unit pricing. This organizational shift displaces site-level metallurgists as primary decision-makers. The pattern is most visible at state-owned Codelco, where centralized sourcing now requires biodegradability data sheets for all collector tenders.
Mining Collectors Market Segmentation
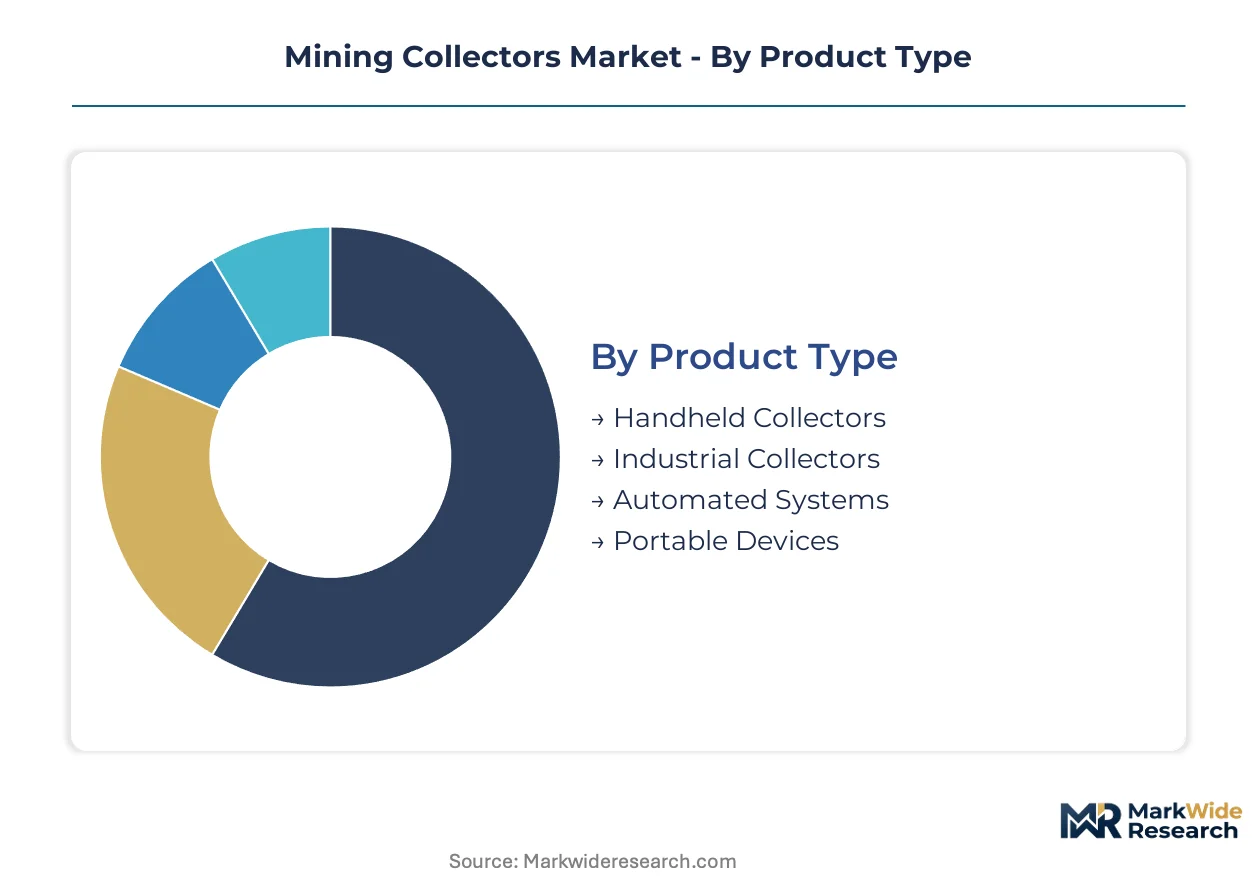
Segmentation in mining collectors reveals how equipment economics diverge between high-volume industrial operations and precision-oriented exploration workflows. Collector selection varies sharply by deployment scale, with automated systems commanding premium positioning against handheld units serving price-constrained geological teams.
Product Type:
Volume concentrates in industrial installations, while margin pools accrue to technology-integrated platforms that reduce chemical overconsumption through predictive control.
- Industrial Collectors:These systems handle bulk reagent delivery across concentrator circuits, typically managing xanthate and dithiophosphate flows exceeding 50 tons annually. Demand clusters in Chile's Atacama copper belt where Codelco and private operators process declining ore grades that inflate per-ton collector consumption. Stricter SMA discharge mandates are forcing retrofits to biodegradable formulations even as throughput requirements climb.
- Automated Systems:Platforms integrating optical and electromagnetic sensor arrays enable real-time ore characterization and closed-loop dosage adjustments. Australia's Pilbara iron ore operations and Peru's southern copper belt are specifying these systems from commissioning to preempt regulatory compliance costs and reduce reagent waste in low-grade circuits.
- Handheld Collectors:Portable units serve artisanal geological surveying where price sensitivity constrains margins to commodity levels.
- Portable Devices:Compact field units support rapid mineral identification in remote exploration camps across Kazakhstan's Kounrad copper district.
Mature deployment sits with Industrial Collectors. Newer deployment is concentrated in Automated Systems.
Technology:
Detection methodology determines precision thresholds and capital intensity across exploration and processing applications.
- Optical:Sensor arrays analyze mineral surface reflectance and froth stability characteristics in real-time flotation optimization. Chilean concentrators are deploying these systems to reduce xanthate overconsumption while maintaining recovery rates in complex polymetallic ores.
- Electromagnetic:Arrays detect conductive mineral signatures through induced field perturbations, enabling non-invasive subsurface mapping. Australian base metal exploration teams favor this approach for rapid target delineation across the Pilbara and Eastern Goldfields.
- Capacitive:Sensors measure dielectric property variations to distinguish ore grades without sample destruction.
- Acoustic:Vibration analysis identifies mineral density differentials in slurry streams for process control feedback.
Established installations favor Electromagnetic detection. Optical technology is climbing the fastest as flotation optimization demands intensify.
Application:
Use case segmentation tracks how collector deployment shifts from discovery-phase geology through production-phase metal recovery.
- Metal Detection:Core application spanning handheld field units to integrated concentrator circuits, with demand scaling directly to ore throughput volumes. Peru's copper expansion pipeline and Chile's existing operations anchor consumption as both jurisdictions tighten aquatic toxicity regulations.
- Mineral Exploration:Early-stage targeting workflows employ portable electromagnetic and acoustic systems to prioritize drill programs. Kazakhstan's Bozshakol modernization and Australia's greenfields programs are absorbing equipment as state geological surveys release new tenure blocks.
- Geological Surveying:Academic and government mapping programs utilize handheld collectors for regional mineral inventory compilation.
- Environmental Monitoring:Tailings stream analysis and watershed compliance verification are emerging specifications under Australia's progressive rehabilitation bond requirements.
Metal Detection retains the largest installed base. Environmental Monitoring represents the steepest expansion trajectory as effluent regulations proliferate.
End User:
Procurement authority is migrating from site metallurgists to corporate sustainability officers, reshaping vendor relationships across customer categories.
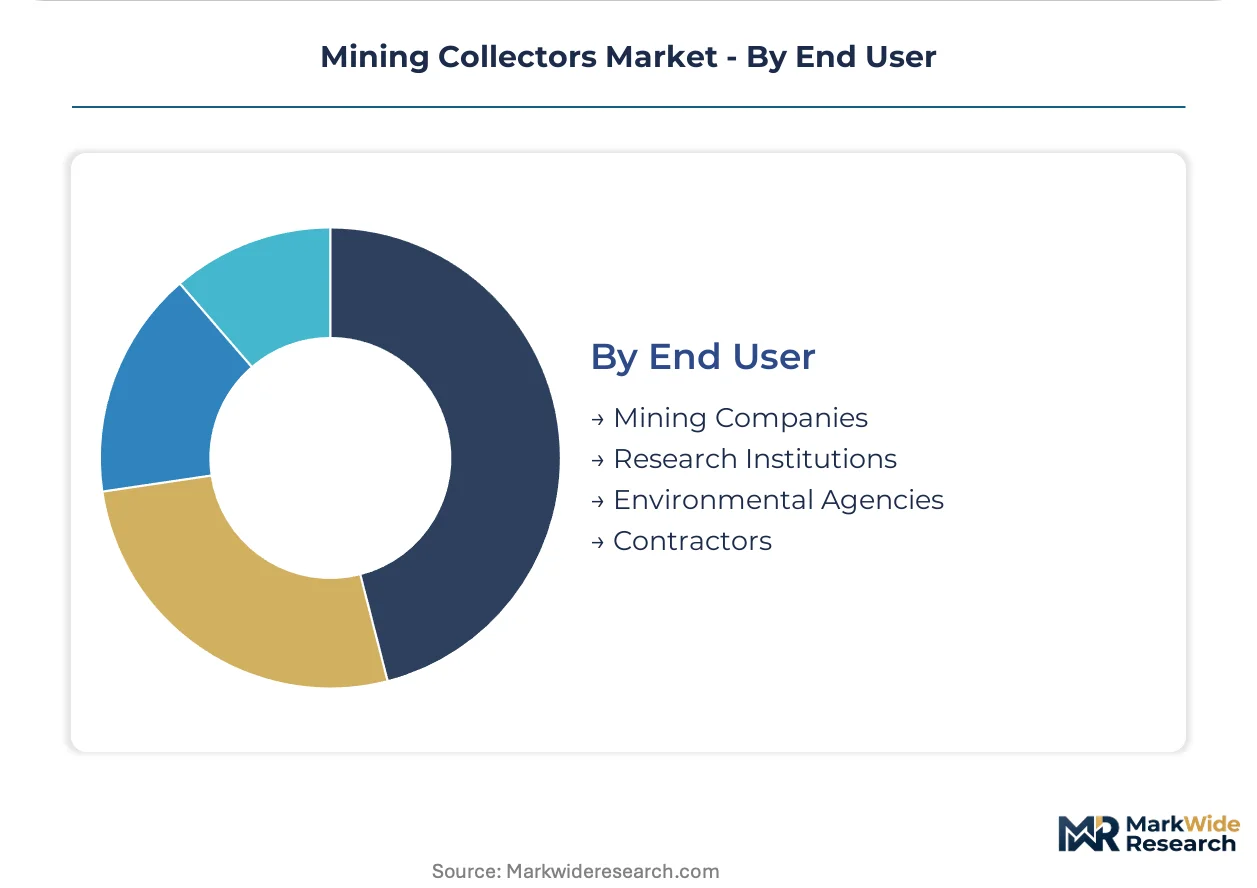
- Mining Companies:Tier-one operators including Chile's Codelco now centralize collector sourcing under sustainability frameworks that mandate biodegradability data sheets. Total cost of environmental compliance has displaced unit pricing as the primary selection criterion in tender evaluations.
- Contractors:Specialist flotation and exploration service providers supply equipment and expertise to junior miners lacking in-house metallurgical capability. These intermediaries are consolidating procurement leverage across multiple client sites in Peru's southern copper belt.
- Research Institutions:Universities and national laboratories pilot alternative collector chemistries and sensor integration prototypes.
- Environmental Agencies:Regulators including Chile's SMA and Australia's Department of Climate Change are acquiring monitoring equipment to verify concentrator discharge compliance.
Procurement concentration rests with Mining Companies. Contractor engagement is gaining share fastest as junior operators outsource technical capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Zona Franca de Iquique tax-incentive zone concentrates collector manufacturing capacity serving the Atacama copper belt. Australian and Peruvian mining corridors absorb premium reagent volumes as ore grades decline. Kazakhstan's modernization programs are opening new demand centers for high-salinity-compatible formulations.
Chile
Codelco's Andina and El Teniente divisions drive concentrated demand for thionocarbamate alternatives to legacy xanthate chemistries. The SMA enforces water discharge mandates that restrict residual collector limits in Andean watershed concentrators. Antofagasta and Calama host the densest cluster of copper flotation circuits where biodegradability data sheets are now mandatory tender requirements.
Australia
Pilbara iron ore and Eastern Goldfields base metal operations specify automated collector systems from commissioning to preempt compliance costs. The Department of Climate Change, Energy, the Environment and Water mandates progressive rehabilitation bonds tied to chemical management plans. Perth-based procurement offices now pre-qualify collectors against aquatic toxicity benchmarks before pilot testing.
Peru
Southern copper belt expansion projects are specifying low-toxicity collectors from initial design, bypassing legacy chemical transitions. The Ministry of Energy and Mines requires environmental impact assessments that document reagent fate in tailings streams. Arequipa and Tacna concentrate new concentrator construction where contractors consolidate procurement leverage across multiple client sites.
Kazakhstan
Kounrad and Bozshakol copper operations modernize Soviet-era concentrators with collectors compatible with high-salinity process water. The national mining regulator mandates technology upgrades as a condition of license renewal. The Karaganda region anchors industrial chemical demand where state geological surveys are releasing new tenure blocks for exploration.
China
Shandong and Jiangsu provinces concentrate bulk xanthate manufacturing capacity that supplies non-integrated buyers across Asia-Pacific. The Ministry of Ecology and Environment suspends export licenses during environmental compliance campaigns, creating supply volatility. Qingdao and Shanghai host blending facilities that reduce lead times for remote mining camps in Mongolia and Southeast Asia.
Mining Collectors Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated producers commanding bulk commodity flows and technology-integrated platforms capturing margin pools. The vendor base organizes around three archetypes: Southern African integrated manufacturers with captive feedstock control, Australian specialists in dithiophosphate tailoring, and global logistics operators with regional blending networks. Competitive moves concentrate on backward integration into carbon disulfide supply and predictive dosage algorithm development.
Among Southern African integrated producers, Senmin International Limited anchors the bulk xanthate tier through manufacturing footprint concentration. Australian specialists exemplified by Coogee Chemicals Pty Limited occupy positions in dithiophosphate customization for base metal circuits. Global logistics scale sits with SNF FloMin Inc., which represents the regional blending facility archetype reducing lead times to remote mining camps.
| Leading Market Players |
|---|
| Senmin International Limited |
| Coogee Chemicals Pty Limited |
| SNF FloMin Inc. |
| Orica Ltd |
| CTC Mining |
| Vanderbilt Chemicals, LLC |
| Tieling Flotation Reagents Co., Ltd |
| QiXia TongDa Flotation Reagent Co., Limited |
| Celtic Chemicals |
| Others |
Value Chain & Pricing Dynamics
Codelco's centralized biodegradability data sheet requirements for all collector tenders are compressing approved supplier lists and forcing non-integrated manufacturers to absorb certification costs or exit premium contract tiers. This procurement consolidation shifts pricing power toward integrated producers with captive carbon disulfide supply and in-house environmental testing capabilities.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Australian Pilbara operators and Chilean concentrators pay 15-25% markups over spot pricing for guaranteed delivery within 72 hours. Three-tier pricing structure across premium certified, standard industrial, and economy spot tiers reflects ISO 14001 certification status and volume commitment scale. Cost compression in economy-grade xanthate is intensifying because Chinese export license suspensions force spot buyers into distressed procurement. Artisanal geological teams in Kazakhstan exhibit highest price sensitivity, while Codelco's centralized sustainability procurement shows least elasticity.
Supply Chain Analysis
Xanthate synthesis rests on carbon disulfide feedstock drawn from Shandong and Jiangsu petrochemical corridors in China, with thionocarbamate alternatives sourcing specialty amines from German and Belgian chemical producers. Sodium hydroxide, sulfur, and C2-C6 alcohols constitute secondary input dependencies. Single-source vulnerability concentrates in Chinese export license regimes that suspend bulk reagent flows during environmental compliance campaigns. Distribution runs through regional blending facilities in Qingdao, Perth, and Antofagasta that reduce lead times to remote mining camps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mining collectors sector sits in a technology-transition phase as automated sensor-integrated platforms displace conventional bulk reagent delivery systems. Predictive dosage algorithms trained on historical flotation data are substituting for experienced froth stability diagnosticians.
For Market Incumbents: Anticipate accelerated procurement consolidation by centralizing biodegradability certification capabilities and securing backward integration into carbon disulfide supply. Threat of Chinese manufacturing concentration disrupting non-integrated buyers creates leverage for regional blending network expansion. Priority lever: predictive algorithm development partnerships with concentrator automation vendors.
For New Entrants and Emerging Players: Begin with Kazakhstan's high-salinity-compatible formulation gap as the most penetrable white-space target, where Soviet-era concentrator modernization lacks established supplier relationships. Environmental monitoring equipment for tailings stream compliance verification offers secondary entry point under Australia's progressive rehabilitation bond mandates. Go-to-market angle: machine learning dosage optimization bundled with sensor hardware.
For Investors and Strategic Acquirers: The window for entry favors technology-integrated platforms combining capacitive detection with closed-loop reagent control over commodity xanthate manufacturers facing margin compression. Long-term viability clusters in predictive dosage algorithm developers with concentrator pilot data libraries. Signal to watch: Codelco tender awards shifting from unit pricing to total cost of environmental compliance metrics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Disulfide | Senmin's Southern African captive feedstock control insulates margins from petrochemical volatility. |
| Predictive Dosage Algorithm Development | Machine learning models trained on Codelco flotation data enable closed-loop reagent optimization. |
| Regional Blending Facility Expansion | Perth and Antofagasta hubs reduce lead times for Australian and Chilean concentrator procurement. |
| Biodegradability Certification Investment | ISO 14001 compliance functions as de facto market access requirement for tier-one mining houses. |
| High-Salinity Formulation Development | Kazakhstan's Kounrad and Bozshakol operations demand collectors compatible with elevated process water salinity. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with concentrator metallurgists, procurement officers at Chilean state-owned mining operations, flotation reagent R&D directors, and environmental compliance managers at Australian Department of Climate Change. Chile's SMA discharge permit databases, Australian progressive rehabilitation bond documentation, and Peruvian Ministry of Energy and Mines environmental impact assessments provided regulatory validation. Bottom-up concentrator consumption estimates triangulated against top-down chemical import flows.
Data-stream reconciliation across product type, technology, application, and end-user segmentation dimensions modeled volume and value trajectories across the projection horizon. CAGRs derived from historical reagent intensity per ton of copper equivalent output, overlaying ore grade decline curves and regulatory substitution mandates. Forecast inputs incorporated sensor-based automation adoption rates and biodegradable formulation penetration thresholds in Andean watershed concentrators.
Underlying measurement precision varies by segment; automated systems and environmental monitoring applications carry tighter precision than handheld collector estimates given concentrated vendor disclosure. Forecasts reflect assumptions around SMA enforcement intensity and Chinese export license stability. Regulatory suspension events, carbon disulfide price spikes, and flotation chemist training program effectiveness warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Logging Cable Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Mining Tester Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Drill Pipe Market