
 Global Microgrid As a Service Market | 2026-2036
Global Microgrid As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microgrid As a Service Market Outlook
Utility-grade resiliency specifications is redrawing competitive boundaries in the Global Microgrid As a Service Market. Eaton leverages its power management heritage to anchor large-scale campus deployments across North America. Siemens AG competes through digital twin integration for predictive microgrid operations, while Schneider Electric differentiates via end-to-end automation platforms that span design through remote maintenance.
Microgrid As a Service denotes a contractual arrangement where third-party providers finance, build, and operate localized energy systems incorporating distributed generation, battery storage, and intelligent load management, typically configured for islanding capability below 50 MW capacity. The primary purpose centers on delivering guaranteed uptime and cost-predictability to entities lacking capital budgets or in-house electrical engineering depth. Among service types, Operations and Maintenance commands recurring revenue streams with the stickiest customer relationships, while Hybrid deployment types are gaining fastest as organizations seek flexibility between grid-tied economics and blackout resilience. Energy Storage technology within the stack is where margin pools concentrate, given the specialized integration expertise required for lithium-ion cycling optimization and thermal management.
The US Federal Energy Regulatory Commission shapes interconnection standards that determine market access for behind-the-meter microgrid operators, while the EU F-Gas Regulation constrains cooling system choices for battery enclosures in European deployments. India's Central Electricity Authority mandates technical standards for distributed generation connectivity that directly influence system design parameters for service providers. Stakeholders must monitor how evolving carbon border mechanisms and domestic content requirements across multiple jurisdictions reshape the cost structure of imported storage hardware versus locally assembled alternatives.
Market Dynamics
The US Inflation Reduction Act tax credits for distributed energy storage are compressing payback periods for third-party microgrid operators, forcing incumbent utilities to defend their commercial and industrial customer base through accelerated rate restructuring.
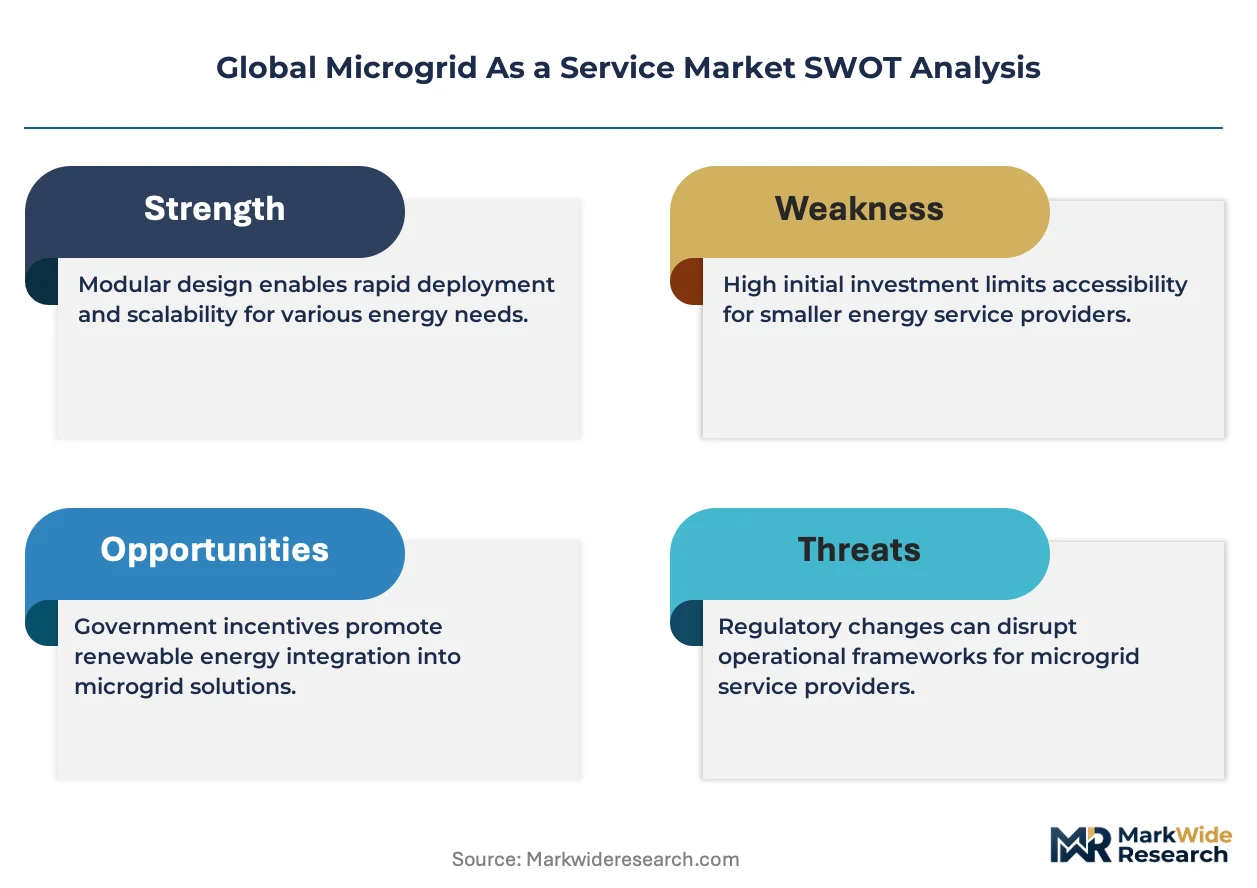
Growth Catalysts
- Rural electrification mandates:India's state-level renewable purchase obligations are compelling distribution utilities to contract private microgrid operators for village-scale deployments, bypassing centralized grid extension timelines.
- FERC Order 2222:This US Federal Energy Regulatory Commission directive enables aggregated distributed energy resources to participate in wholesale markets, opening revenue stacking opportunities for behind-the-meter microgrid fleets.
- Lithium-ion cycling optimization:Advances in battery management systems are extending asset life beyond 6,000 cycles, improving unit economics for energy storage-heavy service contracts.
Market Restraints
- Critical mineral concentration:Cathode active material supply chains concentrate in China and the Democratic Republic of Congo, exposing operators to cobalt and lithium hydroxide price volatility and export restriction risk.
- Interconnection queue delays:US regional transmission organizations are processing distributed generation interconnection requests with 18-36 month backlogs, compressing project IRRs and deterring capital deployment.
- F-Gas Regulation constraints:The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in battery thermal management systems, forcing European operators to redesign enclosure cooling architectures at elevated cost.
Strategic Opportunities
- Data center microgrids:Hyperscale cloud operators in Northern Virginia and Frankfurt are procuring guaranteed uptime contracts that bundle renewable generation with islanding capability, bypassing traditional utility reliability commitments.
- EU Green Deal taxonomy alignment:Microgrid-as-a-Service contracts structured around renewable-plus-storage configurations qualify for green financing instruments, lowering weighted average cost of capital for European deployments.
- Peer-to-peer energy trading platforms:Blockchain-enabled settlement layers are converging with microgrid control systems, enabling campus and residential developments to monetize surplus generation through automated bilateral contracts.
Industry Challenges
- Power systems integration expertise:The shortage of engineers proficient in both protection relay coordination and inverter-based resource modeling is extending commissioning timelines and elevating labor costs for complex hybrid deployments.
- Legacy SCADA interoperability:Industrial facilities with aging supervisory control infrastructure require costly protocol translation layers to integrate modern microgrid controllers, eroding project margins for retrofit-focused service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microgrid As a Service Market |
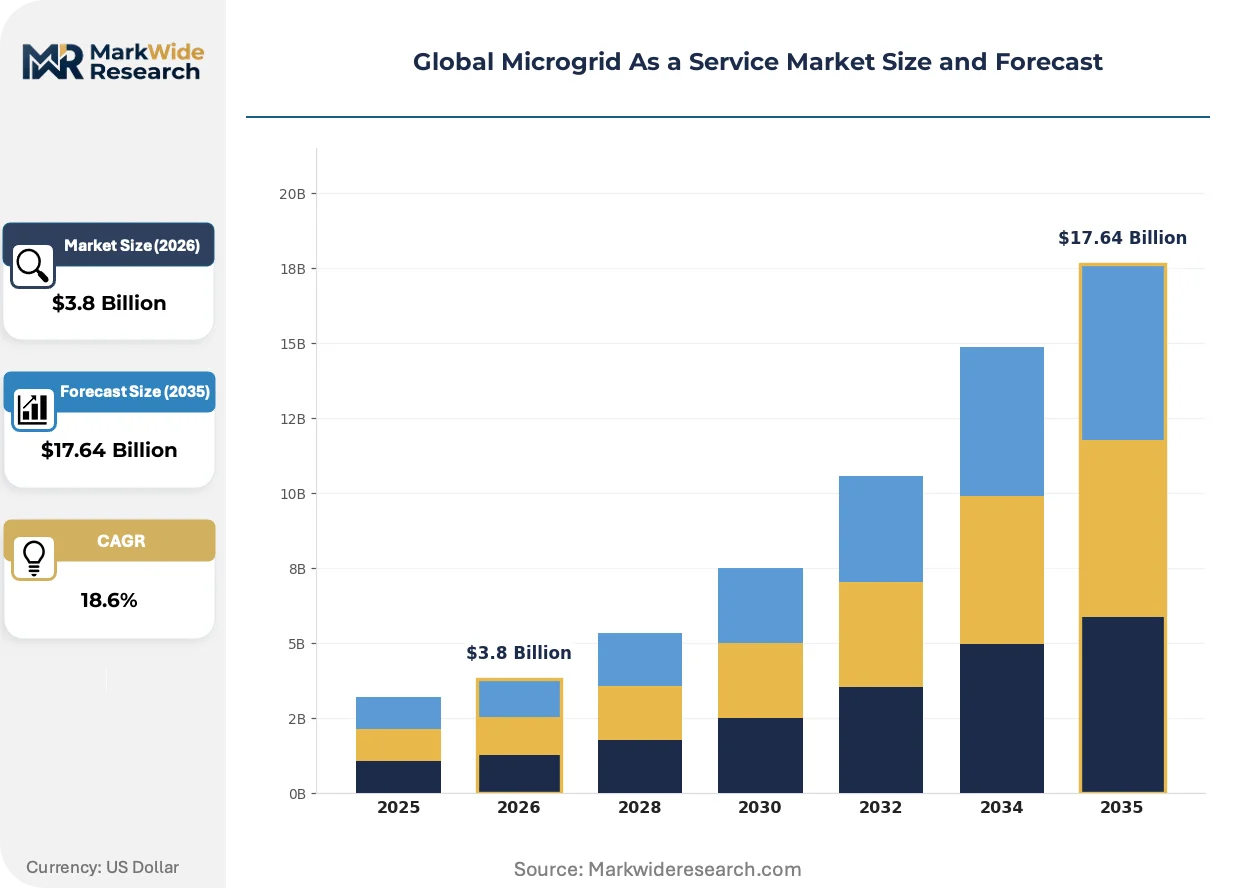
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Capacity Planning, System Design, Operations, Maintenance End User: Educational Institutions, Military Bases, Remote Communities, Industrial Facilities Deployment Type: On-Premises, Off-Grid, Hybrid, Grid-Connected Technology: Solar PV, Wind Turbines, Energy Storage, Smart Controllers |
| Companies Covered | Eaton, ABB, General Electric, Schneider Electric, Siemens AG, NRG Energy, Spirae, Younicos, Pareto Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microgrid As a Service Market Strategic Shifts
Software-defined architectures are displacing hardware-centric control systems across the microgrid stack, compressing commissioning cycles and enabling remote reconfiguration without truck rolls.
Containerized battery energy storage systems with integrated power conversion are decomposing the traditional engineering-procurement-construction model for microgrid deployment. Data center operators in Texas and Arizona are procuring these factory-integrated blocks on 12-week lead times rather than 18-month custom builds. This modularity is compressing the addressable market for site-specific electrical engineering services and shifting margin pools toward system integrators with manufacturing partnerships.
The EU F-Gas Regulation is mandating transition to natural refrigerants and passive cooling designs for battery enclosures in European deployments. This policy is elevating enclosure costs by 15-25 percent while extending thermal design timelines. German and Dutch microgrid operators are responding by sourcing pre-certified battery blocks from suppliers with established European manufacturing footprints to avoid customs delays and technical conformity reassessment.
Commercial and industrial buyers are unbundling long-term service contracts into discrete performance guarantees for uptime, fuel cost predictability, and carbon intensity. This decomposition is displacing the traditional all-inclusive operations and maintenance tariff with itemized service level agreements. The shift is most visible in California and New York, where large manufacturing campuses are negotiating separate contracts for asset ownership, dispatch optimization, and renewable energy credit monetization.
Global Microgrid As a Service Market Segmentation
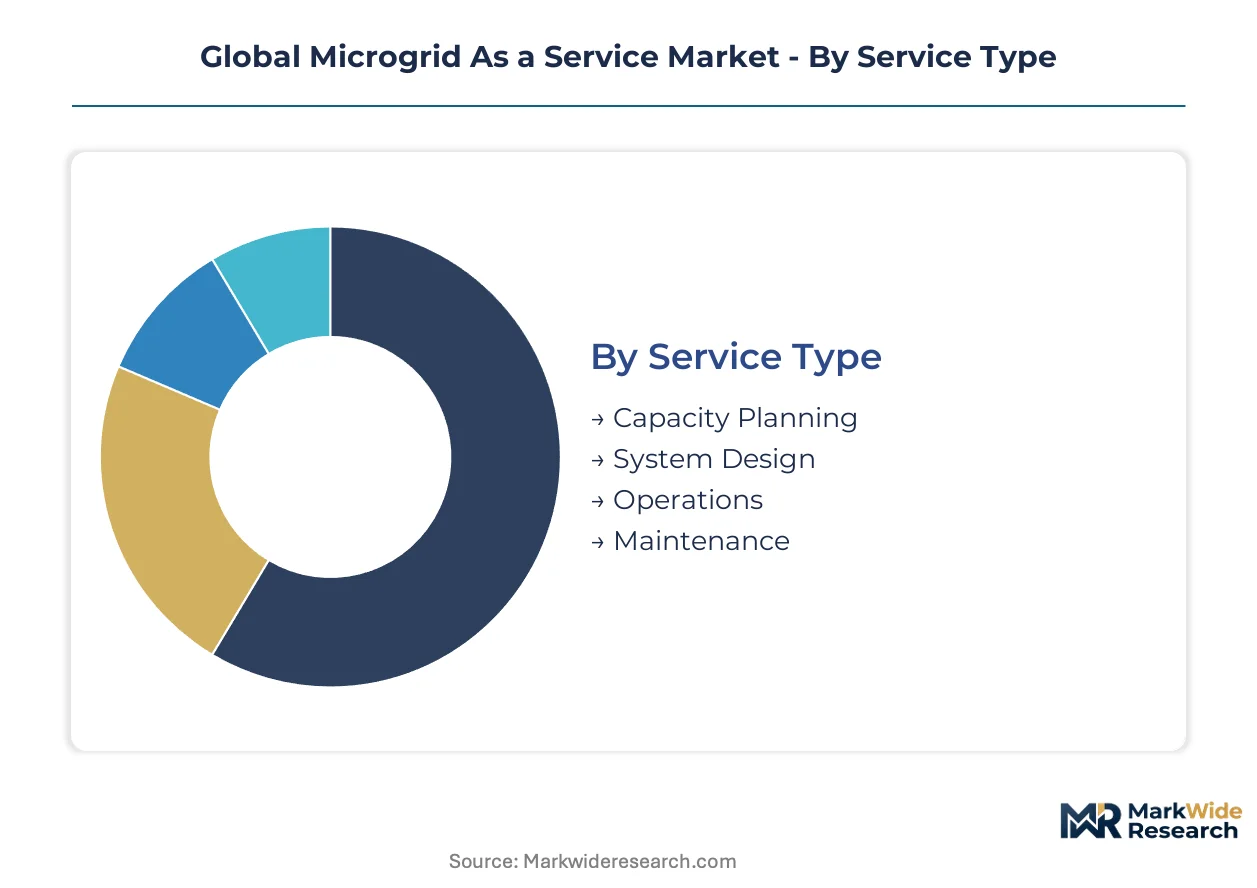
Microgrid As a Service providers structure their offerings across four distinct dimensions that determine contract economics and operational complexity. Service type dictates revenue recognition patterns, while deployment architecture shapes capital deployment and regulatory exposure. End user verticals concentrate demand in geographically specific clusters, and technology mix determines supply chain vulnerability and margin profiles.
Service Type:
Domestic service contracts dominate capacity planning and system design, while operations and maintenance revenue streams increasingly cross borders as providers scale fleet management platforms internationally.
- Operations:Recurring revenue contracts center on dispatch optimization, fuel procurement, and islanding event response. Data center operators in Northern Virginia and hyperscale campuses in Frankfurt are unbundling these services from asset ownership, seeking guaranteed uptime SLAs without balance sheet commitment. FERC Order 2222 compliance adds wholesale market participation as a service layer.
- Maintenance:Predictive service models leverage battery management system telemetry to schedule module replacements before degradation impacts reliability. India's rural electrification programs are driving village-scale maintenance contracts through state distribution utility tenders, bypassing centralized grid extension timelines. CEA technical standards mandate specific response time commitments.
- Capacity Planning:Load forecasting and generation sizing services anchor initial contract phases, typically bundled with financing structures.
- System Design:Engineering-procurement-construction specifications translate customer resilience requirements into equipment procurement packages.
Operations commands the established base. The steepest expansion runs through maintenance.
End User:
Cost tier stratification separates premium uptime guarantees for mission-critical facilities from standardized service levels for remote electrification programs.
- Military Bases:Resilience specifications mandate islanding capability below 50 MW with cyber-hardened control systems. US Department of Defense installations across Texas, California, and Hawaii are accelerating power-as-a-service procurement to meet federal energy security directives without capital appropriation cycles. Contracts bundle renewable generation with blackstart capability.
- Industrial Facilities:Manufacturing campuses prioritize cost predictability over premium uptime, negotiating fuel pass-through structures and renewable energy credit monetization as separate service modules. German automotive suppliers and Dutch chemical processors are segmenting contracts across asset ownership, dispatch optimization, and carbon accounting.
- Educational Institutions:University microgrids emphasize sustainability metrics and student engagement platforms alongside reliability guarantees.
- Remote Communities:Village-scale deployments in India and sub-Saharan Africa rely on mobile payment integration and community ownership structures.
Military bases anchor premium contract values. Remote communities are climbing the fastest as development finance institutions scale pay-as-you-go models.
Deployment Type:
Application context determines architecture selection, with grid-tied economics dominating commercial and industrial sites while islanding capability commands defense and healthcare premiums.
- Hybrid:Configurations combining grid-tied operation with intentional islanding capability are gaining fastest as organizations seek flexibility between wholesale market participation and blackout resilience. Containerized battery blocks with integrated power conversion enable 12-week deployment timelines versus 18-month custom builds. Texas and Arizona data center clusters are standardizing on this architecture.
- Grid-Connected:Behind-the-meter installations optimize for demand charge reduction and wholesale market revenue stacking. FERC interconnection queue delays of 18-36 months are compressing project IRRs and pushing providers toward pre-certified equipment packages.
- On-Premises:Dedicated infrastructure serving single-facility loads requires full capital commitment from service providers.
- Off-Grid:Fully autonomous systems serve remote mining camps and island communities where grid extension is economically prohibitive.
Grid-connected deployments hold the installed base. Hybrid configurations are expanding most quickly as buyers hedge against interconnection uncertainty.
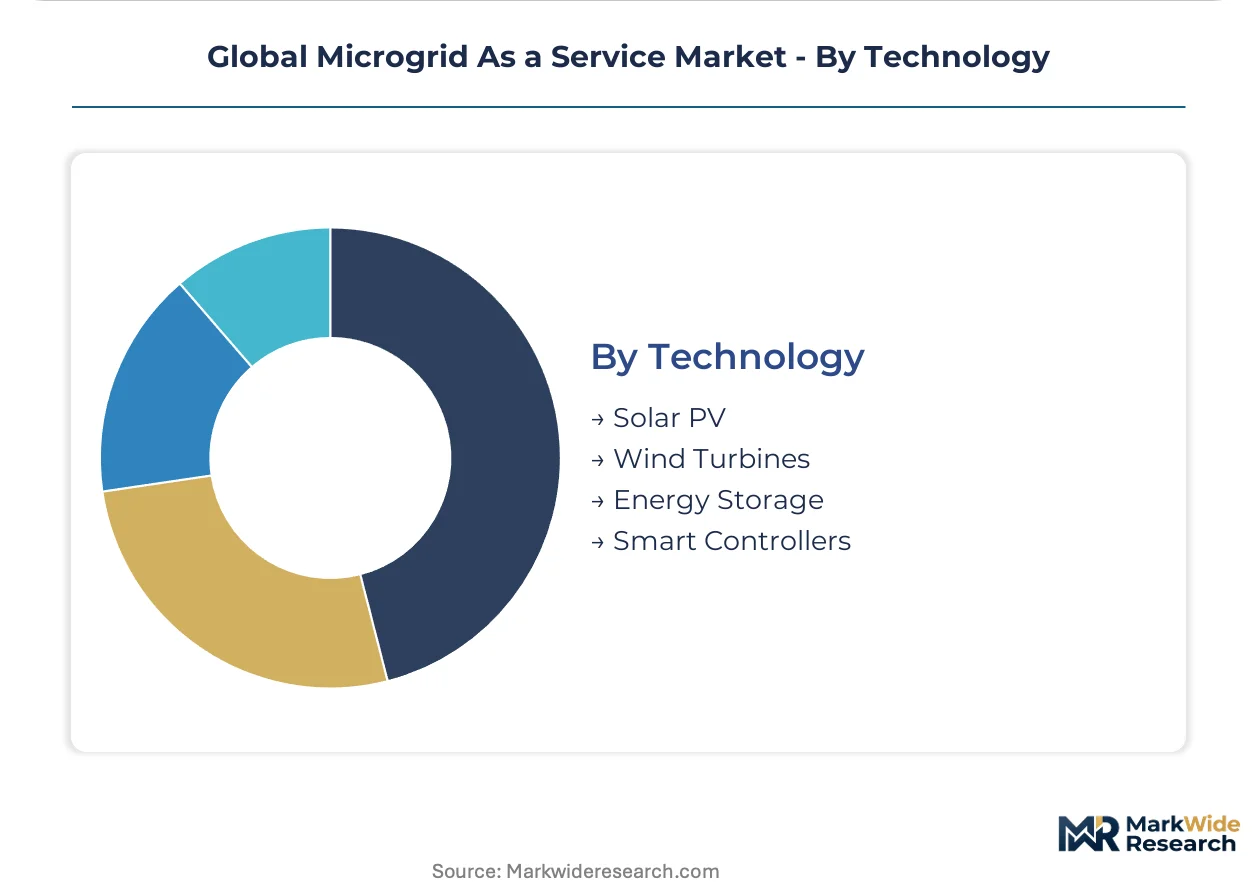
Technology:
Margin concentration varies sharply across the technology stack, with energy storage integration commanding specialized expertise premiums while solar PV commoditizes rapidly.
- Energy Storage:Lithium-ion cycling optimization and thermal management represent the highest-margin service layer, requiring expertise in battery management systems, fire suppression, and F-Gas Regulation compliance for European deployments. German and Dutch operators are sourcing pre-certified blocks from suppliers with established EU manufacturing footprints to avoid technical conformity reassessment.
- Smart Controllers:Software-defined architectures displace hardware-centric control systems, compressing commissioning cycles and enabling remote reconfiguration. Legacy SCADA interoperability requirements at industrial facilities extend timelines and elevate integration costs.
- Solar PV:Module procurement and string inverter configuration are standardizing rapidly, compressing engineering margins.
- Wind Turbines:Small-scale distributed wind sees limited adoption outside specific resource-rich coastal and plains locations.
Energy storage commands technology stack margins. Smart controllers are gaining share fastest as digital twin integration becomes a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microgrid As a Service deployment patterns reflect divergent import dependencies for battery hardware and control electronics. Markets with domestic manufacturing footprints command procurement advantages, while import-reliant regions absorb longer lead times and customs conformity costs.
United States
Defense installations across Texas, California, and Hawaii are accelerating power-as-a-service procurement under federal energy security directives. FERC Order 2222 enables aggregated distributed energy resources to participate in wholesale markets, opening revenue stacking opportunities for behind-the-meter operators. Northern Virginia data center clusters are procuring guaranteed uptime contracts that bundle renewable generation with islanding capability.
Germany
Automotive suppliers and chemical processors are segmenting contracts across asset ownership, dispatch optimization, and carbon accounting. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in battery thermal management, forcing enclosure redesign at elevated cost. Frankfurt hyperscale campuses are standardizing on hybrid microgrid architectures with 12-week deployment timelines.
India
State-level renewable purchase obligations are compelling distribution utilities to contract private operators for village-scale deployments. The Central Electricity Authority mandates technical standards for distributed generation connectivity that directly influence system design parameters. Rural electrification programs in Maharashtra and Gujarat are driving mobile payment-integrated service models.
Netherlands
Industrial facilities prioritize cost predictability over premium uptime, negotiating fuel pass-through structures as separate service modules. EU Green Deal taxonomy alignment qualifies renewable-plus-storage configurations for green financing instruments. Dutch operators are sourcing pre-certified battery blocks from suppliers with established European manufacturing footprints.
Japan
Grid-tied installations optimize for demand charge reduction amid constrained interconnection capacity. METI standards govern inverter-based resource integration for commercial and industrial behind-the-meter systems. Manufacturing campuses in the Kansai region are unbundling long-term contracts into discrete performance guarantees for uptime and carbon intensity.
Global Microgrid As a Service Market Competitive Environment
Concentration sits with diversified electrical equipment conglomerates that anchor large-scale campus and defense deployments. The vendor base spans power management specialists, automation platform providers, and digital twin integrators competing through differentiated control architectures. Three archetypes dominate: heritage electrical manufacturers with protection relay expertise, software-centric operators leveraging predictive analytics, and energy service companies stacking wholesale market revenues. Competitive moves center on manufacturing partnerships for containerized battery blocks and fleet management platform scaling.
Within the heritage electrical tier, Eaton leverages its power management lineage for North American campus deployments. Siemens AG competes through digital twin integration for predictive operations, while Schneider Electric anchors end-to-end automation platforms spanning design through remote maintenance. These three conglomerates exemplify the strategic divergence between hardware-centric and software-defined microgrid control philosophies.
| Leading Market Players |
|---|
| Eaton |
| ABB |
| General Electric |
| Schneider Electric |
| Siemens AG |
| NRG Energy |
| Spirae |
| Younicos |
| Pareto Energy |
| Others |
Value Chain & Pricing Dynamics
FERC Order 2222 compliance certification gates both supplier qualification and contract price tiers simultaneously, forcing third-party operators to absorb interconnection engineering costs upfront while passing through wholesale market participation premiums to data center buyers in Northern Virginia and hyperscale campuses in Frankfurt.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium contracts bundle guaranteed uptime SLAs with cyber-hardened control systems for military installations, while standard tiers optimize for fuel pass-through predictability at manufacturing campuses. Cost compression in the standard tier intensifies as containerized battery blocks commoditize integration services. Data center operators exhibit the lowest price sensitivity, prioritizing islanding capability over per-kWh economics.
Supply Chain Analysis
Strait of Malacca transit underwrites lithium hydroxide feedstock security for cathode active material producers, exposing European operators to shipping disruption cascades. Cathode chemistry draws from concentrated processing capacity in China, South Korea, and Japan. Cobalt sulfate sourcing rests on extraction exposure in the Democratic Republic of Congo. Single-source vulnerability in battery management system firmware creates qualification bottlenecks. Distribution runs through certified system integrators with established manufacturing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microgrid-as-a-Service contracts build defensive moats through regulatory entrenchment, as FERC interconnection standards and EU F-Gas compliance create multi-year certification barriers that lock out unqualified competitors.
For Market Incumbents: Fortify fleet management platform scale by acquiring predictive analytics specialists with digital twin capabilities. Deepen backward integration into containerized battery block assembly through manufacturing partnerships in Texas and Arizona. Eaton and Siemens AG must defend against software-centric entrants by embedding protection relay expertise into subscription-based remote monitoring tiers. For New Entrants and Emerging Players: Anchor in India's village-scale electrification programs, where state distribution utility tenders bypass centralized grid extension timelines and reward mobile payment-integrated service models. Target maintenance-only contracts for existing hybrid deployments, unbundling from asset-heavy incumbents. Pursue EU Green Deal taxonomy alignment to access green financing instruments for renewable-plus-storage configurations. For Investors and Strategic Acquirers: FERC Order 2222 wholesale market participation rules reshape the acquisition landscape toward operators with aggregated distributed energy resource portfolios. Long-term viability hinges on software-defined control architectures that compress commissioning cycles. Target microgrid operators with established manufacturing partnerships for factory-integrated battery blocks. Watch interconnection queue clearance rates as the inflection signal for capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Containerized Battery Block Manufacturing Partnership | Compresses deployment timelines from 18-month custom builds to 12-week factory integration for Texas data center clusters. |
| Digital Twin Platform Integration | Enables predictive microgrid operations through Siemens AG's real-time simulation layers for Frankfurt hyperscale campuses. |
| FERC Order 2222 Compliance Investment | Unlocks wholesale market revenue stacking for behind-the-meter fleets through aggregated distributed energy resource participation. |
| EU F-Gas Regulation Thermal Redesign | Forces natural refrigerant transition in battery enclosures, elevating costs 15-25 percent for German automotive supplier contracts. |
| Mobile Payment-Integrated Service Model | Aligns with India's rural electrification programs in Maharashtra and Gujarat through community ownership structures. |
Study Parameters
The analysis maps service type segmentation across operations, maintenance, capacity planning, and system design, each validated through primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation draws from FERC filings, EIA project development databases, IEA renewable integration reports, and EU F-Gas Regulation implementation guidance. Bottom-up capacity deployment estimates triangulate against top-down addressable market sizing across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models deployment type, technology stack composition, end-user vertical, and regional regulatory framework as core segmentation dimensions. CAGRs derive from installed base evolution and replacement cycle analysis. Forecast inputs incorporate lithium-ion cycling degradation curves and interconnection queue clearance assumptions without year-specific milestones.
Material uncertainties — critical mineral export restrictions, FERC interconnection standard revisions, and EU carbon border mechanism expansions — sit outside the modeled envelope. Forecasts reflect documented assumptions about battery cost trajectories and wholesale market participation rates. Practitioners should keep alternative scenarios live as India's renewable purchase obligation enforcement and US defense procurement acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
Smart Microgrid Market
Smart Grid
North America Microgrid Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Smart Grid Network Market
Smart Grid
Smart Demand Response Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
North America Smart Grid Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
Smart Grid Market
Smart Grid
Asia-Pacific Smart Grid Network Market