
 Mixers and Attachments Market | 2026-2036
Mixers and Attachments Market Size, Share, and Industry Trends Forecast 2026-2036
Mixers and Attachments Market Foresight
Equipment leasing and pay-per-use financing for commercial-grade mixers is reconfiguring capital deployment across mid-scale foodservice operations. KitchenAid leverages its brand heritage and direct-to-consumer channel control to sustain premium pricing in the household segment. Groupe SEB anchors European commercial demand through Hobart's institutional footprint, while Midea Group competes on manufacturing scale to occupy cost-sensitive Asian markets.
Mixers and attachments comprise motorized base units with variable-speed drivetrains and interchangeable tooling designed to homogenize, aerate, or develop gluten structures in food substrates, typically operating at 50–60 Hz with thermal overload protection and planetary or spiral mixing action. Stand mixers and immersion blenders lead product type revenue due to cross-utilization in both household and professional settings, while dough hooks and mixing bowls capture recurring attachment sales from wear and hygiene replacement cycles. Commercial-grade power ratings command the highest margin pools as NSF-listed stainless steel construction and continuous-duty motors differentiate institutional procurement specifications.
NSF International standards, FDA Food Code provisions, and EU Machinery Directive 2006/42/EC compliance requirements shape material selection, guarding design, and sanitation protocols across export-oriented manufacturers. CE marking and ETL sanitation certifications function as gatekeeping mechanisms for market access in Europe and North America respectively. Stakeholders must monitor evolving energy efficiency thresholds and right-to-repair legislation as these frameworks increasingly influence motor specification and attachment interoperability design decisions.
Market Dynamics
NSF International's tightening sanitation standards are forcing stainless steel specification upgrades across North American supply chains, compressing margin structures for mid-tier manufacturers while creating certification premiums for compliant producers.
Growth Catalysts
- Commercial bakery throughput mandates:United States operators are expanding planetary stand mixer fleet purchases to meet production volume requirements. Equipment leasing models lower capital barriers for mid-scale foodservice entrants.
- EU Machinery Directive 2006/42/EC compliance:CE marking requirements are standardizing guarding design and motor thermal protection across export-oriented manufacturers, reducing technical trade friction.
- German industrial baking clusters:Munich and Stuttgart concentration drives premium attachment replacement cycles, with stainless steel dough hooks and mixing bowls capturing recurring hygiene-driven sales.
Market Restraints
- Copper and rare-earth magnet cost volatility:Motor winding materials face commodity price swings that compress manufacturing margins and complicate long-term contract pricing.
- Asian component concentration:Variable-speed drivetrain subassemblies rely heavily on China-based suppliers, exposing procurement timelines to geopolitical disruption risk.
- Right-to-repair legislative friction:Emerging interoperability mandates in multiple jurisdictions threaten proprietary attachment locking mechanisms and recurring revenue streams.
Strategic Opportunities
- Pay-per-use financing penetration:Equipment-as-a-service models remain underdeveloped in mid-scale European foodservice, offering first-mover advantage to capital-light entrants.
- Energy efficiency threshold acceleration:EPA and EU Ecodesign tightening creates upgrade demand for continuous-duty motor replacements in institutional kitchens.
- Smart torque sensing convergence:IoT-enabled overload protection is hybridizing with traditional thermal cutoffs, enabling predictive maintenance contracts in high-throughput bakeries.
Industry Challenges
- NSF/ETL certification timeline compression:Sanitation listing procedures for new stainless steel grades extend product launch windows by 8-14 months, straining R&D pipeline velocity.
- Legacy planetary mixer integration complexity:Food manufacturers face retrofit friction when attaching smart monitoring systems to 20-30 year old Hobart and KitchenAid base units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixers and Attachments Market |
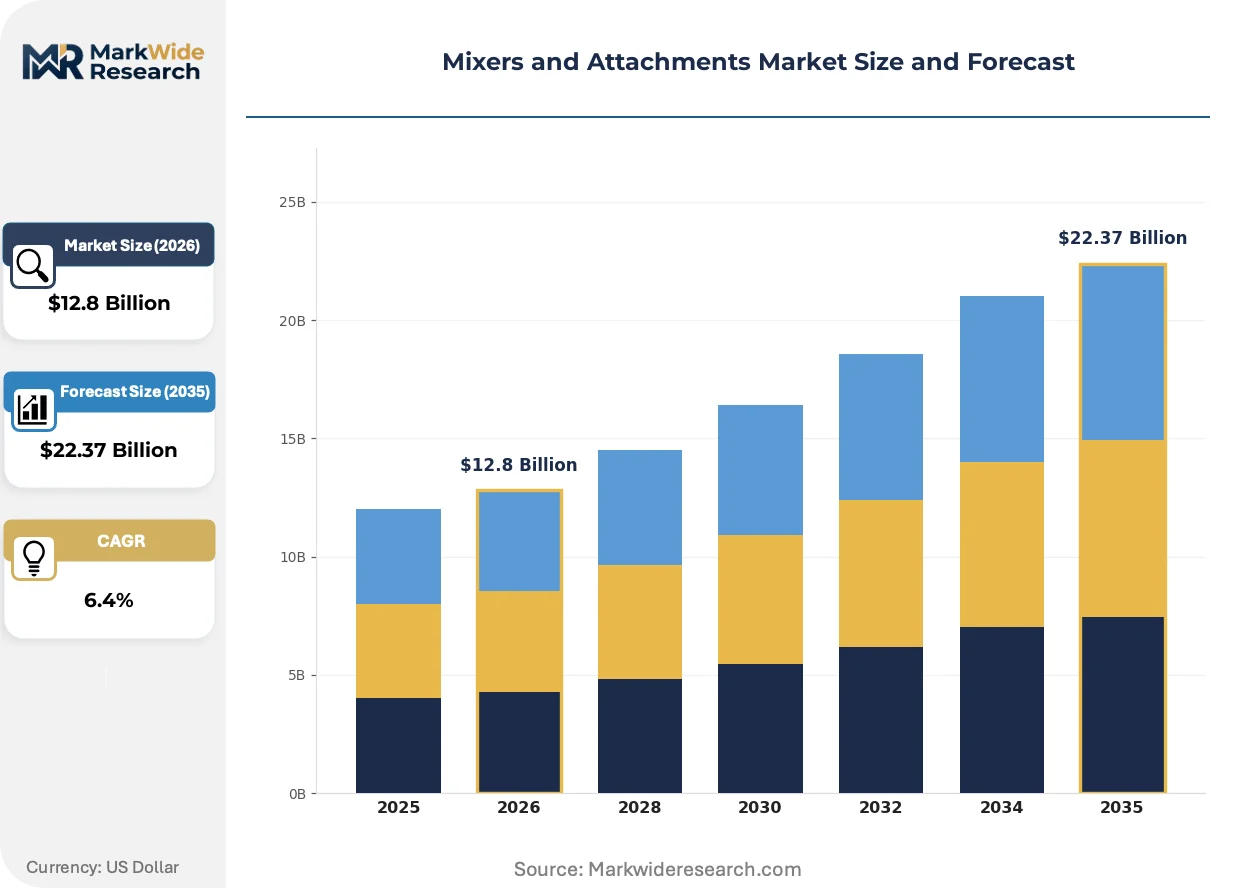
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Mixers, Stand Mixers, Immersion Blenders, Food Processors Attachment Type: Dough Hooks, Whisks, Mixing Bowls, Blender Jars End User: Households, Restaurants, Catering Services, Bakeries Power Rating: Low Power, Medium Power, High Power, Commercial Grade |
| Companies Covered | KitchenAid, Whirlpool Corporation, Groupe SEB, ITW Food Equipment Group (Hobart), Philips (Versuni), Midea Group, Electrolux AB, Breville Group, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixers and Attachments Market Shifts & Advancements
Three interconnected shifts are reconfiguring competitive advantage: motor-drivetrain electrification, regulatory-driven material substitution, and procurement model disintermediation. Each trend compresses legacy cost structures while opening premium positioning for adaptive suppliers.
Brushless DC motor technology is hybridizing with traditional AC induction designs in commercial-grade stand mixers, enabling precise speed control and energy recovery. United States institutional kitchens are adopting these systems fastest, driven by IRA efficiency incentives and utility rebate programs. The technology is compressing maintenance intervals and enabling longer continuous-duty cycles that displace batch-processing workflows.
REACH substance restrictions and RoHS amendments are phasing out certain chrome plating processes in mixing bowl manufacturing, forcing suppliers toward electropolished stainless steel alternatives. European manufacturers face the steepest compliance curves, with German producers already certifying new surface finishes to maintain CE marking validity. This regulatory pressure is accelerating consolidation among coating specialists unable to fund process retooling.
Foodservice operators are unbundling after-sales service from equipment purchase, preferring third-party maintenance contracts over manufacturer-captive programs. Independent service networks in the United States are capturing attachment replacement and calibration work previously reserved for OEM channels. This behavior shift is most visible in multi-site bakery chains seeking to standardize fleet uptime across distributed production facilities.
Mixers and Attachments Market Segmentation
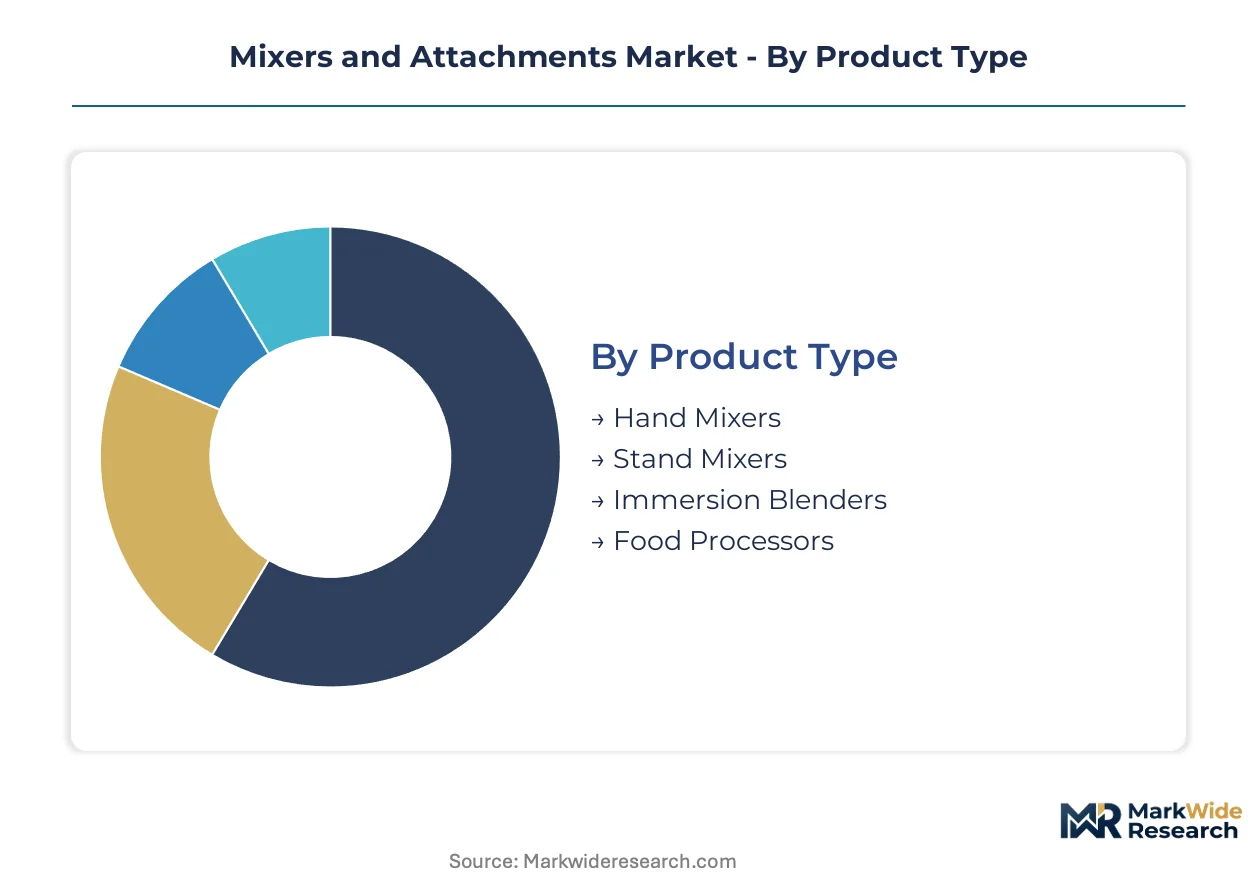
Segmentation in mixers and attachments reveals distinct replacement cadences and margin profiles across equipment categories. Stand mixers and commercial-grade power ratings command extended depreciation schedules, while consumable attachments and household-grade units turn over rapidly through wear cycles and upgrade triggers.
Product Type:
Replacement velocity varies dramatically across product categories, with handheld equipment cycling fastest due to lower price elasticity and impulse-driven purchase behavior.
- Stand Mixers:Planetary and spiral drive systems anchor commercial kitchen capital budgets with 10-15 year service lives. United States bakery chains concentrate fleet standardization around NSF-listed continuous-duty models to minimize cross-training and spare parts complexity.
- Immersion Blenders:Variable-speed DC motor systems enable precise shear control for emulsion work in institutional kitchens. German food manufacturers drive premium cordless lithium-ion adoption, prioritizing operator mobility over corded torque density.
- Hand Mixers:Entry-level DC motor units dominate household replacement cycles triggered by cosmetic wear or minor functional degradation.
- Food Processors:Multi-function bowl systems capture mid-scale catering demand where space constraints prohibit dedicated unitask equipment.
Stand mixers dominate installed base. Immersion blenders are where expansion concentrates.
Attachment Type:
Margin structures invert between durable base units and consumable tooling, with stainless steel contact surfaces driving recurring hygiene-mandated replacement revenue.
- Dough Hooks:Spiral and J-hook geometries in 304 and 316 stainless steel withstand gluten development torque in high-hydration applications. Munich and Stuttgart industrial baking clusters sustain premium replacement cycles as CE-marked surface finish standards tighten under REACH amendments.
- Mixing Bowls:Electropolished stainless steel construction eliminates chrome plating residues phased out by RoHS restrictions. North American institutional procurement now specifies NSF-listed bowl interchangeability as a fleet standardization requirement.
- Whisks:Piano wire and stainless balloon configurations capture pastry-focused bakery demand with 18-24 month replacement intervals.
- Blender Jars:Tritan copolyester and glass vessels face distinct fracture-risk profiles across commercial versus household duty cycles.
Mixing bowls dominate installed base. Dough hooks are where expansion concentrates.
End User:
Customer type segmentation separates capital-intensive equipment decisions from consumable attachment purchasing authority across organizational boundaries.
- Bakeries:Continuous-duty planetary mixers with thermal overload protection anchor production line throughput. United States commercial operators are expanding fleet purchases to meet volume mandates while leasing models lower capital barriers for mid-scale entrants.
- Restaurants:Multi-function stand mixer systems with quick-release hubs enable cross-menu flexibility in space-constrained back-of-house configurations.
- Households:KitchenAid heritage branding sustains premium direct-to-consumer pricing through controlled channel distribution.
- Catering Services:Portable immersion blender systems prioritize rapid deployment and sanitation compliance across distributed event sites.
Bakeries dominate installed base. Restaurants are where expansion concentrates.
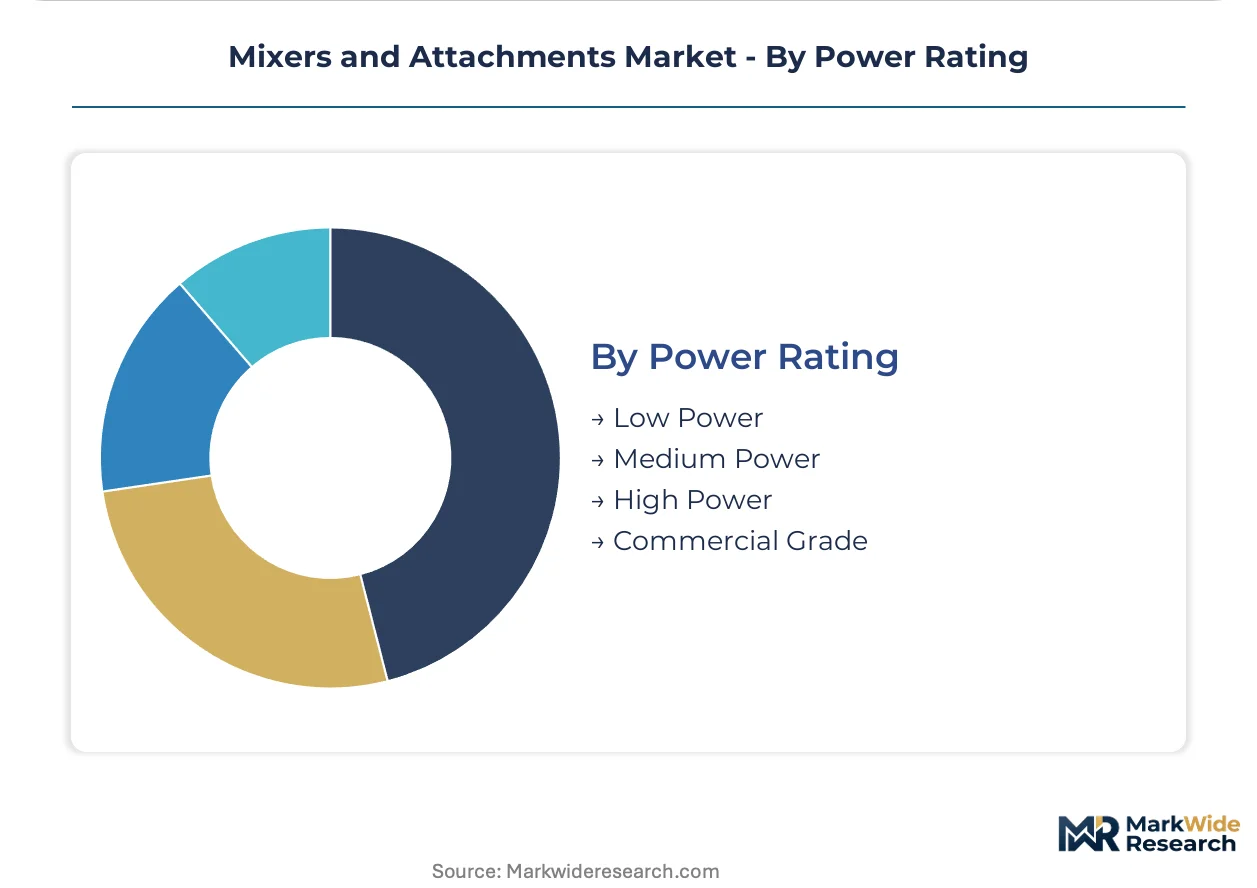
Power Rating:
Electrical specification tiers separate intermittent household duty from continuous commercial operation, with motor thermal protection and drivetrain durability as the critical differentiators.
- Commercial Grade:Continuous-duty AC induction and brushless DC systems operate at 50-60 Hz with integrated overload protection. IRA efficiency incentives and utility rebate programs in United States institutional kitchens accelerate adoption of energy-recovery motor designs.
- High Power:1-2 HP variable-speed systems bridge semi-professional and light commercial use cases with batch-processing workflows.
- Medium Power:Residential-grade AC motors with thermal cutoffs serve enthusiastic home bakers seeking extended mixing durations.
- Low Power:Entry-level DC motor hand mixers target price-sensitive household replacement demand with minimal feature differentiation.
Commercial grade dominates installed base. High power is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA efficiency incentives and utility rebate programs in the United States are accelerating brushless DC motor adoption in institutional kitchens. EU Ecodesign tightening and REACH substance restrictions are reshaping material specifications across European supply chains. China's manufacturing scale advantages continue to dominate variable-speed drivetrain component sourcing despite geopolitical friction.
United States
Commercial bakery chains are expanding planetary stand mixer fleet purchases to meet production throughput mandates. EPA energy efficiency thresholds and IRA tax credits accelerate continuous-duty motor replacements in institutional kitchens. Texas and California foodservice operators lead adoption of equipment-as-a-service financing models.
Germany
Industrial baking clusters around Munich and Stuttgart sustain premium attachment replacement cycles for stainless steel dough hooks and mixing bowls. REACH amendments and RoHS restrictions are phasing out chrome plating processes, forcing electropolished stainless steel alternatives. Baden-Württemberg manufacturers are certifying new surface finishes to maintain CE marking validity.
China
Variable-speed drivetrain subassemblies concentrate manufacturing in coastal provinces serving global OEM demand. MIIT industrial policy and GB standards shape motor efficiency specifications for export-oriented production. Yangtze River Delta suppliers dominate rare-earth magnet and copper winding component flows despite procurement timeline risks.
Japan
Precision motor manufacturers supply thermal overload protection systems to commercial-grade mixer OEMs. METI energy efficiency guidelines and JIS standards govern continuous-duty motor specifications for institutional export markets. Kanto region electronics clusters specialize in IoT-enabled torque sensing modules for predictive maintenance integration.
India
Mid-scale foodservice operators are emerging as price-sensitive demand centers for planetary mixer systems. BIS certification requirements and FSSAI food equipment sanitation standards are tightening import specifications. Maharashtra and Gujarat industrial corridors host contract manufacturing for cost-optimized motor assemblies.
Mixers and Attachments Market Competitive Landscape
On the supply side, the industry is bifurcated between heritage-brand premium positioning and manufacturing-scale cost leadership. KitchenAid and Groupe SEB anchor the brand-heritage tier through controlled distribution and institutional footprint respectively. Midea Group occupies the scale-driven vector with captive component sourcing. Competitive moves concentrate on pay-per-use financing penetration and smart torque sensing technology licensing.
Within the heritage-brand tier, KitchenAid exemplifies direct-to-consumer channel control sustaining premium household pricing. Groupe SEB anchors European commercial demand through Hobart's institutional footprint. Midea Group represents manufacturing-scale competition targeting cost-sensitive Asian markets. These three archetypes illustrate the strategic segmentation between brand equity, institutional relationships, and production efficiency.
| Leading Market Players |
|---|
| KitchenAid |
| Whirlpool Corporation |
| Groupe SEB |
| ITW Food Equipment Group (Hobart) |
| Philips (Versuni) |
| Midea Group |
| Electrolux AB |
| Breville Group |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Copper and rare-earth magnet cost volatility compresses manufacturing margins while simultaneously widening spreads between NSF-listed continuous-duty systems and uncertified alternatives. This commodity exposure forces tiered sourcing strategies that bifurcate supply chains into captive component flows versus spot-market procurement.
Pricing Analysis
Certification level creates the primary spread between commercial-grade and household-tier equipment, with NSF/ETL-listed stainless steel construction commanding substantial premiums over non-compliant alternatives. Three-tier pricing structure across premium continuous-duty, standard batch-processing, and economy intermittent-use levels reflects motor thermal protection ratings and duty cycle specifications. Pricing pressure stems from right-to-repair legislative friction threatening proprietary attachment locking mechanisms and recurring revenue streams. Mid-scale foodservice operators exhibit highest price sensitivity, while institutional bakery chains prioritize fleet standardization over unit cost.
Supply Chain Analysis
Contract manufacturing concentration in China's Yangtze River Delta and Pearl River Delta anchors variable-speed drivetrain subassembly production for global OEM demand. Rare-earth magnet processing centers on Inner Mongolia and Jiangxi province facilities, while copper winding components flow from Chilean and Peruvian mining operations through Chinese smelters. Single-source vulnerability in brushless DC motor controller chips exposes procurement timelines to geopolitical disruption risk. Distribution runs through manufacturer-direct channels for institutional accounts and specialized foodservice equipment distributors for mid-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food processor substitution and automated batching systems threaten traditional stand mixer installed bases, requiring incumbents to articulate clear throughput and precision advantages. Defense of market position demands proactive moves against this equipment-class displacement.
For Market Incumbents: Pre-empt attachment interoperability mandates by open-sourcing hub interface specifications before regulatory compulsion, converting compliance burden into first-mover standard-setting advantage. Deepen captive supply of brushless DC motor subassemblies through backward integration into Yangtze River Delta component partnerships, insulating against rare-earth magnet cost volatility. Fortify institutional relationships through predictive maintenance contract bundling that embeds torque-sensing IoT modules as fleet management infrastructure.
For New Entrants and Emerging Players: Build out pay-per-use financing infrastructure targeting mid-scale European foodservice operators where equipment-as-a-service models remain underdeveloped. Concentrate initial penetration on cordless immersion blender systems for German catering services, where lithium-ion mobility commands premium positioning absent from saturated household markets. Leverage third-party NSF certification acceleration services to compress 8-14 month listing timelines that currently strain incumbent R&D velocity.
For Investors and Strategic Acquirers: REACH substance restriction implementation reshapes the acquisition landscape toward electropolished stainless steel specialists with validated CE marking pathways. Long-term viability concentrates in suppliers with demonstrated compliance agility across RoHS amendments and emerging right-to-repair jurisdictions. Target contract manufacturers with captive surface finishing capabilities rather than coating-dependent legacy operations. Monitor EPA energy efficiency threshold announcements as inflection indicators for brushless DC motor replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Acceleration | Compresses 8-14 month product launch windows for new stainless steel grades. |
| Brushless DC Motor Integration | Captures IRA efficiency incentives in United States institutional kitchen procurement. |
| Equipment-as-a-Service Launch | Penetrates underdeveloped mid-scale European foodservice financing markets. |
| Predictive Maintenance Platform | Hybridizes IoT torque sensing with traditional thermal cutoffs for bakery chains. |
| Electropolished Surface Transition | Maintains CE marking validity under REACH chrome plating phase-out mandates. |
Research Methodology
The analysis maps planetary stand mixer systems, immersion blender configurations, and attachment replacement cycles, each validated through maintenance directors at multi-site bakery chains, foodservice equipment procurement managers, and aftermarket service network operators. Primary interview findings triangulate against customs trade records for stainless steel food equipment imports, NSF International certification databases, and SEC 10-K disclosures from listed appliance manufacturers. Bottom-up unit economics and top-down category spending estimates converge through iterative stakeholder feedback loops.
Forecast assumptions hold fixed current REACH substance restriction timelines and IRA efficiency incentive structures while varying copper price trajectories and right-to-repair legislative adoption rates across the projection horizon. Segmentation dimensions include product type, power rating tier, end-user category, and regional regulatory cluster. CAGRs derive from installed base depreciation schedules and replacement cycle elasticity modeled against historical NSF certification volume data and commercial bakery capital expenditure surveys.
Sensitivities concentrate around rare-earth magnet export restrictions, EPA energy efficiency threshold acceleration, and ETL sanitation listing procedure modifications. Forecasts reflect documented assumptions regarding equipment-as-a-service adoption velocity and smart torque sensing technology cost curves. Quarterly review of NSF certification application backlogs, brushless DC motor controller chip lead times, and German industrial baking cluster capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Europe Smart Cooker Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
Electric Lunch Box Market