
 Smart Faucets Market | 2026-2036
Smart Faucets Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Faucets Market Outlook
Modular sensor-and-spout configurations is broadening buyer choice across retrofit and new-build channels. Kohler Co. leverages its captive ceramics ecosystem to bundle smart faucets with matching basin systems. Moen Incorporated anchors North American distribution through exclusive plumbing-contractor relationships. LIXIL Group dominates Asian specification markets with JIS-certified infrared platforms.
A smart faucet integrates electronic valve actuation, proximity or voice-based input, and network connectivity into a water-delivery fixture, typically operating at flow rates between 1.0 and 1.5 gallons per minute to balance user experience with conservation mandates. Touchless variants lead volume shipments in commercial hygiene applications, while Wi-Fi enabled units capture the fastest expansion as residential smart home ecosystems standardize on unified app control. Deck-mounted installation types hold the deepest existing replacement base, though wall-mounted configurations are gaining specification share in minimalist hospitality and healthcare interiors.
EPA WaterSense and DOE appliance standards govern flow efficiency and electromagnetic compatibility in the United States, while EU Ecodesign regulations and CE marking requirements shape product access across European member states. China's GB standards and MIIT connectivity certifications add compliance layers for networked fixtures entering that market. Stakeholders must monitor divergence between regional cybersecurity mandates for IoT-enabled plumbing devices and evolving interoperability protocols that could fragment or consolidate platform loyalty.
Market Dynamics
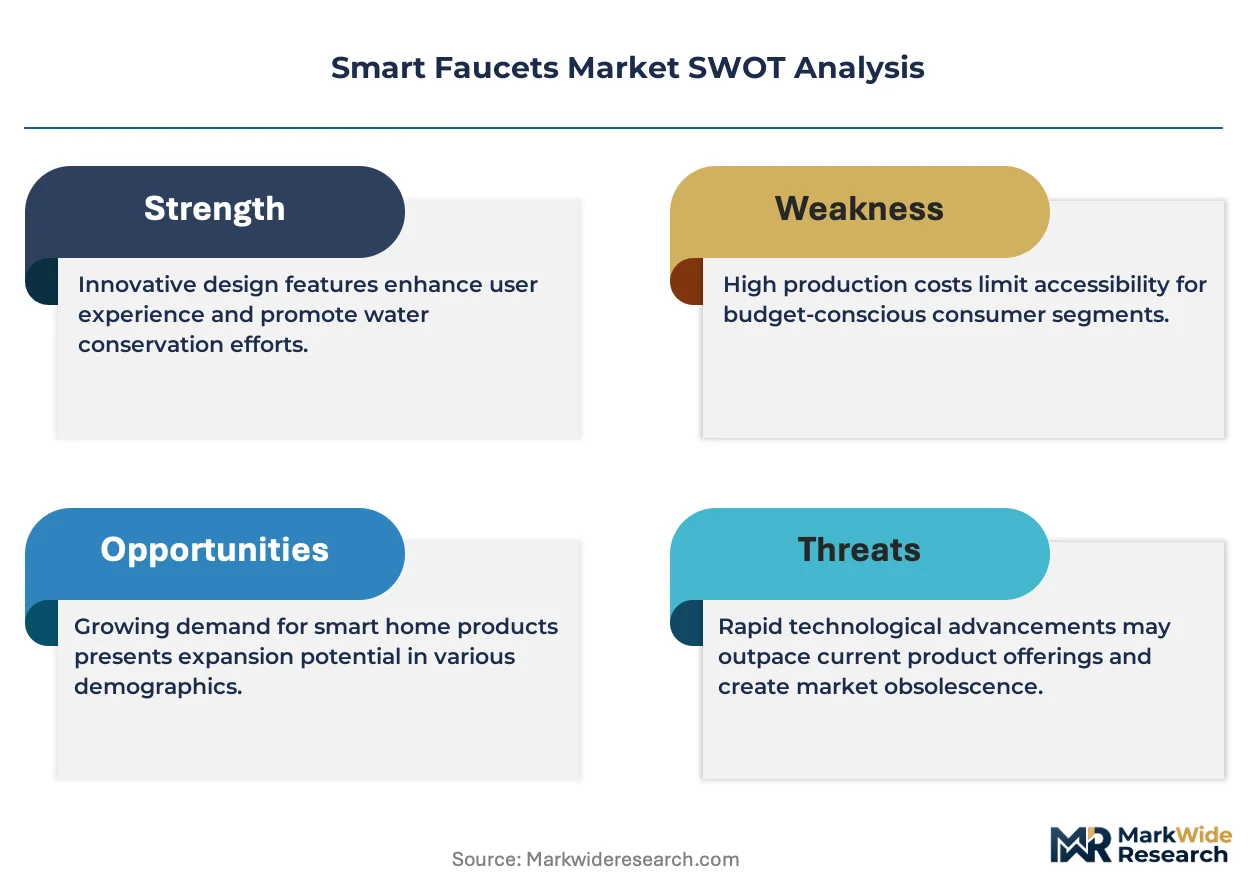
Sensor-actuated valve technology is compressing replacement cycles across commercial and residential channels, while EPA WaterSense flow-rate mandates force redesigns of legacy mechanical platforms.
Growth Catalysts
- EPA WaterSense Certification:Tightened flow-rate thresholds in the United States accelerate sensor-optimized fixture adoption among specification engineers and facility managers.
- China Tier-One Urbanization:Shanghai, Beijing, and Shenzhen residential construction integrates smart home ecosystems at rates outpacing most other national markets.
- Hospitality Hygiene Protocols:Luxury hotel chains deploy touchless fixtures to meet elevated guest-sanitation expectations post-pandemic.
Market Restraints
- Semiconductor Supply Concentration:Infrared sensor chip fabrication concentrates in Taiwan and South Korea, exposing manufacturers to geopolitical disruption.
- Copper and Zinc Input Volatility:Brass alloy pricing swings directly compress margin on mid-tier deck-mounted units.
- Legacy Plumbing Contractor Skill Gaps:Electrician-plumber licensing overlap creates installation friction in jurisdictions with strict trade boundaries.
Strategic Opportunities
- India Residential Penetration:Smart home adoption in Mumbai and Delhi NCR remains underdeveloped relative to hardware cost curves.
- Voice-Actuation Convergence:Integration of Alexa and Google Assistant protocols with valve-control firmware opens premium residential positioning.
- EU Ecodesign Regulatory Tailwind:Flow-efficiency mandates create specification preference for sensor-optimized designs in German and French new-build markets.
Industry Challenges
- Cybersecurity Certification Timelines:MIIT connectivity approvals for IoT-enabled fixtures in China extend product launch windows by 4-8 months.
- Legacy Mechanical Installer Base:Retraining programs for union plumbing contractors on electronic troubleshooting lag hardware innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Faucets Market |
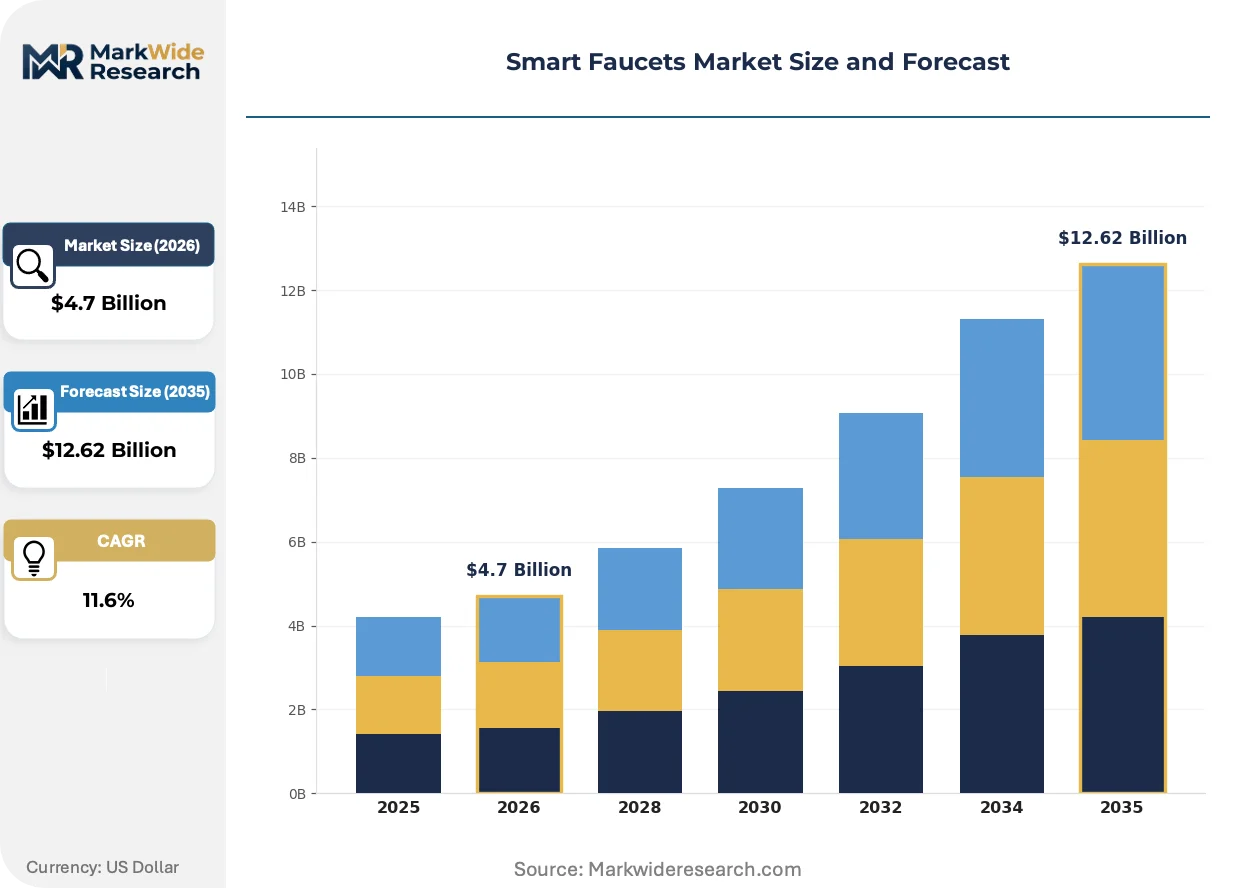
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchless, Digital, Bluetooth Connected, Wi-Fi Enabled End User: Residential, Commercial, Industrial, Hospitality Technology: Infrared Sensors, Voice Activation, App Control, Smart Home Integration Installation Type: Wall-Mounted, Deck-Mounted, Freestanding, Portable |
| Companies Covered | Kohler Co., Moen Incorporated, Delta Faucet Company, LIXIL Group, Hansgrohe SE, Grohe, Oras Ltd., TOTO Ltd., Pfister, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Faucets Market Strategic Shifts
Valve-actuation architectures are bifurcating between commodity infrared platforms and premium voice-networked systems, with specification preferences diverging sharply by channel and price tier.
Capacitive proximity sensing is overtaking traditional infrared beam detection in high-traffic commercial restrooms. The technology eliminates false triggers from ambient light interference. Airport operators and hospital facility managers in the United States and Germany specify capacitive platforms for reliability-critical installations. This shift is compressing specification share for legacy infrared suppliers in institutional procurement.
EU Ecodesign regulations now mandate maximum flow rates of 5.7 liters per minute for basin taps, with CE marking requirements expanding to cover electromagnetic compatibility testing. Manufacturers serving European markets must redesign solenoid valve coils to meet stricter efficiency thresholds. German and Dutch specification engineers increasingly pre-filter vendor lists based on pre-certified Ecodesign compliance, accelerating consolidation among prepared suppliers.
Facility managers now bundle fixture procurement into comprehensive water-management service contracts rather than discrete capital purchases. Plumbing contractors in California and Texas pilot subscription models covering installation, sensor calibration, and predictive maintenance. This reconfiguration transfers technical risk to manufacturers while locking in multi-year replacement revenue streams in commercial verticals.
Smart Faucets Market Segmentation
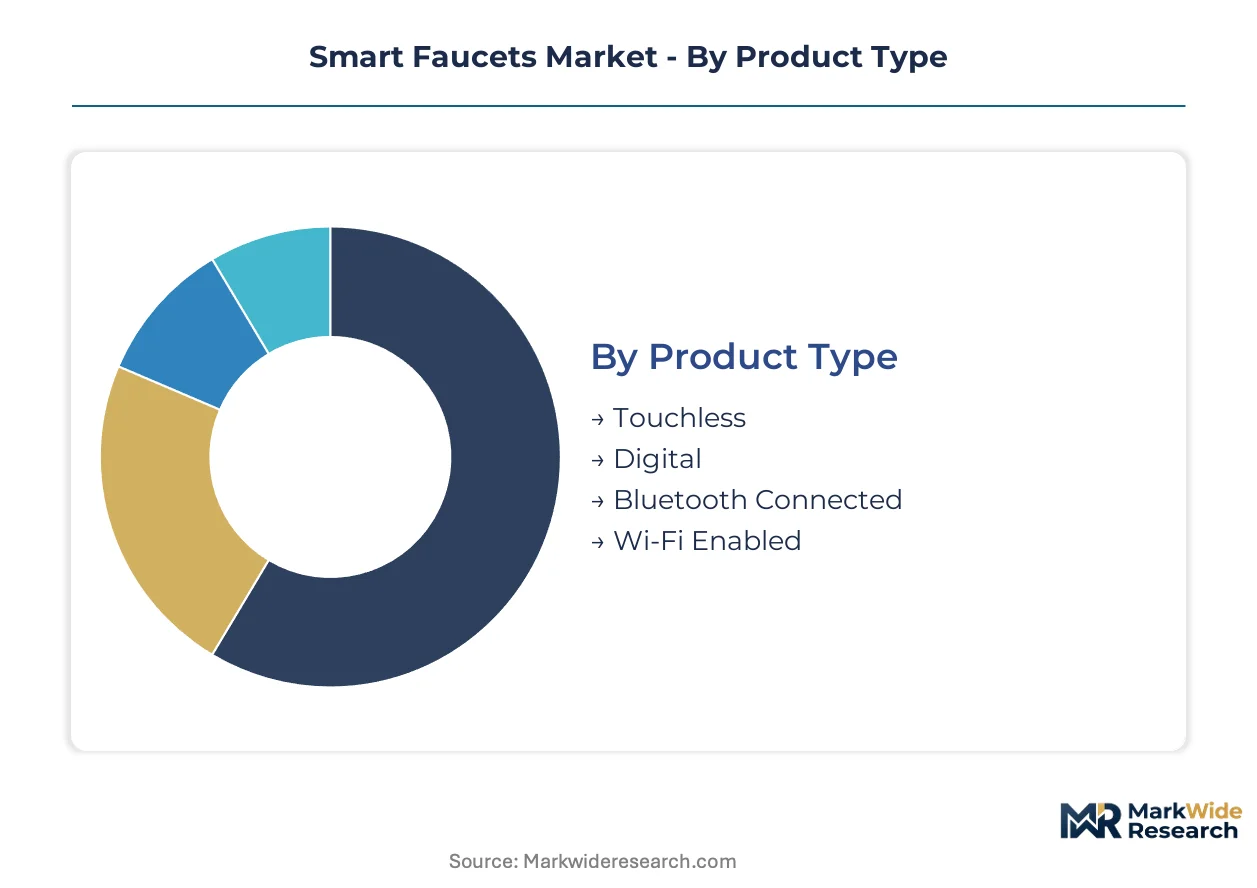
Smart faucet procurement patterns diverge sharply across installation contexts, sensor architectures, and connectivity protocols. Specification engineers and facility managers weight hygiene mandates, smart home ecosystem compatibility, and retrofit feasibility differently by channel. Understanding these segment boundaries clarifies where sensor-optimized designs displace legacy mechanical platforms.
Product Type:
Supply concentration clusters around infrared-actuated platforms, though voice-networked systems command premium positioning in residential smart home integration.
- Touchless:Infrared or capacitive proximity sensors trigger solenoid valve actuation without physical contact. Luxury hotel chains in Shanghai and Shenzhen specify these for guest bathroom renovations driven by post-pandemic hygiene protocols.
- Wi-Fi Enabled:Network connectivity enables remote flow monitoring, usage analytics, and integration with unified home automation apps. Residential construction in China's tier-one cities absorbs these units fastest as smart home standardization accelerates.
- Digital:Temperature and flow displays assist user control through embedded LED or LCD interfaces.
- Bluetooth Connected:Short-range pairing with smartphones supports localized control without full home network dependency.
Today's leader: Touchless. Tomorrow's challenger: Wi-Fi Enabled.
End User:
Application requirements shape sensor reliability specifications and connectivity investment levels across buyer categories.
- Commercial:High-traffic restrooms in airports, hospitals, and office towers demand capacitive sensing platforms that eliminate false triggers from ambient light interference. German facility managers specify these for reliability-critical institutional procurement.
- Hospitality:Luxury hotel chains bundle touchless fixtures with comprehensive water-management service contracts covering installation, calibration, and predictive maintenance. California and Texas contractors pilot subscription models transferring technical risk to manufacturers.
- Residential:Smart home ecosystem integration drives specification in new construction and renovation projects.
- Industrial:Heavy-duty valve architectures withstand corrosive environments and high-cycle operation.
Commercial installations dominate current volume. Hospitality contracts capture the steepest expansion trajectory as service-based procurement reconfigures capital expenditure patterns.
Technology:
Valve-actuation architectures bifurcate between commodity infrared platforms and premium voice-networked systems with diverging margin profiles.
- Infrared Sensors:Legacy beam-detection technology faces specification compression as capacitive proximity sensing overtakes it in high-traffic commercial restrooms. Airport operators in the United States and Germany now pre-filter vendor lists based on capacitive reliability.
- Smart Home Integration:Unified app control through Alexa and Google Assistant protocols opens premium residential positioning. Mumbai and Delhi NCR residential penetration remains underdeveloped relative to hardware cost curves, creating expansion headroom.
- Voice Activation:Hands-free operation through natural language commands.
- App Control:Smartphone-based flow adjustment and usage monitoring.
Infrared Sensors anchor current specification share. Smart Home Integration gains fastest as residential ecosystem standardization accelerates.
Installation Type:
Mounting configurations reflect tension between existing replacement infrastructure and minimalist interior design trends.
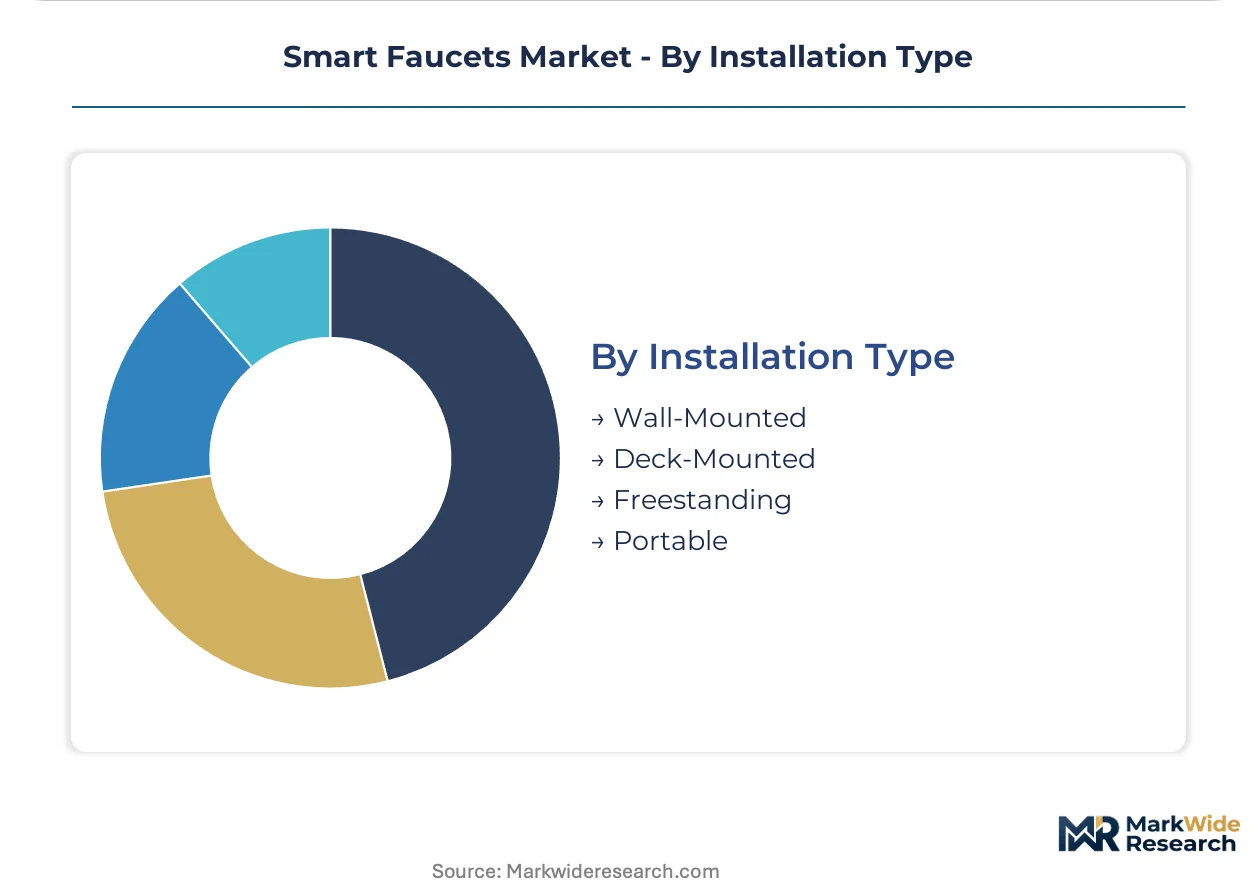
- Deck-Mounted:The deepest existing replacement base across residential and commercial channels. Brass alloy input volatility directly compresses margin on mid-tier units in this category.
- Wall-Mounted:Gaining specification share in minimalist hospitality and healthcare interiors. German and Dutch new-build markets favor these configurations for clean sightlines and simplified cleaning protocols.
- Freestanding:Floor-mounted architectures for specialized basin designs.
- Portable:Temporary or rental-market solutions without permanent plumbing modification.
Deck-Mounted units hold installed base dominance. Wall-Mounted configurations climb fastest as hospitality and healthcare interior specifications evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor-optimized plumbing fixtures first achieved commercial scale in post-war Japan, where JIS certification protocols and dense urban housing created early standardization. That historical foundation now shapes procurement patterns across three continents.
United States
EPA WaterSense flow-rate mandates now govern specification decisions for institutional and residential channels. The DOE appliance standards layer electromagnetic compatibility requirements onto networked fixture designs. California and Texas plumbing contractors pilot subscription-based water-management service contracts covering predictive maintenance.
Germany
EU Ecodesign regulations mandate maximum flow rates of 5.7 liters per minute for basin taps, compressing specification windows for non-compliant suppliers. CE marking requirements now extend to electromagnetic compatibility testing for solenoid valve architectures. Facility managers in Frankfurt and Munich increasingly pre-filter vendor lists based on pre-certified compliance status.
China
MIIT connectivity certifications add 4-8 month approval timelines for IoT-enabled fixtures entering domestic distribution. GB standards govern baseline performance while dual carbon goals accelerate sensor-optimized adoption in new construction. Shanghai, Beijing, and Shenzhen residential projects integrate smart home ecosystems at rates outpacing comparable markets.
Japan
METI efficiency programs and JIS-certified infrared platforms anchor specification preferences in commercial and hospitality verticals. The country's historical leadership in touchless fixture deployment now transfers to voice-networked system integration. Tokyo and Osaka facility managers specify capacitive proximity sensing for high-traffic institutional restrooms.
Smart Faucets Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and captive ecosystem breadth. The vendor base clusters around three strategic archetypes: diversified fixture conglomerates with ceramics integration, specialized sensor-technology developers, and regional plumbing contractors with exclusive distribution relationships. Consolidation pressure concentrates among mid-tier suppliers facing brass alloy input volatility and extended cybersecurity certification timelines. Dominant competitive moves include backward integration into sensor chip sourcing and geographic expansion through specification-engineer relationship building.
Within the diversified conglomerate tier, Kohler Co. and LIXIL Group exemplify players leveraging captive manufacturing ecosystems to bundle fixture systems. Moen Incorporated anchors North American positioning through plumbing-contractor channel relationships. These three names represent distinct strategic vectors: ceramics-forward integration, Asian specification dominance, and contractor-anchored distribution.
| Leading Market Players |
|---|
| Kohler Co. |
| Moen Incorporated |
| Delta Faucet Company |
| LIXIL Group |
| Hansgrohe SE |
| Grohe |
| Oras Ltd. |
| TOTO Ltd. |
| Pfister |
| Others |
Value Chain & Pricing Dynamics
Brass alloy pricing swings propagate through three distinct product tiers, compressing margins on mid-tier deck-mounted units while premium voice-networked systems absorb volatility through bundled service contracts. Copper and zinc input concentration in Chilean and Peruvian mining operations exposes manufacturers to commodity-driven cost resets that reshape procurement negotiations with California and Texas plumbing contractors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Wi-Fi-enabled residential systems from infrared commercial platforms and basic mechanical retrofits. Price differentiation hinges on EPA WaterSense certification grade and after-sales service bundling, with hospitality procurement showing lowest sensitivity due to subscription contract structures. Pricing pressure stems from semiconductor supply concentration in Taiwan and South Korea, forcing mid-tier manufacturers toward cost compression in sensor-actuated valve assemblies.
Supply Chain Analysis
Refurbishment flows for sensor modules and solenoid valve assemblies remain underdeveloped, creating stranded asset risk in commercial retrofit cycles. Manufacturing concentration clusters in China, Taiwan, and Germany, with infrared sensor chip fabrication drawing from concentrated wafer foundry capacity. Raw material dependencies center on brass alloys, rare-earth magnets for valve actuation, and epoxy resins for electronic encapsulation. Single-source vulnerability in Taiwan-based semiconductor fabrication threatens production continuity for networked fixture lines. Distribution runs through exclusive plumbing-contractor relationships in North America and specification-engineer channels in European new-build markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart faucets function as a regulatory compounder where EPA WaterSense flow-rate mandates and EU Ecodesign efficiency thresholds continuously reset baseline demand for sensor-optimized designs.
For Market Incumbents: Cement specification-engineer relationships through pre-certified Ecodesign compliance and JIS-certified platform standardization. Deepen backward integration into sensor chip sourcing to offset Taiwan concentration risk. Invest in captive ceramics ecosystems that bundle basin systems with matching touchless fixtures, mirroring Kohler Co.'s defensive architecture against modular competitors. For New Entrants and Emerging Players: Mumbai and Delhi NCR residential contractors represent an underserved buyer archetype with smart home adoption lagging hardware cost curves. Penetrate India's tier-one urbanization wave through voice-actuation convergence with Alexa and Google Assistant protocols. Pursue white-label partnerships with Asian specification channels rather than direct brand building. For Investors and Strategic Acquirers: Roll-up economics work for regional plumbing contractors with exclusive distribution relationships because service-based procurement reconfigures capital expenditure patterns toward multi-year replacement revenue. Target mid-tier sensor-technology developers facing extended MIIT cybersecurity certification timelines. Monitor capacitive proximity sensing specification share in German and Dutch institutional procurement as inflection indicator for infrared platform displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Chip Sourcing | Taiwan concentration risk demands captive supply chains for production continuity. |
| Pre-Certified Ecodesign Compliance Investment | German specification engineers pre-filter vendor lists based on CE marking status. |
| Subscription-Based Water-Management Service Contracts | California and Texas contractors pilot models transferring technical risk to manufacturers. |
| Voice-Actuation Protocol Integration | Alexa and Google Assistant convergence opens premium residential positioning in underpenetrated markets. |
| Capacitive Proximity Sensing Platform Development | Airport operators in the United States and Germany specify these for reliability-critical installations. |
Study Parameters
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each market cluster combining interviews with specification engineers, facility managers, plumbing contractors, and smart home integration specialists. Secondary validation draws from EPA WaterSense certification databases, EU Ecodesign regulatory filings, MIIT connectivity approval records, and JIS standard documentation. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions across installation type and connectivity protocol segments.
Granularity-level modeling disaggregates volume and value outputs by product type, end user, technology architecture, and installation configuration, with additional dimensioning for regional regulatory cluster and smart home ecosystem compatibility. CAGRs derive from fitted growth curves applied to segment-level baselines, incorporating semiconductor supply constraints, brass alloy price trajectories, and certification timeline delays as industry-specific forecast inputs across the projection horizon.
Underlying measurement precision varies by segment; Wi-Fi-enabled residential systems carry tighter precision than industrial heavy-duty architectures due to smart home standardization transparency. Forecasts reflect assumptions about EPA WaterSense threshold evolution, MIIT approval velocity, and copper-zinc price stabilization that practitioners should monitor for early revision signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Saudi Arabia Cookware Market
Household Items
North America Liquid Hand Soap Market
Household Items
Dry and Wet Wipes Market
Household Items
Facial Tissue Paper Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Sleeping Pods Market
Household Items
Domestic Sauna Heaters Market
Household Items
Party Balloon Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Ceramic Travel Mug Market
Household Items
Barbecue Grill Market
Household Items
Cast Iron Cookware Market
Household Items
Air Care Market
Household Items
Gas Hobs Market
Household Items
Global Nap Pod Market