
 Power Diode Market | 2026-2036
Power Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Power Diode Market Analysis
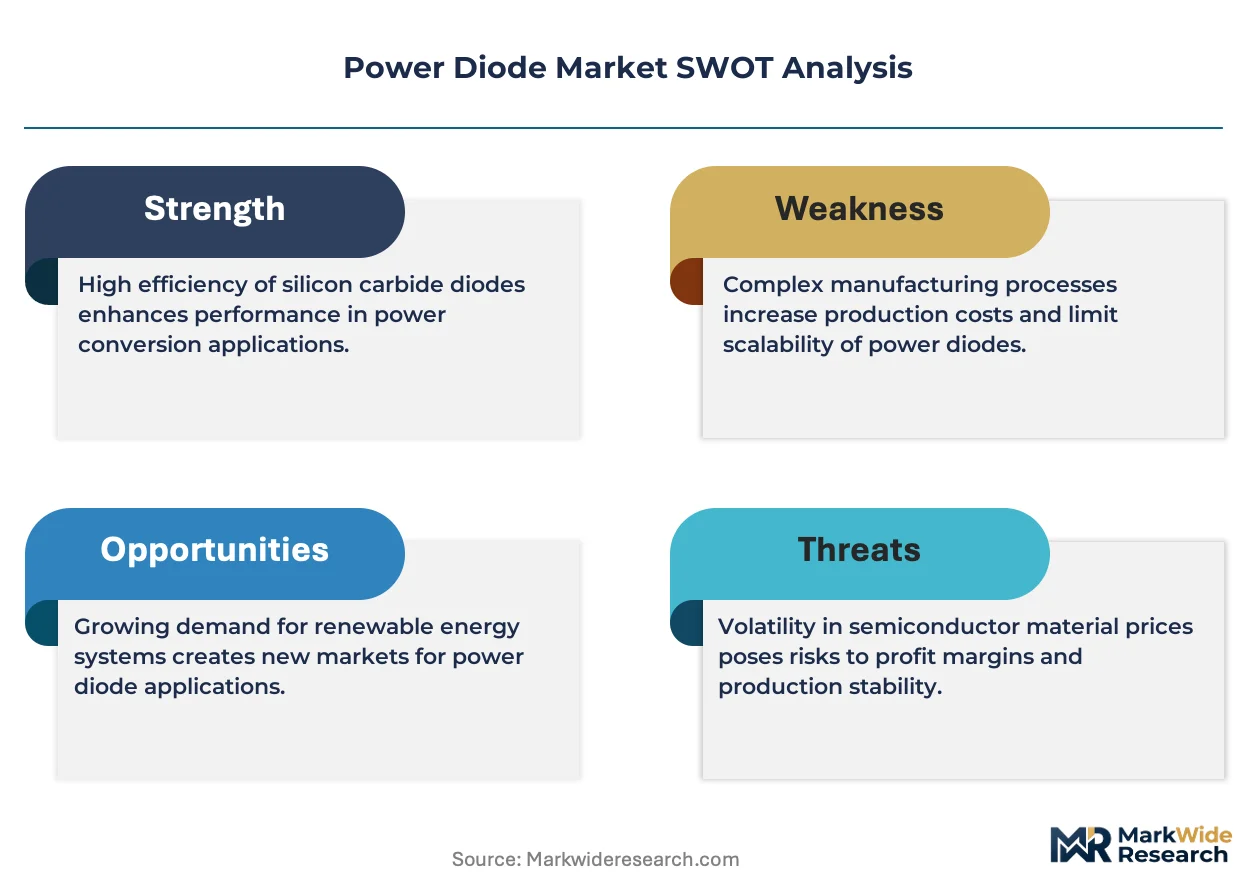
Silicon carbide is shifting from niche aerospace applications into mainstream power diode designs, cutting switching losses by half against conventional silicon. Infineon Technologies AG leverages captive SiC crystal growth to anchor supply security for automotive customers. STMicroelectronics competes through integrated module packaging that sustains margin capture from bare die to system-level solutions.
Power diodes are two-terminal semiconductor devices engineered to conduct current in one direction while blocking reverse voltage, typically fabricated from silicon or wide-bandgap materials with breakdown ratings from tens to thousands of volts. Silicon retains manufacturing scale and cost advantage for standard rectification below 600V, while silicon carbide diodes command premium positioning in 1200V+ traction and renewable energy converters where efficiency thresholds justify material cost. Schottky diodes dominate low-voltage power supply segments with near-zero recovery charge, whereas fast recovery variants lead motor drive applications where switching frequency demands suppress electromagnetic interference. Gallium nitride technology is displacing silicon in sub-100V consumer electronics adapters, fragmenting the technology hierarchy across voltage tiers.
FCC electromagnetic compatibility rules in the United States, EU RoHS substance restrictions, and China's GB standards for grid-connected inverters collectively shape product qualification requirements and market access timelines. Japan's METI efficiency mandates for industrial motor systems are redirecting procurement toward fast recovery and SiC hybrid configurations. Stakeholders must monitor how automotive OEMs reconcile their 800V platform roadmaps with foundry capacity allocation for SiC epitaxy.
Market Dynamics
The transition from silicon to silicon carbide substrates is compressing switching losses while amplifying foundry competition for automotive-grade epitaxy capacity.
Growth Catalysts
- EU F-Gas Regulation:Tightening material purity mandates for semiconductor substrates are accelerating substrate qualification programs across European automotive supply chains.
- Traction inverter demand:Electric vehicle manufacturers are expanding procurement of silicon carbide diodes for 800V platform architectures.
- Germany's automotive corridor:Munich-Stuttgart electronics clustering is concentrating design-in activity and technical support infrastructure for power semiconductor vendors.
Market Restraints
- SiC substrate cost volatility:Limited boule growth capacity concentrates supply among specialized crystal producers, amplifying input cost pressure.
- Technical limitation in defect density:Micropipe and dislocation rates in 150mm SiC wafers constrain yield economics for high-voltage discrete devices.
- Regulatory friction from REACH:Substance disclosure requirements for semiconductor processing chemicals extend qualification timelines for new package materials.
Strategic Opportunities
- Grid-scale storage integration:Utility-scale battery inverters represent an underpenetrated application segment for 1700V SiC diode modules.
- Japan METI efficiency mandates:Industrial motor system regulations are redirecting procurement toward fast recovery and SiC hybrid configurations.
- Direct OEM contracting:Automotive manufacturers are bypassing traditional distribution to secure multi-year die supply agreements.
Industry Challenges
- Power electronics talent scarcity:Shortage of engineers with wide-bandgap device characterization expertise constrains product development velocity.
- Multi-standard certification burden:Simultaneous FCC electromagnetic compatibility, EU RoHS, and China GB grid standards extend time-to-revenue for new product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Diode Market |
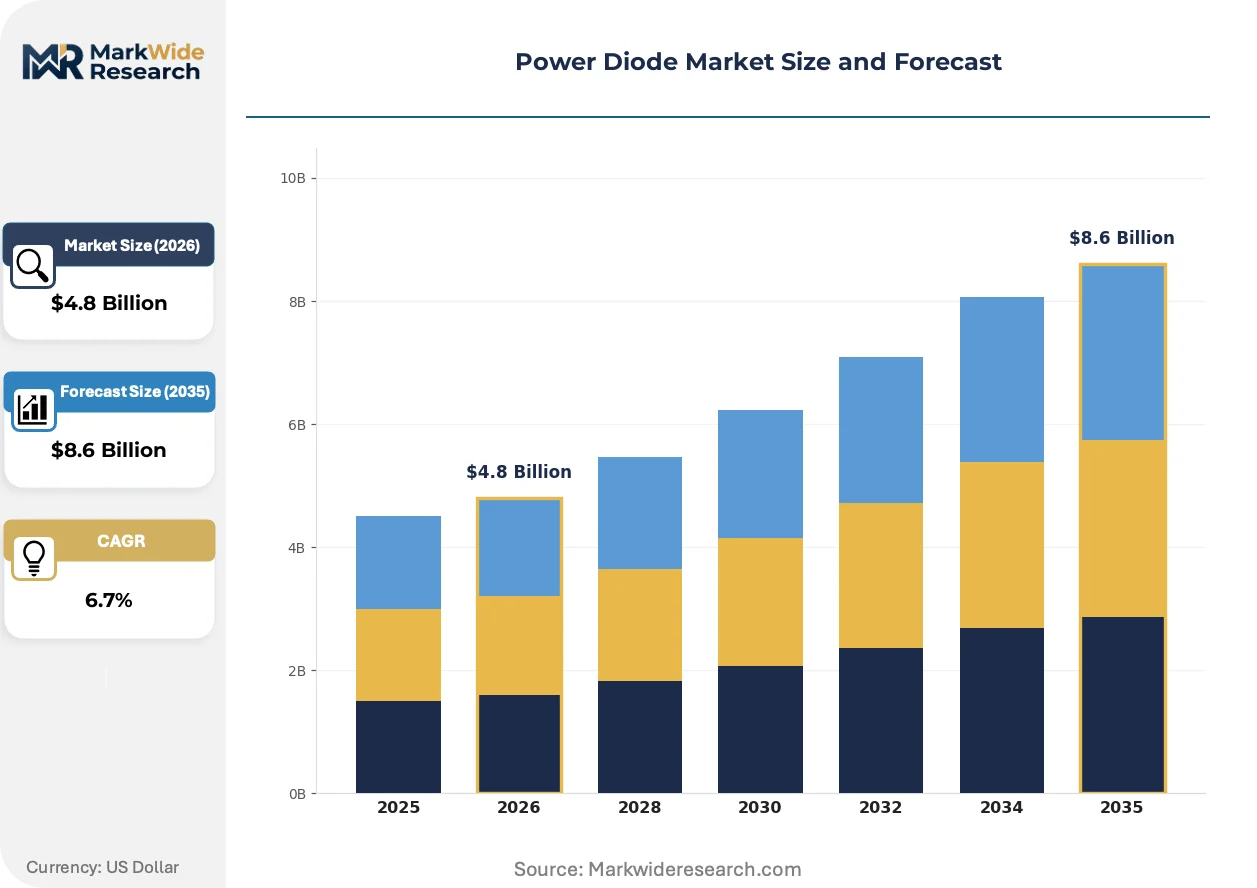
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
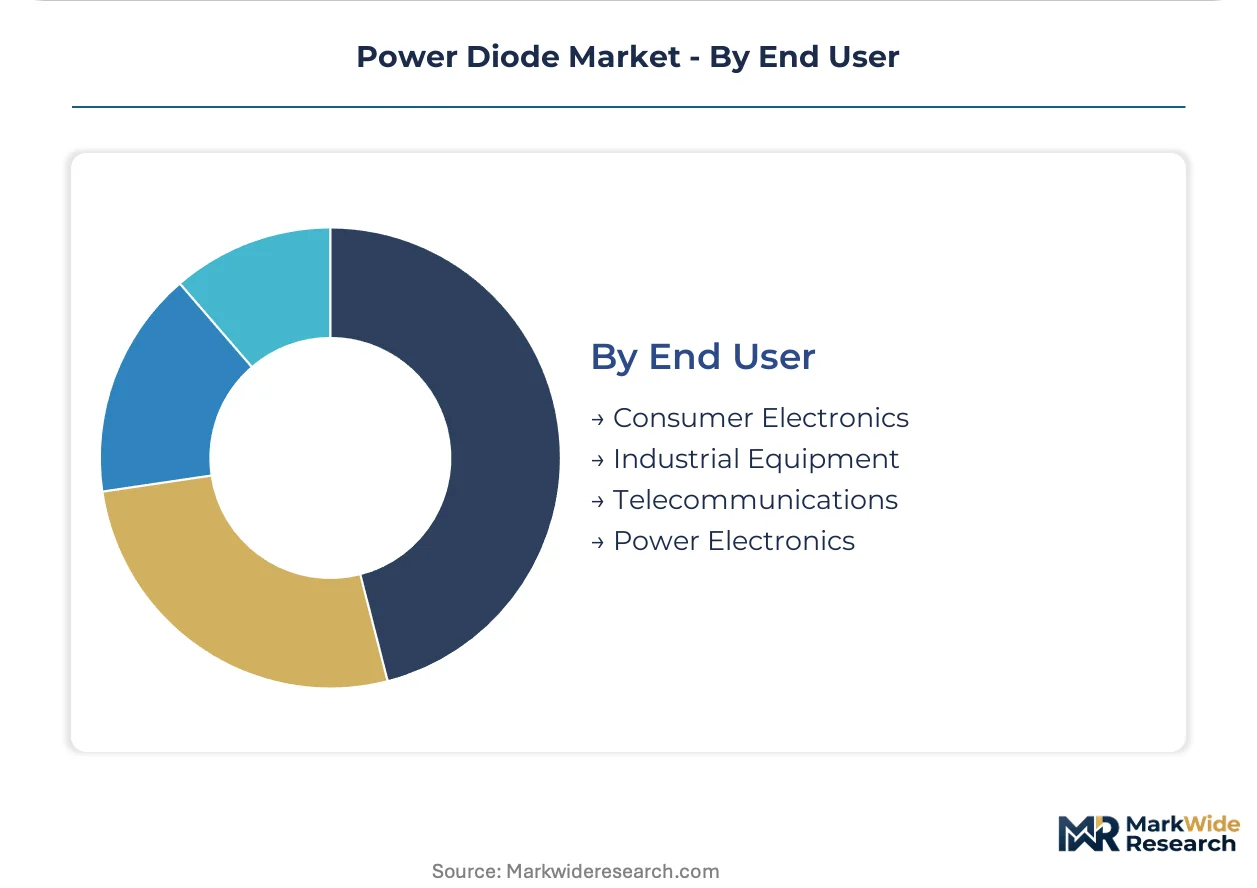
| Segmentation | Product Type: Standard Diodes, Schottky Diodes, Zener Diodes, Fast Recovery Diodes Technology: Silicon, Silicon Carbide, Gallium Nitride, Hybrid Technologies Application: Power Supplies, Motor Drives, Renewable Energy, Automotive Systems End User: Consumer Electronics, Industrial Equipment, Telecommunications, Power Electronics |
| Companies Covered | onsemi, STMicroelectronics, Nexperia, Diodes Incorporated, Vishay Intertechnology, ROHM Semiconductor, Infineon Technologies AG, Renesas Electronics, Shindengen Electric Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Diode Market Emerging Trajectories
Material substitution and packaging integration are compressing the traditional hierarchy between discrete components and system-level power modules.
Silicon carbide Schottky diodes are absorbing switching loss reduction requirements in 1200V traction inverters. Tier-1 automotive suppliers are accelerating design-in cycles from 36 to 18 months. This absorption is compressing the addressable market for conventional fast recovery silicon diodes above 600V.
EU F-Gas Regulation amendments are tightening fluorinated greenhouse gas restrictions for semiconductor manufacturing equipment. Process tool suppliers must retrofit abatement systems or face production quota limitations. German and French substrate fabs are prioritizing fluorine-free cleaning chemistries to maintain capacity allocation.
Long-term supply agreements are displacing spot market purchasing for automotive-qualified die. Tier-1 suppliers are locking three to five year capacity reservations directly with foundries. This pattern is most visible in Germany where OEMs are securing SiC epitaxy output for 800V platform ramp-ups.
Power Diode Market Segmentation
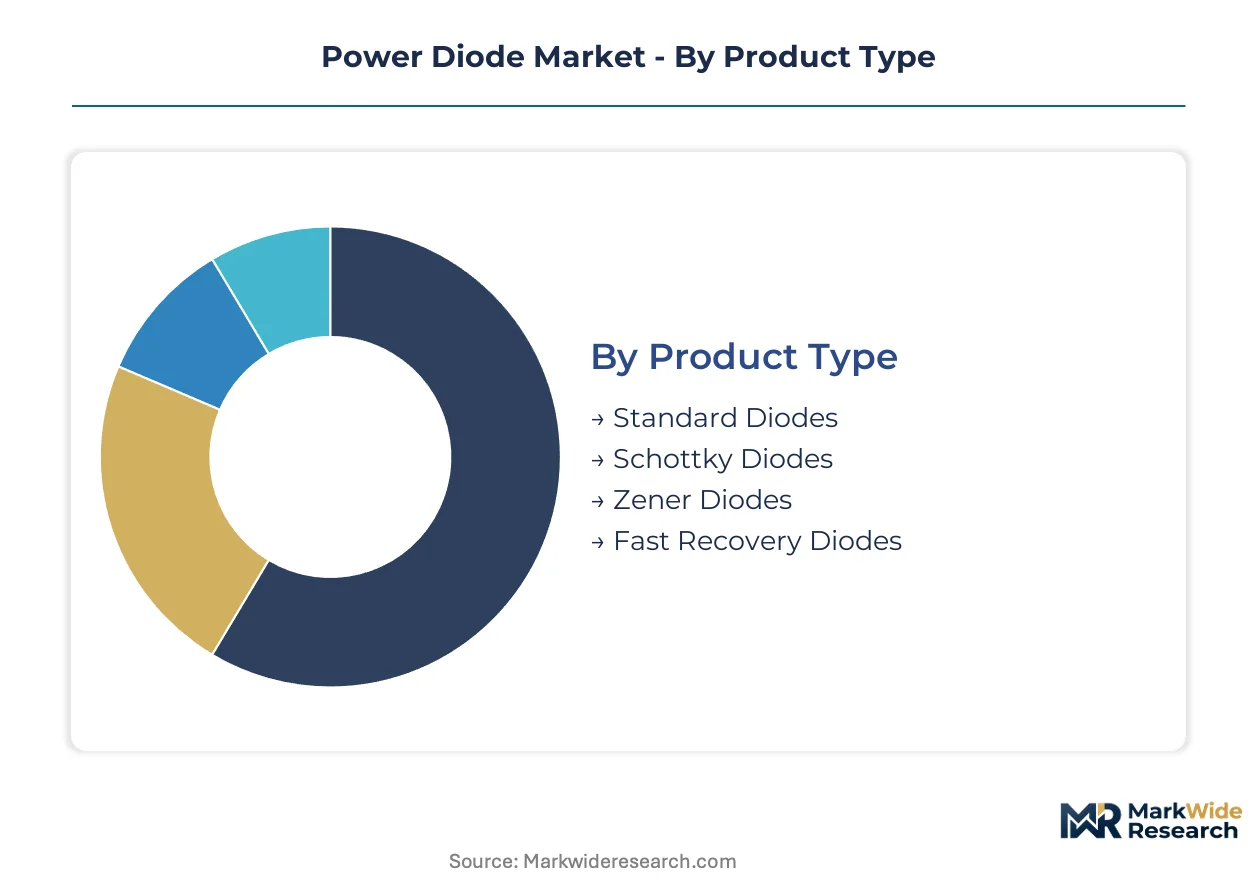
Power diode procurement patterns diverge sharply across voltage thresholds and switching frequency requirements. Material selection and package integration decisions cascade through automotive qualification timelines and renewable energy converter specifications.
Product Type:
Standardization dominates below 600V where silicon rectifiers suffice, while customization intensity rises with recovery speed demands in traction applications.
- Standard Diodes:General-purpose silicon rectifiers handle line-frequency conversion in industrial power supplies and appliance inverters. Demand concentrates in China's manufacturing belt for motor control modules where cost-per-ampere drives supplier selection.
- Schottky Diodes:Metal-semiconductor junctions deliver near-zero reverse recovery charge for switch-mode power supplies below 100V. Procurement is shifting toward gallium nitride replacements in consumer electronics adapters from Shenzhen and Dongguan contract manufacturers.
- Zener Diodes:Voltage reference and clamping functions in protection circuits across telecommunications infrastructure.
- Fast Recovery Diodes:Optimized reverse recovery characteristics suppress electromagnetic interference in motor drives and welding equipment.
Most installed capacity flows through Standard Diodes. Expansion is steepest in Fast Recovery Diodes.
Technology:
Cost tiers separate mature silicon processes from wide-bandgap materials commanding premium positioning in high-voltage, high-frequency applications.
- Silicon:Mature epitaxial growth and ion implantation sustain cost leadership for breakdown ratings below 1200V. Volume concentrates in discrete packaged devices for industrial motor drives where Infineon and STMicroelectronics maintain captive wafer supply.
- Silicon Carbide:4H-SiC substrates enable 1200V-3300V Schottky diodes with half the switching losses of silicon equivalents. Demand is accelerating in Germany's automotive corridor for 800V traction inverters where EU F-Gas Regulation compliance requires fluorine-free substrate processing.
- Gallium Nitride:HEMT-integrated diodes displace silicon in sub-100V consumer power adapters.
- Hybrid Technologies:SiC-silicon co-packaged modules balance cost and performance in mid-voltage motor drives.
Silicon retains the largest manufacturing footprint. Silicon Carbide is gaining share fastest in automotive-qualified die.
Application:
Customer type stratification separates high-volume, price-sensitive supply contracts from low-volume, qualification-intensive automotive programs.
- Power Supplies:AC-DC and DC-DC conversion across server racks, telecom base stations, and consumer adapters. Schottky and super-junction silicon diodes dominate below 600V where efficiency regulations from the US DOE and EU Ecodesign shape component selection.
- Motor Drives:Variable frequency inverters for industrial automation and HVAC compressors. Fast recovery silicon diodes face displacement pressure from SiC hybrids under Japan METI efficiency mandates for industrial motor systems.
- Renewable Energy:Solar inverters and wind turbine converters requiring 1200V-1700V blocking capability.
- Automotive Systems:Traction inverters, onboard chargers, and DC-DC converters for electric vehicle platforms.
Power Supplies absorb the highest unit volumes. Automotive Systems follow the steepest expansion trajectory.
End User:
Geographic concentration of downstream manufacturing dictates regional sourcing patterns and technical support requirements.
- Consumer Electronics:Smartphone chargers, laptop adapters, and white goods requiring sub-100V Schottky and ultrafast silicon diodes. Design activity clusters in Taiwan and South Korea where original design manufacturers specify cost-optimized discrete solutions.
- Industrial Equipment:Welding machines, CNC drives, and uninterruptible power supplies demanding 600V-1200V fast recovery devices.
- Telecommunications:Base station power amplifiers and data center rectifiers with 48V bus architectures.
- Power Electronics:Specialized inverter and converter manufacturers serving grid-scale storage and electric vehicle charging infrastructure.
Industrial Equipment channels the majority of mature-product demand. Power Electronics is expanding most quickly behind grid-scale battery storage deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive electronics corridor around Munich and Stuttgart anchors procurement concentration for silicon carbide power diodes. Regulatory pressure from EU F-Gas Regulation and REACH compliance is reshaping substrate qualification programs. Foundry capacity allocation for 800V platform architectures is tightening across European supply chains.
Germany
OEM procurement for 800V traction inverters and onboard chargers is accelerating design-in cycles from 36 to 18 months. EU F-Gas Regulation amendments mandate fluorine-free cleaning chemistries in substrate processing. Munich-Stuttgart clustering concentrates technical support infrastructure and multi-year die supply negotiations.
United States
Data center power supply upgrades and electric vehicle manufacturing expansion are absorbing 1200V SiC diode volumes. FCC electromagnetic compatibility rules shape qualification timelines for grid-connected inverter products. Texas and Arizona fab investments are attracting packaging and test facility co-location.
China
Domestic electric vehicle production exceeding internal combustion output is pulling wide-bandgap diode demand. GB standards for grid-connected inverters mandate specific efficiency thresholds and electromagnetic compatibility testing. Yangtze River Delta contract manufacturers are specifying cost-optimized silicon solutions below 600V.
Japan
Industrial motor system efficiency mandates from METI are redirecting procurement toward fast recovery and SiC hybrid configurations. Domestic automotive semiconductor supply chains prioritize captive wafer supply for traction applications. Kyushu and Nagoya manufacturing bases sustain packaging integration capabilities.
South Korea
Battery electric vehicle platform ramp-ups from Hyundai-Kia are consuming 650V-1200V diode modules. MFDS-aligned substance disclosure frameworks extend qualification timelines for new package materials. Seoul Capital Area design houses are driving specification activity for consumer electronics adapters.
Power Diode Market Vendor Landscape
Long-term supply agreement negotiations dominate the current landscape as automotive OEMs bypass traditional distribution channels. The vendor base stratifies across three tiers: integrated device manufacturers with captive SiC crystal growth, fabless specialists leveraging foundry partnerships, and discrete packaging houses serving cost-sensitive industrial segments. Technology licensing and backward integration into epitaxy capacity represent the two most visible competitive vectors.
Among European-integrated device manufacturers, Infineon Technologies AG and STMicroelectronics occupy positions anchored by automotive qualification heritage and module packaging capabilities. STMicroelectronics exemplifies the integrated-module archetype capturing margin from bare die through system-level solutions. Infineon Technologies AG represents the captive-supply archetype with in-house SiC crystal growth securing automotive customer commitments. ROHM Semiconductor sits within the Japanese specialist tier with historical positioning in wide-bandgap materials.
| Leading Market Players |
|---|
| onsemi |
| STMicroelectronics |
| Nexperia |
| Diodes Incorporated |
| Vishay Intertechnology |
| ROHM Semiconductor |
| Infineon Technologies AG |
| Renesas Electronics |
| Shindengen Electric Manufacturing Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Silicon carbide wafer spot prices cascade through three-tier pricing structures across premium, standard, and economy levels, compressing margins for fabless packaging houses while integrated device manufacturers with captive crystal growth capture widening spreads. Automotive OEMs in Germany's Munich-Stuttgart corridor leverage multi-year die supply agreements to lock input costs against substrate volatility, feeding cost pass-through pressure downstream to Tier-1 inverter suppliers.
Pricing Analysis
Input-cost pass-through from 150mm SiC substrate scarcity stratifies pricing across automotive-qualified die, industrial-grade discrete devices, and consumer electronics rectifiers. Price differentiation hinges on AEC-Q101 certification tier and volume scale, with single-source automotive contracts commanding premiums against spot-market industrial procurement. Pricing pressure stems from foundry competition for epitaxy capacity as 800V platform ramp-ups absorb available output. Consumer electronics adapters below 100V exhibit highest price sensitivity, while traction inverter programs demonstrate lowest elasticity due to qualification lock-in.
Supply Chain Analysis
Power electronics engineering talent scarcity in Germany, Japan, and the United States constrains product development velocity across substrate processing and module packaging stages. Raw material dependencies center on high-purity silicon carbide boules, fluorine-free cleaning chemistries for EU F-Gas Regulation compliance, and specialized ceramic substrates for high-temperature packaging. Single-source vulnerability concentrates in 150mm SiC wafer supply among specialized crystal producers. Distribution runs through direct OEM contracting displacing traditional semiconductor distribution for automotive-qualified die.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in power diodes rests on silicon carbide cost-down curves and the premium-tier shift toward 1200V+ automotive-qualified modules. Captive substrate supply and integrated packaging capabilities widen spread capture for incumbents while fragmenting access for fabless competitors.
For Market Incumbents: Lock in multi-year epitaxy capacity reservations with foundry partners to defend against gallium nitride displacement in sub-100V adapters. Deepen backward integration into SiC crystal growth to secure supply autonomy as EU F-Gas Regulation tightens substrate qualification timelines. Prioritize module packaging R&D to capture margin from bare die through system-level solutions.
For New Entrants and Emerging Players: Enter via grid-scale battery storage inverters, an underpenetrated application segment for 1700V SiC diode modules lacking entrenched supplier relationships. Target Japan's industrial motor drive retrofit market where METI efficiency mandates redirect procurement toward fast recovery and SiC hybrid configurations. Pursue licensing agreements with established substrate fabs to bypass capital-intensive boule growth requirements.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap packaging specialists possessing AEC-Q101 certification infrastructure and unfilled capacity in automotive corridor geographies. Long-term viability favors targets with demonstrated design-in velocity compression from 36 to 18 months. Monitor foundry capacity allocation announcements for 800V platform architectures as inflection indicators for SiC demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Direct OEM contracting in Germany's automotive corridor secures multi-year die capacity against substrate volatility. |
| Backward Integration | Captive SiC crystal growth anchors supply security for automotive customers amid fluorine-free processing mandates. |
| Module Packaging Integration | System-level solutions from bare die capture margin expansion in 1200V traction inverter applications. |
| Regulatory Compliance Investment | EU F-Gas Regulation and REACH alignment accelerates substrate qualification programs across European supply chains. |
| Geographic Manufacturing Footprint | Texas and Arizona fab investments attract packaging and test facility co-location for data center and EV demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with power semiconductor procurement managers, Tier-1 inverter platform engineers, substrate fab operations directors, and automotive electronics sourcing leads with secondary validation. SEC 10-K filings from integrated device manufacturers, customs data on SiC substrate trade flows, EU F-Gas Regulation implementation documents, and Japan METI efficiency mandate filings anchored bottom-up and top-down triangulation.
Segment-weighting across voltage tier, material technology, application intensity, and regional manufacturing concentration shaped analytical framework construction across the projection horizon. Modeled dimensions included breakdown rating thresholds, switching frequency requirements, automotive qualification status, and end-user industry vertical. CAGRs derived from production capacity buildout schedules, design-in cycle compression trends, and substitution elasticity estimates between silicon and wide-bandgap alternatives.
The model holds under stable foundry capacity allocation and gradual SiC cost-down curves; deviation in substrate supply disruptions or regulatory acceleration would shift trajectory. Forecasts reflect documented assumptions on technology substitution rates and geographic demand clustering. Practitioners should monitor 800V platform ramp-up announcements and fluorine-free processing chemistry adoption for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Asia Pacific Low Voltage Drives Market
Power Systems
Integrated UPS Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market
Power Systems
Telecom Battery Market
Power Systems
Global Flexible Batteries Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market
Power Systems
Pulse Generator Market
Power Systems
Global Automatic Voltage Stabilizer Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Europe Micro Inverter Market
Power Systems
Global Data Center Transformer Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Global Pin Fin Heat Sink for IGBT Market