
 Smart Tap Timer Market | 2026-2036
Smart Tap Timer Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Tap Timer Market Insights
Subscription-based hardware leasing is reconfiguring competitive entry barriers for smaller irrigation brands. Toro leverages its dealer network to sustain commercial-grade timer distribution across municipal contracts. Rain Bird Corporation anchors its position through backward integration into valve manufacturing, cutting supplier dependency. Holman competes aggressively in Australian retail channels with weather-responsive firmware as a standard feature.
Smart tap timers are electronically controlled water flow devices that connect to standard hose bibs or spigots, typically operating at pressures between 20 and 120 PSI with programmable scheduling via onboard processors or cloud-connected mobile interfaces. Their primary commercial purpose is to automate and meter water delivery for residential irrigation, aquarium systems, and pool maintenance while reducing manual intervention and waste. Smart timers with Wi-Fi connectivity capture the highest margin pools as households prioritize remote scheduling and weather integration, while Bluetooth variants serve cost-sensitive gardeners through simplified local control without infrastructure dependency. Mechanical timers retain volume in developing markets but face displacement where GSM-enabled units support agricultural micro-irrigation in bandwidth-constrained regions.
FCC certification governs wireless transmission protocols for timers sold in the United States, while the EPA WaterSense program mandates flow accuracy and leak-detection standards that shape product development roadmaps. REACH compliance in Europe restricts certain plastics and electronic components, forcing redesigns of housing materials and circuit board coatings. Stakeholders must monitor how fragmented municipal water restrictions across drought-affected states redefine the baseline feature set that consumers expect from connected irrigation hardware.
Market Dynamics
Subscription-based hardware leasing is reconfiguring competitive entry barriers for smaller irrigation brands, forcing established manufacturers to defend dealer relationships against asset-light challengers offering firmware-as-a-service.
Growth Catalysts
- EPA WaterSense Certification:North American flow-monitoring mandates push manufacturers toward precision metering capabilities, creating baseline feature expectations that accelerate replacement cycles.
- Australian Suburban Irrigation:Residential systems in drought-prone metropolitan corridors drive hardware demand as tiered water pricing structures reward automated conservation.
- Cellular Module Miniaturization:Low-power GSM chipsets enable agricultural micro-irrigation deployments in bandwidth-constrained regions previously unreachable by Wi-Fi-dependent units.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries control critical microcontroller fabrication, exposing timer manufacturers to allocation volatility and extended lead times.
- REACH Compliance Burden:European restrictions on halogenated flame retardants force housing material redesigns that extend product development timelines by 8-14 months.
- Mechanical Timer Substitution:Low-cost spring-wound alternatives retain volume in developing markets where electricity reliability undermines electronic unit value propositions.
Strategic Opportunities
- India Agricultural Micro-Irrigation:PM-KUSUM scheme subsidies for solar-powered drip systems create entry points for GSM-enabled timers in water-stressed Maharashtra and Gujarat farming belts.
- Utility Demand Response Integration:California IOU smart grid programs compensate households for irrigation load curtailment during peak events, opening recurring revenue streams beyond hardware sales.
- Bluetooth-to-Wi-Fi Bridge Convergence:Hybrid connectivity architectures serve cost-conscious gardeners today while preserving upgrade paths to cloud-dependent scheduling ecosystems.
Industry Challenges
- FCC Certification Timeline:Wireless protocol validation for 915 MHz ISM band devices averages 14-22 weeks, compressing seasonal product launch windows and straining working capital.
- Embedded Firmware Talent Scarcity:Real-time operating system expertise for ultra-low-power irrigation controllers concentrates in semiconductor hubs, forcing manufacturers into remote compensation wars.
- Legacy Hose Bib Standard Variation:Thread pitch and flow geometry differences across Australian, North American, and European plumbing fixtures fragment SKUs and inflate inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Tap Timer Market |
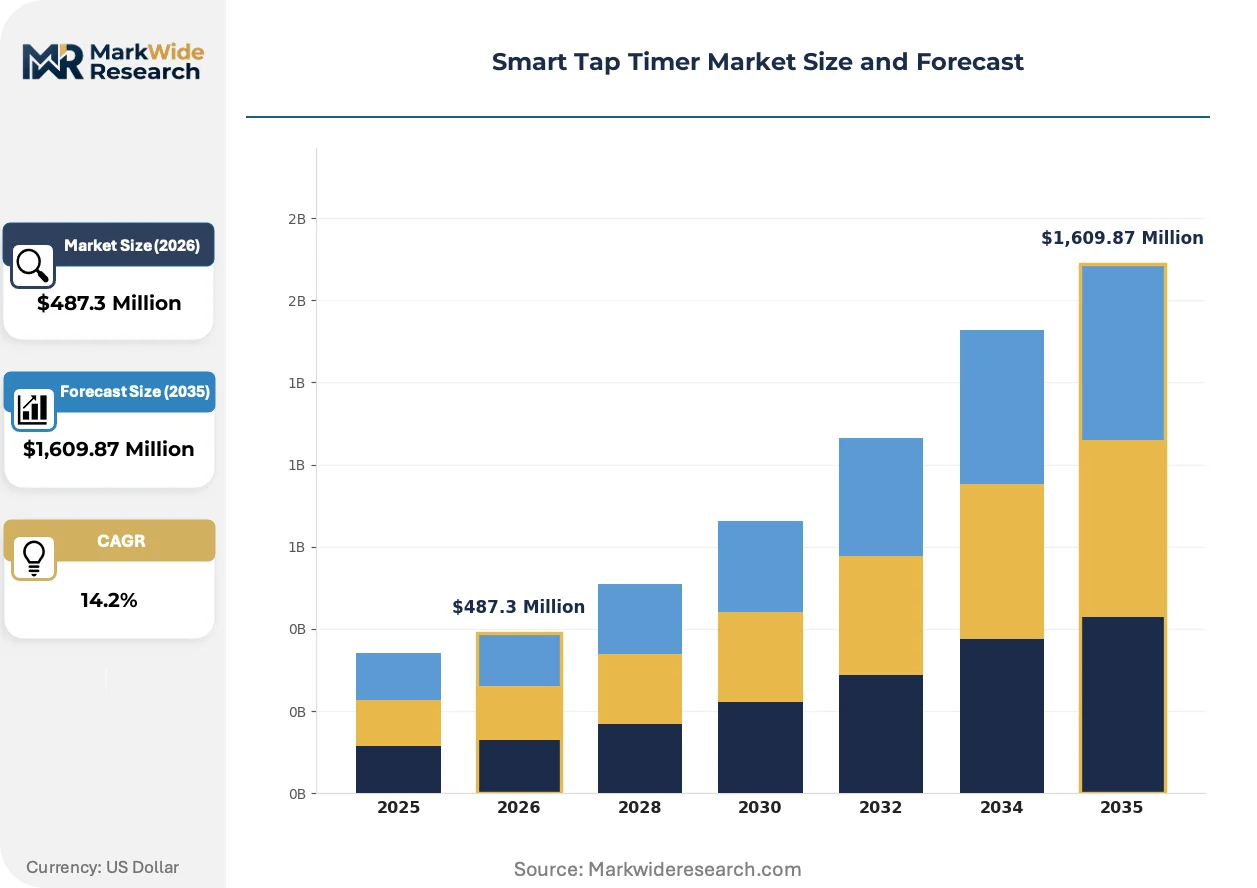
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Timers, Mechanical Timers, Smart Timers, Wireless Timers End User: Households, Gardeners, Professional Landscapers, Industrial Users Technology: Wi-Fi, Bluetooth, Zigbee, GSM Application: Irrigation, Aquariums, Home Automation, Pool Maintenance |
| Companies Covered | Toro, Orbit, Rain Bird Corporation, Hunter Industries, Melnor, Gardena, Hozelock, Holman, DIG Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Tap Timer Market Trends and Innovations
Connectivity architectures are fragmenting into purpose-built tiers as manufacturers abandon one-size-fits-all Wi-Fi strategies in favor of topology-matched solutions for distinct use cases and infrastructure constraints.
Mesh network protocols are hybridizing with traditional star topologies in premium residential controllers. California households with spotty router coverage adopt Thread-enabled timers that relay commands through border routers rather than direct cloud dependency. This architecture compresses support costs for manufacturers while enabling battery-operated endpoints previously impossible under Wi-Fi power budgets.
REACH enforcement is tightening scrutiny of recycled plastic feedstocks in European-bound housings. ECHA's 2024 updated restriction list forces manufacturers to document polymer chain-of-custody or switch to virgin ABS alternatives. German retail channels now demand third-party material certifications as standard procurement preconditions, filtering out Asian suppliers lacking laboratory documentation capabilities.
Leasing models are displacing outright purchase in Australian municipal conservation programs. Sydney Water's pilot subscription offering bundles hardware, cellular data, and predictive maintenance into per-hectare pricing. This procurement pattern shifts margin capture from upfront manufacturing to recurring service revenue, rewarding firmware-update capabilities over bill-of-materials cost engineering.
Smart Tap Timer Market Segmentation
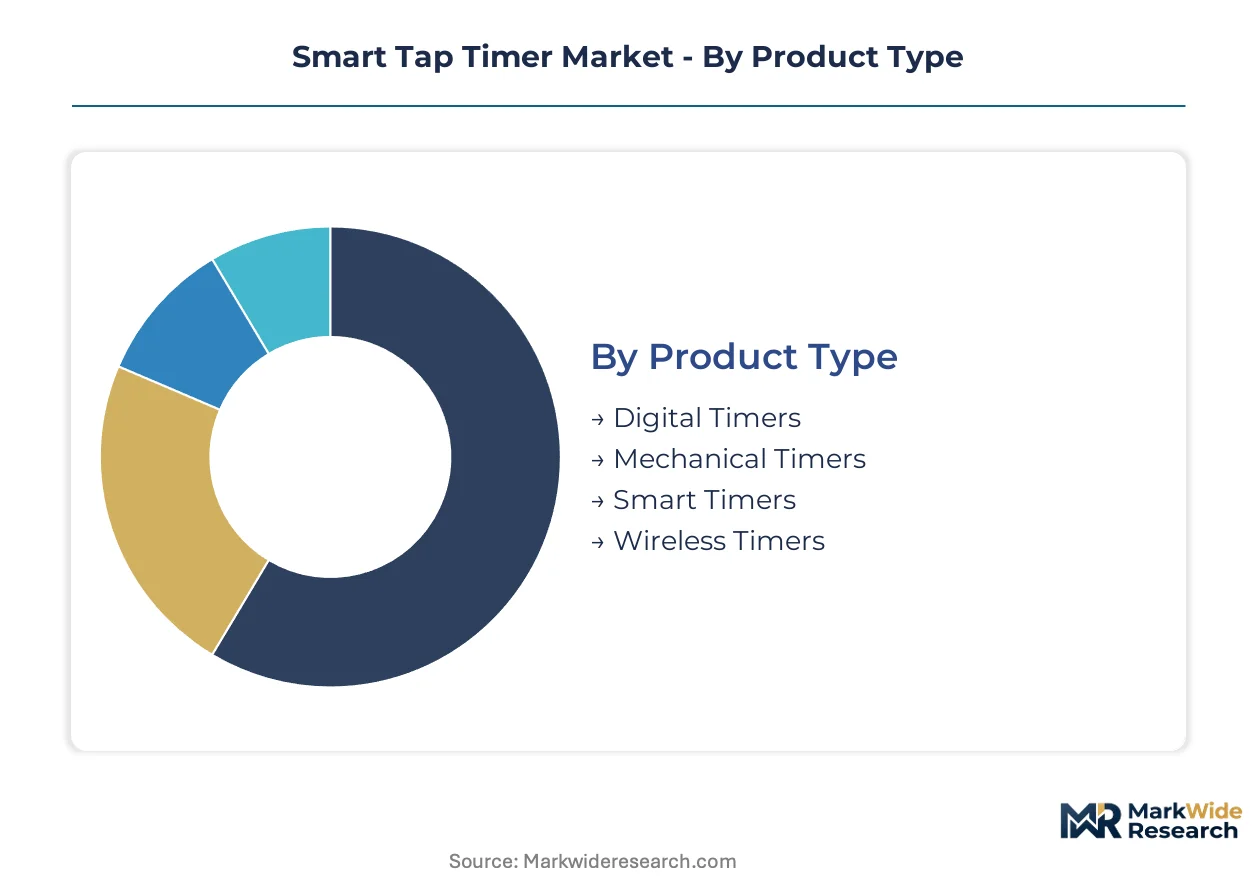
Segmentation in smart tap timers exposes divergent service intensity requirements. Wi-Fi-enabled units demand continuous cloud infrastructure support, while mechanical alternatives require minimal post-sale engagement, reshaping how manufacturers allocate field engineering resources.
Product Type:
After-sales-service intensity varies dramatically across product categories, with cloud-connected units requiring firmware update pipelines and cellular-enabled variants needing SIM provisioning support that mechanical alternatives never trigger.
- Smart Timers:Programmable units with onboard processors and mobile interfaces operating at 20-120 PSI. Demand concentrates in California's drought-prone metropolitan corridors where tiered water pricing accelerates automated conservation upgrades and EPA WaterSense certification becomes table stakes.
- Digital Timers:Electronically controlled devices with LCD displays and basic scheduling functions. Australian suburban irrigation systems drive hardware demand as weather-responsive firmware becomes standard in retail channels.
- Mechanical Timers:Spring-wound alternatives retaining volume in developing markets where electricity reliability undermines electronic value propositions.
- Wireless Timers:Radio-frequency units enabling remote operation without full cloud dependency.
Smart Timers holds the largest share; momentum sits with Digital Timers.
End User:
Cost tier stratification separates households seeking sub-$50 entry points from industrial buyers negotiating volume contracts with predictive maintenance clauses.
- Households:Residential consumers prioritizing remote scheduling and weather integration through Wi-Fi connectivity. California IOU smart grid programs compensate these users for irrigation load curtailment during peak events, opening recurring revenue streams beyond hardware sales.
- Gardeners:Cost-sensitive hobbyists favoring Bluetooth variants with simplified local control and no infrastructure dependency.
- Professional Landscapers:Commercial operators requiring fleet management capabilities and dealer network support for municipal contract fulfillment.
- Industrial Users:Agricultural and facility managers deploying GSM-enabled units for micro-irrigation in bandwidth-constrained regions.
Households holds the largest share; momentum sits with Professional Landscapers.
Technology:
Supply concentration in Taiwan-based foundries for microcontroller fabrication exposes manufacturers to allocation volatility across all connectivity architectures.
- Wi-Fi:Cloud-connected protocols capturing premium margin pools as households prioritize seamless mobile integration. FCC certification for 915 MHz ISM band devices averages 14-22 weeks, compressing seasonal launch windows.
- Bluetooth:Low-energy local control serving cost-conscious gardeners today while hybrid architectures preserve upgrade paths to cloud-dependent ecosystems.
- GSM:Cellular modules enabling agricultural micro-irrigation in Maharashtra and Gujarat farming belts under India's PM-KUSUM scheme subsidies.
- Zigbee:Mesh network protocols hybridizing with star topologies in premium residential controllers with spotty router coverage.
Wi-Fi holds the largest share; momentum sits with GSM.
Application:
Volume concentration in irrigation masks faster expansion trajectories in adjacent automation categories where integration with broader smart home ecosystems drives replacement cycles.
- Irrigation:Residential and agricultural water delivery automation representing the core commercial purpose. Sydney Water's pilot subscription offering bundles hardware, cellular data, and predictive maintenance into per-hectare pricing.
- Home Automation:Integration with broader connected device ecosystems including voice assistants and centralized hub platforms.
- Pool Maintenance:Chemical dosing and filtration scheduling requiring flow accuracy and leak-detection standards.
- Aquariums:Precision water change and circulation control for specialized hobbyist and commercial installations.
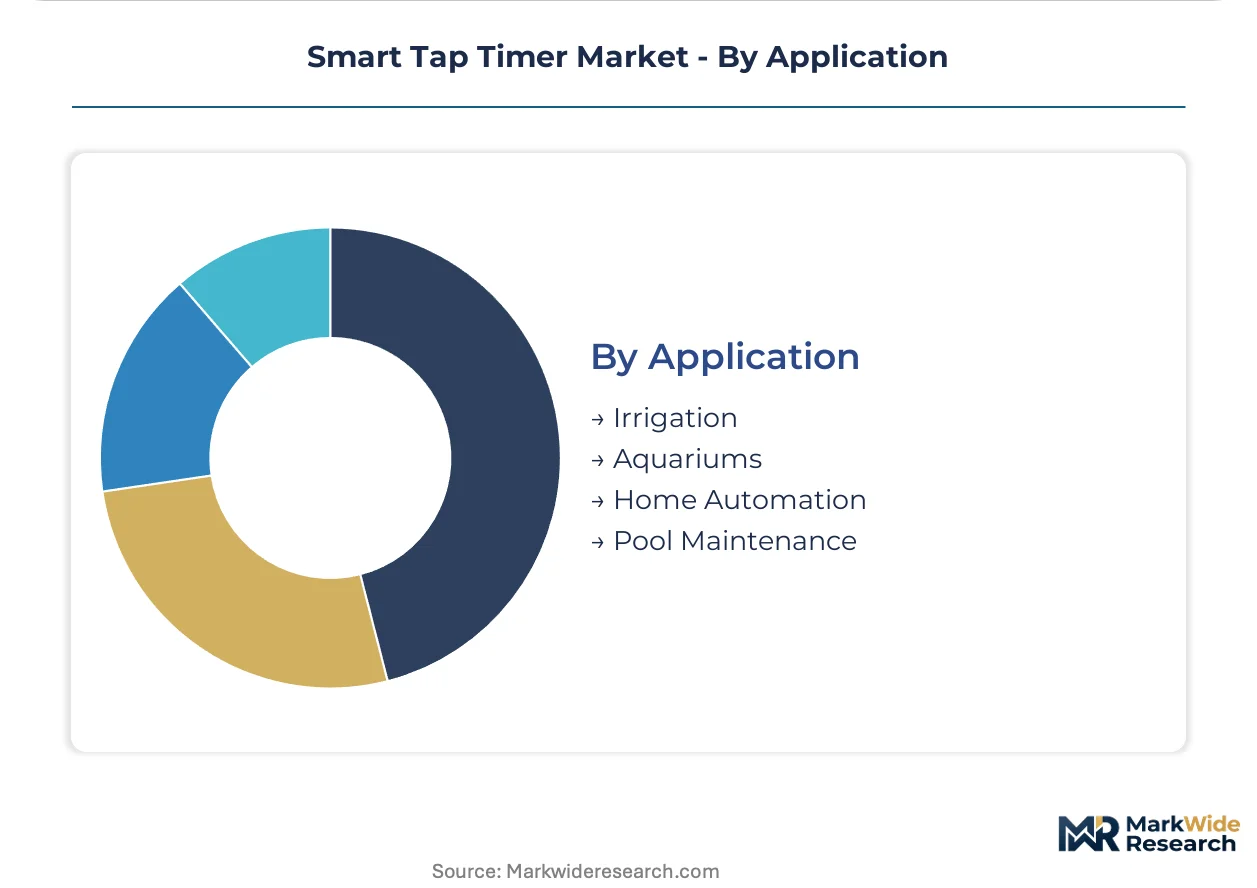
Irrigation holds the largest share; momentum sits with Home Automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in smart tap timers tilt toward deficit in water-stressed importing economies while manufacturing concentration in East Asian electronics clusters shapes supply availability. Trade patterns reflect divergent regulatory stringency rather than pure cost arbitrage.
United States
California's metropolitan corridors anchor hardware demand as tiered water pricing accelerates automated conservation upgrades. EPA WaterSense certification mandates flow accuracy standards that reshape product development roadmaps for North American-bound units. Los Angeles and San Diego retail channels concentrate replacement cycles around drought-declaration timing.
Australia
Suburban irrigation systems in Sydney and Melbourne drive residential hardware procurement as municipal conservation programs expand. Sydney Water's pilot subscription offering bundles hardware, cellular data, and predictive maintenance into per-hectare pricing. Melbourne's retail channels standardize weather-responsive firmware as baseline consumer expectation.
Germany
ECHA's 2024 updated restriction list forces polymer chain-of-custody documentation or virgin ABS alternatives for European-bound housings. German retail channels demand third-party material certifications as standard procurement preconditions. Stuttgart and Munich industrial clusters filter out Asian suppliers lacking laboratory documentation capabilities.
India
Maharashtra and Gujarat farming belts generate demand for GSM-enabled timers under PM-KUSUM scheme subsidies for solar-powered drip systems. The country's national irrigation regulator coordinates state-level micro-irrigation deployment targets. Pune and Ahmedabad manufacturing corridors assemble low-power cellular modules for agricultural export markets.
China
Domestic demand concentrates in Shandong and Jiangsu provinces where facility agriculture expansion requires precision water delivery automation. The Ministry of Industry and Information Technology governs wireless transmission protocol standards for connected irrigation hardware. Shenzhen electronics clusters fabricate low-power GSM chipsets for bandwidth-constrained regional markets.
Smart Tap Timer Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified irrigation conglomerates with captive distribution networks, specialized connectivity hardware firms with firmware-as-a-service capabilities, and regional fabricators competing on bill-of-materials cost engineering. Dominant competitive moves include backward integration into valve manufacturing to cut supplier dependency and subscription-based hardware leasing to capture recurring revenue streams beyond unit sales.
Among diversified irrigation conglomerates, Toro and Rain Bird Corporation exemplify the dealer-network archetype sustaining commercial-grade distribution across municipal contracts. Holman occupies a position within the regional-specialist tier competing aggressively in Australian retail channels. These three anchors represent divergent geographic emphases—North American, North American, and Asia-Pacific respectively—while converging on firmware-update capabilities as the critical service differentiator.
| Leading Market Players |
|---|
| Toro |
| Orbit |
| Rain Bird Corporation |
| Hunter Industries |
| Melnor |
| Gardena |
| Hozelock |
| Holman |
| DIG Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Taiwan-based microcontroller foundries is compressing supplier pricing power while simultaneously inflating input costs for timer manufacturers, creating asymmetric margin pressure across connectivity tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on EPA WaterSense certification grade and after-sales firmware support intensity. Pricing pressure stems from REACH compliance-driven material redesigns extending development timelines. Municipal contract buyers exhibit lowest price sensitivity; retail gardeners in developing markets show highest elasticity.
Supply Chain Analysis
Tariff exposure between China and North America dominates supply chain risk calculations for electronics-heavy timer assemblies. Manufacturing concentrates in China, Taiwan, and South Korea for microcontroller fabrication and cellular module production. Raw material dependencies include ABS polymer housings, low-power GSM chipsets, and halogen-free flame retardant compounds. Single-source vulnerability in Taiwan-based foundries threatens allocation stability. Distribution runs through dealer networks for commercial-grade units and big-box retail for consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where EPA WaterSense certification creates switching costs that lock municipal buyers into validated supplier relationships.
For Market Incumbents: Build certification moats by accelerating EPA WaterSense validation pipelines and securing exclusive dealer network lock-ups in California metropolitan corridors. Threat of firmware-as-a-service entrants from asset-light challengers demands preemptive backward integration into valve manufacturing. Leverage vertical control over critical components to compress lead times during Taiwan foundry allocation crunches. For New Entrants and Emerging Players: Build out white-space positions in India's Maharashtra and Gujarat agricultural belts where PM-KUSUM subsidies for solar-powered drip irrigation create unguarded entry points. GSM-enabled micro-irrigation timers face minimal incumbent saturation. Pursue cellular-module miniaturization partnerships with Shenzhen electronics clusters to bypass Wi-Fi infrastructure dependencies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based hardware leasing providers bundling predictive maintenance and cellular data services. Long-term viability favors asset-light platforms over bill-of-materials engineering shops. Target acquisition archetypes include firmware-as-a-service specialists with proven over-the-air update pipelines. Watch Sydney Water's per-hectare pricing pilot as the signal indicating municipal procurement pattern shifts toward service-based models.| Strategic Initiative | Industry Significance |
|---|---|
| EPA WaterSense Certification Investment | Validates flow accuracy for California municipal contracts and accelerates replacement cycles. |
| Backward Integration into Valve Manufacturing | Reduces supplier dependency for Rain Bird Corporation and Toro commercial-grade distribution. |
| Cellular Module Miniaturization Partnership | Enables GSM-enabled deployments in Maharashtra and Gujarat bandwidth-constrained farming belts. |
| Subscription Hardware Leasing Launch | Shifts margin capture from upfront manufacturing to recurring service revenue per Sydney Water pilot. |
| REACH-Compliant Material Redesign | Documents polymer chain-of-custody for German retail channel procurement preconditions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EPA WaterSense certification databases, ECHA restriction lists, and customs trade records. Irrigation equipment executives, municipal water utility procurement officers, cellular module engineers, and retail channel buyers provided structured input. Bottom-up unit shipment estimates triangulate against top-down market sizing across connectivity architectures and end-use segments.
Forecast inputs span product type segmentation, technology tier stratification, application intensity, and regional regulatory cluster variations over the projection horizon. CAGRs derive from historical replacement cycle analysis, tiered water pricing adoption curves, and cellular infrastructure penetration trajectories. Modeled variables include semiconductor allocation volatility, REACH compliance timeline extensions, and drought-declaration frequency in California metropolitan corridors.
Stress conditions across Taiwan foundry capacity utilization, ECHA polymer restriction enforcement, and California IOU demand response program participation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about firmware update adoption and municipal subscription procurement elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Qatar Agriculture Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market