
 Asia-Pacific Smart Agriculture Market | 2026-2036
Asia-Pacific Smart Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Agriculture Market Analysis
Large-scale agribusiness is shifting toward automated crop management systems across the Asia-Pacific region. Deere & Company leverages its precision agriculture portfolio to anchor premium equipment sales in Australia and Japan. Kubota Corporation dominates compact mechanization segments tailored to East Asian smallholder terrain. Trimble Inc. competes through GNSS-guided solutions that extend across diverse topographies from India's Deccan Plateau to New Zealand's Canterbury Plains.
Asia-Pacific smart agriculture integrates sensor networks, autonomous machinery, and data analytics platforms to optimize input efficiency and output predictability across climatic zones. The primary commercial purpose centers on reducing water, fertilizer, and labor intensity while stabilizing yields against monsoon variability and heat stress. Precision farming occupies the largest value share as variable-rate application technology matures across Australian broadacre operations. AI Analytics represents the fastest-expanding technology segment as cloud-based yield prediction models penetrate Indian cooperative networks. Livestock Monitoring sustains margin concentration in Japan and South Korea where dairy and pork sectors face labor shortages and biosecurity pressures.
Japan's METI promotes agricultural robot deployment through targeted subsidy frameworks, while Australia's central bank and rural development bodies shape credit access for technology-intensive farm upgrades. India's CEA and DGFT coordinate import policy for drone components under evolving unmanned aerial vehicle regulations. Stakeholders must weigh localization requirements against scale economies as national regulators tighten data sovereignty rules for farm-level IoT telemetry.
Market Dynamics
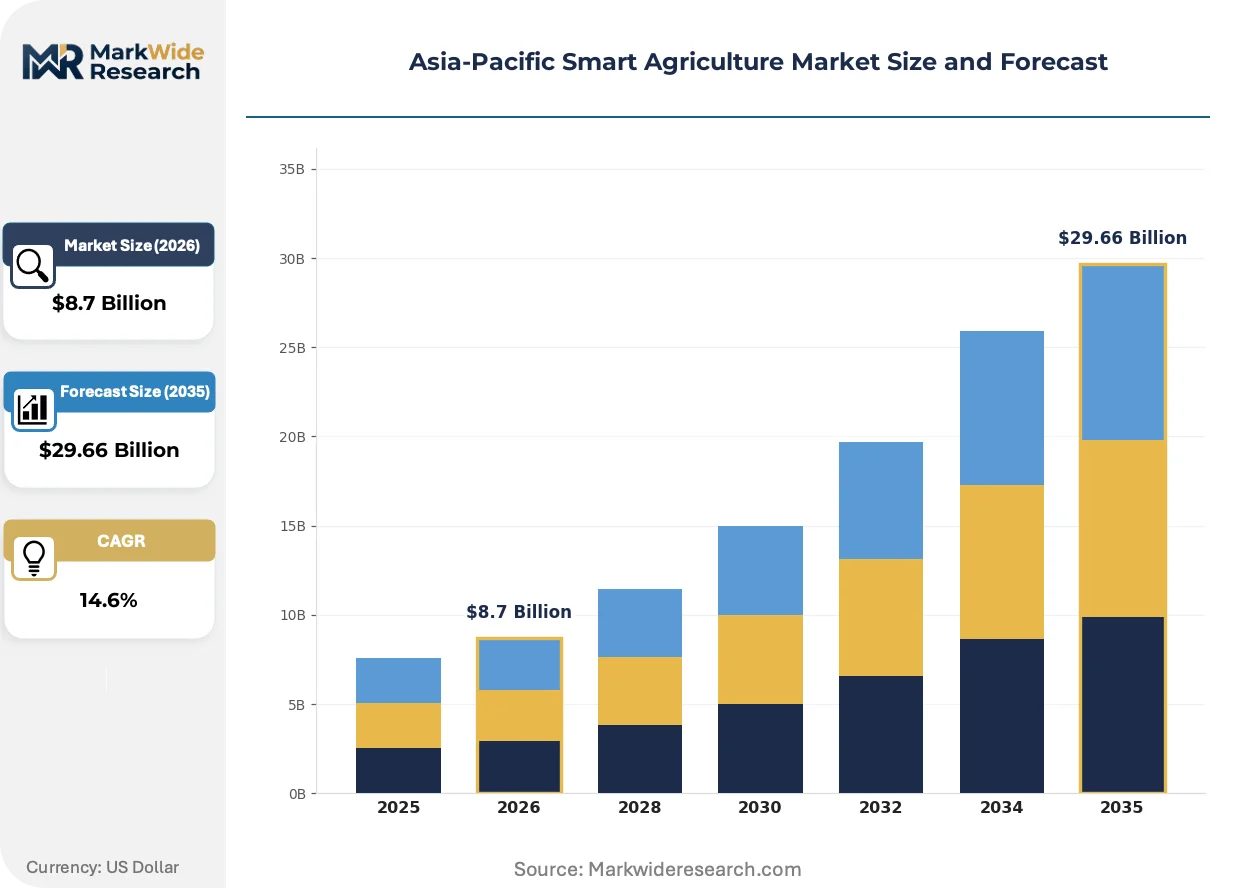
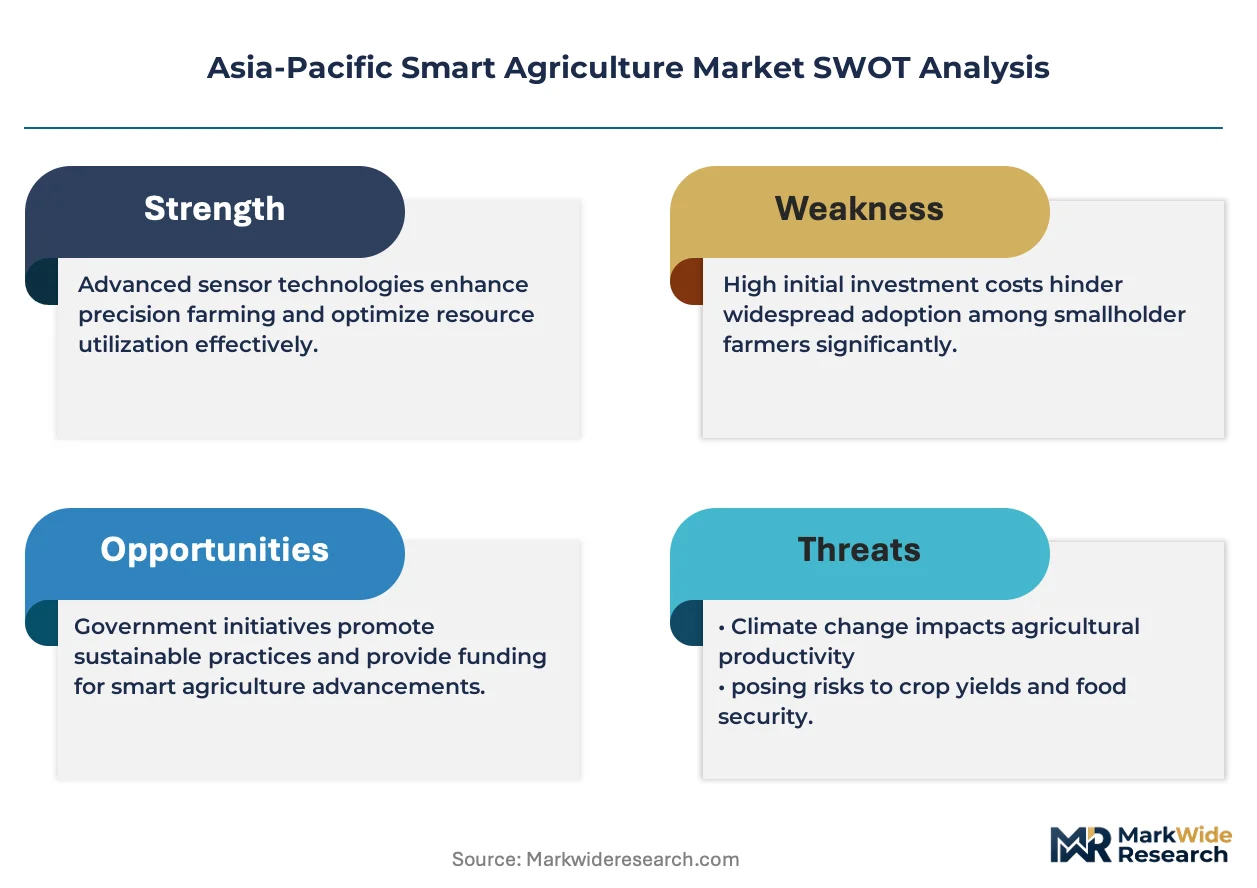
Climate volatility and labor scarcity across Asia-Pacific are compressing payback periods for autonomous field machinery, accelerating capital deployment into sensor-driven irrigation and robotic harvest systems that reduce dependency on seasonal workforce availability.
Growth Catalysts
- India's PLI Scheme:The production-linked incentive framework for agricultural technology is scaling domestic manufacturing capacity for IoT-enabled equipment, reducing import dependency for drone components and precision sensors.
- Australian Broadacre Mechanization:Large-scale wheat and barley operations are deploying variable-rate application systems across Western Australia and New South Wales to optimize fertilizer deployment amid input cost pressures.
- Japan's METI Subsidy Framework:Targeted fiscal support for agricultural robot deployment is accelerating adoption of autonomous tractors and robotic milking systems in Hokkaido dairy and Tohoku rice operations.
Market Restraints
- Semiconductor Supply Concentration:GNSS modules and edge-computing chips for field equipment depend heavily on Taiwan and South Korea fabrication capacity, exposing equipment lead times to geopolitical friction.
- Smallholder Land Fragmentation:Average plot sizes below two hectares across India, Vietnam, and Indonesia limit returns on precision farming hardware designed for contiguous large-acreage deployment.
- Data Sovereignty Compliance Costs:China's Personal Information Protection Law and India's draft Digital Personal Data Protection Bill impose localization mandates for farm telemetry storage, raising cloud infrastructure expenditure for platform providers.
Strategic Opportunities
- Vertical Farming Clusters:China's eastern provinces are mandating urban food security infrastructure around Shanghai and Hangzhou, creating concentrated demand for climate-controlled greenhouse automation and hydroponic nutrient management systems.
- Livestock Biosecurity Integration:South Korea's pork sector is adopting AI-powered health monitoring to address African swine fever containment requirements, opening sensor-to-veterinary-platform data pipelines.
- Cooperative Data Pools:Indian farmer producer organizations are aggregating yield and weather data to train localized prediction models, lowering per-farmer analytics subscription costs through collective bargaining.
Industry Challenges
- Agronomic Data Science Talent Gap:Interdisciplinary expertise combining crop science, sensor engineering, and cloud architecture remains scarce across Australia and Japan, constraining platform customization for regional crop varieties.
- Legacy Equipment Interoperability:Retrofitting fifteen-to-twenty-year-old tractors and harvesters with ISOBUS-compliant telematics requires proprietary adapter hardware that fragments fleet management dashboards.
- Drone Pilot Certification Backlogs:India's DGFT unmanned aerial vehicle regulations create multi-month licensing delays for agricultural spraying operators, throttling service provider expansion during critical planting windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Agriculture Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precision Farming, Livestock Monitoring, Smart Greenhouses, Fish Farming Technology: IoT Devices, Drones, AI Analytics, Robotics End User: Farmers, Agribusinesses, Research Institutions, Government Agencies Application: Crop Management, Soil Health Monitoring, Yield Prediction, Irrigation Management |
| Companies Covered | Deere & Company, Trimble Inc., Topcon Positioning Systems, AGCO Corporation, Raven Industries, AgJunction Inc., GEA Group Aktiengesellschaft, Kubota Corporation, Ag Leader Technology, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Agriculture Market Emerging Trajectories
Sensor fusion and edge AI are compressing decision latency in field operations, shifting competitive advantage from hardware durability toward real-time analytics accuracy and predictive maintenance reliability across diverse Asia-Pacific cropping systems.
Hyperspectral imaging mounted on unmanned aerial platforms is consolidating crop stress detection workflows. Australian cotton growers and Japanese tea cooperatives are adopting these systems at three-year replacement cycles for visual scouting teams. The technology is consolidating agronomic advisory services into bundled subscription models that tie imagery analytics to input procurement.
Japan's METI subsidy framework for agricultural robot deployment is mandating JIS-standard interoperability protocols. Equipment manufacturers must certify autonomous navigation systems against collision-avoidance benchmarks before accessing fiscal support. Dairy and greenhouse segments in Gunma and Ibaraki prefectures are restructuring procurement specifications around these certified platforms.
Cooperative purchasing consortia are displacing individual farm capital expenditure across India's Maharashtra and Karnataka states. Farmer producer organizations aggregate precision equipment orders to secure volume pricing and shared technical support, unbundling manufacturer service contracts into third-party maintenance pools. This reconfiguration concentrates buyer power in districts with established cooperative infrastructure.
Asia-Pacific Smart Agriculture Market Segmentation
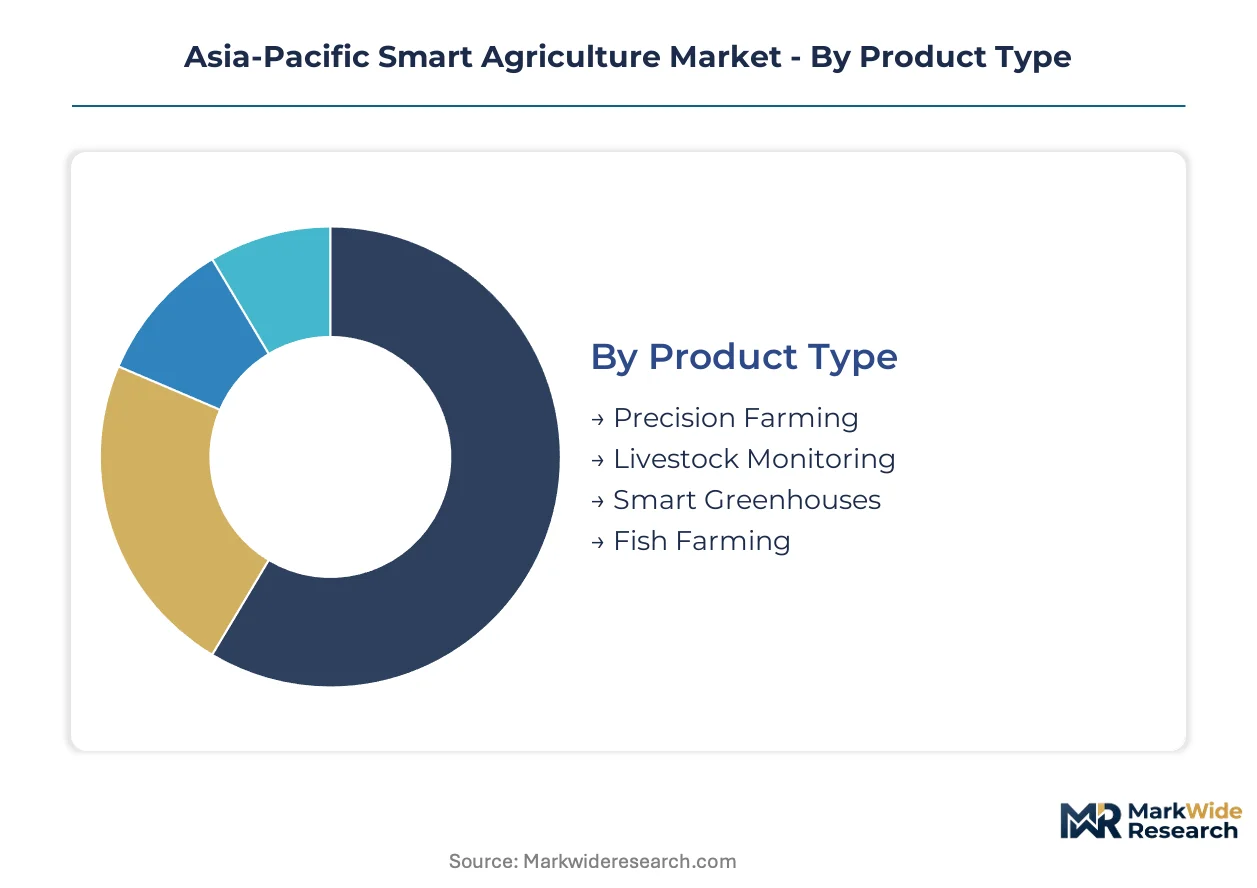
Smart agriculture deployment across Asia-Pacific follows distinct capital intensity profiles. Equipment-heavy segments demand substantial upfront investment in hardware and connectivity infrastructure, while software-centric categories scale through subscription models with lower entry barriers.
Product Type:
Capital intensity varies sharply across product categories, with autonomous machinery requiring the heaviest infrastructure commitment.
- Precision Farming:Variable-rate application systems, GNSS-guided tractors, and sensor networks dominate Australian broadacre wheat and barley operations. Japanese rice cooperatives in Tohoku are consolidating procurement around shared telemetry platforms to amortize hardware costs across member farms.
- Livestock Monitoring:AI-powered health sensors and robotic milking systems address acute labor shortages in Hokkaido dairy and South Korean pork operations. Biosecurity mandates from Japan's Ministry of Agriculture are accelerating sensor-to-veterinary data pipeline investments.
- Smart Greenhouses:Climate-controlled infrastructure clusters around Shanghai and Hangzhou serve urban food security mandates.
- Fish Farming:Automated feeding and water quality monitoring systems penetrate Indonesian and Vietnamese aquaculture zones.
Most installed capacity flows through Precision Farming. Expansion is steepest in Livestock Monitoring.
Technology:
Technology selection tracks farm scale and digital maturity, with large agribusinesses favoring integrated platforms while smallholders adopt modular point solutions.
- IoT Devices:Soil moisture sensors, weather stations, and livestock wearables form the connectivity backbone. Indian farmer producer organizations in Maharashtra aggregate telemetry data to train localized prediction models, lowering per-farmer subscription costs through cooperative bargaining structures.
- AI Analytics:Cloud-based yield prediction and input optimization algorithms penetrate cooperative networks fastest. Australian cotton growers subscribe to bundled advisory services that tie imagery analytics to fertilizer procurement decisions.
- Drones:Multi-spectral and hyperspectral aerial platforms consolidate visual scouting workflows.
- Robotics:Autonomous tractors and harvesters face deployment constraints from land fragmentation across India and Southeast Asia.
IoT Devices capture the broadest installed base. AI Analytics is climbing the fastest as cloud infrastructure costs decline.
End User:
End-user economics diverge between consolidated agribusiness buyers and fragmented smallholder segments with limited capital access.
- Agribusinesses:Large-scale operators across Western Australia and New South Wales deploy enterprise-grade fleet management systems with ISOBUS-compliant telematics. These buyers negotiate volume pricing and demand multi-year service level agreements from equipment suppliers.
- Farmers:Individual smallholders below two-hectare averages in India and Indonesia rely on cooperative purchasing consortia and third-party spraying services to access precision technology without direct capital expenditure.
- Research Institutions:Agricultural universities and extension services pilot varietal-specific algorithms.
- Government Agencies:Japan's METI and India's CEA shape adoption through subsidy frameworks and import policy coordination.
Agribusinesses command the largest transaction values. Farmers represent the deepest volume pool through cooperative aggregation.
Application:
Application prioritization reflects regional resource constraints, with water-scarce zones emphasizing irrigation optimization and labor-short markets automating field operations.
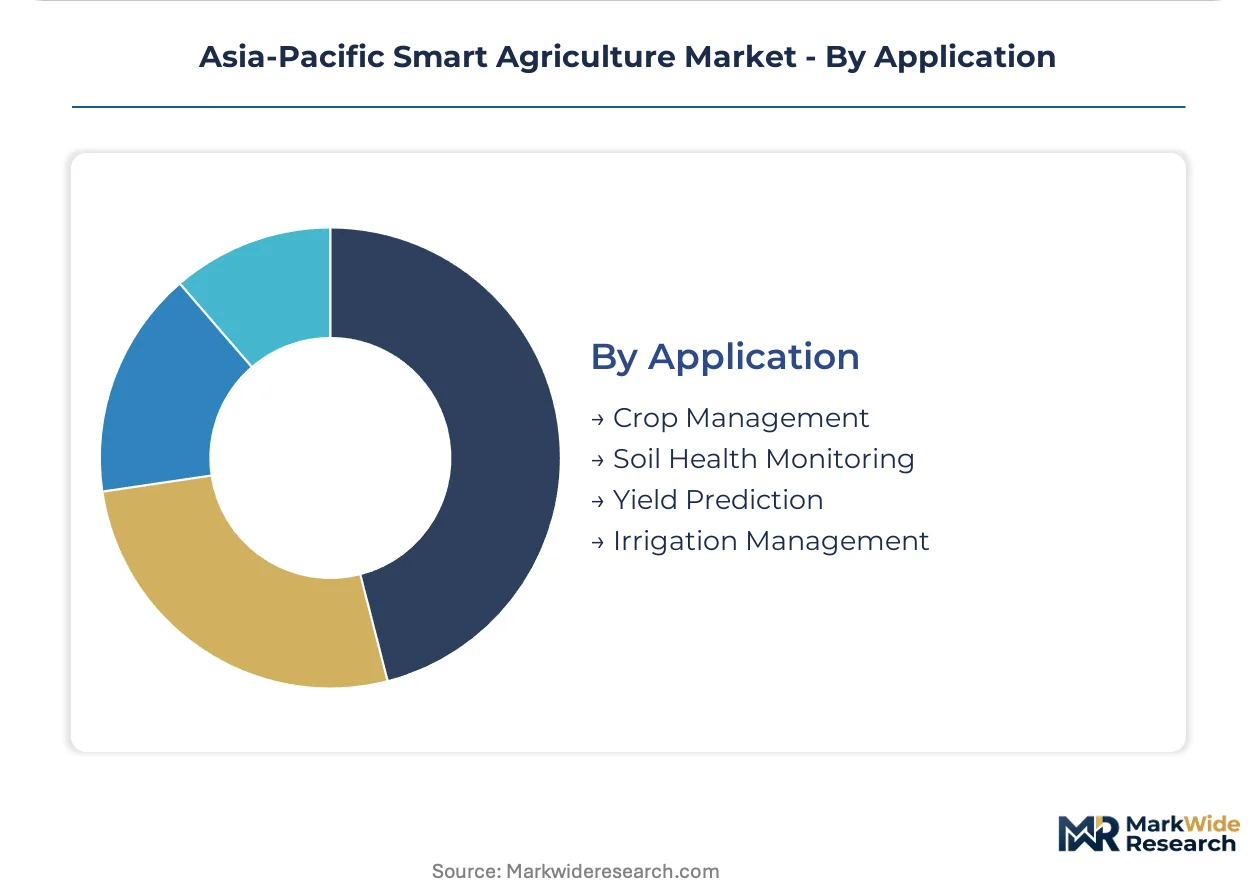
- Irrigation Management:Sensor-driven drip and pivot systems reduce water intensity in Australian cotton and Indian sugarcane belts. Deccan Plateau farmers deploy soil moisture telemetry to time supplemental watering during monsoon gaps.
- Crop Management:Autonomous machinery and variable-rate application technology mature fastest in contiguous broadacre terrain.
- Soil Health Monitoring:Electrochemical and spectroscopic sensors track nutrient depletion patterns.
- Yield Prediction:Satellite and drone imagery analytics consolidate into bundled subscription offerings.
Irrigation Management absorbs the heaviest technology investment. Crop Management is gaining share fastest as robotics costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting smart agriculture manufacturing toward jurisdictions with subsidized component assembly and lighter data-compliance burdens. India's PLI scheme and China's localization mandates are pulling equipment production away from higher-cost assembly bases, reshaping regional supply footprints.
China
Vertical farming clusters in Shanghai and Hangzhou are absorbing automated greenhouse systems under urban food security mandates. MIIT coordinates domestic manufacturing quotas for IoT sensors and autonomous machinery components. The Yangtze River Delta hosts concentrated smart greenhouse deployment serving municipal procurement contracts.
Japan
Hokkaido dairy operations and Tohoku rice cooperatives are deploying robotic milking and autonomous tractors amid acute rural labor shortages. METI subsidy frameworks mandate JIS-standard interoperability certification for equipment accessing fiscal support. Gunma and Ibaraki prefectures are restructuring procurement specifications around these certified platforms.
India
Maharashtra and Karnataka farmer producer organizations are aggregating precision equipment orders through cooperative purchasing consortia. The CEA and DGFT coordinate import policy for drone components under evolving unmanned aerial vehicle regulations. The Deccan Plateau is seeing concentrated soil moisture telemetry deployment for supplemental irrigation timing.
Australia
Western Australia and New South Wales broadacre wheat and barley operations are deploying variable-rate application systems to optimize fertilizer deployment. The country's rural development bodies shape credit access for technology-intensive farm upgrades. The Canterbury Plains region is consolidating GNSS-guided fleet management across large-scale agribusiness holdings.
South Korea
Pork sector operations are adopting AI-powered health monitoring to address African swine fever containment requirements. MFDS biosecurity mandates are accelerating sensor-to-veterinary data pipeline investments. The country's dairy and livestock zones are restructuring around integrated health monitoring platforms.
Asia-Pacific Smart Agriculture Market Vendor Landscape
Strategic partnerships dominate the current landscape as equipment manufacturers ally with cloud analytics providers to bundle hardware subscriptions with predictive software. The vendor base splits between diversified agricultural machinery conglomerates and specialized precision-technology firms. Three archetypes prevail: full-stack equipment integrators, component-focused sensor specialists, and platform-agnostic analytics providers. Geographic expansion and technology licensing are the dominant competitive moves as firms seek access to subsidized manufacturing bases and cooperative distribution channels.
Among Japan-based machinery conglomerates, Kubota Corporation exemplifies the compact-mechanization archetype tailored to East Asian smallholder terrain. Deere & Company anchors the premium-equipment tier for Australian and Japanese broadacre markets. Trimble Inc. occupies a position exemplifying GNSS-guided solution providers extending across diverse topographies from India's Deccan Plateau to New Zealand's Canterbury Plains.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| Topcon Positioning Systems |
| AGCO Corporation |
| Raven Industries |
| AgJunction Inc. |
| GEA Group Aktiengesellschaft |
| Kubota Corporation |
| Ag Leader Technology |
| Others |
Supply Flow & Price Mechanics
Semiconductor wafer price indices cascade through three distinct equipment pricing tiers across the Asia-Pacific smart agriculture value chain, compressing margins for mid-market sensor manufacturers while concentrating premium pricing power with integrated platform providers serving Australian broadacre operators.
Pricing Analysis
Distributor margins of 15-25 percent separate OEM direct pricing from retail channel quotes for precision farming hardware. Three-tier pricing structure across premium, standard, and economy levels stratifies by telemetry integration depth and ISOBUS certification status. Cost compression in economy-tier IoT sensors is intensifying because Indian farmer producer organizations aggregate volume orders for shared equipment pools. Smallholders in Vietnam and Indonesia exhibit acute price sensitivity, while Australian agribusinesses prioritize multi-year service level agreements over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Western Australian wheat operations and Hokkaido dairy cooperatives, bypassing distributor markups for autonomous machinery fleets. Component fabrication concentrates in Taiwan, South Korea, and China, with GNSS modules and edge-computing chips drawing from TSMC and Samsung foundry capacity. Single-source vulnerability in Taiwan Strait logistics threatens equipment lead times for Japanese METI-subsidized robot deployments. Distribution runs through cooperative purchasing consortia in India's Maharashtra and Karnataka states, aggregating smallholder demand into manufacturer-negotiable volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific smart agriculture market functions as a stable compounder, with India's PLI scheme and Japan's METI subsidy frameworks institutionalizing technology replacement cycles that sustain equipment demand through climatic and commodity cycles.
For Market Incumbents: To counter modular point-solution entrants unbundling precision farming platforms, Deere & Company and Kubota Corporation should deepen backward integration into edge-computing chip design, securing supply continuity against Taiwan Strait disruption. Certification investment in JIS-standard interoperability protocols locks in METI subsidy access and raises rival compliance costs.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in livestock monitoring hardware opens white-space targeting of South Korean pork sector biosecurity mandates, where MFDS regulations accelerate sensor-to-veterinary platform demand. Cooperative data pool partnerships in India's Deccan Plateau offer the most penetrable entry vector, with third-party maintenance service contracts providing recurring revenue without capital-intensive manufacturing scale.
For Investors and Strategic Acquirers: Asymmetric upside sits with platform-agnostic analytics providers unburdened by hardware inventory cycles, positioned for acquisition by machinery conglomerates seeking software subscription revenue. Over a multi-year horizon, cooperative infrastructure density in specific Indian districts signals scalable addressable market expansion ahead of equipment saturation. Watch DGFT drone pilot certification processing velocity as inflection indicator for aerial spraying service provider rollout timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge Computing | Captive chip supply secures production continuity against Taiwan Strait logistics chokepoints. |
| JIS Interoperability Certification | Unlocks METI subsidy access for autonomous navigation systems in Gunma prefecture deployments. |
| Cooperative Data Pool Partnerships | Maharashtra farmer producer organizations aggregate telemetry to train localized yield prediction models. |
| Biosecurity Sensor-to-Veterinary Pipelines | MFDS mandates in South Korea's pork sector create regulatory-compelled demand for health monitoring platforms. |
| Third-Party Maintenance Pool Structuring | Unbundles manufacturer service contracts into shared technical support networks across Karnataka smallholders. |
Methodological Framework
Bottom-up cooperative purchasing volume modeling reconciled against top-down machinery shipment tracking forms the analytical core of this study. Primary interviews with precision agriculture platform engineers, OEM procurement leads at Deere and Kubota, farmer producer organization coordinators in Maharashtra, and METI subsidy program administrators combined with secondary validation from DGFT unmanned aerial vehicle regulation filings, Australian Bureau of Agricultural and Resource Economics data, and Japan's Ministry of Agriculture JIS certification records. Triangulation between farm-level capital expenditure surveys and manufacturer revenue disclosures anchors segment-level precision.
Historical trendline analysis of equipment replacement cycles across Australian broadacre wheat operations and Hokkaido dairy cooperatives established baseline adoption velocity assumptions. The analytical framework models product type segmentation by capital intensity tier, technology segmentation by digital maturity curve, and end-user segmentation by cooperative infrastructure density across the projection horizon. CAGRs derive from equipment shipment run-rates correlated with subsidy program budget trajectories and import tariff schedule evolution for drone components.
Caveats apply where semiconductor supply disruption, DGFT regulatory revision, or monsoon pattern variability could materially shift the outlook. Forecasts reflect assumptions regarding subsidy program continuity and cooperative organizational capacity scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Europe Agrivoltaics Market
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Global Agrivoltaics Market
Smart Agriculture
Smart Irrigation Software Market
Smart Agriculture
Smart Farm Management Software Market