
 Global IoT in Agriculture Market | 2026-2036
Global IoT in Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT in Agriculture Market Outlook
Equipment-as-a-service leasing is narrowing the capital barrier for mid-size farms entering precision agriculture. Deere & Company leverages its dealer-financing network to anchor subscription-based telemetry across North American row-crop operations. AGCO Corporation competes through Fuse platform integration that sustains interoperability across mixed-fleet environments. Trimble Inc. specializes in GNSS-guided autonomy, dominating high-accuracy steering systems for controlled-traffic farming.
IoT in agriculture denotes networked sensor arrays, unmanned aerial vehicles, edge-computing nodes, and cloud-based analytics platforms that collect, transmit, and process biophysical and environmental data for agronomic decision-making. These systems typically operate across sub-meter GPS accuracy, LoRaWAN or cellular transmission protocols, and real-time soil-moisture thresholds measured in centibars of tension. Crop Monitoring applications lead installed value due to multispectral imaging penetration in broadacre grains, while Soil Health segments show the fastest growth trajectory as carbon-credit verification protocols mature. Cloud-Based deployment captures the largest margin pools through recurring software revenue, though Edge Computing architectures gain traction where bandwidth constraints persist in remote pastoral zones.
The EPA regulates pesticide application rates that IoT variable-rate systems must document for compliance, while the EU Green Deal and F-Gas Regulation mandate refrigerant tracking in climate-controlled livestock facilities and controlled-environment horticulture. India's CEA enforces grid-interconnection standards for solar-powered irrigation pumps that increasingly embed remote monitoring modules. Stakeholders must weigh whether to build captive data infrastructure or rely on platform providers as jurisdictional data-sovereignty rules proliferate across major agricultural economies.
Market Dynamics
Equipment-as-a-service leasing is compressing capital barriers for mid-size farms entering precision agriculture, while the EU Green Deal and F-Gas Regulation tighten environmental compliance for connected farm equipment across European livestock and controlled-environment operations.
Growth Catalysts
- EU Green Deal:The EU Green Deal mandates refrigerant tracking in climate-controlled livestock facilities, forcing upgrades to sensor-enabled monitoring infrastructure across Dutch dairy and Spanish greenhouse operations.
- Precision livestock operations:Automated feeding systems and wearable biometrics for cattle health monitoring are driving sensor deployment in Brazilian feedlots and US Great Plains grazing operations.
- Carbon-credit verification:Soil carbon measurement protocols in Australia's Murray-Darling Basin and Canada's prairie provinces are accelerating adoption of ground-penetrating radar and soil-moisture sensor networks.
Market Restraints
- Silicon supply concentration:Edge-computing node production depends on semiconductor fabrication concentrated in East Asian foundries, exposing agricultural OEMs to geopolitical supply disruptions.
- Cellular infrastructure gaps:LoRaWAN and NB-IoT coverage remains patchy in remote pastoral zones of Argentina's Patagonia and Kazakhstan's steppe regions, limiting real-time telemetry deployment.
- Interoperability fragmentation:Proprietary data protocols from competing platform providers prevent seamless integration of mixed-fleet equipment, raising total cost of ownership for multi-brand farm operators.
Strategic Opportunities
- India's Punjab wheat corridor:CEA-mandated grid-interconnection standards for solar-powered irrigation pumps create embedded monitoring module demand across 2.5 million tube wells.
- Multispectral imaging convergence:Fusion of drone-mounted hyperspectral cameras with satellite-based SAR data enables sub-field yield prediction for Brazilian Mato Grosso soybean belt cooperatives.
- Subscription telemetry channels:Dealer-financed leasing networks bypass traditional equipment sales cycles, opening precision agriculture access to 200-500 hectare mid-size farms in Poland and Ukraine.
Industry Challenges
- Data-sovereignty compliance:Jurisdictional rules proliferating across major agricultural economies force stakeholders to choose between captive infrastructure investment and platform-provider dependency.
- Sensor calibration expertise:Soil-moisture tension measurement in centibars requires agronomic training scarce in extension services across Sub-Saharan African emerging markets.
- Legacy equipment integration:Retrofitting 1990s-era tractors with GNSS-guided steering demands mechanical-electrical interface engineering that strains OEM service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT in Agriculture Market |
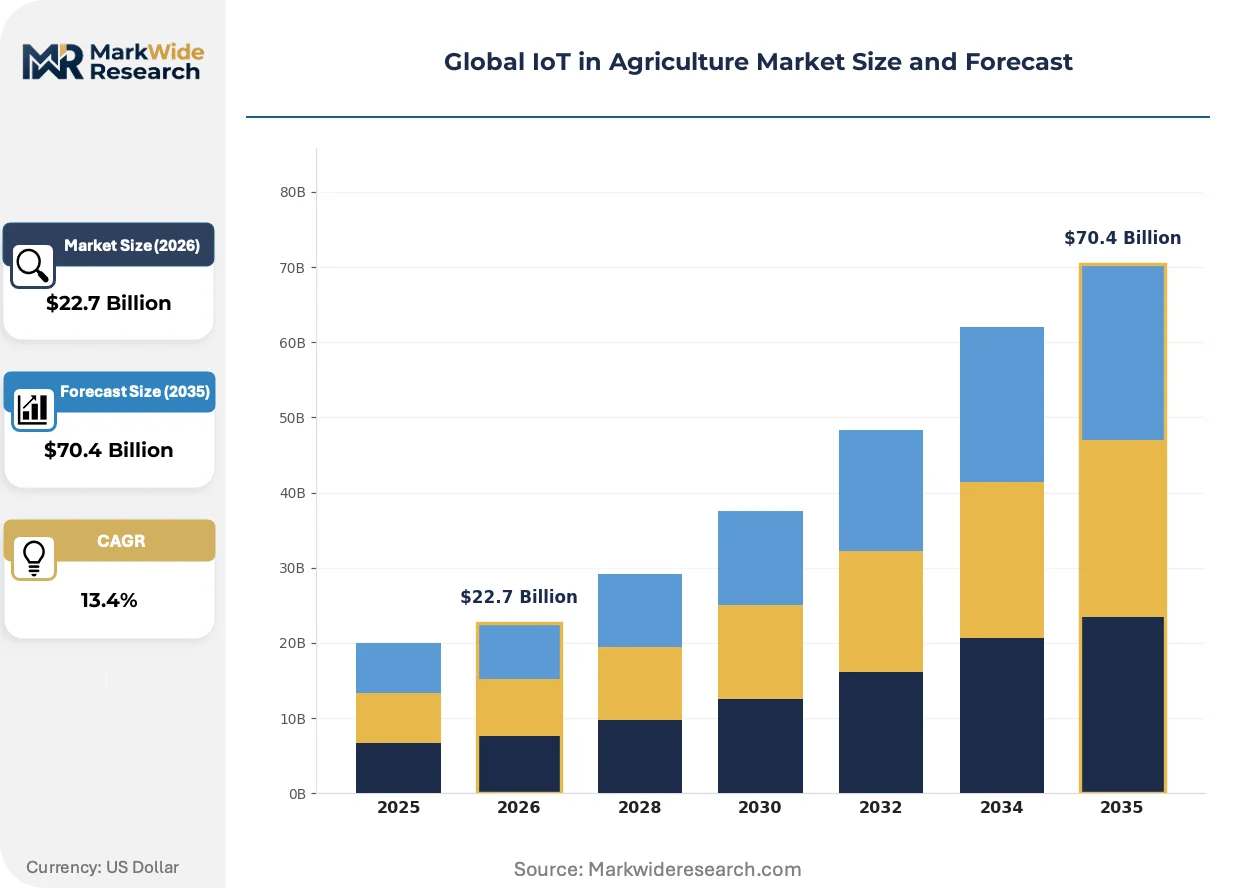
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $70.4 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sensors, Drones, Cloud Computing, Automation Application: Crop Monitoring, Livestock Management, Soil Health, Irrigation Management End User: Farms, Agribusinesses, Agricultural Cooperatives, Research Organizations Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., Trimble Inc., Raven Industries, Robert Bosch GmbH, Microsoft, IBM Corporation, KUBOTA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT in Agriculture Market Strategic Shifts
Telemetry architectures are bifurcating between cloud-native platforms capturing recurring software margins and edge-computing deployments addressing bandwidth constraints in remote pastoral zones.
Hyperspectral imaging is migrating from research-grade laboratory instrumentation to ruggedized drone payloads. Brazilian soybean cooperatives in Mato Grosso are adopting these systems for early-season disease detection. The technology is migrating from aerial survey companies to agronomic service providers, compressing the analytics value chain into farm-gate decision tools.
The EU F-Gas Regulation mandates real-time refrigerant leak detection in controlled-environment horticulture and climate-controlled livestock facilities. Dutch greenhouse operators must install connected pressure sensors and automated reporting systems. Spain's Almería greenhouse cluster is responding fastest, embedding IoT nodes in 340,000 hectares of protected vegetable production.
Mid-size farm cooperatives are consolidating procurement of precision agriculture services through shared equipment pools. Poland's 50-200 hectare family farms are bypassing individual ownership of telemetry-enabled tractors. This cooperative purchasing concentrates negotiating leverage with platform providers, forcing subscription pricing models that unbundle hardware from software access across Eastern European grain belts.
Global IoT in Agriculture Market Segmentation
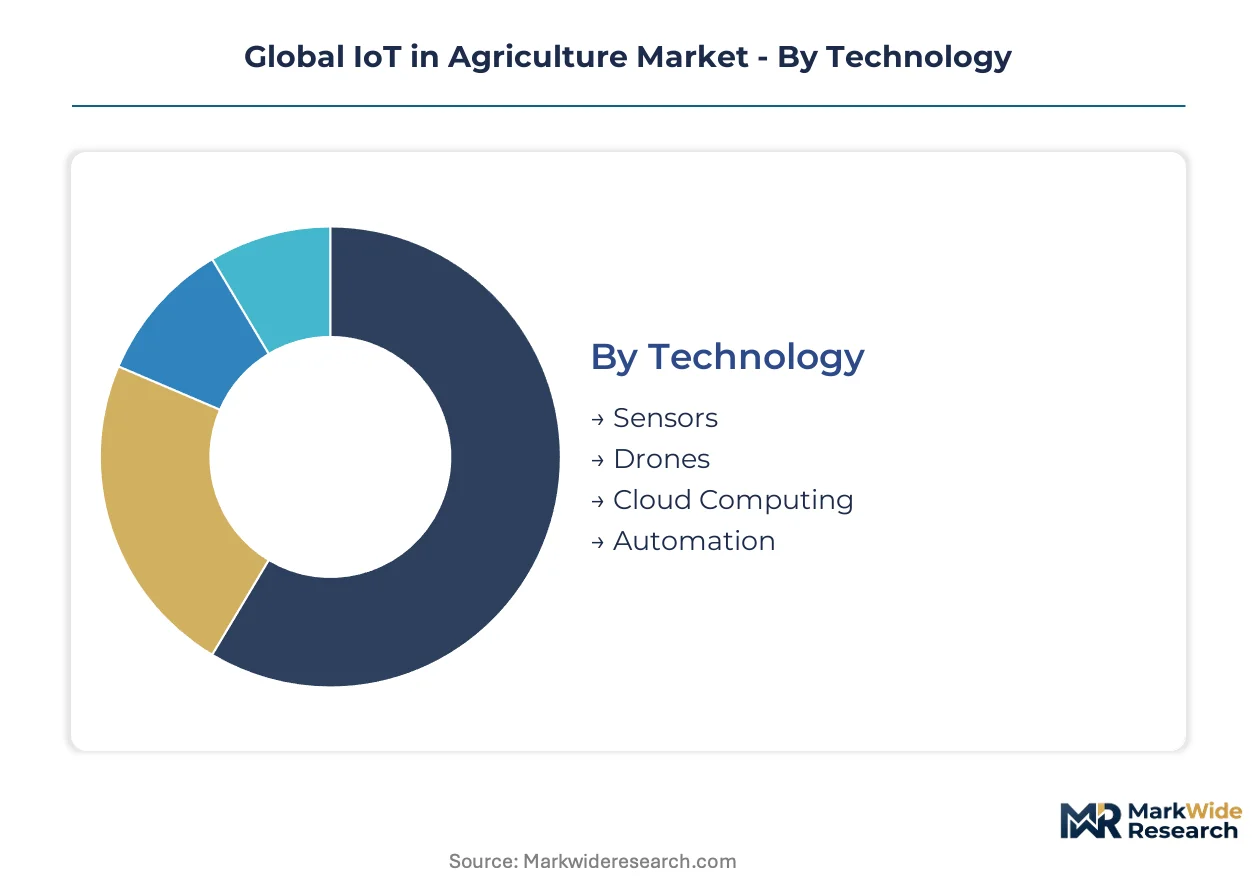
Technology heterogeneity in agricultural IoT creates divergent service intensity requirements across hardware, connectivity, and analytics layers. Equipment manufacturers must calibrate aftermarket support networks to sensor calibration cycles, drone maintenance protocols, and cloud platform uptime guarantees that vary sharply by deployment archetype.
Technology:
After-sales service intensity varies dramatically across technology layers, with sensor networks demanding continuous calibration support and automation systems requiring field engineering deployment.
- Sensors:Soil-moisture tension probes, weather stations, and livestock biometrics operate across LoRaWAN and cellular protocols requiring annual recalibration. Dutch greenhouse operators in Westland cluster drive replacement demand through EU F-Gas Regulation-mandated refrigerant monitoring retrofits.
- Drones:Fixed-wing and multirotor platforms carry multispectral and hyperspectral cameras for sub-field disease detection. Brazilian Mato Grosso soybean cooperatives concentrate procurement of aerial survey services, compressing ownership models toward equipment-as-a-service leasing.
- Cloud Computing:Centralized data lakes process telemetry from distributed edge nodes, with recurring software margins capturing the largest value pools in the technology stack.
- Automation:Variable-rate applicators and robotic harvesters integrate GNSS-guided steering with real-time control systems, demanding OEM field service capacity for mechanical-electrical interface engineering.
Sensors hold the largest share; momentum sits with Drones.
Application:
Application segments stratify by data latency tolerance, with irrigation systems requiring real-time response and soil carbon measurement accepting batch processing cycles.
- Crop Monitoring:Multispectral imaging penetration in broadacre grains generates the deepest installed value base. India's Punjab wheat corridor deploys satellite-SAR fusion for yield prediction across 2.5 million hectares of irrigated production.
- Livestock Management:Wearable biometrics and automated feeding systems dominate Brazilian feedlots and US Great Plains grazing operations. Precision livestock operations show the steepest expansion trajectory as methane monitoring protocols mature for carbon-credit verification.
- Soil Health:Ground-penetrating radar and electrical conductivity mapping support carbon-credit protocols in Australia's Murray-Darling Basin.
- Irrigation Management:Solar-powered pump controllers with embedded telemetry respond to CEA grid-interconnection standards across India's tube well networks.
Crop Monitoring anchors current deployment value; Soil Health is climbing the fastest.
End User:
End-user segments diverge by procurement sophistication, with cooperatives consolidating negotiating leverage and research organizations demanding open data architectures.
- Farms:Mid-size 200-500 hectare operations in Poland and Ukraine access precision agriculture through dealer-financed subscription telemetry, bypassing capital ownership barriers.
- Agribusinesses:Vertically integrated grain traders and protein processors deploy private sensor networks for supply chain visibility and quality assurance.
- Agricultural Cooperatives:Shared equipment pools concentrate demand leverage, forcing unbundled hardware-software pricing across Eastern European grain belts.
- Research Organizations:Universities and extension services require interoperable data standards for agronomic model validation, resisting proprietary platform lock-in.
Farms represent the deepest addressable base; Agricultural Cooperatives are gaining share fastest.
Deployment:
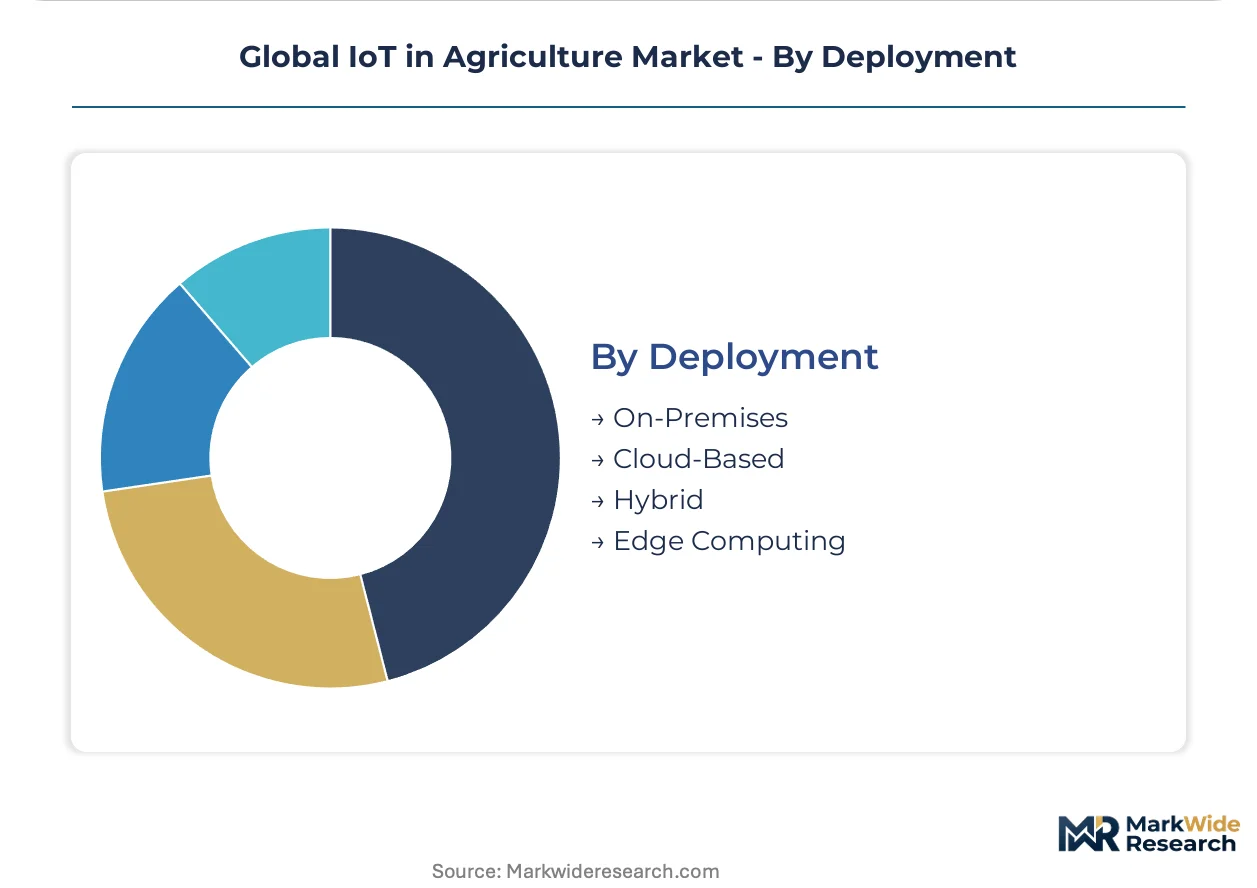
Deployment architecture selection hinges on bandwidth availability and data sovereignty constraints, with remote pastoral zones favoring edge resilience and regulated markets demanding cloud audit trails.
- On-Premises:Local server infrastructure supports air-gapped operations where data sovereignty rules prohibit cross-border telemetry transmission.
- Cloud-Based:Centralized platforms capture recurring software revenue through subscription analytics access, dominating margin pools where cellular infrastructure permits.
- Hybrid:Tiered processing splits real-time control at the edge with archival analytics in cloud data lakes, balancing latency and computational cost.
- Edge Computing:Distributed nodes address bandwidth constraints in Argentina's Patagonia and Kazakhstan's steppe regions, enabling autonomous decision-making without persistent connectivity.
Cloud-Based deployment commands the largest margin capture; Edge Computing is expanding most quickly in bandwidth-constrained pastoral zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and F-Gas Regulation are accelerating sensor deployment in European livestock and greenhouse operations, while India's CEA mandates reshape irrigation infrastructure across its northern grain belt. Brazil's Mato Grosso soybean belt and Australia's Murray-Darling Basin anchor precision agriculture adoption in the Southern Hemisphere.
United States
Automated feeding systems and wearable cattle biometrics drive sensor deployment across US Great Plains grazing operations. The EPA regulates pesticide application rates that IoT variable-rate systems must document for compliance. Midwest row-crop operations concentrate dealer-financed subscription telemetry through established agricultural equipment networks.
Brazil
Hyperspectral imaging adoption for early-season soybean disease detection is compressing ownership models toward equipment-as-a-service leasing. ANVISA regulates agricultural chemical applications that precision systems must track. Mato Grosso soybean belt cooperatives concentrate procurement of aerial survey services and sub-field yield prediction technologies.
India
CEA-mandated grid-interconnection standards for solar-powered irrigation pumps create embedded monitoring module demand across 2.5 million tube wells. The Punjab wheat corridor deploys satellite-SAR fusion for yield prediction across irrigated production zones. Mid-size farms access precision agriculture through shared equipment pools that concentrate negotiating leverage with platform providers.
Netherlands
EU F-Gas Regulation mandates real-time refrigerant leak detection in climate-controlled livestock facilities and controlled-environment horticulture. Westland greenhouse operators drive replacement demand through mandated refrigerant monitoring retrofits. Dutch dairy operations anchor sensor-enabled monitoring infrastructure upgrades across European precision livestock markets.
Australia
Soil carbon measurement protocols in the Murray-Darling Basin accelerate adoption of ground-penetrating radar and soil-moisture sensor networks. TGA-equivalent agricultural chemical regulators enforce documentation standards for variable-rate application systems. Prairie provinces concentrate carbon-credit verification infrastructure that supports emerging agronomic service provider networks.
Global IoT in Agriculture Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented platform ecosystems. The vendor base spans three tiers: established agricultural equipment manufacturers with dealer-financing networks, technology specialists in GNSS and telemetry systems, and cloud-native analytics providers. Consolidation pressure intensifies as interoperability demands force partnerships between hardware OEMs and software platforms. Strategic moves center on subscription model unbundling and edge-computing capacity expansion in bandwidth-constrained pastoral zones.
Within the equipment manufacturer tier, Deere & Company and AGCO Corporation exemplify divergent platform strategies. Trimble Inc. anchors the precision navigation specialist position. Among technology conglomerates, Microsoft and IBM Corporation occupy positions in cloud analytics and artificial intelligence layers. KUBOTA Corporation represents the Asian equipment manufacturer archetype expanding precision agriculture capabilities. Robert Bosch GmbH exemplifies industrial automation crossover into agricultural sensor systems. CNH Industrial N.V. and Raven Industries complete the competitive set across automation and aerial application segments.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Trimble Inc. |
| Raven Industries |
| Robert Bosch GmbH |
| Microsoft |
| IBM Corporation |
| KUBOTA Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in East Asian semiconductor foundries is compressing sensor module costs while tightening margin structures for European automation OEMs, forcing pricing discipline that favors subscription-based telemetry over capital-intensive hardware sales.
Pricing Analysis
Certification level (CE/ISO-grade for EU F-Gas compliance, FCC-certified for US telemetry) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers bundling predictive analytics and regulatory audit trails. Pricing pressure stems from cooperative procurement consolidation in Poland and Ukraine, where mid-size farms demand unbundled hardware-software contracts. Agribusinesses show lowest price sensitivity due to supply chain visibility requirements, while 200-500 hectare family farms in Eastern Europe negotiate hardest on per-hectare subscription rates.
Supply Chain Analysis
Export-control regimes restricting high-precision GNSS receiver exports from the United States are fragmenting sourcing strategies for autonomy-grade steering systems. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, while sensor assembly and system integration anchor in Germany, the United States, and Japan. Raw material dependencies span silicon wafers, rare-earth magnets for drone motors, and lithium cells for solar-powered field nodes. Single-source vulnerability in advanced node fabrication exposes agricultural OEMs to geopolitical disruption. Distribution runs through dealer-financing networks that bundle telemetry subscriptions with equipment leasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision agriculture faces substitution pressure from low-cost manual monitoring systems in bandwidth-constrained pastoral zones, requiring incumbents to defend telemetry value through regulatory compliance integration that manual alternatives cannot replicate.
For Market Incumbents: Build switching-cost moats through F-Gas Regulation-mandated audit trail integration that locks Dutch greenhouse operators into proprietary refrigerant monitoring platforms. Deepen backward integration into edge-computing node production to offset East Asian semiconductor supply risk. Channel control through dealer-financing networks remains the priority lever against emerging equipment-as-a-service competitors. For New Entrants and Emerging Players: Establish a beachhead in India's Punjab wheat corridor, where CEA-mandated solar pump monitoring creates 2.5 million unit demand with limited incumbent presence. Target soil carbon verification protocols in Australia's Murray-Darling Basin as the most penetrable application segment. Go-to-market through agronomic service providers rather than direct farm sales compresses customer acquisition costs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native analytics platforms as recurring software margins displace hardware-heavy business models. Long-term viability favors platform providers with data-sovereignty-compliant architectures spanning multiple regulatory jurisdictions. Acquisition targets should demonstrate interoperability across mixed-fleet environments. Watch for inflection when EU Green Deal enforcement tightens refrigerant tracking mandates beyond Dutch and Spanish greenhouse clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Interoperability Investment | AGCO's Fuse platform demonstrates how open architecture captures multi-brand farm operators. |
| Edge Computing Capacity Expansion | Trimble's GNSS-guided autonomy systems address bandwidth gaps in Argentina's Patagonia grazing zones. |
| Subscription Telemetry Unbundling | Deere's dealer-financed leasing networks bypass capital barriers for 200-500 hectare Polish farms. |
| Regulatory Compliance Integration | Dutch Westland greenhouse operators drive F-Gas-mandated refrigerant sensor retrofit demand. |
| Cooperative Procurement Partnership | Eastern European shared equipment pools concentrate negotiating leverage against platform providers. |
Study Parameters
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Agronomic service providers, precision livestock facility managers, agricultural equipment dealership operators, and CEA grid-interconnection compliance officers contributed field-level perspective. Secondary sources include EPA pesticide application documentation, EU F-Gas Regulation implementation guidance, India's CEA solar pump standards, and ANVISA chemical tracking requirements. Bottom-up sensor deployment counts triangulate against top-down equipment manufacturer revenue segmentation.
Calibration against historical adoption curves in Brazilian Mato Grosso and US Great Plains grazing operations validates projection assumptions across the analysis window. Segmentation dimensions span technology layer (sensors, drones, cloud, automation), application (crop monitoring, livestock, soil health, irrigation), and deployment architecture (cloud, edge, hybrid). CAGRs derive from installed base expansion rates adjusted for replacement cycles and technology migration patterns. Carbon-credit verification protocol maturation and cooperative procurement consolidation serve as industry-specific demand drivers.
Sensitivities concentrate around semiconductor supply disruption, cellular infrastructure buildout pace in remote pastoral zones, and jurisdictional data-sovereignty rule proliferation. Forecasts reflect documented assumptions on regulatory enforcement timelines and equipment-as-a-service adoption curves. Material shifts in EU Green Deal implementation scope or East Asian export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
Global AI in Agriculture Market
Smart Agriculture
Qatar Agriculture Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Smart Agriculture Solutions Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Europe Agrivoltaics Market