
 IoT in Smart Farming Market | 2026-2036
IoT in Smart Farming Market Size, Share, and Industry Trends Forecast 2026-2036
IoT in Smart Farming Market Insights
Precision livestock management is expanding faster than row-crop automation as dairy and cattle operations prioritize real-time health monitoring. Deere & Company leverages its established dealer network to dominate North American telemetry deployments for large-scale grain producers. Trimble Inc. competes through specialized GNSS correction services that anchor its precision agriculture hardware ecosystem. AGCO Corporation differentiates via open-platform connectivity standards that let mixed-fleet operators integrate third-party sensors.
IoT in smart farming encompasses networked sensor arrays, autonomous aerial platforms, and edge-computing gateways that collect field-level biophysical data and execute automated actuation commands. Systems typically operate across sub-gigahertz mesh networks or cellular LPWAN protocols, transmitting soil moisture, canopy temperature, and animal vital signs to cloud-based decision engines for predictive intervention scheduling. Wireless communication infrastructure leads installed technology value due to the retrofit intensity of legacy farms with poor broadband coverage. Artificial intelligence is displacing rule-based analytics in crop monitoring as computer vision models trained on hyperspectral imagery reduce false-positive pest detection rates. Big data analytics occupies the fastest-expanding margin pool among technology segments because subscription-based agronomic advisory services generate recurring revenue from agricultural cooperatives.
The EPA enforces Clean Water Act provisions that mandate nutrient management documentation, forcing farm operators to adopt validated soil and runoff sensors for compliance evidence. USDA Natural Resources Conservation Service cost-share programs offset capital barriers for irrigation control upgrades, while the EU Green Deal's Farm to Fork strategy tightens pesticide reduction targets that accelerate drone-based variable-rate application adoption. Stakeholders must monitor how emerging carbon credit verification protocols reshape data ownership terms between equipment manufacturers and farm operators.
Market Dynamics
USDA conservation compliance programs and EPA water quality mandates are tightening reporting requirements, forcing farm operators to deploy validated sensor networks for runoff documentation and nutrient management evidence.
Growth Catalysts
- Precision Livestock Operations:Commercial dairies and feedlots prioritize real-time health monitoring, accelerating sensor deployments for animal vital signs tracking.
- EU Green Deal Farm to Fork Strategy:Pesticide reduction targets tighten across member states, driving drone-based variable-rate application adoption.
- Brazil-Australia-Netherlands Demand Concentration:These markets concentrate demand for automated irrigation and remote herd monitoring systems.
Market Restraints
- Wireless Infrastructure Retrofit Costs:Legacy farms with poor broadband coverage face high capital intensity for sub-gigahertz mesh network and cellular LPWAN protocol deployment.
- Data Ownership Ambiguity:Emerging carbon credit verification protocols create unresolved terms between equipment manufacturers and farm operators over who controls field-level biophysical data.
- Edge Computing Hardware Limitations:Field-level gateways struggle with processing latency for real-time actuation commands in remote agricultural zones.
Strategic Opportunities
- Carbon Credit Verification Services:Subscription-based agronomic advisory platforms can capture recurring revenue by validating sequestration claims for agricultural cooperatives.
- Computer Vision Convergence:Hyperspectral imagery combined with AI models reduces false-positive pest detection rates, opening precision intervention scheduling markets.
- USDA NRCS Cost-Share Programs:Irrigation control upgrade subsidies lower capital barriers for mid-scale operators seeking automated water management.
Industry Challenges
- Agronomic Data Science Talent Gap:Farm operators lack personnel skilled in interpreting cloud-based decision engine outputs for predictive intervention scheduling.
- Mixed-Fleet Integration Complexity:Operators running equipment from multiple manufacturers face friction connecting third-party sensors to proprietary telemetry platforms.
- Clean Water Act Compliance Documentation:EPA-mandated nutrient management evidence requires validated sensor calibration protocols many operators have not implemented.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT in Smart Farming Market |
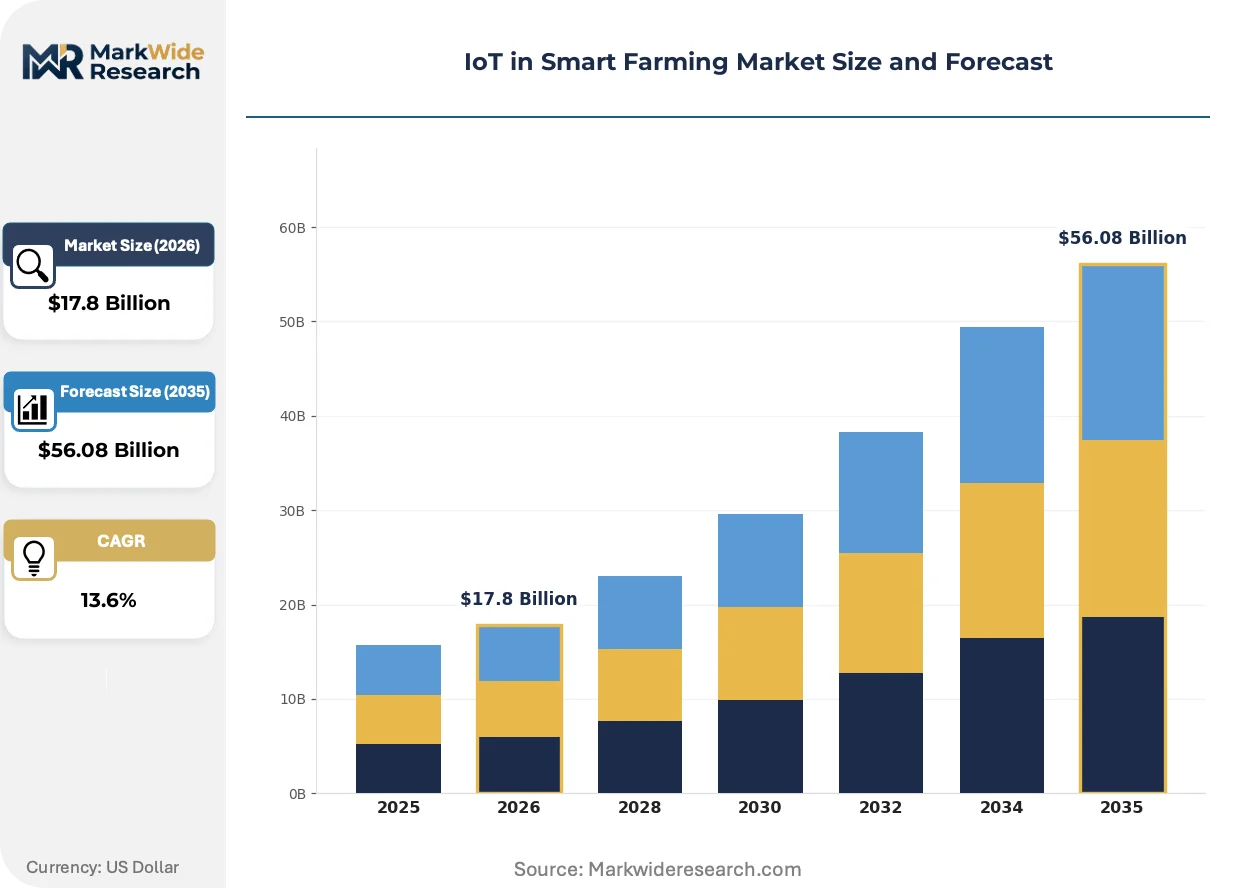
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $56.08 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Drones, Livestock Monitoring Systems, Irrigation Control Systems End User: Farmers, Agronomists, Agricultural Cooperatives, Research Institutions Technology: Wireless Communication, Cloud Computing, Artificial Intelligence, Big Data Analytics Application: Crop Monitoring, Soil Analysis, Weather Tracking, Livestock Management |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, CNH Industrial N.V., Raven Industries, Topcon Positioning Systems, Robert Bosch GmbH, Microsoft, KUBOTA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT in Smart Farming Market Trends and Innovations
Artificial intelligence is displacing rule-based analytics across crop monitoring workflows, while regulatory pressure on water quality and carbon reporting reshapes how agricultural data gets collected, processed, and monetized.
Computer vision models trained on hyperspectral imagery are overtaking spectral index-based pest detection methods. Large-scale grain producers now demand sub-field resolution for variable-rate chemical application. This compression of false-positive rates is enabling per-acre subscription pricing for advisory services.
REACH chemical registration requirements and the EU AI Act's risk classification framework are tightening compliance burdens on drone-based spraying systems. Manufacturers must now document algorithmic decision transparency for autonomous aerial platforms. Dutch and German operators face the steepest re-certification timelines for existing fleet deployments.
Farm cooperatives now unbundle equipment purchases from agronomic advisory subscriptions. Previously bundled telemetry and decision-support services separate into standalone SaaS contracts. This shift is most visible in Brazil's commercial soybean belt, where operators prefer purchasing sensor hardware outright while subscribing separately to AI-powered yield prediction platforms.
IoT in Smart Farming Market Segmentation
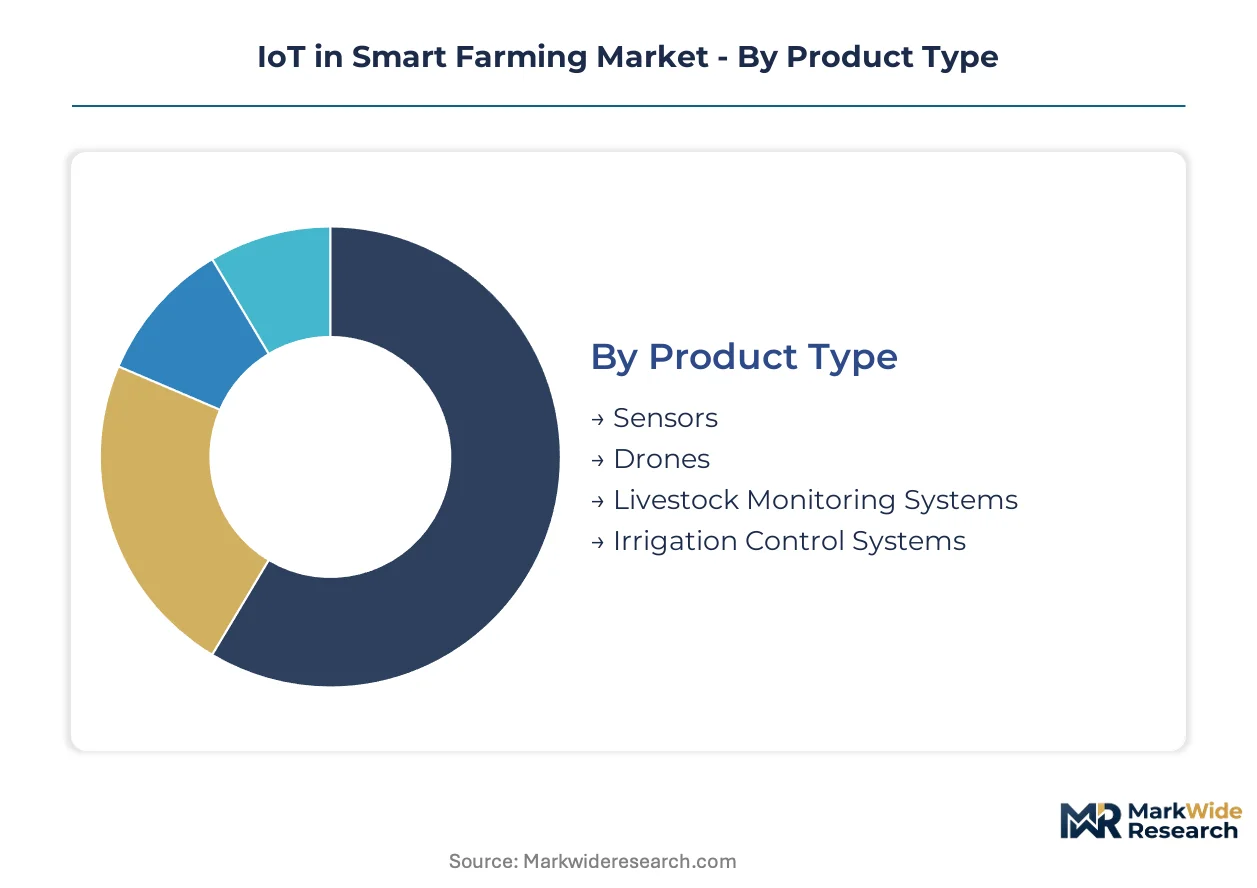
Segmentation reveals how capital flows diverge between retrofit hardware and recurring service revenue. Equipment categories face replacement cycles tied to connectivity protocol evolution, while technology layers compete on margin structure and customer lock-in duration.
Product Type:
Upgrade cycles accelerate where legacy farms replace standalone devices with networked sensor arrays that feed cloud-based decision engines.
- Sensors:Soil moisture probes, canopy temperature arrays, and animal vital sign monitors form the hardware base layer. Brazilian soybean operators and Dutch greenhouse complexes drive volume for validated runoff documentation sensors under tightening EPA and EU water quality mandates.
- Drones:Autonomous aerial platforms carry hyperspectral cameras and variable-rate application payloads. Australian broadacre wheat farms and Brazilian cotton operations concentrate demand for drone-based pest detection that reduces false-positive rates through AI-trained computer vision models.
- Livestock Monitoring Systems:Ear-tag transmitters and rumen boluses track real-time health metrics across commercial dairies. Feedlots in feed-conversion efficiency programs prioritize these deployments.
- Irrigation Control Systems:Automated valve actuators and pivot controllers integrate with soil moisture feedback loops. USDA NRCS cost-share programs offset capital barriers for mid-scale grain producers retrofitting flood irrigation infrastructure.
Sensors sit at the top of the volume ranking, with drones climbing the fastest as regulatory pressure tightens on chemical application precision.
End User:
Customer type determines pricing architecture and contract structure, with cooperatives commanding volume discounts unavailable to individual operators.
- Farmers:Individual owner-operators purchase hardware outright and subscribe separately to SaaS advisory layers. Brazil's commercial soybean belt exemplifies this unbundling preference.
- Agronomists:Independent consultants license multi-farm data aggregation platforms to deliver prescription services across client portfolios.
- Agricultural Cooperatives:Member-owned enterprises negotiate enterprise telemetry contracts and capture recurring revenue from carbon credit verification services. These entities generate the steepest expansion trajectory for subscription-based agronomic advisory platforms.
- Research Institutions:Universities and government extension services validate sensor calibration protocols and algorithmic decision transparency for regulatory compliance documentation.
Agricultural cooperatives anchor the revenue base, with agronomists gaining share fastest as advisory services unbundle from equipment sales.
Technology:
Margin pools concentrate in layers that enable recurring revenue rather than one-time hardware transactions.
- Wireless Communication:Sub-gigahertz mesh networks and cellular LPWAN protocols dominate retrofit deployments on legacy farms with poor broadband coverage. This layer commands the highest installed value due to infrastructure intensity.
- Cloud Computing:Distributed processing architectures host decision engines for predictive intervention scheduling. Farm operators face talent gaps in interpreting cloud-based outputs for field-level execution.
- Artificial Intelligence:Computer vision models displace rule-based analytics for pest detection and yield prediction. The EU AI Act's risk classification framework imposes algorithmic transparency documentation burdens on autonomous platform manufacturers.
- Big Data Analytics:Subscription-based agronomic advisory services generate recurring revenue from yield prediction and variable-rate prescription optimization. This segment captures the fastest-expanding margin pool among technology layers.
Wireless communication leads absolute technology value, while big data analytics expands most quickly through recurring SaaS contract structures.
Application:
Application focus shifts with regulatory pressure, as water quality mandates force adoption of validated monitoring systems regardless of near-term ROI.
- Crop Monitoring:Hyperspectral imagery and canopy temperature sensing enable sub-field resolution for variable-rate chemical application. Large-scale grain producers demand per-acre subscription pricing tied to false-positive rate compression.
- Soil Analysis:Validated nutrient and moisture sensors provide compliance evidence for EPA Clean Water Act documentation requirements. Operators face calibration protocol gaps that delay regulatory submission timelines.
- Weather Tracking:Microclimate stations and predictive models optimize planting and harvest windows. Integration with irrigation control systems creates closed-loop automation for water-stressed regions.
- Livestock Management:Real-time health monitoring accelerates across commercial dairies and feedlots. Precision livestock operations now outpace row-crop automation in sensor deployment velocity.
Livestock management commands the steepest adoption curve, with soil analysis climbing fastest as EPA and EU water quality enforcement tightens documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping investment flows as operators migrate sensor deployments toward jurisdictions with favorable cost-share structures and streamlined compliance pathways. Brazil, Australia, and the Netherlands concentrate automated irrigation and remote herd monitoring demand, while EPA and EU enforcement tighten documentation requirements elsewhere.
United States
Commercial dairies in Wisconsin and California accelerate ear-tag transmitter deployments for real-time health monitoring. USDA Natural Resources Conservation Service cost-share programs offset capital barriers for irrigation control upgrades across the Corn Belt. EPA Clean Water Act enforcement in the Chesapeake Bay watershed forces validated soil sensor adoption for nutrient management documentation.
Brazil
Soybean operators in Mato Grosso and Goiás unbundle equipment purchases from agronomic advisory subscriptions, preferring outright sensor hardware ownership. ANVISA chemical registration requirements intersect with EU Green Deal export compliance pressures. São Paulo-based cooperatives negotiate enterprise telemetry contracts for carbon credit verification services.
Australia
Broadacre wheat farms in Western Australia concentrate demand for drone-based pest detection using AI-trained computer vision models. TGA-equivalent agricultural chemical regulators impose algorithmic transparency documentation on autonomous spraying platforms. Queensland feedlots prioritize rumen bolus deployments for feed-conversion efficiency programs.
Netherlands
Greenhouse complexes in Westland and Aalsmeer drive volume for validated runoff documentation sensors under tightening EU water quality mandates. REACH chemical registration requirements and the EU AI Act's risk classification framework steepen re-certification timelines for existing drone fleets. Wageningen University anchors research institution validation of sensor calibration protocols.
Germany
Bavarian dairy cooperatives deploy precision livestock monitoring systems ahead of EU Farm to Fork pesticide reduction targets. KBA-equivalent agricultural equipment regulators enforce CE marking compliance on edge-computing gateways. Baden-Württemberg machinery manufacturers face pressure to document algorithmic decision transparency for autonomous platforms.
IoT in Smart Farming Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment manufacturers ally with cloud computing providers to bundle telemetry with decision-support services. The vendor base organizes around three tiers: diversified machinery conglomerates with captive dealer networks, specialized GNSS and sensor technology firms, and software-native platforms unbundling advisory from hardware. Two competitive moves define current positioning: geographic expansion through distributor acquisition in Brazil and Australia, and technology licensing agreements that let mixed-fleet operators integrate third-party sensors.
Within the machinery conglomerate tier, Deere & Company and CNH Industrial N.V. anchor North American and European market presence through established dealer infrastructure. Trimble Inc. and Topcon Positioning Systems exemplify the specialized positioning technology archetype, while Microsoft represents the software-native entrant leveraging cloud computing scale for agronomic advisory platforms.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| CNH Industrial N.V. |
| Raven Industries |
| Topcon Positioning Systems |
| Robert Bosch GmbH |
| Microsoft |
| KUBOTA Corporation |
| Others |
Pricing and Supply Chain Analysis
Edge-computing gateway miniaturization is compressing hardware production costs while concentrating semiconductor sourcing among Taiwanese and South Korean foundries, simultaneously lowering sensor array price floors and tightening supply leverage for legacy farm retrofit deployments.
Pricing Analysis
Distributor margins on precision agriculture hardware compress under direct-to-cooperative enterprise contracts. Three-tier pricing structure across premium, standard, and economy levels segments by connectivity protocol certification and after-sales telemetry bundling. Price differentiation stems from USDA NRCS cost-share eligibility and LPWAN coverage density. Brazilian soybean operators exhibit highest price sensitivity due to unbundled procurement preferences, while Dutch greenhouse complexes tolerate premium tiers for validated runoff documentation compliance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cooperative demand, while authorized dealer networks serve individual owner-operators. Semiconductor fabrication concentrates in Taiwan, South Korea, and Germany. Sensor assembly draws from Chinese PCB manufacturing, Mexican enclosure production, and Israeli spectral component design. Single-source vulnerability in sub-gigahertz radio modules creates tariff exposure risk. Distribution runs through machinery conglomerate captive networks and independent agronomic advisory platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT in smart farming operates as a stable compounder anchored by regulatory compliance mandates that institutionalize recurring sensor replacement cycles regardless of commodity price cycles.
For Market Incumbents: Anticipate margin compression from software-native platforms unbundling advisory services by deepening backward integration into edge-computing semiconductor design. Capture channel control through distributor acquisitions in Brazil and Australia before regional cooperatives consolidate procurement leverage. Prioritize open-platform connectivity standards to neutralize mixed-fleet integration friction. For New Entrants and Emerging Players: Enter via carbon credit verification SaaS layers where agricultural cooperatives lack in-house agronomic data science talent. Target mid-scale Corn Belt grain producers underserved by Deere's enterprise-focused telemetry deployments. Lead with USDA NRCS cost-share navigation as customer acquisition wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized GNSS correction service providers facing hyperscaler cloud entry. Five-to-ten-year viability hinges on regulatory enforcement durability for water quality and carbon reporting mandates. Monitor EPA Clean Water Act settlement patterns as inflection signal for compliance-driven sensor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Open connectivity standards let AGCO capture mixed-fleet operators fleeing proprietary Deere telemetry lock-in. |
| Geographic Expansion | Distributor acquisitions in Brazil's Mato Grosso soybean belt secure enterprise cooperative contracts before local consolidation. |
| Strategic Partnership | Microsoft's cloud alliances with machinery OEMs bundle decision-support SaaS without hardware manufacturing capital. |
| Acquisition of Specialist Firm | Computer vision startups trained on hyperspectral imagery compress false-positive rates for drone-based pest detection premiums. |
| Product Launch | Validated runoff documentation sensors with EPA-recognized calibration protocols command compliance-driven price premiums. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged precision agriculture product managers at machinery OEMs, agronomic advisory platform CTOs, USDA NRCS program administrators, cooperative procurement directors, and EPA regional enforcement officers. Secondary validation drew from SEC 10-K equipment manufacturer filings, FCC device authorization databases, EU Farm to Fork strategy implementation reports, and ANVISA chemical registration dockets. Bottom-up sensor shipment tracking and top-down agricultural expenditure modeling triangulated market sizing.
Historical reference periods anchored the projection horizon through verified installation base counts and replacement cycle analysis. Segmentation dimensions modeled include product type, end user archetype, technology layer, and application focus across connectivity protocol generations. CAGRs derived from protocol migration curves and regulatory compliance deadline clustering. Forecast inputs incorporated USDA cost-share appropriation trajectories and EU AI Act implementation timelines for autonomous platform recertification.
The model holds under sustained regulatory enforcement intensity; deviation in EPA budget appropriations or EU Green Deal suspension would shift replacement demand timing. Forecasts reflect assumptions about LPWAN network buildout pace and cooperative consolidation rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Smart Irrigation Software Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
Europe Agrivoltaics Market