
 Europe Agrivoltaics Market | 2026-2036
Europe Agrivoltaics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agrivoltaics Market Analytics
Spanish solar engineering firms is broadening agrivoltaic installation capacity across southern Europe. Akuo Energy leverages its dual-use project pipeline to secure long-term power purchase agreements in France. Falck Renewables anchors its position through specialized agronomic partnerships that optimize panel shading for vineyard operations. Enel Green Power dominates utility-scale agrivoltaic deployments in Italy through integrated energy management platforms.
Europe agrivoltaics combines photovoltaic electricity generation with active agricultural production through elevated or semi-transparent panel arrays, typically mounted at heights of 2.5 to 5 meters to permit mechanized farming beneath while capturing solar irradiance. Fixed tilt technology occupies the majority of installed capacity due to lower capital requirements and simpler maintenance protocols, though bifacial systems are gaining traction in high-latitude markets where albedo from crop surfaces enhances rear-side energy yield. Agricultural production applications sustain the largest revenue pool as farmers seek income diversification, while mounting systems represent a concentrated margin segment where steel suppliers compete on structural adaptability to varied terrain.
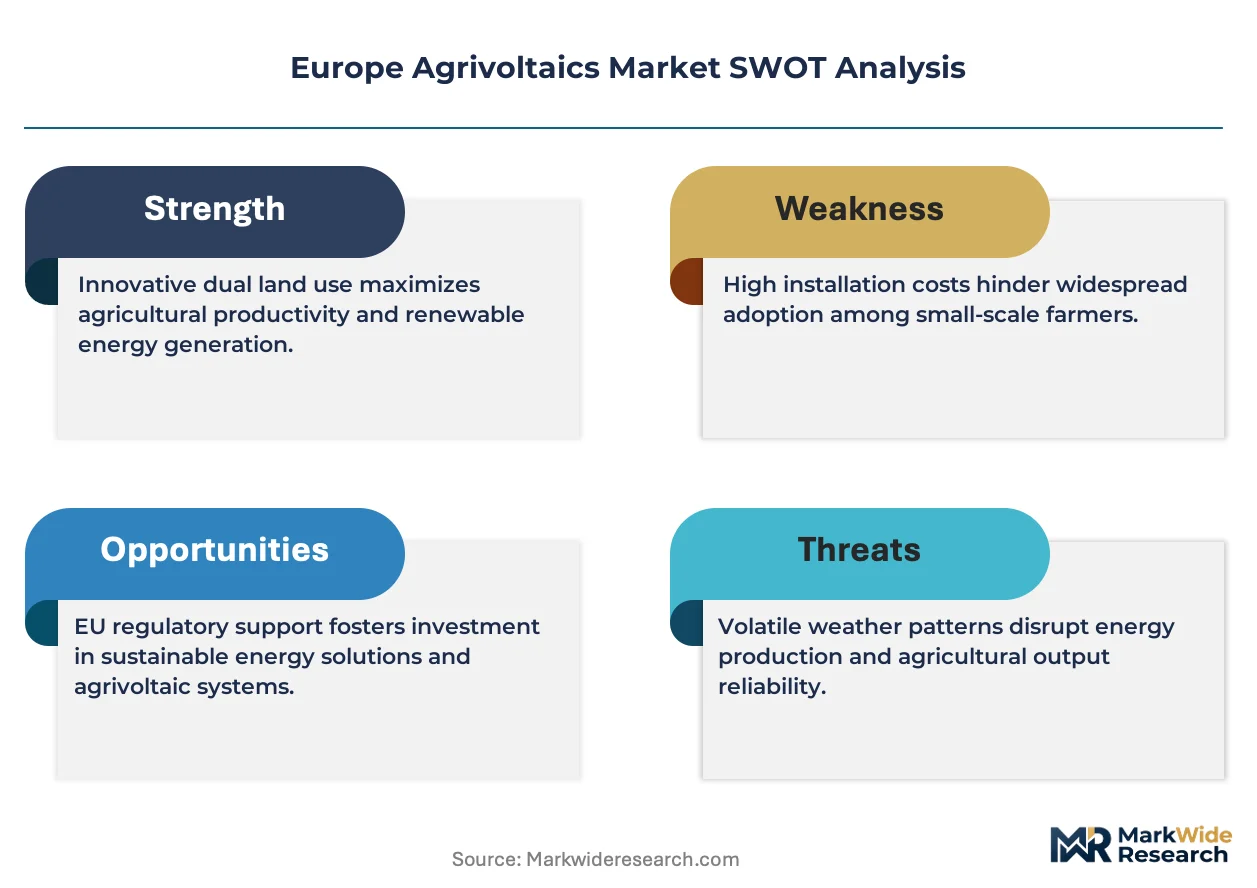
The EU Green Deal and Common Agricultural Policy condition subsidy eligibility on sustainable land use practices that agrivoltaic projects satisfy. ECHA REACH compliance governs panel material composition and end-of-life recycling obligations across member states. France's national agrivoltaic framework and Germany's EEG tariff structures create divergent incentive landscapes that stakeholders must navigate when prioritizing market entry sequences.
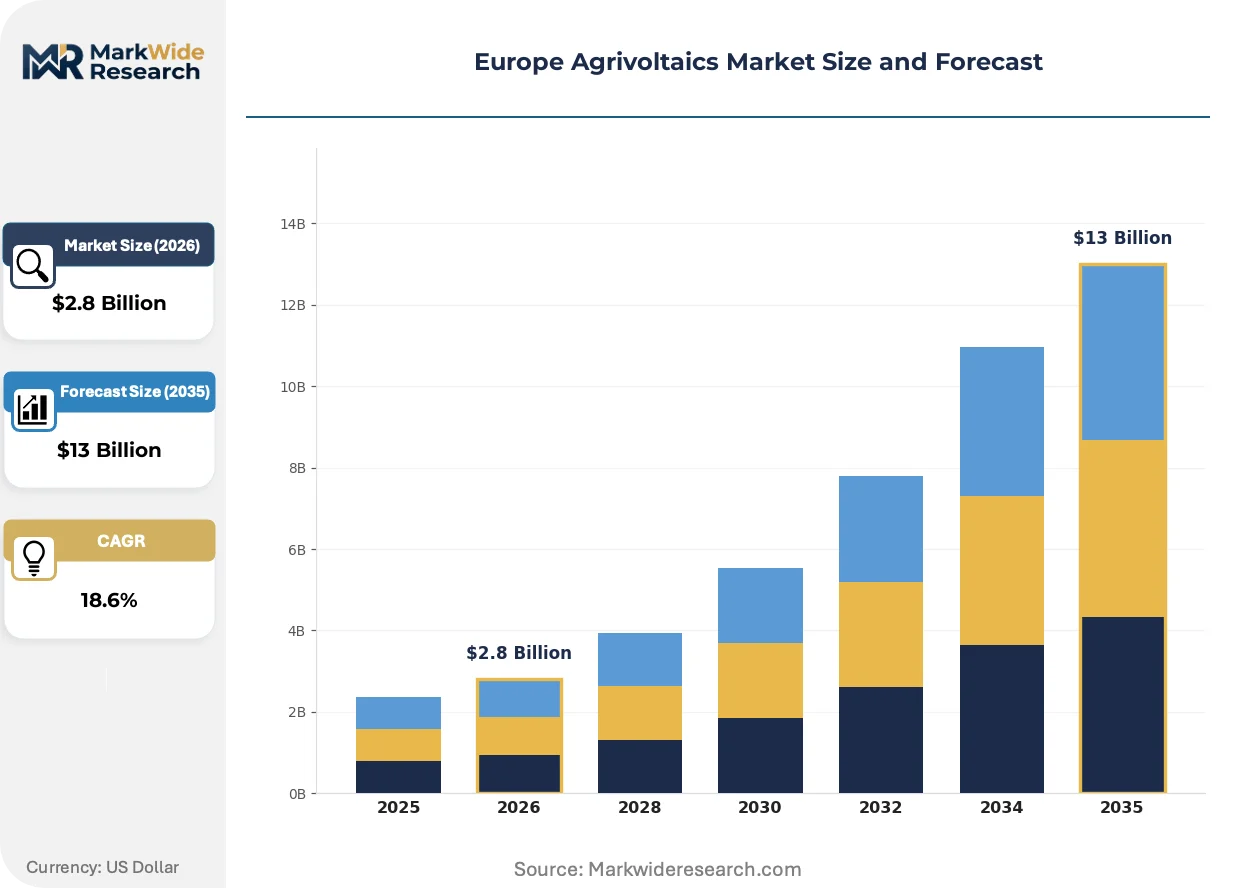
Market Dynamics
The EU Green Deal's land-use conditionality requirements are forcing rapid capital reallocation toward dual-use solar infrastructure, as farmers face subsidy loss without sustainable practice verification.
Growth Catalysts
- EU Green Deal conditionality:Subsidy eligibility now requires demonstrable sustainable land use, which elevated agrivoltaic arrays satisfy through combined electricity and crop production.
- France's national agrivoltaic framework:Clear permitting pathways for vineyard and orchard installations reduce regulatory uncertainty for agricultural landowners.
- Bifacial panel technology:Rear-side energy capture from crop albedo enhances yield economics in high-latitude Bavarian and northern Italian deployments.
Market Restraints
- Steel price volatility:Mounting system fabrication depends on structural steel inputs subject to energy-intensive production cost swings.
- German grid connection queues:EEG tariff applicants face multi-year interconnection delays that compress project IRR timelines.
- Fixed-tilt technical ceiling:Tracking system exclusion limits energy yield optimization for high-value specialty crop configurations.
Strategic Opportunities
- Spanish southern plateau expansion:Extensive arid agricultural zones with high solar irradiance remain underpenetrated for olive and almond co-location.
- Common Agricultural Policy eco-scheme payments:Newly introduced cover crop and biodiversity premiums stack with energy revenue for diversified farm income.
- Semi-transparent organic photovoltaics:Spectral selectivity convergence with greenhouse horticulture opens protected cultivation segments previously excluded from agrivoltaic eligibility.
Industry Challenges
- Agronomic technician shortage:Cross-disciplinary expertise spanning photovoltaic engineering and crop science remains concentrated among specialized consultancies.
- ECHA REACH end-of-life compliance:Panel recycling obligation documentation creates administrative burden for distributed farm-scale installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agrivoltaics Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Mounting Systems, Storage Solutions Application: Agricultural Production, Land Management, Renewable Energy Generation, Crop Insurance End User: Farmers, Agricultural Cooperatives, Energy Companies, Investors Technology: Fixed Tilt, Single-Axis Tracking, Bifacial, Transparent Solutions |
| Companies Covered | Akuo Energy, Falck Renewables, Enel Green Power, REM Tec, GreenYellow, Sun'Agri, Next2Sun, Gonvarri Solar Steel, BayWa r.e., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agrivoltaics Market Evolving Landscape
Technology convergence between spectral engineering and precision agriculture is redefining panel-crop interaction design, while regulatory clarity accelerates standardization across previously fragmented national frameworks.
Bifacial glass-glass modules are integrating crop-specific light transmission algorithms that adjust row spacing and tilt angles based on vine or cereal phenology stages. French wine cooperatives in Bordeaux and Champagne are deploying these configurations at commercial scale. The structural consequence is compression of payback periods for high-value agricultural zones previously marginal for standalone solar economics.
Germany's EEG tariff restructuring creates differentiated compensation bands based on agricultural continuity requirements, forcing developers to document active cultivation beneath arrays. Bavarian dairy and hop farms must now submit annual crop yield reports to maintain feed-in premium eligibility. This regulatory mechanism most affects utility-scale projects where passive grazing previously satisfied minimal land-use conditions.
Farmer-owned energy cooperatives are displacing third-party lease arrangements as the dominant transaction structure in Italy's Po Valley. These aggregations pool land access and share balance-of-plant costs while retaining full energy revenue. The shift is most visible among medium-scale arable operations in Emilia-Romagna where land fragmentation historically discouraged individual solar investment.
Europe Agrivoltaics Market Segmentation
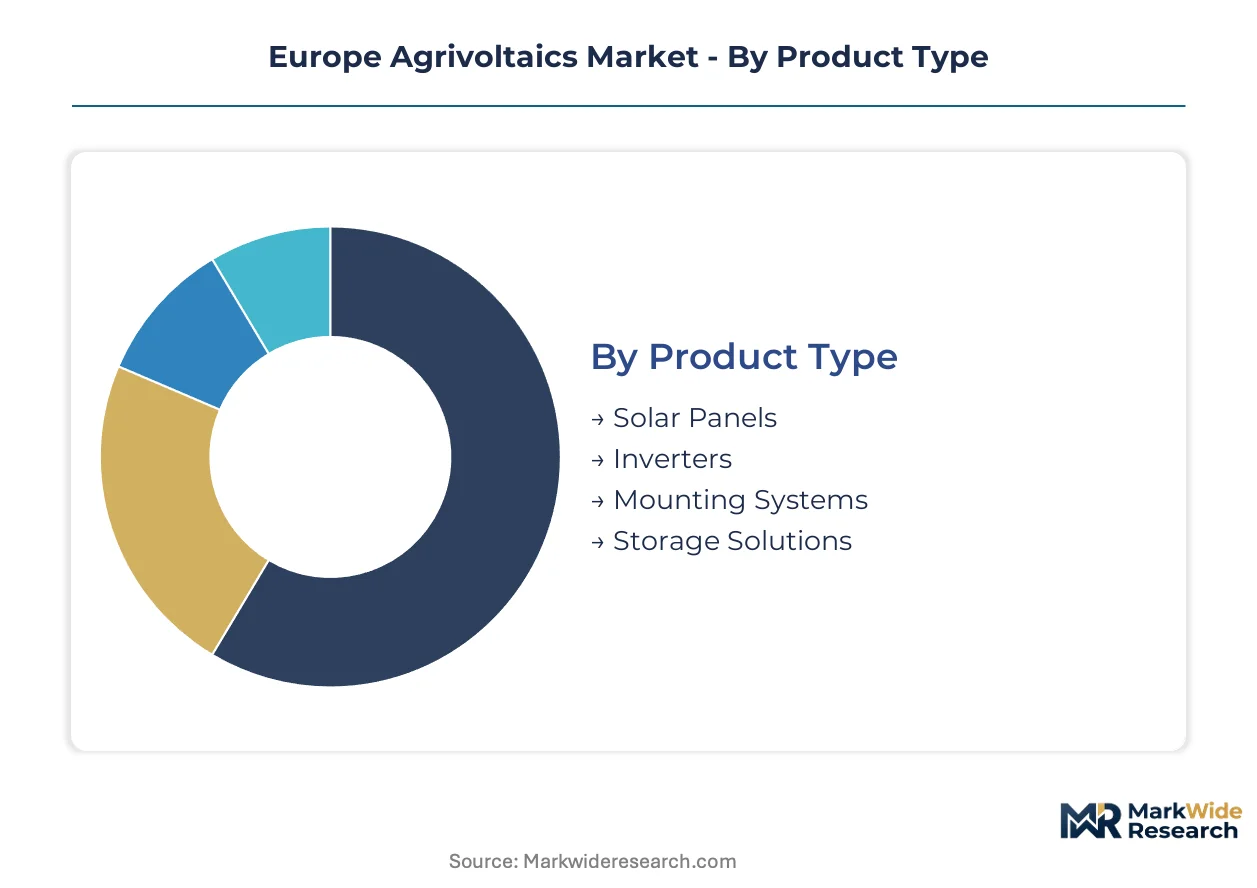
Technology and application diversity in agrivoltaics creates distinct procurement patterns across European agricultural zones. Equipment specifications vary sharply between vineyard elevations and arable flatlands, while regulatory frameworks in France, Germany, and Italy impose divergent compliance requirements on each segment.
Product Type:
Equipment replacement cycles in agrivoltaic installations accelerate as farmers upgrade from pilot configurations to revenue-optimized systems. Capital allocation shifts toward integrated solutions that reduce operational complexity across dual-use sites.
- Solar Panels:Glass-glass and glass-backsheet configurations dominate vineyard and orchard deployments in Bordeaux and Champagne, where elevated humidity demands enhanced moisture resistance. French wine cooperatives specify panels with 25-year performance warranties to match vine replacement cycles.
- Mounting Systems:Steel lattice structures with adjustable height mechanisms (2.5–5 meter range) enable mechanized cultivation beneath arrays in Germany's Bavarian hop farms. Steel price volatility compresses margins for fabricators supplying terrain-adaptive foundations.
- Inverters:String and central inverter architectures process DC output from distributed panel arrays across Italy's Po Valley cooperative installations.
- Storage Solutions:Lithium-ion battery systems capture midday generation peaks for evening grid export in German EEG tariff structures.
Mounting Systems sits at the top of the volume ranking, with Storage Solutions climbing the fastest.
Application:
Revenue stacking potential determines application prioritization, with farmers selecting configurations that maximize subsidy layering and energy income.
- Agricultural Production:Active cultivation beneath elevated arrays satisfies EU Green Deal land-use conditionality for subsidy retention. Bavarian dairy farms submit annual crop yield documentation to German grid regulators to maintain feed-in premium eligibility.
- Renewable Energy Generation:Utility-scale deployments in Italy's Emilia-Romagna region aggregate fragmented landholdings through farmer-owned cooperatives. These structures pool balance-of-plant costs while retaining full energy revenue.
- Land Management:Soil moisture retention and erosion control benefits attract olive growers in Spain's southern plateau zones.
- Crop Insurance:Weather risk mitigation through panel hail protection commands premiums in French storm-prone viticulture areas.
Agricultural Production commands the largest revenue pool, with Renewable Energy Generation expanding most quickly as cooperative structures proliferate.
End User:
Transaction structure evolution from third-party leases to farmer ownership redefines procurement authority and equipment specification influence.
- Farmers:Individual landowners in France's national agrivoltaic framework navigate streamlined permitting for vineyard and orchard installations. Direct ownership captures full energy revenue but requires capital deployment and technical risk assumption.
- Agricultural Cooperatives:Aggregated land access in Italy's Po Valley enables utility-scale procurement leverage previously unavailable to fragmented holdings. Shared balance-of-plant costs reduce per-hectare entry thresholds.
- Energy Companies:Utility-scale developers deploy integrated energy management platforms across Italian agrivoltaic pipelines.
- Investors:Infrastructure funds target operational assets with contracted revenue streams in France and Germany.
Farmers retain the dominant transaction volume, with Agricultural Cooperatives gaining share fastest as aggregation models mature.
Technology:
Yield optimization requirements drive technology selection, with latitude and crop type determining panel configuration economics.
- Fixed Tilt:Simplified maintenance protocols and lower capital requirements sustain majority installed capacity across European deployments. Standard configurations suit mechanized cereal farming in flat terrain applications.
- Bifacial:Rear-side energy capture from crop surface albedo enhances yield economics in high-latitude Bavarian and northern Italian zones. Glass-glass modules integrate crop-specific light transmission algorithms based on vine phenology stages.
- Single-Axis Tracking:Dynamic orientation systems optimize irradiance capture for high-value specialty crops with compatible shading tolerance profiles.
- Transparent Solutions:Semi-transparent organic photovoltaics enable spectral selectivity convergence with greenhouse horticulture in protected cultivation segments.
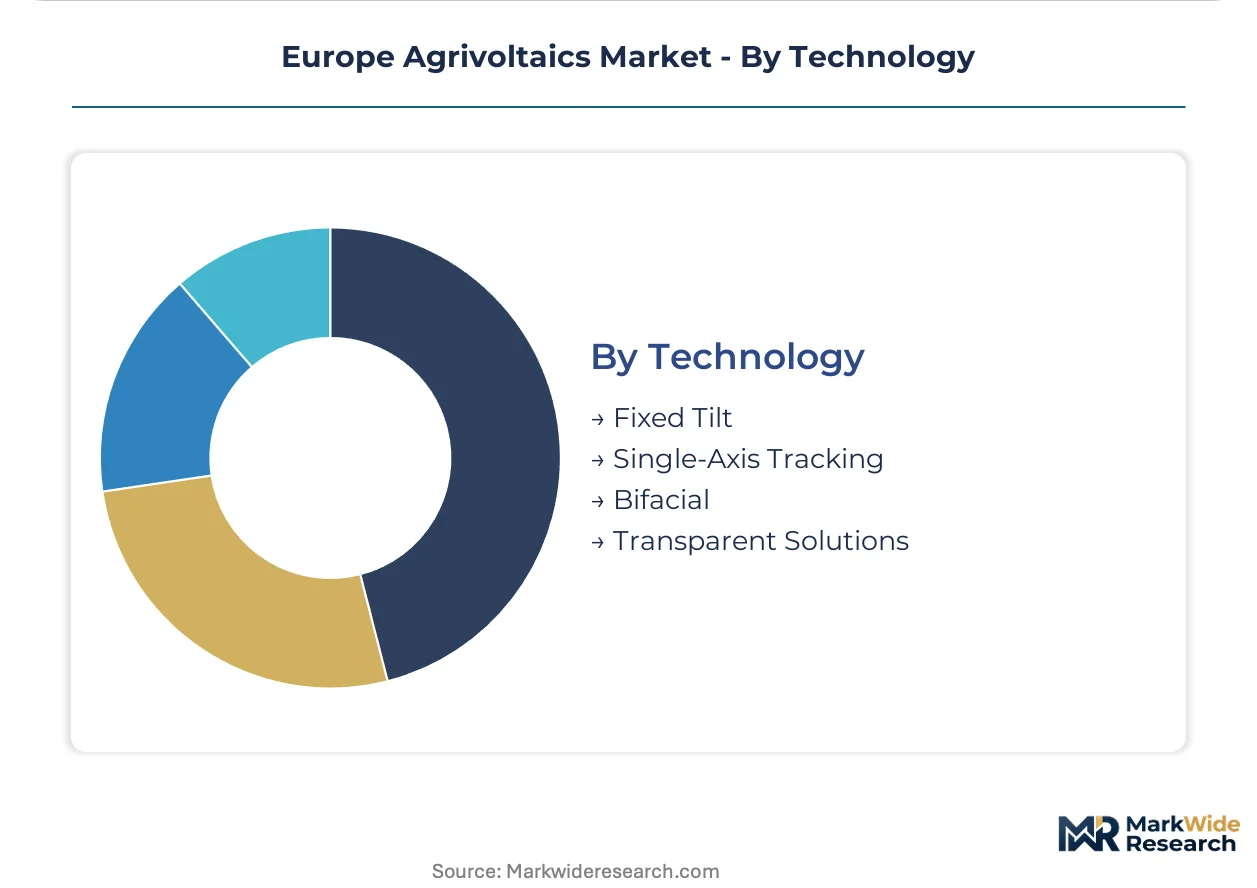
Fixed Tilt maintains installed capacity leadership, with Bifacial posting the steepest expansion trajectory as albedo economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are channeling agrivoltaic investment toward jurisdictions with streamlined permitting and stacked subsidy eligibility. France, Germany, and Italy currently capture the majority of capital deployment, though Spain and the Netherlands are accelerating project pipelines through policy refinements.
France
Wine cooperatives in Bordeaux and Champagne drive equipment demand through cooperative procurement structures. The national agrivoltaic framework established by the Ministry of Ecological Transition provides permitting certainty for vineyard and orchard installations. Sun'Agri operates demonstration arrays across southern viticulture zones, validating crop-specific light transmission algorithms.
Germany
Bavarian dairy and hop farms anchor mechanized cultivation beneath elevated arrays, submitting annual yield reports to grid regulators. EEG tariff restructuring by the Federal Network Agency differentiates compensation based on documented agricultural continuity. Next2Sun deploys vertical bifacial configurations across northern cereal zones, optimizing rear-side albedo capture.
Italy
Farmer-owned energy cooperatives in Emilia-Romagna displace third-party lease arrangements through pooled land access and shared balance-of-plant costs. Enel Green Power integrates utility-scale deployments with grid management platforms across the Po Valley. REM Tec supplies tracking-adapted mounting systems for specialty crop configurations in Piedmont.
Spain
Extensive arid zones in Andalusia remain underpenetrated for olive and almond co-location despite high solar irradiance. The Ministry for the Ecological Transition is finalizing agrivoltaic-specific regulations to unlock southern plateau development. GreenYellow positions project development capacity across Extremadura and Castilla-La Mancha agricultural corridors.
Netherlands
Greenhouse horticulture operators in Westland and Noord-Brabant pilot semi-transparent organic photovoltaics for spectral-selective protected cultivation. The national climate agreement conditions agricultural subsidies on renewable energy integration. BayWa r.e. develops elevated array configurations compatible with mechanized vegetable harvesting beneath.
Europe Agrivoltaics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue spectral engineering and cooperative ownership models. The vendor base stratifies across three tiers: utility-scale developers with integrated energy platforms, specialized mounting system fabricators, and agronomic consultancies bridging photovoltaic and crop science expertise. Dominant competitive moves include strategic partnerships with agricultural cooperatives and technology licensing for bifacial light-transmission algorithms.
Within the utility-scale developer tier, Enel Green Power and Akuo Energy exemplify platform-integrated deployment models across Italian and French pipelines. Falck Renewables occupies a specialized position through agronomic partnership structures. Among mounting system specialists, Gonvarri Solar Steel represents steel-adaptive fabrication capabilities for varied European terrain.
| Leading Market Players |
|---|
| Akuo Energy |
| Falck Renewables |
| Enel Green Power |
| REM Tec |
| GreenYellow |
| Sun'Agri |
| Next2Sun |
| Gonvarri Solar Steel |
| BayWa r.e. |
| Others |
Value Network & Pricing Analysis
EU Green Deal land-use conditionality gates qualified supply access and premium-tier pricing for agrivoltaic configurations that satisfy dual-use verification requirements. The regulatory mandate compresses procurement timelines for compliant mounting systems and bifacial panels while elevating cost structures for non-qualifying alternatives.
Pricing Analysis
Direct-to-farmer channels capture margin compression from cooperative aggregation models displacing third-party lease markups. Project-based pricing dominates utility-scale deployments, with differentiation driven by ECHA REACH certification tier and steel-input volume scale. Pricing pressure stems from steel price volatility feeding into mounting system fabrication costs. Smallholder farmers exhibit highest price sensitivity, while energy companies demonstrate lowest sensitivity due to long-term power purchase agreement revenue visibility.
Supply Chain Analysis
ECHA REACH certification gates panel supplier qualification across member states, with glass-glass module production concentrated in Germany, France, and Italy. Structural steel for mounting systems draws from Spanish and German fabrication capacity, while lithium-ion storage components rest on South Korean and Chinese cell supply. Single-source vulnerability runs through specialized agronomic consultancy capacity for crop-light optimization algorithms. Distribution runs through EPC contractors with agricultural sector expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe agrivoltaics market compounds returns through layered regulatory incentives, with Common Agricultural Policy eco-scheme payments stacking with EEG tariff structures to drive demand acceleration.
For Market Incumbents: Acquire specialized agronomic consultancy capabilities to defend against technology convergence threats from spectral engineering specialists. Prioritize backward integration into steel-adaptive mounting fabrication to buffer margin compression from commodity volatility. Expand certification investment in ECHA REACH compliance documentation to maintain subsidy eligibility gatekeeping.
For New Entrants and Emerging Players: Digital-channel farmer cooperative platforms offer lowest customer acquisition cost penetration routes. Target Spain's southern plateau olive and almond zones as the most penetrable geography given regulatory finalization timelines. Pursue semi-transparent organic photovoltaic go-to-market positioning for greenhouse horticulture applications.
For Investors and Strategic Acquirers: Roll-up economics work for fragmented mounting system fabricators because terrain-adaptive engineering capabilities remain geographically dispersed without scale leaders. Five-to-ten year viability hinges on EU Green Deal conditionality persistence. Watch German grid connection queue clearance rates as the signal for project IRR inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Agrivoltaic-Specific Permitting Investment | France's national framework reduces regulatory uncertainty for vineyard and orchard landowners. |
| Bifacial Technology Licensing | Light-transmission algorithms for vine phenology stages compress payback periods in Champagne. |
| Cooperative Ownership Platform Development | Italy's Po Valley aggregation models pool fragmented landholdings for utility-scale procurement. |
| Steel Supply Agreement Structuring | Long-term contracts with German and Spanish fabricators hedge mounting system margin volatility. |
| Grid Interconnection Queue Management | EEG tariff applicants in Bavaria face multi-year delays compressing project timeline economics. |
Research Methodology
Coverage spans France, Germany, Italy, Spain, and the Netherlands, with primary inputs from each market's regulatory and project development clusters. Data combines interviews with agrivoltaic project developers, agricultural cooperative managers, EPC contractors, and grid operators with secondary validation from EU Green Deal policy documents, EEG tariff filings, Common Agricultural Policy implementation guidance, and ECHA REACH compliance databases. Bottom-up project pipeline aggregation triangulates against top-down subsidy allocation analysis.
Rate-of-change decomposition separates technology adoption velocity from regulatory incentive phase-in effects across the analysis window. Segmentation models incorporate technology type, application, end user, and country-specific regulatory framework dimensions. CAGRs derive from installed capacity build-up curves and revenue-per-hectare economics by configuration type. Forecast inputs include steel price trajectory assumptions and grid interconnection clearance rate projections.
Steel price volatility, German grid queue duration extension, and Common Agricultural Policy payment recalibration are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in EU Green Deal conditionality enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Smart Farming Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
Global Blockchain in Agriculture Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
US Smart Agriculture Market