
 Global Blockchain in Agriculture Market | 2026-2036
Global Blockchain in Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain in Agriculture Market Foresight
Permissioned ledger architectures with embedded IoT oracles is reshaping how agricultural data layers authenticate field-to-shelf provenance. IBM leverages its Hyperledger Fabric deployments to anchor enterprise-grade traceability networks across multinational food conglomerates. SAP SE competes through deep ERP integration that extends blockchain workflows into existing procurement and inventory systems. OriginTrail specializes in decentralized knowledge graph protocols that differentiate its approach from conventional linear chain structures.
Blockchain in agriculture refers to cryptographically linked distributed databases that immutably record transactions, sensor readings, and custody transfers across food production ecosystems, typically employing consensus mechanisms with sub-second finality for high-throughput supply chain environments. The technology's primary commercial purpose is to eliminate information asymmetry between disconnected agricultural stakeholders while automating compliance verification through programmable smart contract logic. Traceability Solutions currently dominates application spending as food safety scandals and regulatory disclosure requirements intensify audit burdens across supply chain managers and retailers. Private Blockchain deployments lead technology adoption among large agribusinesses seeking controlled participant access, though Consortium Blockchain configurations are gaining traction among cooperative networks that require shared governance without full public transparency.
The EU Green Deal and its accompanying farm-to-fork strategy mandate granular traceability disclosures that directly shape platform requirements for any supplier accessing European consumer markets. The USDA's emerging bioengineered food disclosure rules and China's SAMR food safety traceability guidelines are creating parallel compliance architectures that vendors must simultaneously address. Brazil's ANVISA and India's FSSAI are developing comparable digital provenance frameworks that will expand addressable market scope for multi-jurisdictional platform providers. Stakeholders must monitor which regulatory jurisdictions will mandate interoperable data standards versus permitting proprietary silos, as this determination will fundamentally reshape competitive moats and partnership requirements across the technology stack.
Market Dynamics
Permissioned ledger architectures with embedded IoT oracles are compressing authentication timelines across field-to-shelf provenance chains, forcing agribusinesses to reconfigure data infrastructure around sub-second finality requirements rather than batch-processing legacy systems.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:Granular traceability disclosures required for European market access are accelerating platform procurement cycles among export-dependent producers.
- Soybean certification demand:Brazil's agricultural exporters require immutable certification records to satisfy EU import verification protocols, creating concentrated deployment urgency.
- IoT oracle integration:Sensor-to-chain data pipelines are automating compliance verification without manual audit intervention, reducing operational overhead for supply chain managers.
Market Restraints
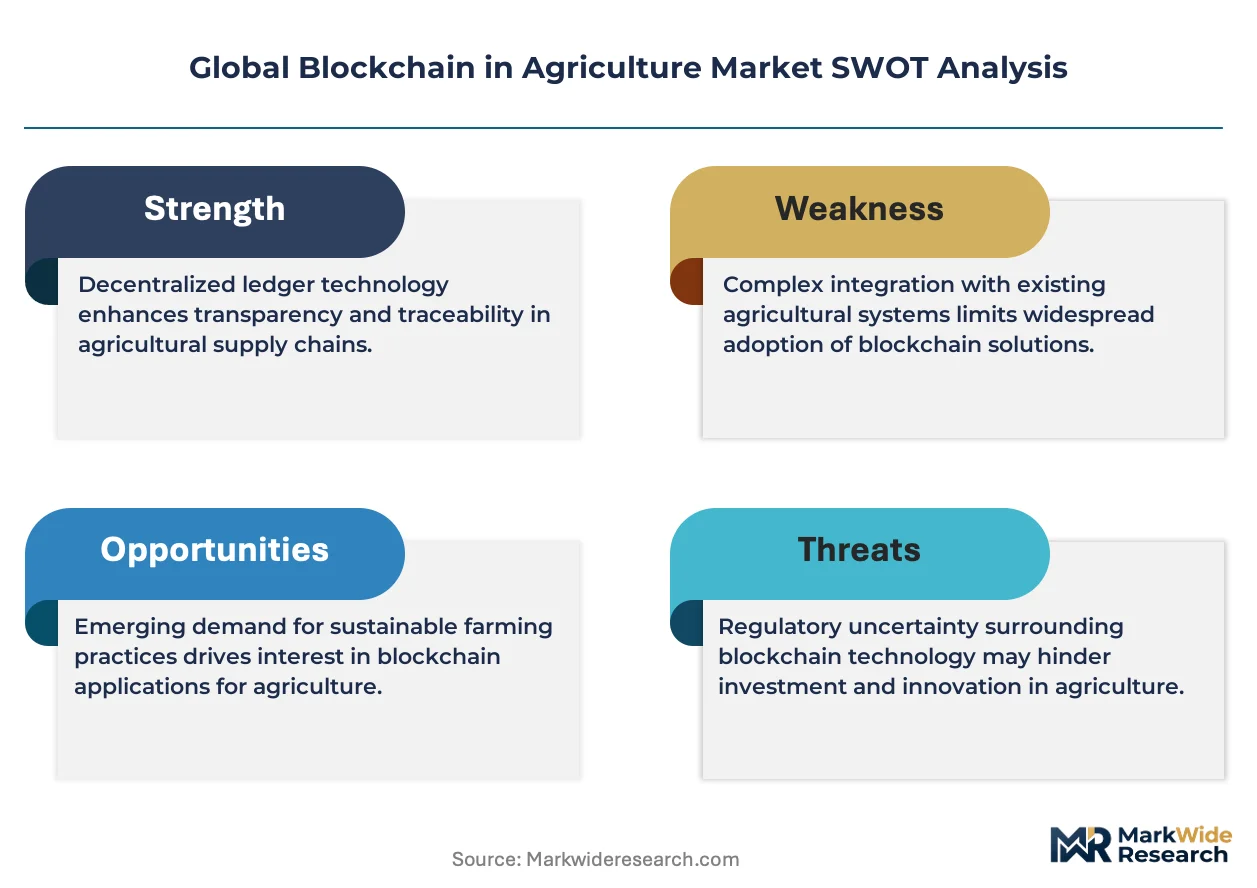
- Energy-intensive consensus mechanisms:Proof-of-work validation protocols impose prohibitive computational costs for smallholder cooperative networks with limited infrastructure budgets.
- Interoperability fragmentation:Proprietary data standards across competing platforms prevent seamless cross-chain verification, locking participants into single-vendor ecosystems.
- Connectivity infrastructure gaps:Rural agricultural regions in sub-Saharan Africa and Southeast Asia lack reliable broadband coverage necessary for real-time distributed ledger synchronization.
Strategic Opportunities
- Carbon credit verification:Regenerative agriculture practitioners in Australia and Canada seek blockchain-anchored soil carbon sequestration records for voluntary carbon market participation.
- India's FSSAI digital provenance framework:Emerging mandatory traceability guidelines for domestic food safety are creating first-mover advantages for compliance-ready platform providers.
- Smart contract automation:Programmable payment triggers upon IoT-confirmed delivery milestones are displacing letter-of-credit arrangements in cross-border agricultural trade.
Industry Challenges
- Distributed systems engineering talent scarcity:Agricultural technology vendors struggle to recruit cryptographers and consensus protocol specialists willing to relocate to rural deployment sites.
- Legacy ERP integration complexity:Decades-old procurement and inventory management systems require expensive middleware development to achieve blockchain data interoperability without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain in Agriculture Market |
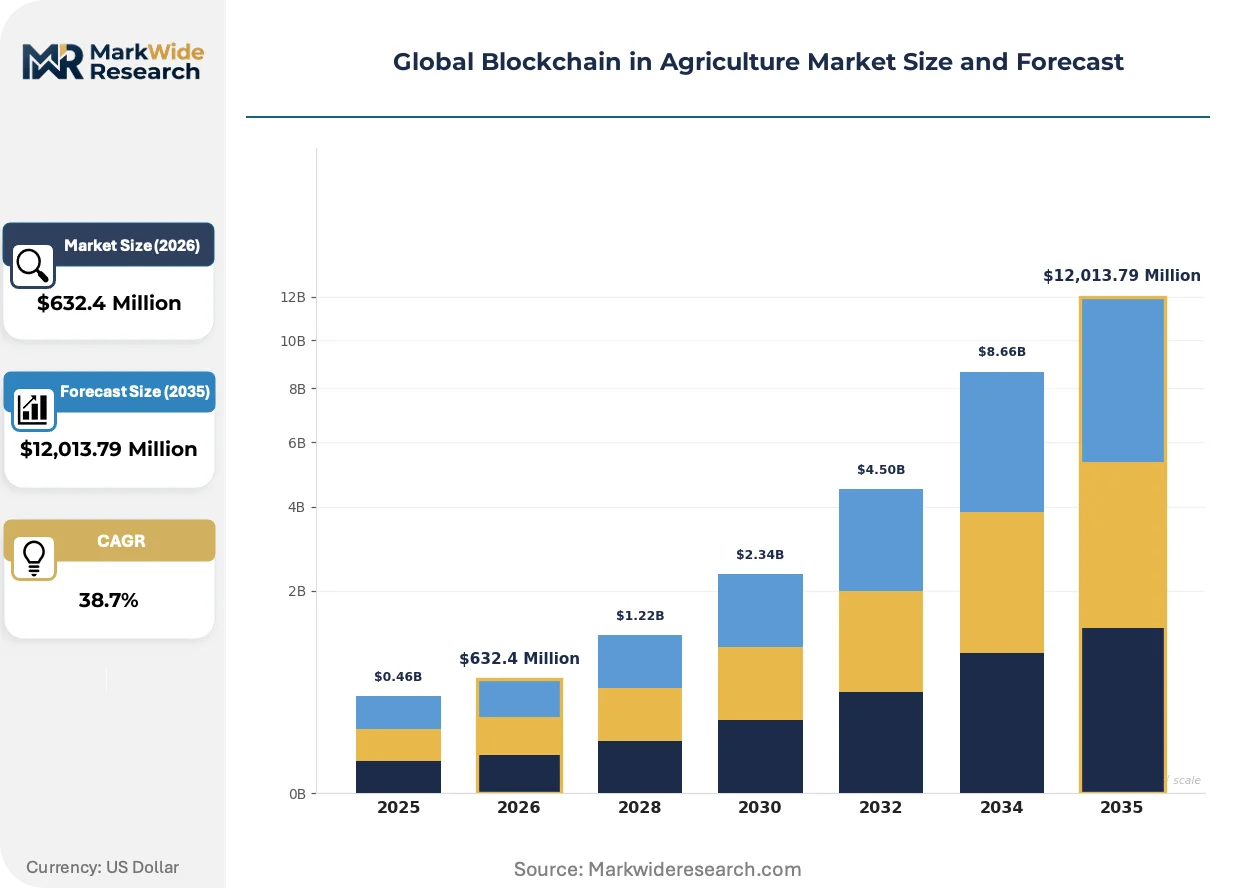
| Market Size in 2026 | $632.4 Million |
| Market Size in 2035 | $12,013.79 Million |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Contracts, Traceability Solutions, Payment Systems, Data Management Tools End User: Farmers, Retailers, Supply Chain Managers, Cooperatives Application: Supply Chain Verification, Crop Monitoring, Inventory Management, Asset Tracking Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain |
| Companies Covered | IBM, Microsoft, SAP SE, Ambrosus, OriginTrail, VeChain, AgriDigital, Ripe.io, Provenance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain in Agriculture Market Shifts & Advancements
Sensor-to-chain authentication pipelines are replacing paper-based custody documentation across agricultural supply networks, compressing provenance verification from weeks to seconds and eliminating information asymmetries between disconnected stakeholders.
Edge computing nodes with embedded cryptographic modules are digitizing field-level data collection for high-value crop monitoring. Specialty coffee cooperatives in Colombia and Kenya deploy these devices to anchor harvest timestamps and geolocation coordinates directly to permissioned ledgers without cloud intermediation. This architecture is digitizing trust relationships between smallholder producers and distant roasters who previously relied on third-party certification bodies.
China's SAMR food safety traceability guidelines are mandating granular production record disclosure for imported agricultural commodities entering domestic distribution channels. The regulation requires immutable batch-level documentation from foreign suppliers, compelling export-oriented packers in Chile and New Zealand to deploy Mandarin-language blockchain interfaces. Seafood and dairy processors face the steepest compliance curves due to complex multi-node supply chains spanning aquaculture farms and pastoral grazing operations.
Direct-to-retailer procurement platforms are displacing traditional commodity broker intermediaries in specialty grain and produce categories. North American organic vegetable growers now contract directly with regional grocery chains through blockchain-anchored forward agreements that lock pricing upon planting rather than harvest. This pattern is most visible in California's Central Valley and the Netherlands' greenhouse clusters, where vertical integration between cultivation and retail shelf planning compresses margin extraction by legacy distributors.
Global Blockchain in Agriculture Market Segmentation
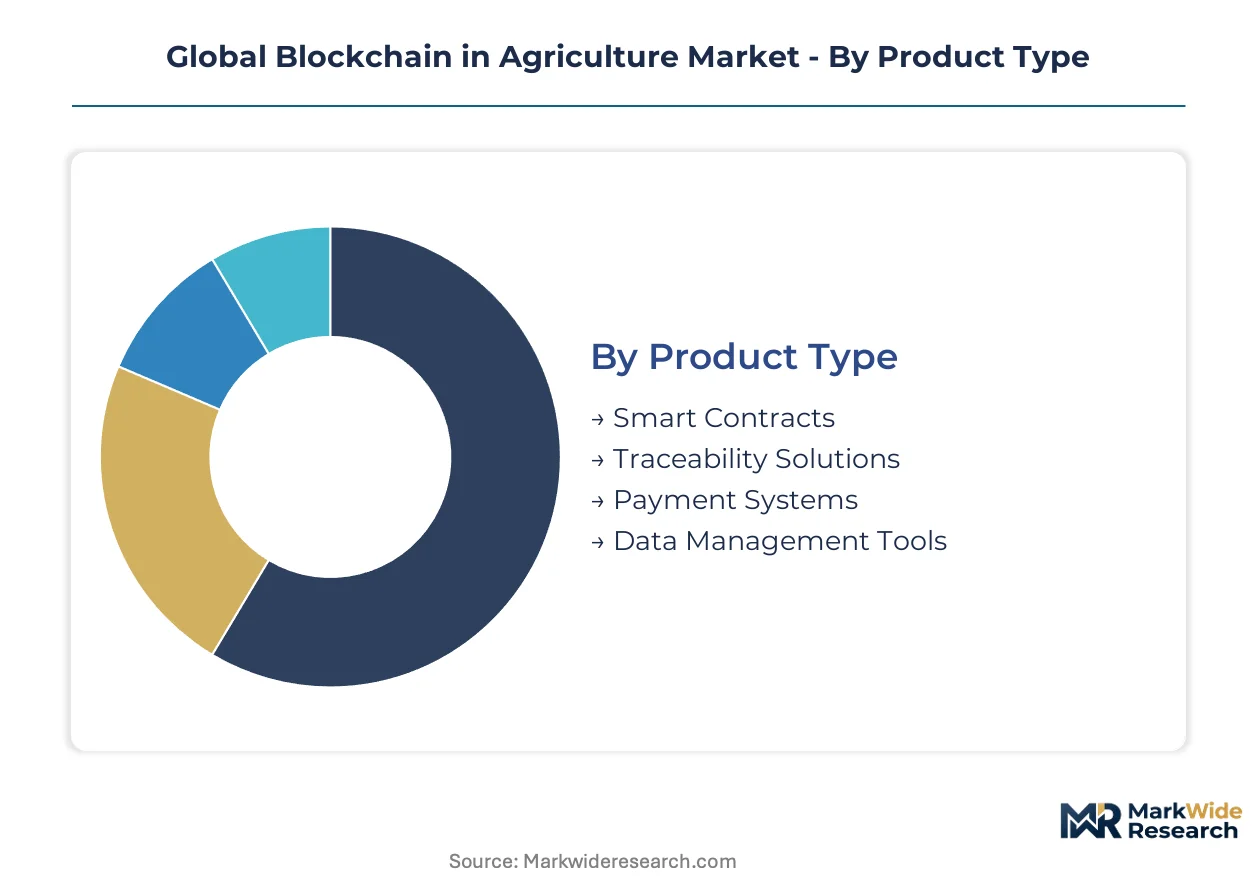
Blockchain in agriculture segments around governance models, functional applications, and stakeholder access tiers. Each dimension shapes deployment architecture, cost structures, and interoperability requirements across farm-to-fork ecosystems.
Product Type:
Use-case spectrum spans executable automation, audit documentation, settlement infrastructure, and data orchestration layers.
- Traceability Solutions:Immutable provenance ledgers anchor batch-level documentation from cultivation through retail shelf placement. EU Green Deal farm-to-fork mandates compress procurement timelines among Brazilian soybean exporters and Chilean fruit packers seeking European market access.
- Smart Contracts:Programmable logic automates payment triggers upon IoT-confirmed delivery milestones, displacing letter-of-credit arrangements in cross-border agricultural trade. Australian grain handlers and Dutch greenhouse operators deploy these for forward pricing agreements locked at planting.
- Payment Systems:Cryptographic settlement rails reduce correspondent banking delays for smallholder cooperatives in Kenya and Colombia.
- Data Management Tools:Distributed storage protocols aggregate sensor streams and certification records for compliance reporting to India's FSSAI and China's SAMR.
Established volume favors Traceability Solutions; emerging adoption favors Smart Contracts.
End User:
Customer archetypes range from dispersed smallholders to consolidated procurement networks with divergent technical capacity.
- Supply Chain Managers:Enterprise-grade orchestration platforms coordinate multi-node verification across cold chain logistics and customs documentation. Large agribusinesses in Argentina and Canada deploy these for EU and US export compliance.
- Retailers:Direct-to-shelf provenance interfaces satisfy consumer transparency demands and regulatory disclosure requirements. North American grocery chains and European supermarket cooperatives anchor private consortium networks.
- Farmers:Mobile-first applications digitize field records for individual producers with limited infrastructure budgets.
- Cooperatives:Shared governance models enable pooled certification costs among Colombian coffee growers and Kenyan tea associations.
Procurement concentration elevates Supply Chain Managers; cooperative digitization elevates emerging platform demand among farmer associations.
Application:
Functional deployment targets verification fidelity, biological monitoring, stock synchronization, and asset custody.
- Supply Chain Verification:End-to-end provenance authentication eliminates information asymmetry between disconnected stakeholders. New Zealand dairy processors and Norwegian aquaculture operators deploy these for China's SAMR import documentation.
- Crop Monitoring:Sensor-to-chain pipelines anchor harvest timestamps and geolocation coordinates for specialty coffee and premium winegrape categories. Edge computing nodes with embedded cryptographic modules enable field-level data collection without cloud intermediation.
- Inventory Management:Real-time stock synchronization reduces waste in perishable produce distribution networks.
- Asset Tracking:Equipment and livestock custody records support insurance claims and breeding documentation.
Regulatory pressure concentrates deployment in Supply Chain Verification; sensor cost declines accelerate Crop Monitoring expansion.
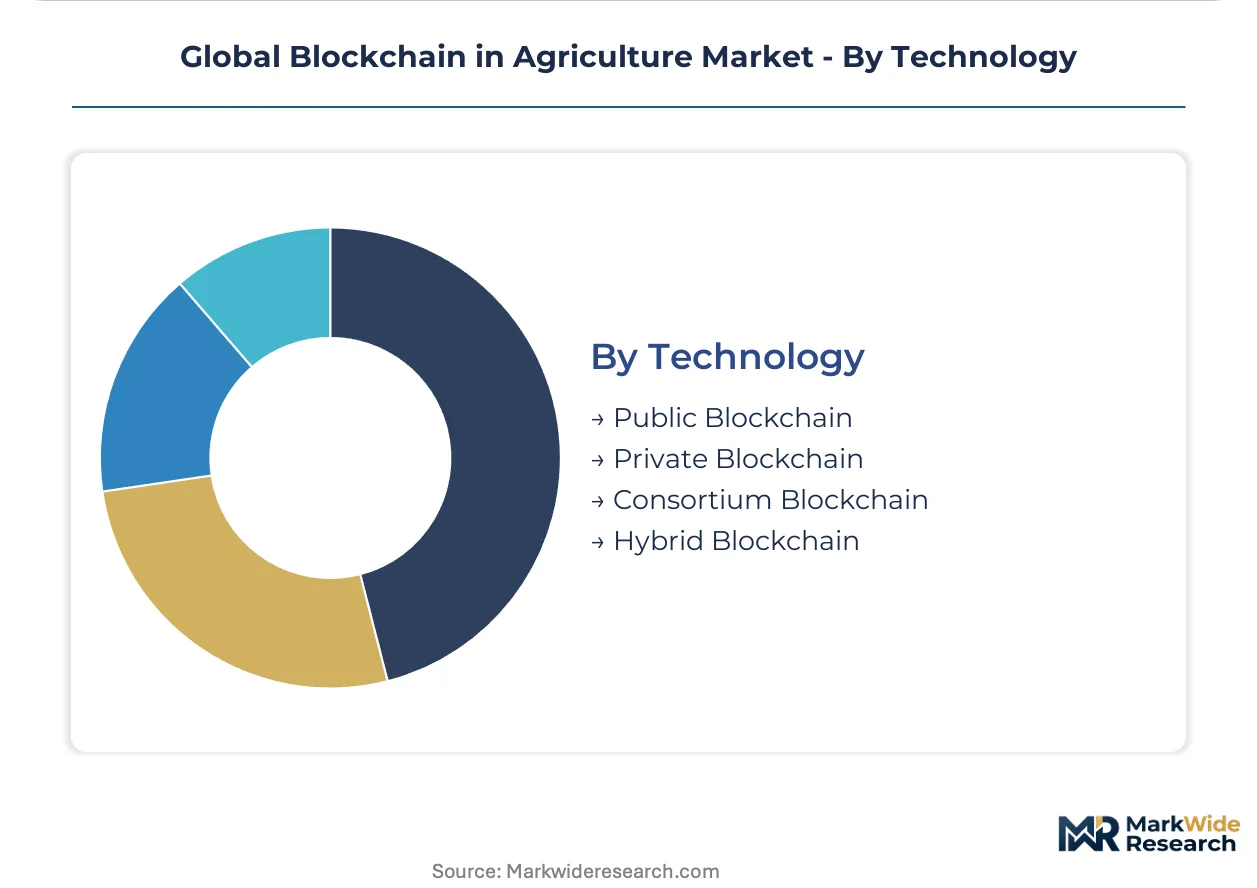
Technology:
Governance architecture determines participant access, consensus overhead, and interoperability boundaries.
- Private Blockchain:Permissioned ledgers with controlled node admission dominate large agribusiness deployments seeking sub-second finality and data sovereignty. Cargill and Bunge anchor internal networks for procurement and inventory workflows.
- Consortium Blockchain:Shared governance without full public transparency gains traction among cooperative networks and industry associations. Dutch flower auction cooperatives and Australian wool marketing groups deploy these for collective certification.
- Public Blockchain:Open participation models attract carbon credit verification and voluntary sustainability standard projects.
- Hybrid Blockchain:Selective disclosure architectures balance transparency requirements with competitive confidentiality.
Enterprise control favors Private Blockchain; multi-party trust requirements favor Consortium Blockchain configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large agribusinesses and export-dependent cooperatives dominate procurement of blockchain traceability platforms, with deployment intensity tracking regulatory enforcement timelines across major agricultural economies.
Brazil
Soybean exporters and coffee cooperatives drive platform adoption to satisfy EU import verification protocols. ANVISA is developing digital provenance frameworks that will expand mandatory disclosure requirements for agricultural commodities. São Paulo state anchors the densest cluster of deployment activity, where grain handlers integrate IoT-to-chain pipelines for EU-bound shipments.
United States
Enterprise agribusinesses and organic vegetable growers deploy private ledgers for supply chain verification and direct-to-retailer contracting. The USDA's bioengineered food disclosure rules shape platform requirements for domestic compliance. California's Central Valley concentrates greenhouse and specialty crop implementations where vertical coordination between cultivation and retail shelf planning displaces legacy distributors.
China
Import-dependent processors and domestic food safety authorities mandate granular traceability for foreign agricultural commodities entering distribution channels. SAMR food safety traceability guidelines compel export-oriented packers in partner countries to deploy Mandarin-language blockchain interfaces. Yangtze River Delta processing hubs enforce the strictest documentation requirements for dairy and seafood imports.
Germany
Food retailers and supermarket cooperatives anchor private consortium networks to satisfy consumer transparency demands and EU Green Deal farm-to-fork mandates. EFSA disclosure requirements shape platform specifications for suppliers accessing European consumer markets. The Netherlands-Germany border region concentrates greenhouse cluster implementations where real-time inventory synchronization reduces perishable produce waste.
India
Domestic food safety compliance and export certification drive platform procurement among spice processors and grain traders. FSSAI's emerging digital provenance framework creates first-mover advantages for compliance-ready providers. Maharashtra and Gujarat host the most active pilot deployments where cooperative networks test shared governance models for pooled certification costs.
Global Blockchain in Agriculture Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages concentrate among enterprise technology vendors while niche protocols carve defensible positions in knowledge graph and sensor integration domains. The vendor base spans three strategic archetypes: ERP-integrated platform providers, standalone traceability specialists, and IoT-native oracle developers. Dominant competitive moves include strategic partnerships between ledger infrastructure and sensor hardware providers, plus geographic expansion through regulatory compliance bundling for multi-jurisdictional exporters.
Within the enterprise platform tier, IBM and Microsoft represent the scale-driven anchor positions, while SAP SE occupies the deep ERP integration archetype. OriginTrail exemplifies the specialized protocol approach with its decentralized knowledge graph architecture that differentiates from conventional linear chain structures. These three entities collectively illustrate how competitive positioning stratifies between horizontal technology stacks and vertical application depth.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| SAP SE |
| Ambrosus |
| OriginTrail |
| VeChain |
| AgriDigital |
| Ripe.io |
| Provenance |
| Others |
Supply & Pricing Matrix
EU Green Deal farm-to-fork compliance exposure compresses both platform pricing spreads and supply chain architecture, forcing vendors to absorb certification middleware costs while agribusinesses consolidate procurement around multi-jurisdictional providers capable of unified disclosure workflows.
Pricing Analysis
Cost-plus contracts indexed to IoT hardware and cloud compute unit economics dominate enterprise deployments, with subscription tiers stratifying across premium certification-grade, standard compliance-ready, and economy sensor-only levels. Price differentiation hinges on ERP integration depth and named regulatory bundle coverage—EU EFSA, China SAMR, India FSSAI. Cost compression in the economy tier intensifies as open-source ledger protocols commoditize base-layer functionality. Smallholder cooperatives exhibit acute price sensitivity; multinational agribusinesses prioritize compliance assurance over unit cost.
Supply Chain Analysis
Supply-chain finance facilities with extended payment terms anchor vendor-cashflow relationships, particularly for sensor hardware providers serving Brazilian soybean exporters and Colombian coffee cooperatives. Manufacturing concentrates in Taiwan for cryptographic modules, Germany for industrial edge-computing nodes, and China for mass-market IoT sensors. Component dependencies span semiconductor wafers, LoRaWAN communication chipsets, and tamper-resistant secure elements. Single-source vulnerability in cryptographic hardware sourcing threatens deployment timelines. Distribution runs through systems integrators with agribusiness vertical expertise rather than direct vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation across incompatible ledger standards creates white-space opportunities for interoperability middleware providers, as export-dependent producers demand unified compliance interfaces spanning EU, Chinese, and Indian regulatory regimes.
For Market Incumbents: Harden consortium governance positions by embedding IoT oracle partnerships that lock in sensor-to-chain data pipelines, while acquiring niche knowledge-graph specialists to neutralize OriginTrail's decentralized architecture threat. Prioritize certification investment in India's emerging FSSAI framework to preempt first-mover displacement. For New Entrants and Emerging Players: Mid-tier grain handlers in Argentina and Australia represent the most penetrable entry point, as these export-dependent operators lack internal distributed systems engineering capacity and face acute EU compliance deadlines. Carbon credit verification protocols for regenerative agriculture practitioners offer a second white-space channel with voluntary-market pricing flexibility. Lead with API-first integration to bypass legacy ERP replacement cycles. For Investors and Strategic Acquirers: The market sits at a standards-coalescence phase that favors vertical application depth over horizontal infrastructure breadth. Long-term viability across the projection horizon rests on regulatory certification moats rather than technology differentiation. Target acquisition archetypes: IoT-native oracle developers with field-hardened deployments in Brazil or Kenya, and Mandarin-interface specialists with SAMR compliance track records. The signal to watch is EU-India mutual recognition agreements for digital provenance standards.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Oracle Partnership | Embedded sensor-to-chain pipelines lock in Brazilian soybean exporters for EU Green Deal compliance. |
| Regulatory Certification Bundle | Unified EFSA-SAMR-FSSAI interfaces reduce procurement friction for multi-jurisdictional agribusinesses. |
| Knowledge Graph Acquisition | Decentralized provenance architectures differentiate from linear Hyperledger Fabric deployments. |
| Carbon Credit Verification Launch | Soil sequestration records anchor Australian and Canadian farmers to voluntary carbon markets. |
| Consortium Governance Expansion | Shared ledger infrastructure pools certification costs for Colombian coffee and Kenyan tea cooperatives. |
Research Methodology
Operator-level perspectives from supply chain managers at multinational agribusinesses, IoT platform engineers, regulatory affairs leads at certification bodies, and procurement officers at European supermarket cooperatives anchored the qualitative base. Secondary validation drew from EU Green Deal implementation documents, ANVISA digital framework drafts, SAMR food safety traceability guidelines, and Hyperledger Fabric deployment case studies. Bottom-up deployment counts across Brazil, Germany, China, India, and the United States triangulated against top-down platform revenue estimates.
Scenario-bracketing around regulatory enforcement timelines—EU farm-to-fork mandate phase-ins, FSSAI mandatory disclosure triggers, and SAMR import documentation expansion—shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include governance architecture (private, consortium, public, hybrid), application type (traceability, smart contracts, payments, data management), and stakeholder access tier (enterprise agribusiness, cooperative network, smallholder individual). CAGRs derived from deployment velocity curves weighted by export market dependency and compliance deadline proximity. Industry-specific forecast inputs encompassed IoT sensor cost decline trajectories and cryptographic module availability constraints.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price volatility, cross-border data localization enforcement, or semiconductor foundry capacity would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization pace and sensor hardware cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Qatar Agriculture Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Smart Farming Market
Smart Agriculture
Smart Irrigation Software Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Fertigation Monitoring Market