
 Fertigation Monitoring Market | 2026-2036
Fertigation Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Fertigation Monitoring Market Analysis
Sensor-based subscription services is pivoting the commercial model from hardware ownership to recurring revenue in fertigation monitoring. Netafim leverages its irrigation heritage to bundle monitoring with drip system installations. Jain Irrigation Systems anchors its position through backward integration into pump and valve manufacturing. The Toro Company competes on brand strength in golf and turf segments where precision nutrient delivery commands premium pricing.
Fertigation monitoring encompasses the integrated measurement and control of fertilizer injection into irrigation water, typically employing electrical conductivity sensors, pH probes, and flow meters to maintain nutrient solution concentrations within crop-specific ranges of 1.0 to 4.0 dS/m. Its primary purpose is to optimize nutrient use efficiency while preventing root zone salinity damage in intensive cropping systems. Drip irrigation technology leads installed value due to mature compatibility with inline fertigation, though sensor-based systems represent the fastest-expanding margin pool as growers seek autonomous adjustment capabilities. Controller components capture disproportionate software value as edge computing enables localized decision-making without cloud dependency.
The EPA enforces Clean Water Act limits on agricultural nutrient discharge, compelling growers to document fertilizer application rates and runoff prevention measures. California's State Water Resources Control Board imposes the nation's strictest agricultural water quality regulations through Irrigated Lands Regulatory Program requirements. The EU Green Deal's Farm to Fork 50% pesticide reduction target indirectly intensifies fertigation precision demands as growers substitute targeted nutrient management for chemical interventions. Stakeholders must weigh capital intensity against regulatory audit exposure when selecting monitoring system architectures.
Market Dynamics
Sensor-to-cloud integration is compressing decision cycles from days to hours, forcing hardware vendors to restructure around recurring software revenue rather than unit sales.
Growth Catalysts
- EU Green Deal Farm to Fork:The 50% pesticide reduction mandate intensifies precision nutrient management as growers substitute targeted fertigation for chemical interventions. Vegetable producers in the Netherlands and Spain accelerate sensor deployment to maintain yields under tighter residue limits.
- Drip irrigation maturity:Inline fertigation compatibility with established drip infrastructure lowers adoption friction for monitoring add-ons. California's Central Valley farming corridor concentrates retrofit demand where drip penetration already exceeds 70% in processing tomatoes and almonds.
- Edge computing enablement:Localized processing eliminates cloud latency for autonomous pH and EC adjustments. Controller manufacturers embed ARM-based chipsets to execute crop-specific algorithms without connectivity dependency.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for sensor microcontrollers concentrates in Taiwan and South Korea, exposing lead times to geopolitical friction. Analog-to-digital converter chips face 26-week order backlogs during capacity crunches.
- Calibration labor intensity:pH probe drift requires weekly manual verification in high-salinity groundwater zones, inflating total cost of ownership beyond hardware purchase price. Labor availability constrains viable deployment scale for mid-size growers.
- Copper and lithium volatility:Wiring harnesses and battery-backed controllers face input cost swings from commodity markets. Price spikes in 2022-2023 compressed system integrator margins by 8-12 percentage points.
Strategic Opportunities
- Subscription telemetry services:Sensor-as-a-service models convert capital expenditure to operating budgets, expanding addressable base among cash-constrained specialty crop growers. Data analytics packages command 40-60% gross margins versus 20-25% for hardware.
- Controlled environment agriculture:Vertical farms and greenhouse complexes in the United Arab Emirates and Saudi Arabia import monitoring systems for closed-loop hydroponic operations. These facilities prioritize precision over capital cost due to water scarcity premiums.
- Carbon accounting integration:Nitrogen use efficiency metrics feed into Scope 3 emissions reporting for food processors. Sensor networks that document fertilizer reduction generate verifiable credits for supply chain decarbonization claims.
Industry Challenges
- Agronomy-IT skill convergence:System deployment requires staff fluent in both crop physiology and network configuration. Vocational training pipelines in agricultural regions lag sensor complexity, extending implementation timelines.
- Legacy controller retrofit friction:Proprietary communication protocols from 1990s-era irrigation systems block seamless sensor integration. Growers face full replacement costs rather than modular upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertigation Monitoring Market |
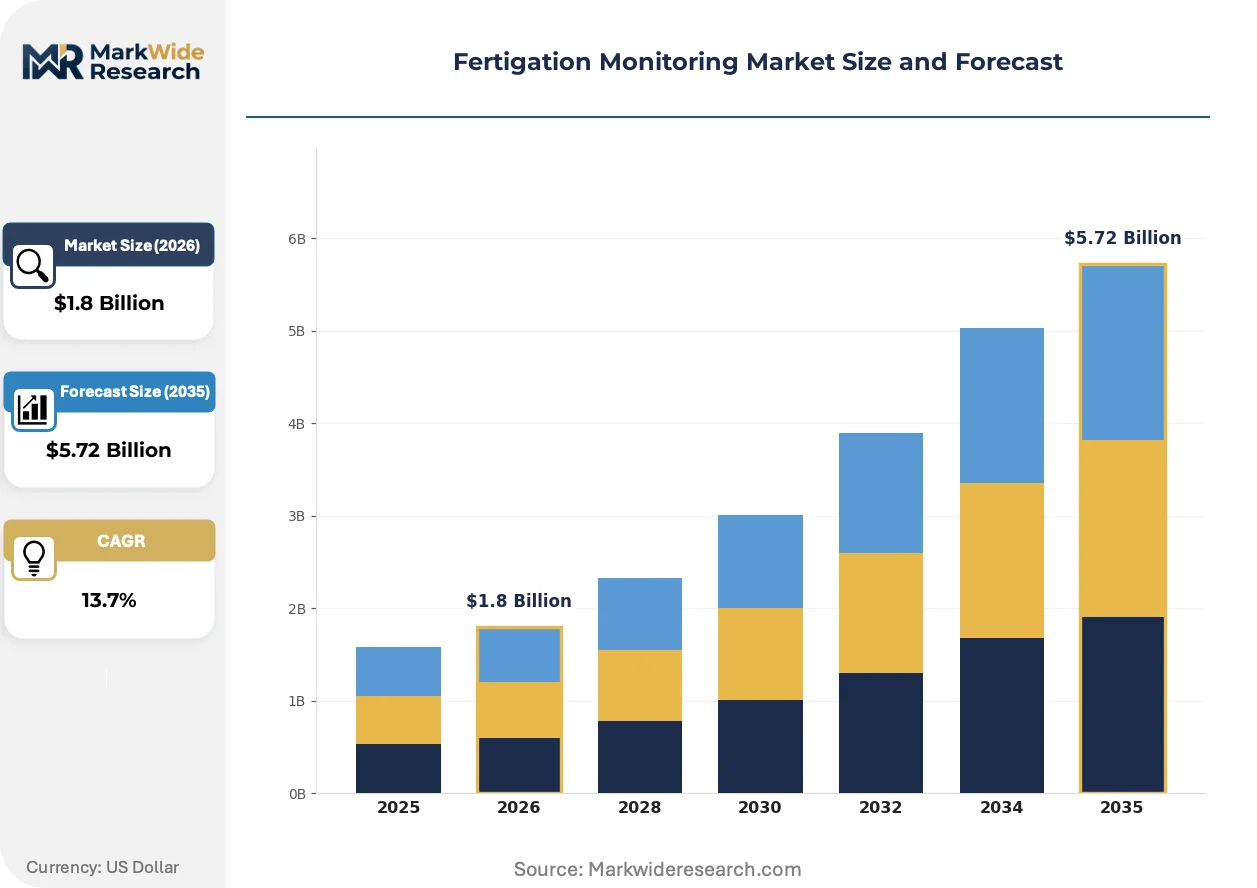
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Drip Irrigation, Microirrigation, Fertilizer Injection, Sensor-Based Systems Component: Controllers, Sensors, Pumps, Valves Application: Agriculture, Greenhouses, Landscaping, Horticulture End User: Farmers, Agricultural Cooperatives, Nurseries, Research Institutions |
| Companies Covered | Netafim, Jain Irrigation Systems, The Toro Company, Irritec, Novedades Agrícolas, Soilmoisture Equipment Corp., LaMotte Company, Argus Control Systems, Rain Bird Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertigation Monitoring Market Emerging Trajectories
Machine learning inference at the sensor node is collapsing the feedback loop between measurement and actuation, eliminating the latency that previously constrained autonomous fertigation.
Hyperspectral imaging is rewriting nutrient stress detection by capturing chlorophyll fluorescence signatures invisible to RGB cameras. Strawberry and lettuce growers in California deploy tractor-mounted units to map nitrogen deficiency at 10-meter resolution. The technology compresses soil sampling costs while enabling variable-rate injection prescriptions that previously required laboratory analysis.
California's State Water Resources Control Board Irrigated Lands Regulatory Program mandates documented fertilizer application rates and runoff prevention measures for enrolled growers. The audit exposure compels investment in data-logging infrastructure that timestamps every injection event. Vegetable operations in the Salinas Valley prioritize systems with tamper-evident recordkeeping to satisfy enforcement inspections.
Consolidated procurement by agricultural cooperatives is displacing individual grower purchasing for monitoring hardware. Central Valley-based processing tomato cooperatives negotiate fleet pricing for 50+ member farms, extracting service commitments and training inclusion that solo buyers cannot command. The channel shift concentrates vendor sales resources on relationship management rather than direct field demonstrations.
Fertigation Monitoring Market Segmentation
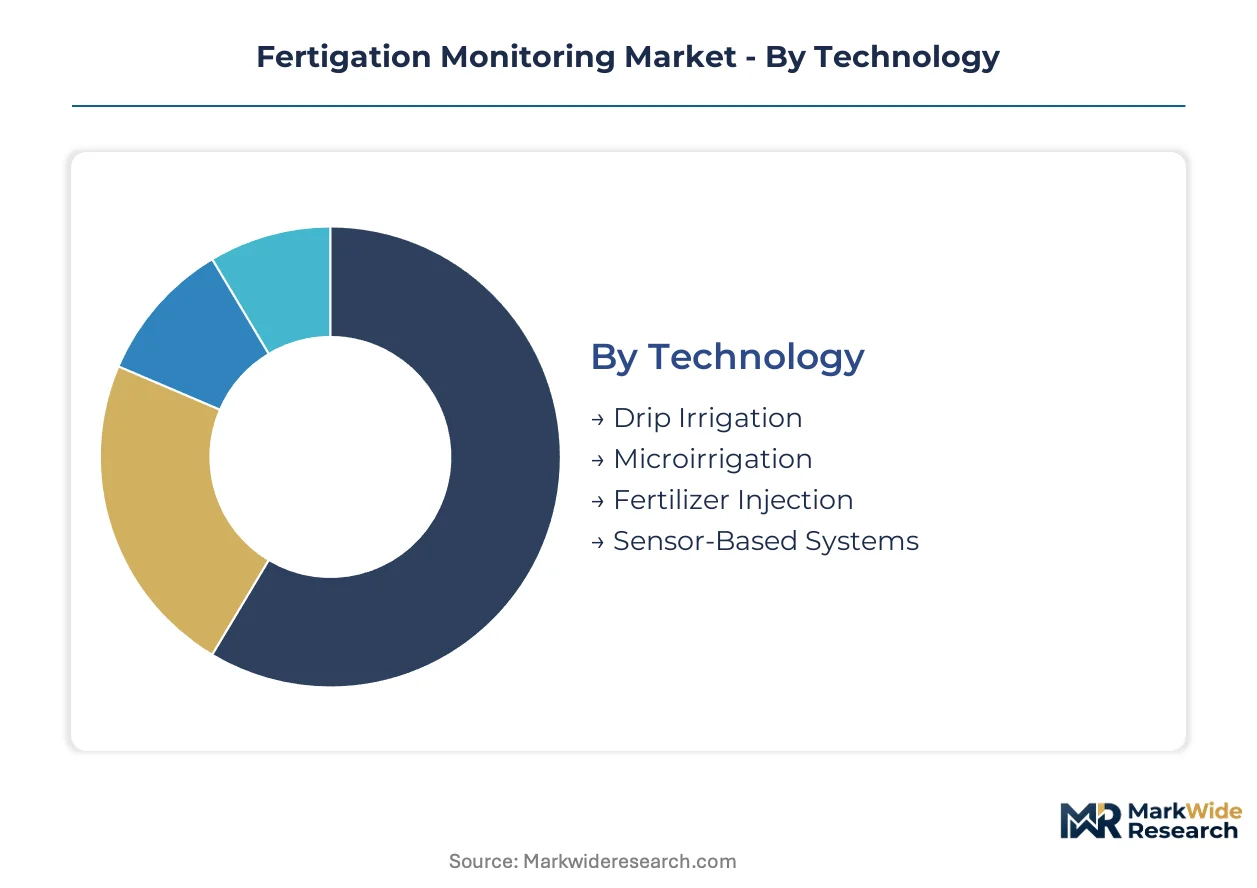
Fertigation monitoring segments reflect divergent capital intensity and precision requirements across cropping systems. Technology choices determine whether growers achieve autonomous nutrient control or remain dependent on manual calibration cycles.
Technology:
Volume deployment favors established irrigation hardware, while premium expansion concentrates in autonomous sensing infrastructure.
- Drip Irrigation:Inline emitter systems enable precise nutrient delivery through laminar flow tubing rated at 1-4 liters per hour. California almond orchards and Spanish greenhouse vegetable operations deploy these systems for established compatibility with soluble fertilizer chemistries.
- Sensor-Based Systems:Electrochemical probes measuring electrical conductivity and pH enable closed-loop adjustment without operator intervention. Netherlands tomato growers and UAE vertical farms prioritize these systems where labor costs exceed sensor capital expense.
- Microirrigation:Micro-sprinkler and bubbler configurations serve tree crops with wider root zones than drip-irrigated row vegetables. South African citrus operations favor microjet systems for frost protection dual-use.
- Fertilizer Injection:Venturi and piston pump injectors meter concentrated stock solutions into mainline flow. These units dominate retrofit installations where existing irrigation infrastructure predates monitoring capability.
Mature deployment sits with Drip Irrigation. Newer deployment is concentrated in Sensor-Based Systems.
Component:
Margin capture shifts upstream from commodity hardware to software-embedded control units.
- Controllers:Edge computing units execute crop-specific algorithms using ARM-based chipsets for localized decision-making. These components command disproportionate value share through embedded software licensing.
- Sensors:Ion-selective electrodes and optical dissolved oxygen probes provide real-time nutrient solution characterization. pH probe drift in high-salinity groundwater zones inflates total ownership cost through weekly calibration labor.
- Pumps:Positive displacement and centrifugal designs handle corrosive fertilizer concentrates at varying viscosity. Stainless steel construction resists acid degradation in continuous-duty greenhouse operations.
- Valves:Solenoid and hydraulic actuators regulate zone-specific nutrient delivery in multi-crop installations. Pressure-compensating variants maintain uniform flow across elevation changes in undulating terrain.
Hardware commoditization pressures Pumps and Valves. Controllers and Sensors concentrate margin expansion.
Application:
Water scarcity premiums and regulatory exposure determine precision investment thresholds across cropping environments.
- Agriculture:Open-field row crops and orchards deploy monitoring to comply with discharge documentation requirements. California's Irrigated Lands Regulatory Program mandates timestamped injection records for enrolled vegetable operations.
- Greenhouses:Controlled environment agriculture achieves closed-loop nutrient recirculation with zero runoff. Dutch glasshouse tomato complexes and Saudi Arabian hydroponic facilities prioritize precision over capital cost.
- Horticulture:Container nursery stock requires precise EC management to prevent root zone salinity damage in limited substrate volumes. Pacific Northwest ornamental producers face seasonal labor constraints favoring automation.
- Landscaping:Turf and amenity plantings employ fertigation for uniform color consistency across large areas. Golf course superintendents command premium pricing for precision nutrient delivery.
Field-scale Agriculture dominates installed base. Greenhouse applications climb fastest on water scarcity premiums.
End User:
Procurement scale and technical capability shape system architecture preferences across buyer types.
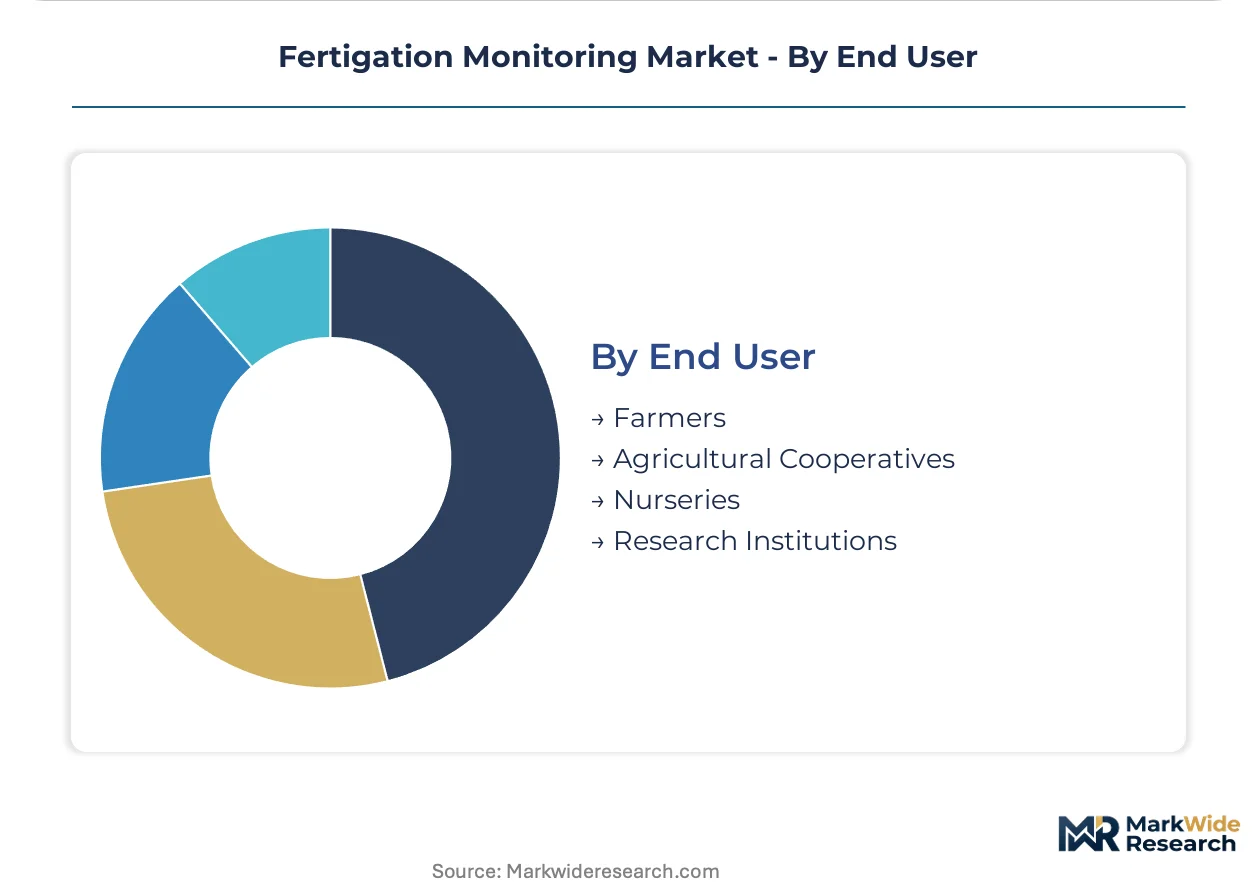
- Farmers:Individual growers select modular systems compatible with existing irrigation infrastructure. Mid-size operations face agronomy-IT skill convergence constraints extending implementation timelines.
- Agricultural Cooperatives:Consolidated procurement by processing tomato and almond cooperatives extracts fleet pricing and training inclusion. Central Valley-based groups negotiate service commitments unavailable to solo buyers.
- Nurseries:Container production specialists prioritize portable monitoring units for seasonal crop rotation flexibility. Labor availability limits viable deployment scale below 50-hectare thresholds.
- Research Institutions:University extension stations and breeding programs demand research-grade calibration and data export capability. These users tolerate higher complexity for experimental reproducibility.
Individual Farmers anchor volume procurement. Cooperative buying is displacing direct sales fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Israel and the United States while consumption clusters in water-stressed agricultural regions across Europe, the Middle East, and North America. Component fabrication and system integration concentrate in established irrigation technology hubs. Demand expansion tracks regulatory pressure on nutrient discharge and water scarcity premiums in intensive cropping zones.
United States
California's Central Valley farming corridor anchors North American demand, where almond orchards and processing tomatoes drive retrofit installations. The EPA enforces Clean Water Act limits on agricultural nutrient discharge through the Irrigated Lands Regulatory Program. Fresno County vegetable operations prioritize timestamped injection records to satisfy State Water Resources Control Board audits.
Netherlands
Glasshouse tomato complexes deploy sensor-based systems where labor costs exceed capital investment thresholds. The EU Green Deal's Farm to Fork strategy mandates 50% pesticide reduction, intensifying precision nutrient management substitution. Westland municipality growers accelerate closed-loop recirculation adoption to maintain yields under tighter residue limits.
Spain
Almería province greenhouse vegetable operations face water scarcity premiums driving precision irrigation investment. National water pricing reforms under the EU Water Framework Directive intensify efficiency mandates. Murcia region citrus and lettuce producers deploy monitoring infrastructure to document compliance with basin-level abstraction limits.
United Arab Emirates
Vertical farms and hydroponic facilities in Dubai and Abu Dhabi import monitoring systems for closed-loop operations where desalination costs dominate economics. The national food security strategy subsidizes precision agriculture technology adoption. Al Ain agricultural zones prioritize autonomous nutrient adjustment capabilities over capital cost considerations.
Australia
Murray-Darling Basin irrigators confront statutory water buyback programs and salinity trading schemes. The Murray-Darling Basin Authority enforces sustainable diversion limits requiring documented water use efficiency. Riverina region rice and cotton operations invest in sensor networks to generate verifiable water savings credentials for allocation trading.
Fertigation Monitoring Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fertigation monitoring value chain. The market structures around three tiers: integrated irrigation system manufacturers, specialized sensor technology developers, and regional component fabricators. Strategic archetypes include heritage irrigation brands bundling monitoring with drip infrastructure, precision agriculture pure-plays selling subscription telemetry, and pump-and-valve manufacturers extending into control systems. Dominant competitive moves encompass backward integration into captive sensor production and geographic expansion through agricultural cooperative channel partnerships.
Within the integrated system tier, Netafim leverages its Israeli irrigation heritage to anchor bundled offerings, while Jain Irrigation Systems occupies a position exemplifying manufacturing conglomerate diversification into precision agriculture. The Toro Company represents brand-strength competition in premium turf and amenity segments where precision nutrient delivery commands pricing power. These three players illustrate distinct archetype strategies without exhaustively mapping competitive positioning across all market participants.
| Leading Market Players |
|---|
| Netafim |
| Jain Irrigation Systems |
| The Toro Company |
| Irritec |
| Novedades Agrícolas |
| Soilmoisture Equipment Corp. |
| LaMotte Company |
| Argus Control Systems |
| Rain Bird Corporation |
| Others |
Supply Flow & Price Mechanics
Copper and lithium commodity swings cascade through controller manufacturing costs into three-tier pricing structures across premium, standard, and economy levels, with Taiwanese semiconductor foundries transmitting foundry pricing power downstream to sensor module assemblers in Israel and California.
Pricing Analysis
Cost-down pressure on mid-tier hardware accelerates because agricultural cooperatives extract fleet pricing concessions that compress system integrator margins. Three-tier pricing structure across premium, standard, and economy levels separates subscription-enabled sensor networks from basic injection controllers from commodity pump-and-valve packages. Price differentiation traces to certification grade—systems with EPA-compliant data logging command 15-25% premiums—and after-sales service bundling. Individual farmers exhibit highest price sensitivity, while UAE vertical farms and Dutch greenhouse operators prioritize precision over capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for ARM-based microcontroller fabrication, while analog-to-digital converter chip supply concentrates in the same geography. Wiring harness copper draws from Chilean and Peruvian mining operations, and lithium for battery-backed controllers sources from Australian and Chilean brine extraction. Tariff exposure on semiconductor imports into the US and EU threatens controller cost structures. Distribution runs through agricultural cooperative procurement offices and irrigation equipment dealers serving California's Central Valley corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive position in fertigation monitoring increasingly rests on backward integration into captive sensor production and control software development, with players racing to own the edge computing layer that commands disproportionate margin capture.
For Market Incumbents: Acquire electrochemical sensor manufacturing capabilities to reduce dependency on Taiwanese semiconductor supply chains. Consolidate position through exclusive data analytics partnerships with California agricultural cooperatives facing State Water Resources Control Board audit exposure. Certification investment in EPA-compliant tamper-evident logging systems defends against emerging pure-play telemetry entrants. For New Entrants and Emerging Players: Agricultural cooperatives in California's Central Valley represent the most penetrable channel archetype, given their consolidated procurement scale and unmet demand for training-inclusive service bundles. Target mid-size vegetable operations in Spain's Almería province where water scarcity premiums override capital constraints. Pursue sensor-as-a-service subscription models that convert capital expenditure to operating budgets for cash-constrained specialty crop growers. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision agriculture pure-plays with established cloud telemetry platforms in the Netherlands and UAE. Long-term viability hinges on nitrogen use efficiency data monetization for Scope 3 carbon accounting integration. Monitor EU Green Deal Farm to Fork implementation velocity as inflection indicator for precision nutrient management substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of pH and EC probes insulates margin from Taiwanese foundry pricing volatility. |
| Subscription Telemetry Service Launch | Recurring revenue models expand addressable base among California almond cooperative members. |
| Carbon Accounting Data Partnership | Nitrogen use efficiency metrics generate verifiable credits for Nestlé and Unilever supply chain claims. |
| Edge Computing Controller Development | ARM-based localized processing eliminates cloud latency for autonomous greenhouse nutrient adjustment. |
| Agricultural Cooperative Channel Exclusive | Fleet pricing negotiations with Central Valley processing tomato groups lock out competitor field access. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with irrigation system engineers, agricultural cooperative procurement managers, greenhouse operations directors, and precision agriculture software developers. EPA enforcement databases, California State Water Resources Control Board Irrigated Lands Regulatory Program enrollment records, EU Green Deal implementation progress reports, and Israeli Irrigation Association export statistics provided validation layers. Bottom-up sensor shipment tallies and top-down agricultural expenditure estimates underwent cross-triangulation.
Segment-level modeling applied technology, component, application, and end-user dimensions at country-specific resolution across the projection horizon. Drip irrigation penetration rates, sensor replacement cycles, and cooperative procurement consolidation velocity fed analytical frameworks. CAGRs derived from fitted growth curves incorporating regulatory mandate timelines and water scarcity premium escalation patterns.
Caveats apply where EU Green Deal implementation delays, Taiwan semiconductor supply disruptions, or California agricultural water allocation cuts could materially shift the outlook. Forecasts reflect documented assumptions about precision agriculture adoption curves and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
Smart Irrigation Controllers Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Global Agrivoltaics Market
Smart Agriculture
Autonomous Farm Vehicle Market