
 Field Effect Transistor Market | 2026-2036
Field Effect Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Field Effect Transistor Market Foresight
The premium RF FET tier is consolidating around gallium nitride-on-silicon-carbide substrates for millimeter-wave base stations, while commodity silicon MOSFETs face margin compression from Chinese foundry oversupply. Infineon Technologies AG leverages its Dresden fab capacity to sustain insulated-gate bipolar transistor and super-junction MOSFET leadership in automotive traction inverters. Taiwan Semiconductor Manufacturing Company Ltd anchors the foundry model for fabless RF designers, while NXP Semiconductors differentiates through AEC-Q100-qualified power FET portfolios for electric vehicle powertrains.
A field effect transistor modulates channel conductivity via an electric field applied to a gate terminal, with modern power devices achieving breakdown voltages above 600V through vertical drift region engineering. Enhancement-mode silicon MOSFETs occupy mature, high-volume slots in consumer switching adapters where margin pools have thinned to single-digit percentages. Gallium nitride high electron mobility transistors lead RF communication applications, particularly in 5G massive MIMO arrays where efficiency above 60% at sub-6GHz frequencies is mandatory. Silicon carbide junction FETs serve industrial automation motor drives, though organic thin-film variants remain confined to low-frequency analog circuits and flexible electronics prototyping.
EPA hazardous substance rules and EU REACH restrictions on hexavalent chromium in electroplating are forcing gate metallization redesigns across US and European supply chains. China's GB standards for wide-bandgap semiconductor reliability testing, administered by MIIT, create market access barriers for imported power modules. ISO 26262 functional safety requirements from Germany's KBA-type approval process now extend to gate driver-FET integration in automotive systems. Stakeholders must monitor how substrate wafer allocation between logic and power FETs shifts foundry pricing dynamics without explicit capacity announcements.
Market Dynamics
Wafer allocation competition between logic and power FETs at leading foundries is compressing lead times for automotive-qualified devices while extending RF component delivery schedules. This substrate scarcity is reshaping procurement patterns across telecommunications and electric vehicle supply chains.
Growth Catalysts
- 5G massive MIMO deployment:Base station power amplifiers require gallium nitride high electron mobility transistors with efficiency above 60% at sub-6GHz frequencies, pulling capacity from foundries serving defense radar programs.
- EU RoHS and REACH substrate qualification:Silicon carbide qualification under these frameworks redirects procurement toward wide-bandgap technologies for industrial motor drives and traction inverters.
- Hsinchu Science Park cluster concentration:Taiwan's foundry ecosystem anchors backend integration for RF and power FETs, reducing packaging costs for fabless designers.
Market Restraints
- Silicon carbide substrate cost volatility:Boule growth yields below 50% for 150mm wafers sustain raw material premiums three to five times above silicon equivalents, constraining mid-voltage power module adoption.
- Chinese foundry oversupply in commodity MOSFETs:Mature-node capacity expansion for 40V-100V planar devices has collapsed spot pricing, eroding margin pools for standard-grade consumer adapters.
- Hexavalent chromium plating restrictions:EPA hazardous substance rules and EU REACH gate metallization redesigns are forcing qualification delays across US and European supply chains.
Strategic Opportunities
- India PLI scheme for semiconductor manufacturing:Incentives for compound semiconductor fabs create white space for gallium nitride-on-silicon RF device production serving domestic telecom infrastructure.
- Gate driver-FET integration for automotive:ISO 26262 functional safety requirements from Germany's KBA-type approval process extend to integrated modules, favoring suppliers with in-house driver design capability.
- Organic thin-film FETs for flexible electronics:Low-frequency analog variants remain confined to prototyping but offer entry points for printed sensor applications in wearable health monitors.
Industry Challenges
- Wide-bandgap reliability certification timelines:China's GB standards administered by MIIT create market access barriers requiring 2,000-hour HTOL testing that extends product introduction cycles for imported power modules.
- Compound semiconductor process engineering scarcity:Gallium nitride HEMT epitaxy and silicon carbide trench etch expertise concentrates at a handful of research institutions, constraining foundry technology transfer.
- Legacy silicon MOSFET inventory obsolescence:Super-junction device generations face premature replacement as 650V silicon carbide MOSFETs achieve price parity in solar inverter applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Effect Transistor Market |
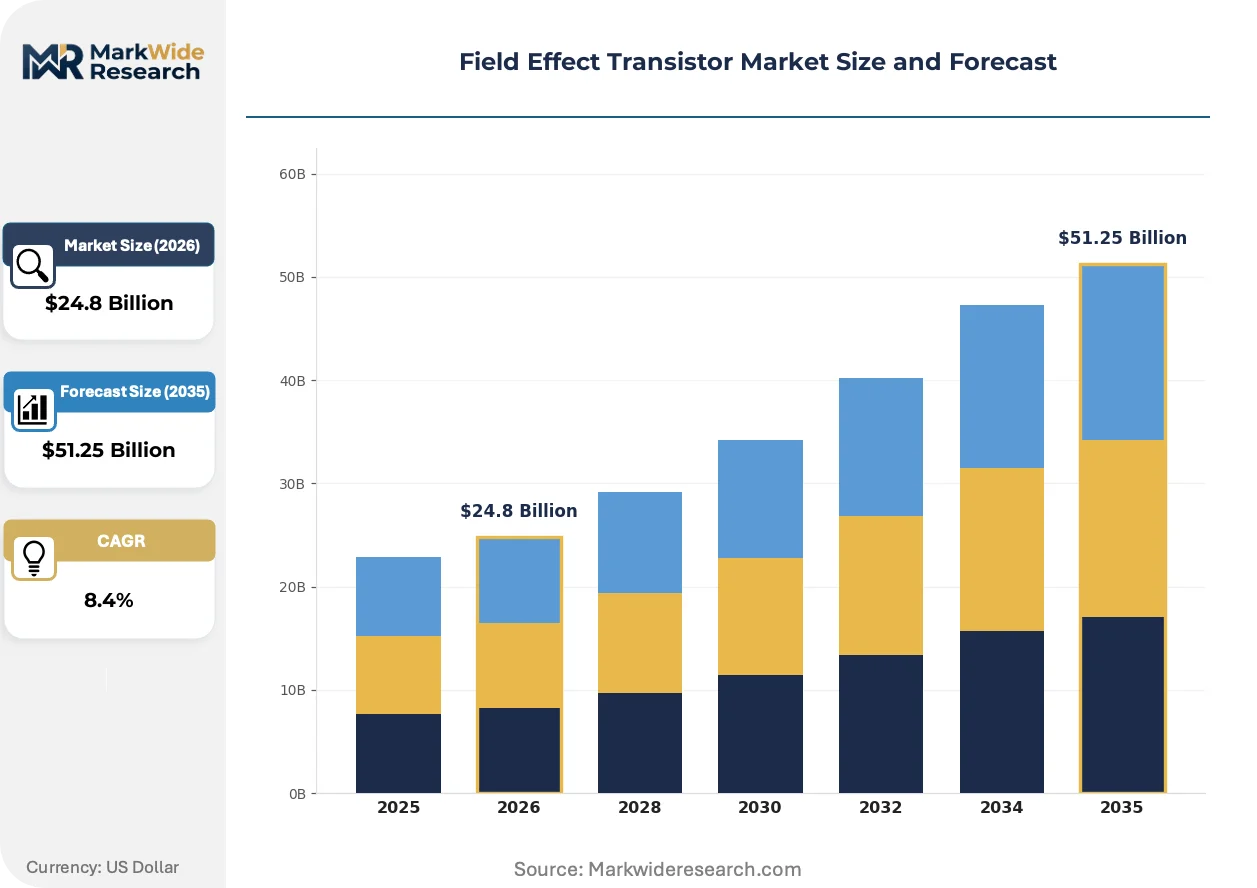
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enhancement Mode, Depletion Mode, High Electron Mobility Transistor, Junction FET Technology: Silicon-Based, Gallium Nitride, Silicon Carbide, Organic Application: Power Amplifiers, RF Communication, Analog Circuits, Switching Devices End User: Consumer Electronics, Automotive, Telecommunications, Industrial Automation |
| Companies Covered | Nexperia, Infineon Technologies AG, Vishay Intertechnology, Inc., Taiwan Semiconductor Manufacturing Company Ltd, STMicroelectronics, NXP Semiconductors, Mitsubishi Electric Corporation, Texas Instruments, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Effect Transistor Market Shifts & Advancements
Process integration between power and RF device architectures is collapsing traditional category boundaries. Foundries now repurpose gallium nitride HEMT platforms for both millimeter-wave communications and high-frequency power conversion, compressing development cycles across previously isolated segments.
Monolithic integration of gate drivers with silicon carbide MOSFETs is unifying protection logic and power switching in single packages. Automotive tier-one suppliers in Germany and Japan are adopting these modules for 800V traction inverters, eliminating external component counts by 30-40%. This unification is compressing bill-of-material costs while accelerating functional safety certification under ISO 26262.
EPA hazardous substance enforcement and EU REACH amendments on electroplating chemicals are forcing gate metallization transitions from chromium-based to nickel-palladium-gold stacks. Power discrete manufacturers in the United States face 12-18 month requalification timelines for AEC-Q101 automotive grades. European industrial FET suppliers are responding with localized plating capacity to circumvent import documentation burdens.
Direct material sourcing from substrate manufacturers is displacing traditional distributor relationships for high-volume automotive programs. Tier-one power module assemblers in Japan and South Korea now negotiate multi-year silicon carbide wafer agreements bypassing semiconductor trading houses. This pattern is most visible in electric vehicle supply chains where 10,000-unit minimum order quantities and traceability documentation requirements exceed distributor service capabilities.
Field Effect Transistor Market Segmentation
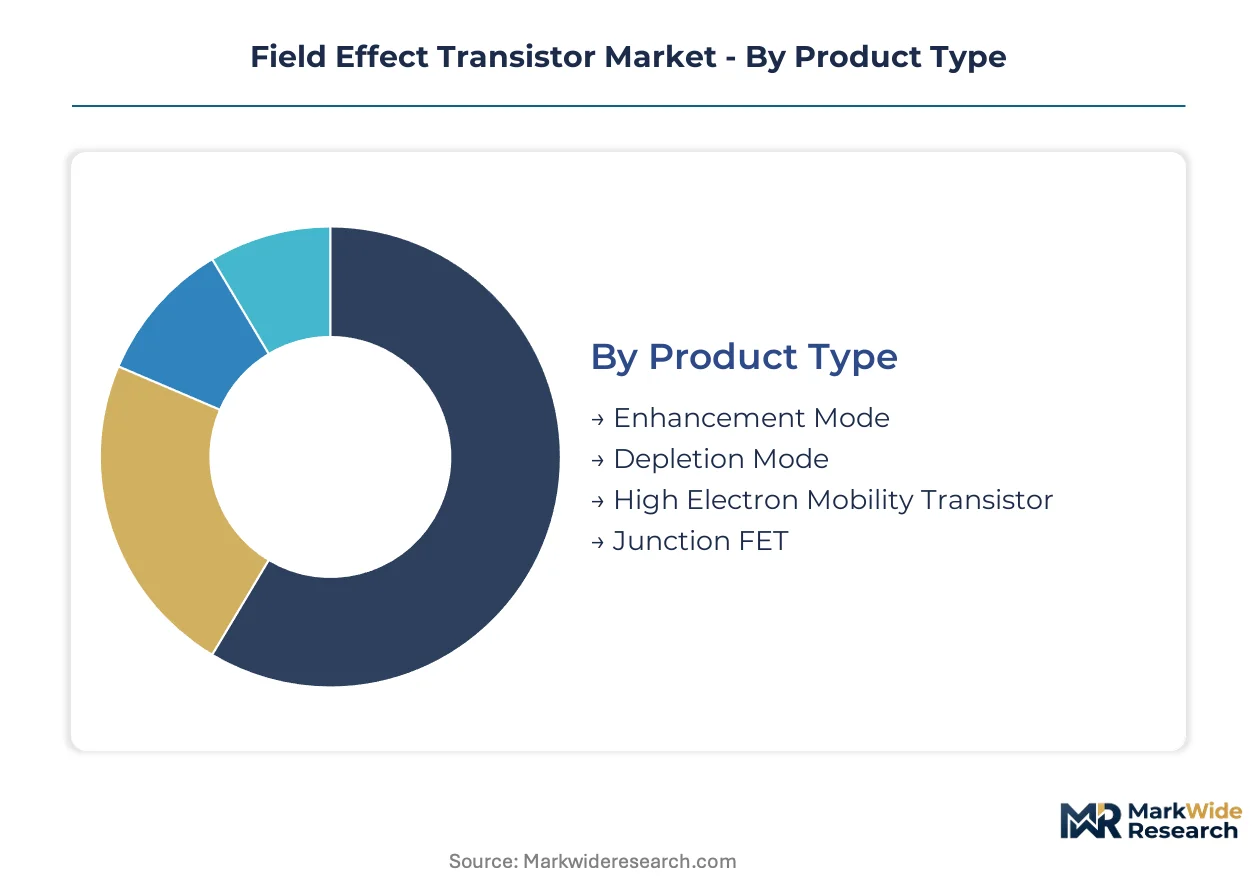
Field effect transistor procurement decisions hinge on voltage rating, switching frequency, and thermal constraints rather than unit cost alone. Device architecture and substrate material together determine suitability for RF power amplification versus motor drive applications.
Product Type:
Engineers select device mode based on fail-safe requirements and gate drive complexity in target circuits.
- Enhancement Mode:These devices require positive gate voltage to establish conducting channels, making them default-off for safety-critical power stages. Automotive traction inverters specify enhancement-mode silicon carbide MOSFETs almost exclusively for their predictable off-state behavior under fault conditions.
- High Electron Mobility Transistor:Gallium nitride HEMTs exploit two-dimensional electron gas mobility exceeding 2,000 cm²/V·s for millimeter-wave amplification. 5G massive MIMO base stations in Taiwan's Hsinchu cluster consume the majority of qualified GaN-on-SiC HEMT foundry output.
- Depletion Mode:Normally-on operation suits current-source biasing in analog front-ends and RF preamplifier stages.
- Junction FET:Voltage-controlled resistive characteristics serve precision analog switches and buffer amplifiers in test equipment.
Volume sits with Enhancement Mode devices; growth tilts toward High Electron Mobility Transistor architectures.
Technology:
Substrate material selection determines breakdown voltage ceiling, thermal conductivity, and ultimately the cost-per-watt of delivered power.
- Silicon-Based:Mature planar and super-junction geometries dominate below 200V applications where silicon cost structures remain unbeatable. Chinese foundry oversupply in 40V-100V planar MOSFETs has collapsed spot pricing for consumer adapter slots.
- Silicon Carbide:Wide bandgap enables vertical drift regions achieving 1,200V breakdown with thinner epitaxial layers than silicon equivalents. EU RoHS and REACH qualification of SiC substrates redirects procurement from legacy insulated-gate bipolar transistors in industrial motor drives.
- Gallium Nitride:Heterostructure devices on silicon or silicon carbide substrates target frequencies above 3GHz where silicon lateral diffusion FETs fail.
- Organic:Solution-processed semiconductor films enable flexible form factors for printed sensor prototypes and disposable health monitors.
Silicon-Based technology retains shipment volume leadership; Gallium Nitride and Silicon Carbide together are climbing the fastest.
Application:
Functional requirements separate high-frequency signal amplification from power switching duties.
- Power Amplifiers:RF output stages in telecommunications infrastructure demand efficiency above 60% at sub-6GHz frequencies to minimize thermal management mass. Gallium nitride HEMTs displace laterally-diffused metal oxide semiconductors in 5G massive MIMO arrays.
- Switching Devices:Hard-switched power conversion for adapters, chargers, and inverters prioritizes low on-resistance and fast reverse recovery. Silicon super-junction MOSFETs face substitution pressure as 650V silicon carbide devices approach price parity in solar string inverters.
- RF Communication:Low-noise amplification and mixing functions in receiver chains.
- Analog Circuits:Precision current sources and voltage followers in instrumentation.
Switching Devices dominate unit shipments; Power Amplifiers show the steepest expansion trajectory.
End User:
Sector-specific qualification regimes create divergent procurement patterns across customer categories.
- Automotive:ISO 26262 functional safety requirements from Germany's KBA-type approval process now extend to gate driver-FET integration. 800V traction inverters specify AEC-Q101-qualified silicon carbide MOSFETs with traceability documentation exceeding distributor capabilities.
- Telecommunications:Base station original equipment manufacturers negotiate direct silicon carbide wafer agreements bypassing semiconductor trading houses. Taiwan's foundry ecosystem anchors backend integration for RF and power FETs serving this sector.
- Industrial Automation:Motor drives and servo controllers favor ruggedized packages with extended temperature ranges.
- Consumer Electronics:Mature-node planar MOSFETs in adapters and chargers face margin compression from Chinese foundry oversupply.
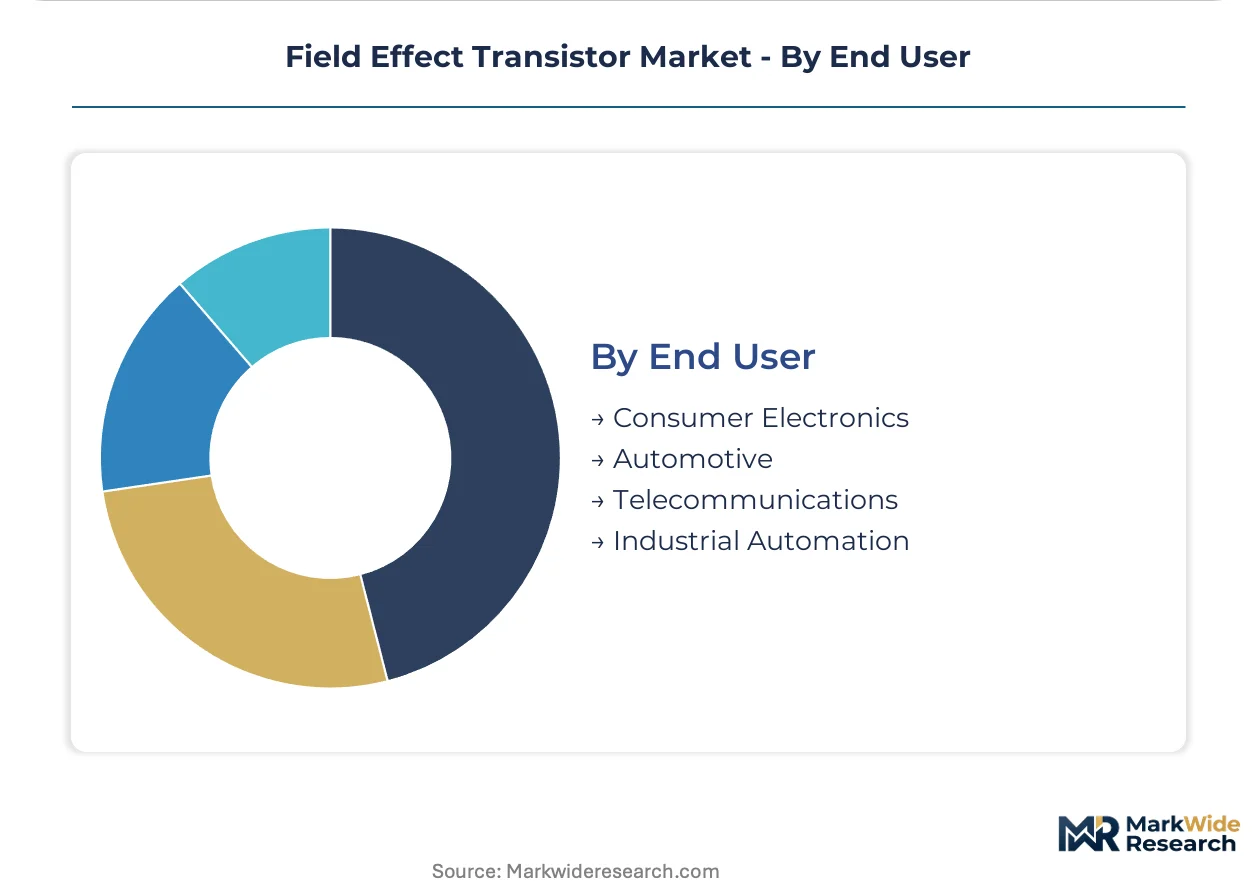
Automotive commands the highest average selling prices; Telecommunications is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan anchors backend integration for RF and power FETs, with foundry ecosystems reducing packaging costs for fabless designers across telecommunications and automotive supply chains.
United States
EPA hazardous substance enforcement drives gate metallization transitions from chromium-based to nickel-palladium-gold stacks at power discrete manufacturers. AEC-Q101 requalification timelines extend 12-18 months for automotive-grade devices. Texas and Arizona host expanding wafer fab capacity serving defense radar and 5G infrastructure programs.
Germany
KBA-type approval processes under ISO 26262 extend functional safety requirements to gate driver-FET integration in 800V traction inverters. Dresden fab capacity sustains insulated-gate bipolar transistor leadership for automotive applications. Bavarian industrial automation clusters drive demand for ruggedized silicon carbide junction FETs in motor drives.
China
MIIT-administered GB standards for wide-bandgap semiconductor reliability create market access barriers requiring 2,000-hour HTOL testing for imported power modules. Mature-node foundry oversupply in 40V-100V planar MOSFETs collapses spot pricing for consumer adapters. Yangtze River Delta concentration of compound semiconductor fabs serves domestic telecom infrastructure buildouts.
Japan
METI industrial policy supports silicon carbide substrate development for traction inverters and solar string converters. Tier-one power module assemblers negotiate multi-year wafer agreements bypassing semiconductor trading houses. Kyushu-based manufacturing clusters specialize in automotive-qualified discrete devices with traceability documentation exceeding distributor capabilities.
South Korea
Seoul Capital Area conglomerates direct material sourcing from substrate manufacturers for high-volume electric vehicle programs with 10,000-unit minimum order quantities. Memory fab equipment repurposing enables gallium nitride HEMT platform development for RF and power conversion applications. Busan-Ulsan industrial corridors anchor backend packaging for export-oriented power modules.
Field Effect Transistor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across substrate material and voltage rating tiers, with wide-bandgap specialists commanding three to five times the raw material premiums of silicon equivalents. The vendor base stratifies between integrated device manufacturers with captive fabs, fabless designers relying on foundry partnerships, and pure-play substrate suppliers controlling boule growth yields. Two dominant competitive moves are reshaping positioning: direct long-term wafer agreements that displace distributor relationships in automotive supply chains, and monolithic integration of gate drivers with power switches that compresses external component counts by 30-40%.
Among European integrated device manufacturers, Infineon Technologies AG and STMicroelectronics exemplify the IDM archetype with in-house Dresden and Crolles fab capacity. Taiwan Semiconductor Manufacturing Company Ltd anchors the foundry-model tier for fabless RF designers requiring gallium nitride-on-silicon-carbide HEMT platforms. These three entities represent distinct strategic postures—European vertical integration against Asian foundry scalability—without overlapping segment focus.
| Leading Market Players |
|---|
| Nexperia |
| Infineon Technologies AG |
| Vishay Intertechnology, Inc. |
| Taiwan Semiconductor Manufacturing Company Ltd |
| STMicroelectronics |
| NXP Semiconductors |
| Mitsubishi Electric Corporation |
| Texas Instruments |
| Toshiba Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between AEC-Q101 automotive-qualified devices and consumer-grade planar MOSFETs splits pricing power and procurement channels. Automotive buyers absorb three to five times the silicon carbide substrate premiums for traceability documentation, while commodity silicon faces spot-price collapse from Chinese foundry oversupply.
Pricing Analysis
Value-based pricing anchors on switching efficiency and thermal performance outcomes rather than unit cost. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade tiers separates AEC-Q101-qualified silicon carbide MOSFETs from standard planar devices. Cost compression in 40V-100V consumer adapters intensifies because Chinese mature-node capacity expansion has flooded spot markets. Automotive OEMs show least price sensitivity due to functional safety requirements; consumer adapter assemblers exhibit highest sensitivity to per-unit swings.
Supply Chain Analysis
Silicon carbide boule supply rests on Japanese and US substrate manufacturers with yields below 50% for 150mm wafers. Raw material dependencies include high-purity silicon carbide source material, gallium nitride epitaxial wafers, and nickel-palladium-gold gate metallization stacks. Single-source vulnerability concentrates in 6-inch silicon carbide substrate supply for automotive traction inverters. Distribution runs through direct long-term wafer agreements that displace semiconductor trading houses in high-volume electric vehicle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The field effect transistor market sits in a substrate-transition phase as silicon carbide MOSFETs displace insulated-gate bipolar transistors in 800V traction inverters and gallium nitride HEMTs replace laterally-diffused metal oxide semiconductors in 5G massive MIMO arrays.
For Market Incumbents: Deploy captive silicon carbide boule capacity to defend automotive margin pools against substrate cost volatility. Secure AEC-Q101 requalification timelines ahead of EPA gate metallization enforcement. Infineon Technologies AG and STMicroelectronics exemplify this posture through Dresden and Crolles fab integration.
For New Entrants and Emerging Players: Enter via India's PLI scheme for compound semiconductor manufacturing to serve domestic telecom infrastructure with gallium nitride-on-silicon RF devices. Target flexible electronics prototyping for organic thin-film FET applications in wearable health monitors. Partner with Taiwan foundry ecosystems for backend packaging cost reduction.
For Investors and Strategic Acquirers: Exit pathways concentrate in wide-bandgap substrate specialists with automotive qualification and in-house epitaxy capability. Long-term viability favors entities controlling silicon carbide trench etch expertise and gallium nitride HEMT platform development. Watch China's GB standards enforcement by MIIT as inflection indicator for imported power module market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Capacity Expansion | Captive boule growth secures supply for automotive traction inverter programs at Infineon and STMicroelectronics. |
| Gate Driver-FET Monolithic Integration | ISO 26262 certification acceleration reduces external component counts by 30-40% in German automotive tier-one supply chains. |
| Long-Term Wafer Supply Agreements | Direct sourcing from Japanese substrate manufacturers bypasses distributor limitations for 10,000-unit electric vehicle minimum orders. |
| Gallium Nitride HEMT Platform Repurposing | Foundries collapse RF and power conversion development cycles through shared Taiwan-based epitaxy infrastructure. |
| Gate Metallization Redesign | Nickel-palladium-gold stack transitions address EPA hazardous substance rules and EU REACH electroplating restrictions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fabless RF designers, automotive tier-one procurement directors, foundry process engineers, and power module assembly managers combined with secondary validation from SEMI industry reports, EPA enforcement disclosures, and EU REACH amendment documentation. Bottom-up wafer shipment aggregation and top-down semiconductor equipment capex analysis provided triangulation across independent data streams.
Data-stream reconciliation across foundry capacity announcements, substrate manufacturer output disclosures, and end-use bill-of-materials penetration rates shaped the analytical framework. Segmentation dimensions modeled include device mode, substrate material, voltage rating, switching frequency tier, and end-use qualification regime. CAGRs derived from substrate allocation trends and technology substitution curves across the projection horizon. Industry-specific inputs incorporated silicon carbide boule yield trajectories and gallium nitride HEMT efficiency benchmarks for 5G massive MIMO deployment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese GB standards enforcement acceleration or silicon carbide substrate yield breakthroughs. Forecasts reflect documented assumptions regarding automotive electrification penetration and telecommunications infrastructure buildout schedules. Substrate allocation competition between logic and power FETs, compound semiconductor process engineering scarcity, and legacy silicon MOSFET inventory obsolescence warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Bipolar Transistors Market
Semiconductor Devices
Japan Power Transistor Market