
 Smart Scales Market | 2026-2036
Smart Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Scales Market Analytics
Market Context
The divergence between premium and commodity tiers in smart scales is hardening around sensor precision, clinical validation, and ecosystem lock-in versus basic weight-tracking functionality. Withings S.A.S. leverages medical-grade certifications and longitudinal health data integration to command pricing power in the clinical-adjacent segment. Xiaomi Corporation anchors the volume tier through aggressive cost engineering and distribution density across Asia, while Garmin Ltd. differentiates by embedding multi-sport recovery metrics into its wearable-integrated scale lineup.
Technical Definition and Segment Structure
Smart scales are electronic weighing devices incorporating bioelectrical impedance analysis (BIA) sensors, load cells with precision to 0.1 kg or finer, and wireless chipsets to transmit body composition metrics to companion software platforms. These instruments serve commercial and consumer markets by transforming isolated weight measurements into longitudinal health datasets for metabolic tracking, athletic programming, and remote patient monitoring. The product type dimension shows smart body composition scales capturing the most favorable margin pools as clinical validation requirements filter out undifferentiated hardware, while the connectivity dimension reveals Bluetooth dominating unit economics due to module standardization and minimal power draw versus Wi-Fi alternatives. End user segmentation indicates fitness centers generating the fastest volume growth as franchise operators standardize member onboarding protocols around connected body composition assessment.
Regulatory Frame and Outlook
The FDA classifies certain smart scales with diagnostic claims as Class II medical devices, while the EU MDR imposes stricter post-market surveillance and clinical evidence standards on manufacturers marketing body fat accuracy. Japan's METI enforces specific measurement precision labeling for consumer health devices, creating a fragmented compliance landscape that favors firms with dedicated regulatory affairs infrastructure. Stakeholders must monitor how national health technology assessment bodies weigh evidence thresholds for reimbursing connected preventive devices, as this determination will reshape which product architectures achieve sustainable unit economics.
Market Dynamics
EU MDR's tightening clinical evidence requirements for body composition accuracy claims are forcing manufacturers to choose between expensive certification upgrades and market exit, hardening the boundary between medical-grade and consumer-grade product tiers.
Growth Catalysts
- Preventive health reimbursement pathways:Germany's statutory health insurers now cover connected body composition monitoring for metabolic syndrome patients, creating institutional demand pull.
- BIA sensor miniaturization:Advances in multi-frequency bioelectrical impedance analysis enable segmental body composition measurement previously requiring clinical-grade equipment.
- Fitness center standardization:Franchise operators deploy connected assessment stations as member retention infrastructure, embedding hardware into recurring revenue models.
Market Restraints
- Load cell supply concentration:Precision strain gauge manufacturing clusters in Japan and Germany, exposing procurement to single-source vulnerability.
- Clinical validation cost inflation:EU MDR's post-market surveillance requirements demand longitudinal studies that commodity producers cannot fund.
- Smartphone substitution threat:Camera-based body composition estimation through computer vision reduces hardware necessity for casual users.
Strategic Opportunities
- Remote patient monitoring integration:Telehealth platforms seek FDA-cleared body composition data streams for chronic disease management programs.
- Corporate wellness mandates:CSRD disclosure requirements push European employers toward quantified employee health metrics.
- Multi-sport recovery convergence:Athletic training facilities combine BIA scales with HRV and sleep data for integrated performance dashboards.
Industry Challenges
- Regulatory affairs talent scarcity:Few hardware firms possess EU MDR technical documentation expertise, slowing certification timelines.
- Legacy platform integration friction:Hospital EHR systems resist API connections with consumer-origin devices, blocking clinical workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Scales Market |
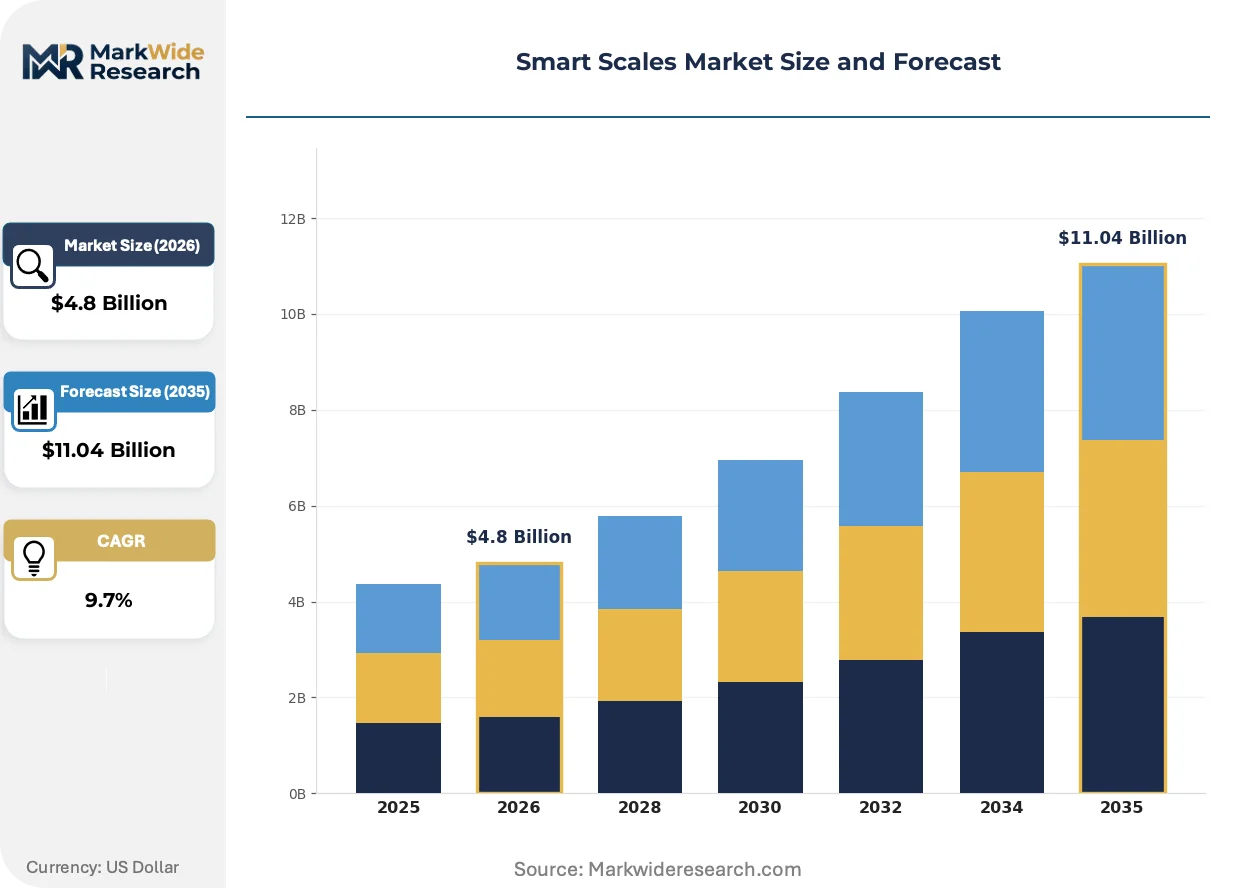
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Scales, Analog Scales, Body Fat Scales, Smart Body Composition Scales End User: Home Users, Fitness Centers, Health Clinics, Professional Trainers Connectivity: Bluetooth, Wi-Fi, USB, NFC Feature: Mobile App Integration, Water Resistance, Multiple User Profiles, Rechargeable Battery |
| Companies Covered | Apple Inc., Samsung Electronics Co Ltd, Xiaomi Corporation, Withings S.A.S., Garmin Ltd., InBody Co. Ltd., Anker Innovations Limited, Fitbit, RENPHO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Scales Market Evolving Landscape
Sensor fusion architectures and algorithmic personalization are compressing the functional gap between clinical laboratory equipment and bathroom-scale form factors, while regulatory fragmentation forces divergent product roadmaps across major markets.
Multi-frequency bioelectrical impedance analysis is unifying segmental body composition measurement into single-platform hardware. Athletic performance centers adopt these systems at accelerating pace for personalized training prescription. The technology is unifying previously separate fat mass, muscle quality, and hydration assessments into one measurement sequence, collapsing the price premium between professional and consumer tiers.
EU MDR's 2021 recast imposes clinical evidence standards on body fat accuracy claims previously treated as consumer marketing. Manufacturers must now submit post-market surveillance data to notified bodies. The regulation most affects Wi-Fi-connected scales with cloud analytics, forcing redesigns of data architecture to satisfy cybersecurity annex requirements.
Subscription revenue models now displace one-time hardware margins as the primary monetization pathway. Fitness chains bundle body composition tracking into membership tiers, while direct-to-consumer brands charge for advanced analytics. Germany exhibits the most pronounced shift, where preventive health reimbursement creates institutional willingness to pay recurring fees for longitudinal data.
Smart Scales Market Segmentation
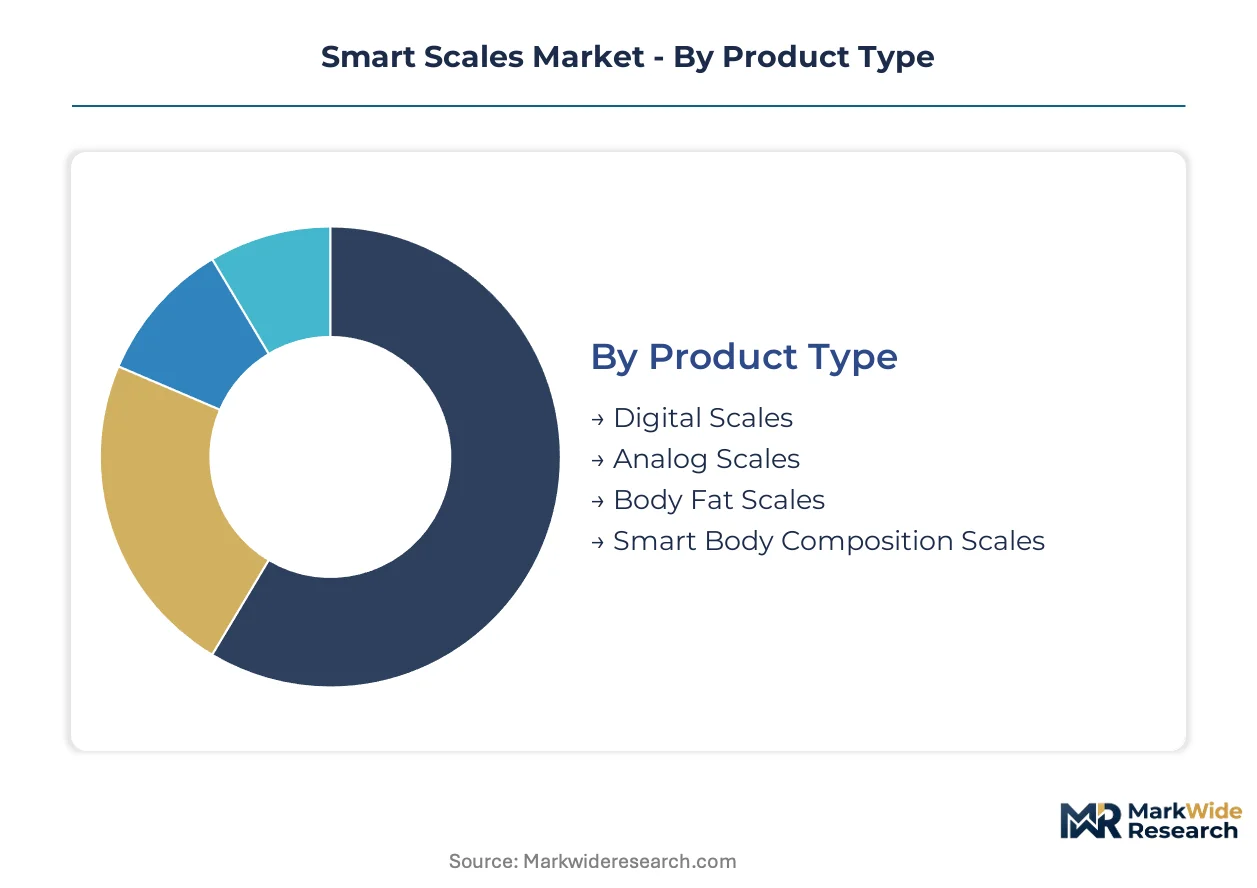
Smart scale segmentation reveals divergent capital requirements across hardware tiers, with clinical-grade validation demanding substantially higher upfront investment than consumer-grade alternatives. Understanding these structural cost differences explains why certain segments consolidate around medical-device specialists while others fragment into electronics commodity competition.
Product Type:
Capital intensity peaks in segments requiring multi-frequency BIA sensors and clinical-grade load cells, where precision manufacturing and regulatory certification consume the largest share of fixed costs.
- Smart Body Composition Scales:Multi-frequency bioelectrical impedance analysis sensors measure segmental fat mass, muscle quality, and hydration status in a single sequence. Demand concentrates in German fitness centers and metabolic syndrome prevention programs reimbursed by statutory health insurers, with EU MDR certification requirements filtering out undercapitalized entrants.
- Body Fat Scales:Single-frequency BIA sensors estimate adipose tissue percentage through foot-to-foot electrical resistance measurement. German wellness infrastructure and corporate wellness mandates under CSRD disclosure requirements drive institutional procurement, though smartphone-based camera estimation erodes casual consumer demand.
- Digital Scales:Load-cell platforms with 0.1 kg precision transmit weight data via standardized wireless chipsets.
- Analog Scales:Spring-based mechanical platforms without connectivity or data storage capabilities.
Most installed capacity flows through Smart Body Composition Scales. Expansion is steepest in Body Fat Scales.
End User:
Volume distribution correlates directly with customer procurement sophistication, from individual price sensitivity to institutional tender processes with multi-year service contracts.
- Fitness Centers:Franchise operators deploy connected assessment stations as member onboarding infrastructure, embedding hardware into recurring revenue models through bundled body composition tracking. Germany's gym chains standardize these protocols fastest, with equipment financing structures that amortize upfront costs across membership tenures.
- Health Clinics:Remote patient monitoring programs seek FDA-cleared data streams for chronic disease management, requiring HIPAA-compliant cloud architecture and EHR integration capabilities that smaller manufacturers cannot fund.
- Home Users:Individual consumers purchase through retail and direct-to-consumer channels with minimal technical support requirements.
- Professional Trainers:Independent coaches acquire portable units for client assessments without institutional procurement backing.
Home Users account for the largest installed base. Fitness Centers are climbing the fastest.
Connectivity:
Module standardization and power consumption characteristics determine which wireless protocols achieve viable unit economics at each price tier.
- Bluetooth:Standardized BLE modules from Nordic Semiconductor and Silicon Labs enable sub-dollar BoM costs with minimal power draw, dominating consumer-grade scales where battery life drives purchase decisions. German retail channels stock almost exclusively Bluetooth-enabled units below premium price thresholds.
- Wi-Fi:Continuous cloud synchronization supports real-time dashboard updates for remote patient monitoring and multi-user fitness center deployments, though EU MDR cybersecurity annex requirements force costly data architecture redesigns that commodity producers abandon.
- USB:Wired connectivity for clinical settings with electromagnetic interference concerns.
- NFC:Tap-to-pair functionality for rapid user profile switching in shared environments.
Bluetooth carries the largest shipment volume. Wi-Fi is gaining share fastest among institutional buyers.
Feature:
Software-enabled differentiation commands recurring revenue premiums that hardware-only competitors cannot match, shifting monetization from one-time sales to subscription economics.
- Mobile App Integration:Companion platforms transform isolated measurements into longitudinal health datasets, with subscription tiers unlocking advanced analytics. German preventive health reimbursement creates institutional willingness to pay recurring fees for metabolic trend monitoring.
- Multiple User Profiles:Automatic recognition algorithms distinguish between household or gym members without manual profile selection, essential for fitness center standardization where frictionless onboarding determines retention rates.
- Water Resistance:IP-rated enclosures enable bathroom installation without humidity damage risk.
- Rechargeable Battery:Lithium-ion cells replace disposable batteries for sustainability-conscious positioning.
Mobile App Integration dominates feature prioritization roadmaps. Multiple User Profiles show the steepest expansion trajectory in commercial deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers specializing in precision load cell manufacturing concentrate in southern Germany and western Japan, anchoring the highest-value supply chains for clinical-grade smart scale components.
Germany
Statutory health insurers reimburse connected body composition monitoring for metabolic syndrome patients, institutionalizing demand for medical-grade devices. The EU MDR's post-market surveillance requirements filter out undercapitalized competitors from reimbursement pathways. Bavaria hosts precision sensor clusters where manufacturers supply validated BIA modules to fitness center chains standardizing member onboarding protocols.
United States
FDA Class II medical device classification for diagnostic-claim scales creates a regulated premium tier distinct from consumer electronics. HIPAA-compliant cloud architecture requirements block smaller manufacturers from hospital EHR integration opportunities. Greater Boston's health technology corridor concentrates firms developing remote patient monitoring data streams for chronic disease management programs.
Japan
METI enforces measurement precision labeling standards that exceed typical consumer electronics requirements, elevating quality baselines. Domestic load cell manufacturing clusters in Nagoya supply strain gauges with single-source vulnerability exposure. Tokyo's corporate wellness mandates under aging workforce policies drive institutional procurement of segmental body composition systems.
China
Aggressive cost engineering enables volume-tier production at price points inaccessible to Western manufacturers. SAMR's consumer device standards focus on electrical safety rather than clinical accuracy, permitting faster product cycles. Shenzhen's electronics ecosystem concentrates Bluetooth module integration and mobile app development for export-oriented brands.
South Korea
Corporate wellness programs at chaebol conglomerates institutionalize quantified employee health metrics. MFDS medical device registration creates compliance barriers for imported clinical-grade scales. Seoul's fitness franchise operators deploy connected assessment stations with financing structures amortizing hardware costs across membership tenures.
Smart Scales Market Competitive Landscape
Top-tier vendors anchor medical-grade certification tiers, while consumer electronics conglomerates dominate volume segments through cost engineering and distribution density. The vendor base stratifies around regulatory affairs capability, with clinical validation expertise separating sustainable competitors from commodity producers. Three archetypes predominate: medical-device specialists leveraging longitudinal health data integration, Asian electronics giants exploiting manufacturing scale, and wearable-integrated platforms converging multi-sport recovery metrics. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms seek to bridge certification gaps or secure load cell supply.
Within the medical-device archetype, Withings S.A.S. exemplifies positioning built upon EU MDR certification and preventive health reimbursement pathways. Xiaomi Corporation anchors the volume-driven tier through Shenzhen-based manufacturing economics and retail channel density. Garmin Ltd. occupies a convergent position representing wearable-integrated scale architectures that embed body composition data within broader athletic performance ecosystems.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co Ltd |
| Xiaomi Corporation |
| Withings S.A.S. |
| Garmin Ltd. |
| InBody Co. Ltd. |
| Anker Innovations Limited |
| Fitbit |
| RENPHO |
| Others |
Value Network & Pricing Analysis
Multi-frequency BIA sensor miniaturization simultaneously collapses manufacturing cost curves and concentrates production expertise in southern Germany and western Japan, creating divergent margin structures between clinical-grade and consumer-grade tiers.
Pricing Analysis
Bundled subscription services now separate from hardware transactions reshape revenue economics across the market. Three-tier pricing structure across premium, standard, and economy levels reflects EU MDR certification grade and longitudinal data integration depth. Price differentiation stems from clinical validation investment and ecosystem lock-in capabilities. Cost compression in the volume tier intensifies because Shenzhen-based manufacturers exploit module standardization. Home users exhibit highest price sensitivity, while German statutory health insurers demonstrate lowest sensitivity due to reimbursement pathways.
Supply Chain Analysis
Freight cost volatility from precision sensor clusters in Germany and Japan to assembly points in China and Vietnam elevates landed cost uncertainty for clinical-grade manufacturers. Load cell manufacturing draws from Nagoya and Bavarian precision engineering hubs, while Bluetooth module production centers on Shenzhen and Taipei. Single-source vulnerability in strain gauge supply exposes procurement to disruption. Distribution runs through fitness center franchise networks and direct-to-consumer e-commerce channels with divergent margin profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart scales market functions as a stable compounder where preventive health reimbursement institutionalization in Germany generates predictable institutional demand pull.
For Market Incumbents: Extend certification portfolios to capture EU MDR-filtered reimbursement pathways before commodity producers recover. Deepen backward integration into precision load cell supply through partnerships with Nagoya manufacturing clusters. Counter smartphone-based camera estimation substitution by embedding irreplaceable clinical-grade accuracy into hardware form factors. For New Entrants and Emerging Players: Begin with corporate wellness procurement under CSRD disclosure requirements, where quantified employee health metrics create institutional willingness to pay. Target South Korean chaebol conglomerates with segmental body composition systems for aging workforce policies. Pursue white-label manufacturing for fitness center chains standardizing member onboarding infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among Wi-Fi-connected scale developers forced into costly EU MDR cybersecurity redesigns. Long-term viability favors firms with dedicated regulatory affairs infrastructure and hospital EHR integration capabilities. Watch FDA 510(k) clearance velocity for remote patient monitoring data streams as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Post-market surveillance compliance unlocks German statutory health insurer reimbursement channels. |
| Multi-frequency BIA Sensor Integration | Segmental body composition measurement collapses price premium between professional and consumer tiers. |
| Hospital EHR System Partnership | HIPAA-compliant API connections enable clinical workflow adoption for chronic disease management programs. |
| Fitness Center Franchise Deployment | Equipment financing structures amortize hardware costs across membership tenures in German gym chains. |
| Preventive Health Reimbursement Strategy | Metabolic syndrome patient coverage creates institutional demand pull for longitudinal monitoring subscriptions. |
Research Methodology
Coverage spans Germany, United States, Japan, China, and South Korea, with primary inputs from each market's regulatory and commercial stakeholders. The analysis combines interviews with biomedical engineers, fitness center procurement directors, regulatory affairs specialists, and health technology assessment bodies with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, METI precision labeling standards, and hospital GPO contract databases. Bottom-up shipment modeling and top-down reimbursement pathway sizing provide cross-check triangulation.
Granularity-level modeling disaggregates volume and value across product type, connectivity protocol, end-user segment, and feature tier throughout the forecast period. The analytical framework derives CAGRs from segment-specific adoption curves weighted by regulatory approval timelines and reimbursement policy trajectories. BIA sensor cost decline trajectories and load cell supply constraints inform hardware margin projections, while subscription attach rate assumptions shape recurring revenue forecasts.
Caveats apply where EU MDR enforcement intensity or FDA diagnostic claim reclassification could materially shift the outlook. Forecasts reflect assumptions about statutory health insurer coverage expansion and fitness center standardization velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
India Fitness Ring Market
Fitness Equipment
Europe E-Commerce Home Fitness Products Market
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
Gym Fitness Accessories Market
Fitness Equipment
Europe Refurbished Fitness Equipment Market
Fitness Equipment
Treadmill Motors Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
Fitness Rings Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
Muscle Oxygen Monitors Market
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Pilates Equipment Market
Fitness Equipment
Elliptical Market
Fitness Equipment
Elliptical Trainers Market