
 Smart Fitness Device Market | 2026-2036
Smart Fitness Device Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fitness Device Market Insights
Subscription revenue from app-integrated coaching and personalized analytics is reshaping margin pools away from one-time hardware sales toward recurring software income. Apple Inc. leverages its HealthKit ecosystem to lock users into continuous data services. Samsung Electronics anchors its position through Galaxy Watch integration with SmartThings home fitness environments. Garmin Ltd. specializes in GPS-enabled performance metrics for outdoor athletes seeking altitude and navigation precision.
Smart fitness devices encompass sensor-embedded electronics that capture biometrics, motion data, and location telemetry for health monitoring and athletic performance optimization. These products incorporate photoplethysmography sensors measuring blood oxygen saturation within ±2% accuracy, accelerometers tracking three-axis movement at 100Hz sampling rates, and Bluetooth Low Energy chipsets enabling sub-10mW power draw during continuous data transmission. Wearables command the largest installed base while ecosystem solutions capture premium pricing through cross-platform synchronization. Fitness trackers face commoditization pressure as basic step-counting saturates entry-level segments. Cloud-connected architectures are displacing standalone storage as users demand seamless mobile-to-desktop data portability.
FDA premarket notification requirements for devices claiming diagnostic functions compel manufacturers to validate algorithm accuracy through clinical trials. EMA medical device regulations in Europe mandate cybersecurity documentation for connected fitness products transmitting personal health data. FCC Part 15 rules govern radio frequency emissions from Bluetooth and Wi-Fi radios embedded in wearable form factors. Stakeholders must monitor evolving classification thresholds that could reclassify consumer fitness trackers as regulated medical devices based on expanded health claims.
Market Dynamics
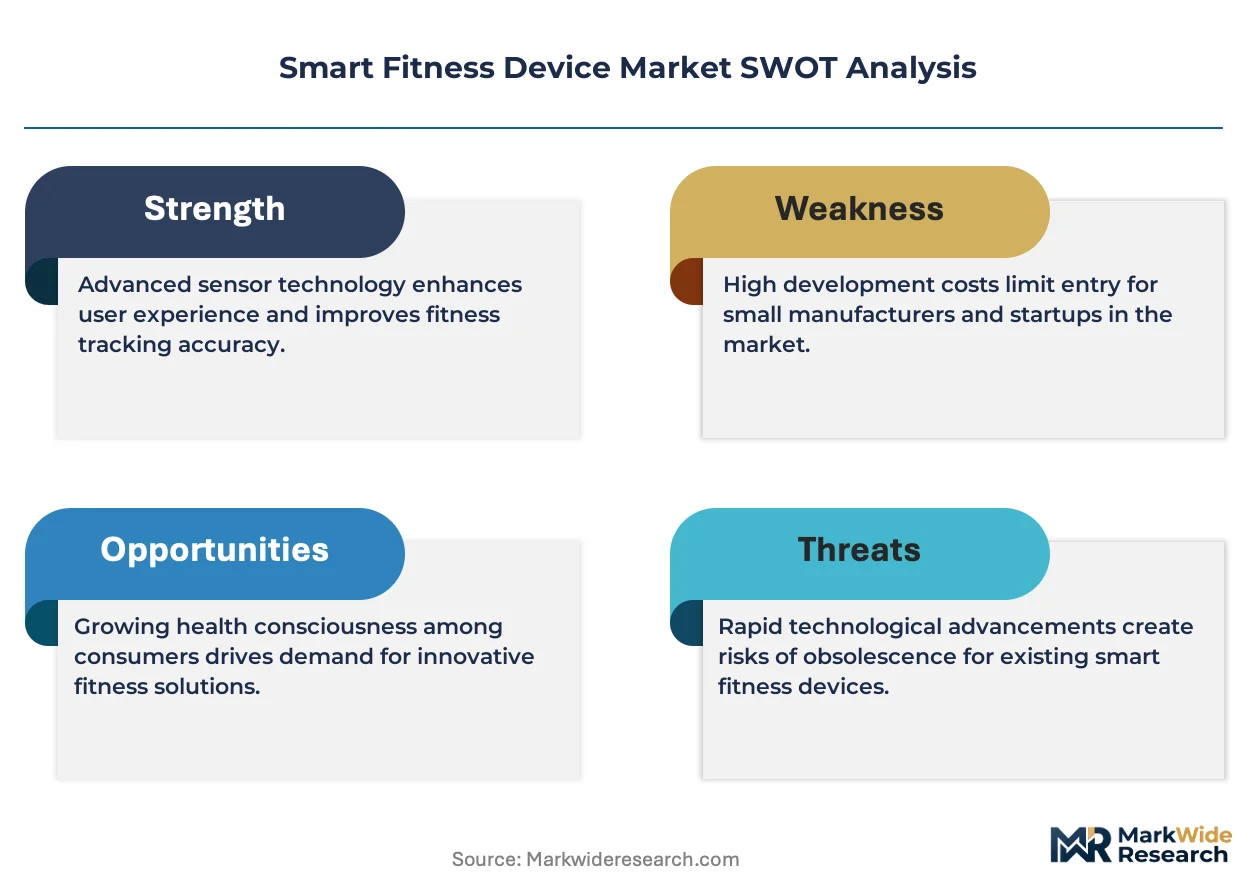
Subscription monetization is rendering obsolete the hardware-centric profit model that once dominated smart fitness devices, forcing manufacturers to architect recurring revenue streams through biometric data services and coaching platforms.
Growth Catalysts
- Corporate wellness procurement:Employers across the United States and Germany are deploying connected wearables for workforce health monitoring, expanding institutional demand beyond consumer retail channels.
- FDA 510(k) clearance pathways:Medical-grade heart rate algorithm validation is accelerating product differentiation and enabling premium positioning for devices claiming diagnostic functions.
- Photoplethysmography advances:Blood oxygen sensors achieving ±2% accuracy are unlocking new clinical applications and expanding reimbursable use cases.
Market Restraints
- MEMS component concentration:Accelerometer and gyroscope supply chains cluster in Taiwan and South Korea, creating single-source vulnerability for motion-sensing hardware.
- Lithium-polymer cost volatility:Battery cell prices fluctuate with cobalt and nickel spot markets, compressing margins on sub-$100 fitness trackers.
- Bluetooth Low Energy bandwidth limits:Sub-10mW power constraints restrict real-time data throughput, forcing trade-offs between sampling frequency and battery life.
Strategic Opportunities
- Rural India penetration:Smartphone-first populations in tier-2 and tier-3 cities present untapped demand for sub-$25 fitness bands with localized language interfaces.
- SmartThings ecosystem convergence:Home fitness environments integrating wearables with connected equipment create sticky multi-device households.
- EU MDR cybersecurity documentation:Early compliance with medical device regulation data protection requirements opens premium positioning in European clinical channels.
Industry Challenges
- Clinical algorithm validation timelines:FDA-mandated trials for SpO2 and arrhythmia detection extend product development cycles by 18-24 months.
- Cloud-to-edge migration complexity:On-device AI inference requires specialized silicon design capabilities scarce among traditional wearable OEMs.
- Interoperability standard fragmentation:Competing health data formats between Apple HealthKit, Google Fit, and Samsung Health complicate third-party developer adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fitness Device Market |
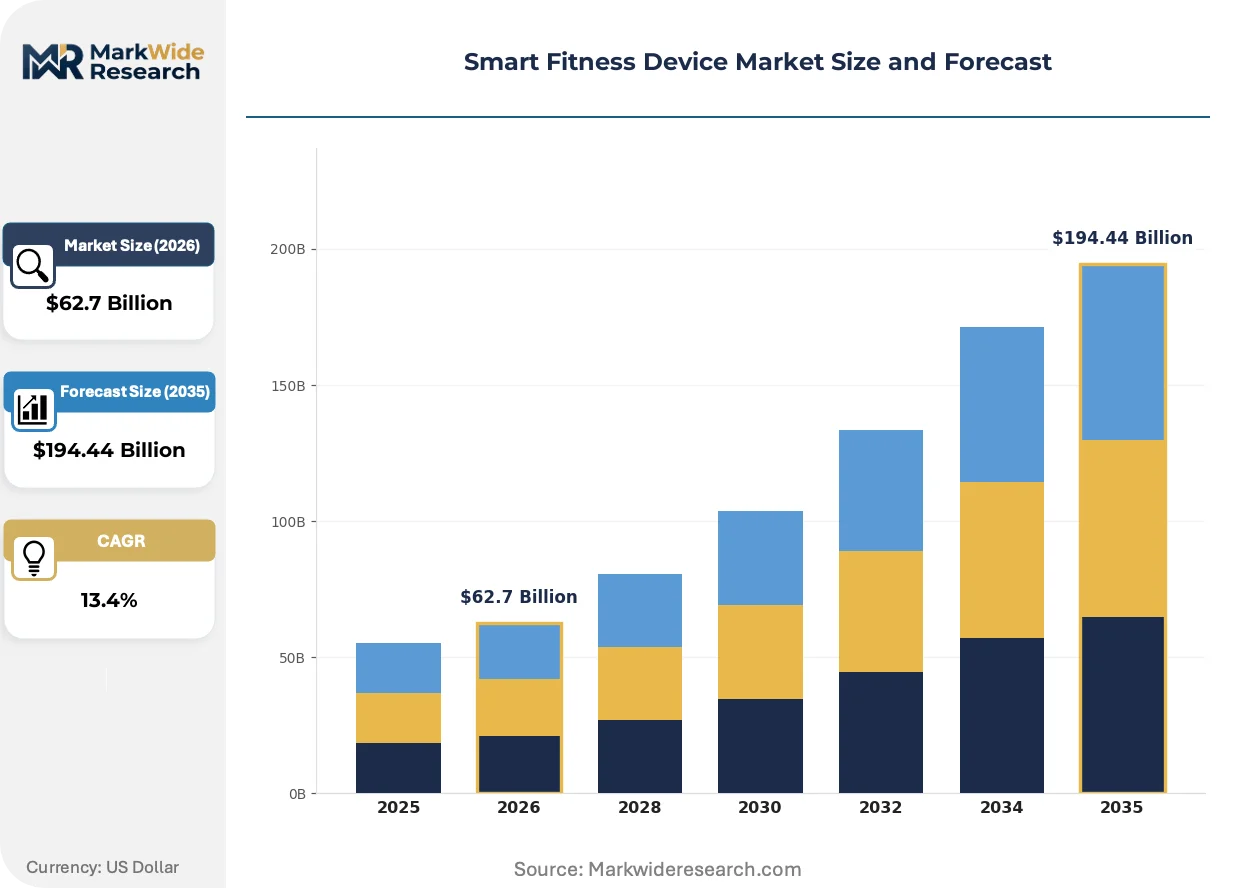
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $194.44 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearables, Smart Gym Equipment, Connected Accessories, Fitness Trackers Technology: Bluetooth, Wi-Fi, NFC, GPS User Segment: Health Enthusiasts, Professional Athletes, Seniors, Beginners Integration Level: Standalone Devices, App-Integrated, Cloud-Connected, Ecosystem Solutions |
| Companies Covered | Apple Inc., Samsung Electronics, Xiaomi Corporation, Huawei Technologies, Garmin Ltd., Fitbit Inc., Fossil Group, Polar Electro, Under Armour Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fitness Device Market Trends and Innovations
Continuous glucose monitoring integration and on-device machine learning are compressing the boundary between consumer wellness and clinical-grade diagnostics, rewriting competitive requirements for sensor fusion and algorithm accuracy.
Multi-spectral photoplethysmography arrays measuring blood pressure without cuff calibration are rendering obsolete single-wavelength heart rate monitors in the premium wearable segment. Cardiology-focused health systems in Singapore and Switzerland are piloting these devices for hypertension management. The technology is compressing addressable market boundaries between consumer electronics and regulated medical devices.
EMA Medical Device Regulation cybersecurity documentation mandates are forcing manufacturers to embed hardware security modules and encrypted telemetry pipelines. European distributors now require ISO 27001 certification for supply chain partnerships. Cardiovascular monitoring features face the strictest documentation burdens, pushing smaller OEMs toward white-label partnerships.
Employer-sponsored wellness programs are consolidating purchasing power through centralized procurement platforms that bypass traditional retail channels. Fortune 500 human resources departments in the United States negotiate direct contracts with manufacturers for annual device refresh cycles. This concentration is visible most acutely in financial services and technology verticals where health insurance premium reductions incentivize participation.
Smart Fitness Device Market Segmentation
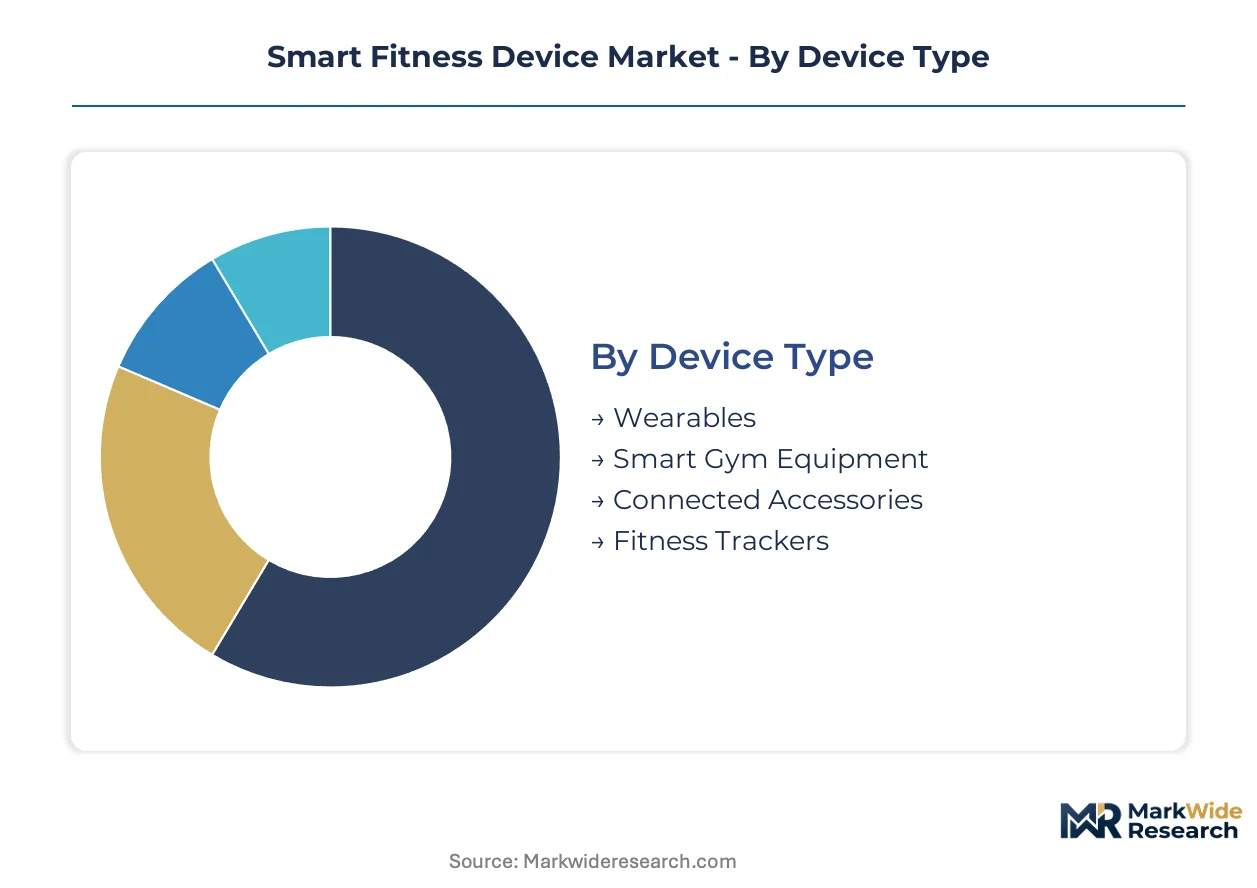
Smart fitness device manufacturers architect product portfolios across multiple segmentation axes to capture divergent willingness-to-pay and technical sophistication levels. Understanding how demand fragments across device types, connectivity standards, and integration architectures determines pricing power and channel strategy.
Device Type:
Cost tier stratification separates premium medical-grade hardware from mass-market entry points, with component precision and algorithm validation driving price positioning.
- Wearables:Wrist-worn and body-worn form factors incorporate photoplethysmography sensors, accelerometers, and Bluetooth Low Energy chipsets for continuous biometric monitoring. Demand concentrates in China where Xiaomi and Huawei dominate domestic distribution through ecosystem retail partnerships, constrained by lithium-polymer cost volatility affecting sub-$100 price bands.
- Smart Gym Equipment:Connected treadmills, stationary bikes, and strength training platforms embed touchscreen displays and real-time performance analytics. Corporate wellness programs across the United States and Germany are expanding procurement for workforce health monitoring, bypassing traditional retail channels through centralized purchasing platforms.
- Connected Accessories:Smart shoes, heart rate chest straps, and sensor-embedded apparel transmit motion data to companion applications.
- Fitness Trackers:Basic step-counting and sleep monitoring devices face commoditization pressure as entry-level segments saturate.
Wearables hold installed capacity. Smart gym equipment is rotating up the share rankings.
Technology:
Connectivity protocol selection trades bandwidth against power consumption, with application requirements dictating radio architecture choices across the product portfolio.
- Bluetooth:Bluetooth Low Energy chipsets enable sub-10mW power draw during continuous data transmission, extending battery life in compact form factors. Health enthusiasts prioritizing seamless smartphone synchronization drive adoption, though bandwidth limits restrict real-time data throughput and force sampling frequency trade-offs.
- Wi-Fi:Higher throughput radios support firmware updates, video streaming, and cloud synchronization for data-intensive applications. Smart gym equipment installations in commercial fitness centers and home environments leverage Wi-Fi for uninterrupted telemetry pipelines, constrained by FCC Part 15 radio frequency emission compliance requirements.
- NFC:Near-field communication enables tap-to-pair setup and contactless payment integration in premium wearable tiers.
- GPS:Satellite positioning supports outdoor activity tracking with altitude and navigation precision for specialized athletic use cases.
Bluetooth dominates shipment volumes. Wi-Fi is climbing the fastest in revenue contribution.
User Segment:
Customer type determines feature prioritization, with clinical validation requirements and interface complexity varying sharply across demographic and athletic sophistication levels.
- Health Enthusiasts:Consumers seeking comprehensive wellness metrics including heart rate variability, blood oxygen saturation, and sleep stage analysis. Demand clusters in employer-sponsored wellness programs where Fortune 500 human resources departments negotiate direct manufacturer contracts for annual device refresh cycles.
- Professional Athletes:Elite competitors require GPS-enabled performance metrics with altitude precision and training load analytics. Garmin Ltd. anchors this segment through specialized outdoor athletic positioning, with Singapore and Switzerland cardiology health systems piloting multi-spectral photoplethysmography for hypertension management.
- Seniors:Simplified interfaces and fall detection algorithms address aging population health monitoring needs.
- Beginners:Price-sensitive entry-level users drive volume in emerging markets including rural India tier-2 and tier-3 cities.
Health enthusiasts command margin pools. Professional athletes are expanding fastest in premium tier attachment.
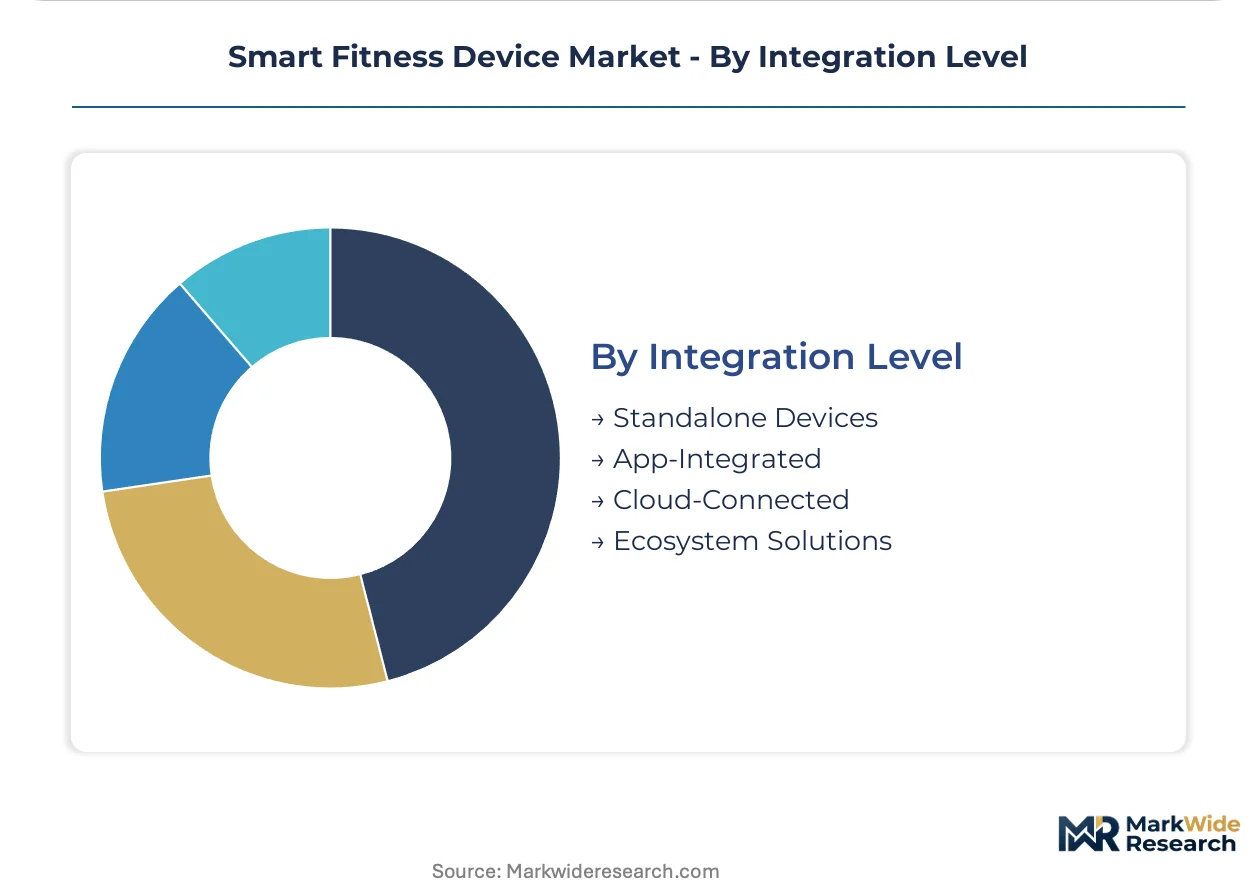
Integration Level:
Maturity of data architecture separates isolated hardware from sticky ecosystem participation, with recurring revenue potential scaling directly with platform connectivity depth.
- Standalone Devices:On-device storage and limited connectivity restrict data portability and long-term user engagement. Basic fitness trackers in entry-level segments increasingly lose share as cloud-connected architectures displace standalone storage.
- App-Integrated:Companion smartphone applications enable data visualization, goal setting, and social features. Subscription revenue from personalized analytics and coaching platforms is reshaping margin pools away from one-time hardware sales toward recurring software income.
- Cloud-Connected:Seamless mobile-to-desktop data portability supports longitudinal health tracking and third-party service integration.
- Ecosystem Solutions:Cross-platform synchronization with smart home environments, health systems, and insurance platforms captures premium pricing through multi-device household stickiness.
Ecosystem solutions defend pricing power. Cloud-connected architectures are gaining share fastest across mid-tier and premium bands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with corporate wellness procurement dominating United States and Germany while ecosystem retail partnerships drive volume in China, and medical-grade validation opens premium channels in Switzerland and Singapore.
United States
Employer-sponsored wellness programs at Fortune 500 technology and financial services firms negotiate direct manufacturer contracts for annual device refresh cycles, bypassing traditional retail channels entirely. FDA 510(k) clearance pathways for medical-grade heart rate algorithms accelerate product differentiation among devices claiming diagnostic functions. Greater Boston and San Francisco Bay Area clusters concentrate health-tech venture capital and clinical trial infrastructure for algorithm validation.
China
Xiaomi and Huawei dominate domestic distribution through ecosystem retail partnerships, capturing smartphone-first populations with localized interface designs. MIIT cybersecurity standards and GB certification requirements shape hardware security module integration for connected wearables. Shenzhen and Dongguan manufacturing corridors anchor global production capacity for photoplethysmography sensors and Bluetooth Low Energy chipsets.
Germany
Corporate wellness procurement expands across automotive and industrial manufacturing sectors, with employers deploying connected wearables for workforce health monitoring and insurance premium reduction programs. EMA Medical Device Regulation cybersecurity documentation mandates force hardware security module embedding and encrypted telemetry pipeline architecture. Bavaria and Baden-Württemberg industrial clusters concentrate precision sensor fabrication and clinical validation partnerships.
Switzerland
Cardiology-focused health systems in Zurich and Geneva pilot multi-spectral photoplethysmography arrays for cuffless blood pressure monitoring and hypertension management applications. Swissmedic medical device regulations enforce stringent clinical algorithm validation timelines for devices claiming diagnostic functions. Basel and Lausanne biotech corridors attract wearable OEMs seeking proximity to pharmaceutical clinical trial infrastructure.
Singapore
Healthcare system pilot programs for cardiovascular monitoring integrate premium wearables into national chronic disease management frameworks. Personal data protection commission guidelines and cybersecurity certification requirements shape cloud-connected architecture design for regional market entry. One-North and Biopolis research clusters concentrate med-tech regulatory expertise and clinical validation partnerships for Asia-Pacific market access.
Smart Fitness Device Market Competitive Landscape
Capability concentration sits with specialized health-tech firms possessing clinical validation expertise; scale advantage sits with consumer electronics conglomerates commanding ecosystem retail distribution and semiconductor supply chain leverage. The market structures around three tiers: premium medical-grade device specialists, mass-market ecosystem integrators, and white-label component suppliers serving smaller OEMs. Dominant competitive moves include strategic partnerships for algorithm licensing and backward integration into sensor fabrication to secure supply chain control.
Within the ecosystem integrator tier, Apple Inc. and Samsung Electronics exemplify platform-centric positioning through HealthKit and SmartThings integration architectures. Garmin Ltd. occupies a specialized position among GPS-enabled performance metric providers for outdoor athletic applications. These three companies represent divergent strategic archetypes: closed-platform data lock-in, open home-environment convergence, and precision navigation specialization respectively.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Xiaomi Corporation |
| Huawei Technologies |
| Garmin Ltd. |
| Fitbit Inc. |
| Fossil Group |
| Polar Electro |
| Under Armour Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in photoplethysmography sensor fabrication across Taiwan and South Korea is forcing wearable OEMs into multi-year component commitments, compressing negotiating leverage and locking premium-tier pricing even as entry-level bands face lithium-polymer cost volatility.
Pricing Analysis
Long-term offtake contracts dominate component procurement for medical-grade wearables seeking FDA 510(k) clearance, while spot-market purchasing persists for mass-market fitness bands. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated devices with clinical algorithm documentation from basic step-counting hardware. Pricing pressure stems from cobalt and nickel spot market swings affecting lithium-polymer cell costs in sub-$100 trackers. Corporate wellness buyers show lowest price sensitivity due to insurance premium reduction incentives, while rural India tier-2 and tier-3 city consumers drive volume at extreme economy tiers.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for wearable OEMs dependent on Shenzhen and Dongguan manufacturing corridors. Photoplethysmography sensors, Bluetooth Low Energy chipsets, and lithium-polymer battery cells draw from concentrated Taiwan, South Korea, and China production. Single-source vulnerability in MEMS accelerometer supply creates exposure for motion-sensing hardware. Distribution runs through ecosystem retail partnerships in China and centralized corporate procurement platforms in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart fitness devices sit in early-cycle expansion as continuous glucose monitoring integration and on-device machine learning compress the boundary between consumer wellness and clinical-grade diagnostics, opening reimbursable use cases previously reserved for regulated medical devices.
For Market Incumbents: Pre-empt algorithm commoditization by accelerating FDA 510(k) submissions for blood pressure and arrhythmia detection features before multi-spectral photoplethysmography arrays achieve widespread clinical validation. Secure backward integration into photoplethysmography sensor fabrication to reduce Taiwan and South Korea supply concentration exposure. Channel control through employer-sponsored wellness program direct contracts defends margin pools against retail price erosion.
For New Entrants and Emerging Players: Mid-tier health enthusiasts in employer-sponsored wellness programs represent the most penetrable entry point, bypassing saturated retail channels through benefits administration platform partnerships. Rural India tier-2 and tier-3 cities offer white-space volume for sub-$25 fitness bands with localized language interfaces. A software-first go-to-market angle emphasizing subscription coaching and personalized analytics enables recurring revenue capture without competing on hardware scale.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ecosystem integrators with HealthKit or SmartThings platform lock-in, positioning them for premium multiples over standalone hardware vendors. Acquisition targets should demonstrate clinical algorithm validation capabilities and European MDR cybersecurity documentation readiness. Watch FDA classification threshold shifts that could reclassify consumer fitness trackers as regulated medical devices as the primary inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Medical-grade heart rate algorithm validation accelerates premium positioning against commodity fitness bands. |
| Backward Integration into Sensor Fabrication | In-house photoplethysmography production reduces Taiwan supply concentration and secures component availability. |
| Corporate Wellness Direct Contracting | Fortune 500 HR department partnerships bypass retail margin compression and enable annual refresh cycles. |
| EU MDR Cybersecurity Compliance | Hardware security module embedding opens premium European clinical channels requiring ISO 27001 certification. |
| On-Device AI Inference Development | Specialized silicon design capabilities enable cloud-to-edge migration and reduce Bluetooth bandwidth constraints. |
Research Methodology
A standing panel of wearable OEM product managers, FDA regulatory affairs consultants, corporate wellness procurement directors, and health system biomedical engineers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA medical device registration databases, SEC 10-K disclosures, and MIIT cybersecurity certification records. Bottom-up shipment modeling and top-down revenue triangulation anchored market size estimates.
Scenario-bracketing around FDA classification threshold evolution, lithium-polymer cost trajectories, and corporate wellness program adoption curves bounded projection uncertainty across the analysis window. Segmentation modeling incorporated device type, connectivity protocol, user sophistication tier, and integration architecture depth. CAGRs derived from fitted growth curves applied to validated base-year estimates, with algorithm validation timeline assumptions and ecosystem partnership penetration rates as key variable inputs.
Stress conditions across FDA regulatory delay scenarios, Taiwan semiconductor supply disruptions, and cobalt price spike events were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory reclassification, cybersecurity mandate expansion, or clinical algorithm accuracy breakthroughs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
France Sports Teams and Clubs Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
Padel Court Operator Market