
 North America Sports Team and Clubs Market | 2026-2036
North America Sports Team and Clubs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sports Team and Clubs Market Insights
Revenue-based financing and stadium lease-back structures are reshaping competitive entry barriers for prospective franchise owners and expansion clubs. The Dallas Cowboys leverages its vertically integrated merchandising and real estate holdings to sustain margin capture beyond game-day operations. The Golden State Warriors anchors its position through technology leadership in venue experience platforms and private seating ecosystems. The Toronto Maple Leafs competes by controlling premium inventory allocation across hockey's most season-ticket-dependent market.
North America sports teams and clubs constitute organized athletic enterprises operating across professional, amateur, and collegiate tiers, generating commercial value through live event production, media rights monetization, and brand licensing with facilities typically exceeding 18,000-seat capacities for major franchises. Ticket sales and broadcasting rights represent the dominant revenue streams, with sponsorship portfolios expanding fastest as brands seek direct fan engagement outside traditional advertising channels. Merchandise operations remain mature with margin pools concentrating in direct-to-consumer digital channels rather than third-party retail, while professional teams command disproportionate valuation multiples relative to amateur clubs due to media contract guarantees.
The NFL's stadium security compliance framework, the NBA's collective bargaining agreement standards, and Canada's Competition Act provisions on ticket resale transparency collectively shape operational cost structures and fan access policies across the region. These regulatory layers influence everything from concession procurement to digital streaming rights distribution, creating differentiated compliance burdens between US and Canadian operations. Stakeholders must monitor evolving state-level sports betting legislation and its integration into stadium revenue architectures as jurisdictions continue to authorize in-venue wagering platforms.
Market Dynamics
Corporate hospitality buyers are consolidating premium seating commitments across NFL and NBA franchises, compressing inventory allocation timelines and forcing venue operators to restructure lease-back financing instruments.
Growth Catalysts
- SAFETY Act compliance mandates:The NFL's enhanced stadium security framework is accelerating capital deployment into integrated surveillance and access control systems across US venues.
- Texas metropolitan cluster density:Franchise valuations and media market concentration in Dallas-Fort Worth and Houston are pulling expansion capital toward Sun Belt infrastructure.
- In-venue wagering platforms:State-level sports betting authorization is creating new revenue architectures for stadium operators with integrated mobile wagering partnerships.
Market Restraints
- Construction input cost volatility:Steel and concrete price fluctuations are extending stadium development timelines and squeezing fixed-price contractor margins.
- Canadian Competition Act friction:Ticket resale transparency provisions are constraining dynamic pricing algorithms and secondary market revenue capture for Toronto-based franchises.
- Collective bargaining agreement rigidity:NBA salary cap mechanics are limiting roster flexibility for mid-market clubs seeking competitive parity.
Strategic Opportunities
- California media market underpenetration:San Diego and Sacramento present expansion-ready demographics with underserved professional franchise presence.
- Real estate lease-back innovation:Revenue-based financing structures are lowering entry barriers for prospective franchise ownership groups.
- Technology convergence in venue experience:Integration of mobile ordering, biometric entry, and personalized content delivery is opening premium pricing tiers.
Industry Challenges
- Specialized stadium operations talent scarcity:Venue management professionals with integrated security, hospitality, and technology platform expertise command premium compensation.
- Legacy concession system integration:Retrofitting cashless payment and dynamic inventory management into existing food service infrastructure creates operational friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sports Team and Clubs Market |
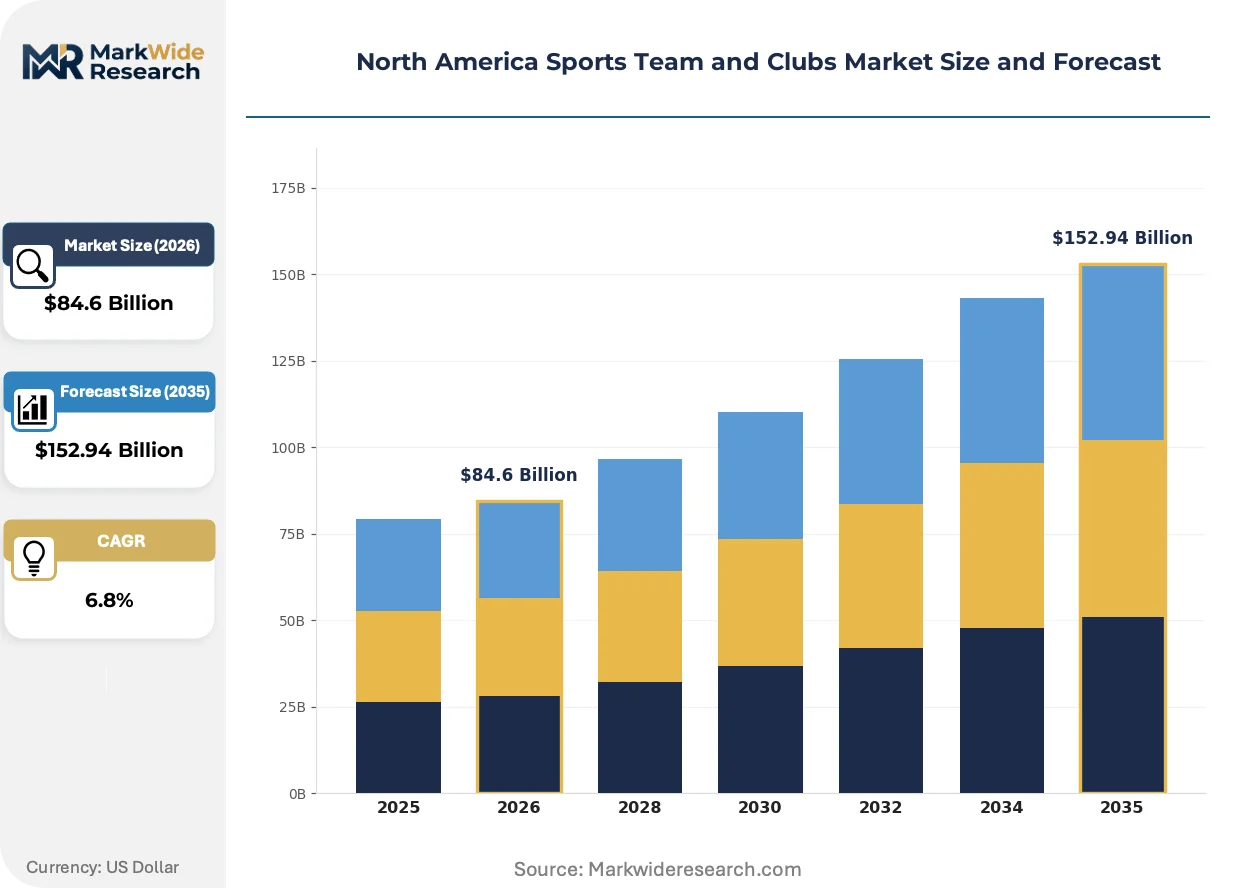
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Organization Type: Professional Teams, Amateur Clubs, College Teams, Recreational Leagues Revenue Stream: Ticket Sales, Sponsorship, Merchandise, Broadcasting Rights Membership Model: Paid Membership, Free Membership, Family Plans, Student Discounts Sport: Football, Basketball, Baseball, Hockey |
| Companies Covered | Dallas Cowboys, Golden State Warriors, Los Angeles Rams, New York Yankees, Los Angeles Lakers, New England Patriots, New York Knicks, Toronto Maple Leafs, Chicago Cubs, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sports Team and Clubs Market Trends and Innovations
Digital infrastructure is compressing the distance between franchise operations and fan touchpoints, enabling real-time inventory monetization and personalized engagement architectures that reshape revenue capture models.
Biometric authentication technology is digitizing venue access and payment workflows. NBA and NFL franchises are deploying facial recognition and palm-vein scanning at scale across premium entry gates and concession points. This convergence is digitizing the entire match-day transaction layer, eliminating physical ticket and payment friction while capturing granular behavioral data for targeted hospitality offers.
The NBA's collective bargaining agreement standards and Canada's Competition Act ticket resale provisions are restructuring revenue distribution mechanics. These frameworks are mandating transparent pricing disclosures and limiting secondary market arbitrage. Canadian operations are responding with direct-to-fan membership models that bypass traditional ticketing intermediaries.
Fan consumption patterns are fragmenting across streaming and in-venue experiences. Younger demographics are prioritizing social media-integrated moments over full-game attendance, forcing franchises to unbundle ticket products into quarter-based or event-specific packages. This shift is most visible in California and Texas markets where franchise apps now dominate initial purchase decisions.
North America Sports Team and Clubs Market Segmentation
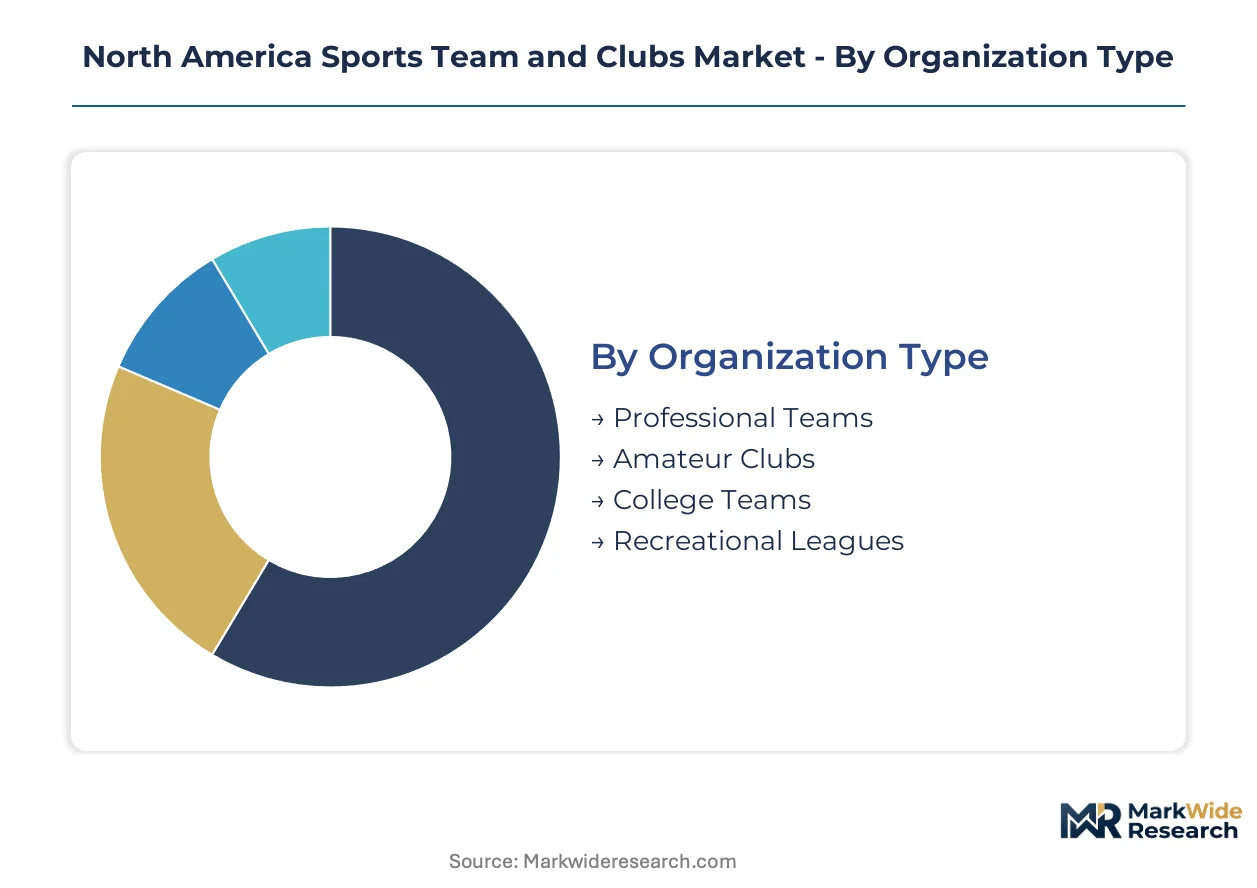
Segmentation in North American sports franchises reveals how capital cycles, fan loyalty patterns, and media monetization architectures differ across organizational tiers. These structural divisions determine which revenue models scale and which remain geographically captive.
Organization Type:
Professional teams turn capital fastest through media rights and franchise sales, while recreational leagues operate on decade-long facility lease cycles.
- Professional Teams:These entities operate under league charter agreements with centralized revenue sharing and salary cap mechanics. NFL and NBA franchises in Texas and California metropolitan clusters command premium valuations due to media market density and corporate hospitality demand.
- Amateur Clubs:Semi-professional operations dependent on regional sponsorship and volunteer labor structures. These organizations in the US Sun Belt face escalating insurance and facility compliance costs under OSHA and state athletic commission frameworks.
- College Teams:Athletic departments integrated within NCAA governance structures, generating revenue through conference media deals and donor endowments. Name-image-likeness compensation rules have restructured athlete recruitment economics.
- Recreational Leagues:Community-based participation models operating on municipal facility contracts and seasonal registration fees. These leagues in Canadian markets navigate municipal subsidy fluctuations and youth participation rate volatility.
Professional teams dominate installed base valuation. Recreational leagues are where participation volume expansion concentrates.
Revenue Stream:
Cost tier segmentation separates capital-intensive infrastructure plays from low-fixed-cost digital monetization.
- Ticket Sales:Primary match-day revenue requiring venue capacity optimization and dynamic pricing algorithms. Canadian franchises face pricing constraints under Competition Act transparency mandates.
- Sponsorship:Brand partnership revenue integrating stadium naming rights, jersey patches, and digital inventory. Corporate hospitality buyers in NFL markets are consolidating multi-year premium commitments.
- Merchandise:Apparel and licensed product sales through direct-to-consumer digital channels and stadium retail. Margin pools concentrate in vertically controlled e-commerce rather than third-party retail distribution.
- Broadcasting Rights:League-level media contracts and franchise-controlled local sports network arrangements. These agreements provide the revenue floor that supports franchise debt financing.
Broadcasting rights anchor balance sheet stability. Sponsorship is where margin expansion concentrates.
Membership Model:
Customer type segmentation determines acquisition cost structures and lifetime value capture mechanics.
- Paid Membership:Annual or multi-year commitments with priority access and exclusive content. NBA franchises deploy these for season-ticket base retention in markets with entertainment competition.
- Free Membership:Registration-based fan engagement for digital content and promotional access. These models build data assets for targeted hospitality upselling.
- Family Plans:Bundled pricing for household participation across multiple events or youth programs. These structures dominate minor league baseball and recreational league economics.
- Student Discounts:Price-tiered access for educational institution affiliates. College athletic departments leverage these to build future donor pipelines and stadium atmosphere.
Paid membership dominates revenue per capita. Free membership is where database scale expansion concentrates.
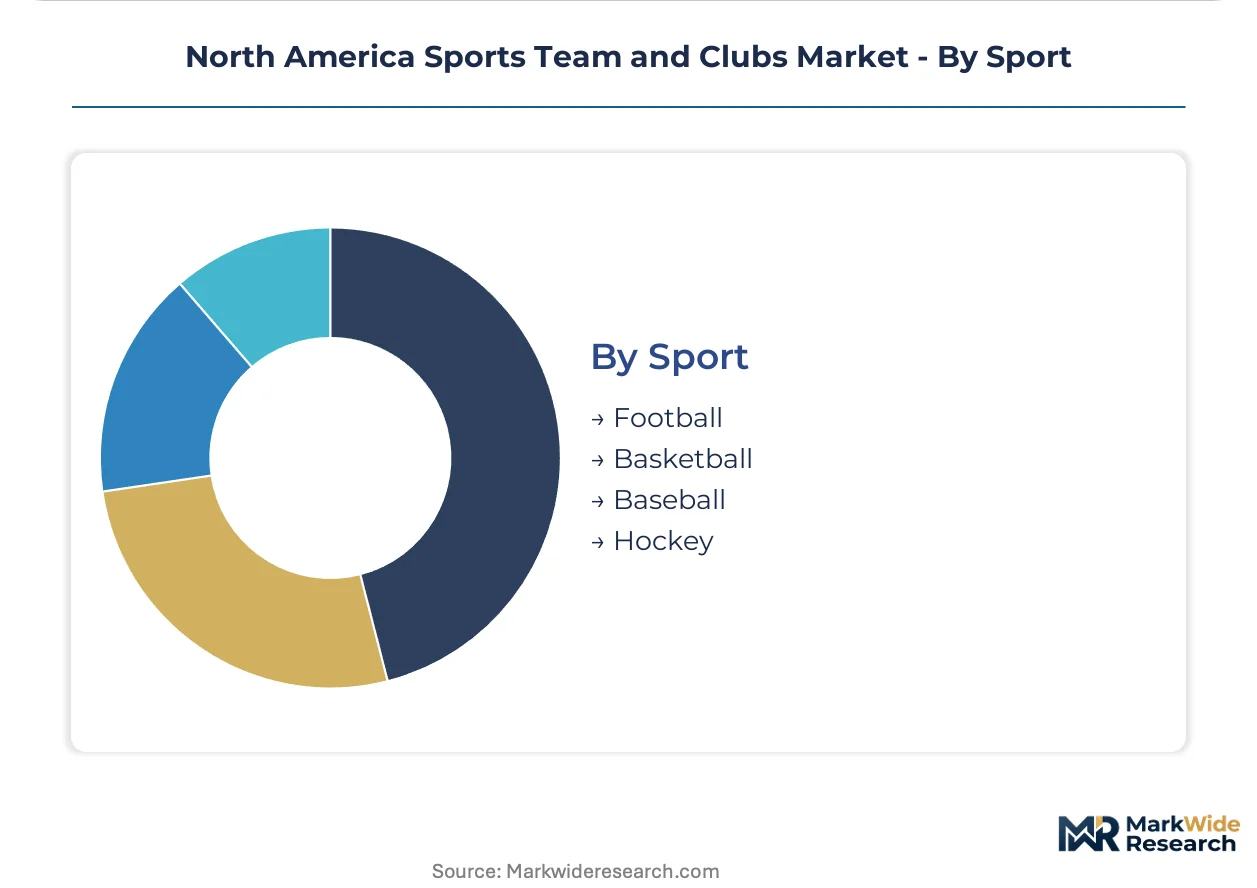
Sport:
Application segmentation aligns facility specifications, season length, and media contract structures with regional market characteristics.
- Football:NFL operations with 8-10 home dates annually and the highest per-game revenue concentration. The league's SAFETY Act compliance mandates are accelerating capital deployment into surveillance and access control infrastructure.
- Basketball:NBA and WNBA franchises with 41+ home dates enabling season-ticket dependency and premium seating inventory optimization. Technology convergence in mobile ordering and biometric entry is reshaping venue experience platforms.
- Baseball:MLB operations with 81 home dates and the most extensive minor league feeder systems. These franchises face the longest season and highest labor cost exposure under collective bargaining frameworks.
- Hockey:NHL and minor league operations concentrated in Canadian markets and northern US states. The Toronto Maple Leafs and Montreal Canadiens anchor the most season-ticket-dependent market structure in professional sports.
Football dominates per-event revenue capture. Basketball is where technology-enabled experience expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America sports team and clubs market operates as a net capital importer, with US franchise valuations attracting sovereign wealth and private equity from outside the region while Canadian clubs face outbound investment friction under foreign ownership review frameworks.
United States
Texas and California metropolitan clusters concentrate franchise expansion capital, with Dallas-Fort Worth and Houston pulling Sun Belt infrastructure investment. The NFL's SAFETY Act compliance mandates under the Department of Homeland Security accelerate stadium security capital deployment. SoFi Stadium in Los Angeles anchors the largest integrated real estate and media campus in professional sports.
Canada
Toronto and Montreal dominate hockey franchise economics through the NHL's most season-ticket-dependent market structure. Competition Act provisions on ticket resale transparency constrain dynamic pricing algorithms for Maple Leaf Sports and Entertainment. Scotiabank Arena in Toronto integrates direct-to-fan membership models that bypass traditional ticketing intermediaries.
California
San Diego and Sacramento present expansion-ready demographics with underserved professional franchise presence relative to media market density. State-level sports betting authorization creates new revenue architectures for stadium operators with integrated mobile wagering partnerships. Chase Center in San Francisco anchors technology convergence in venue experience platforms.
Texas
Dallas-Fort Worth and Houston command premium franchise valuations through corporate hospitality buyer consolidation and media market concentration. The Dallas Cowboys leverages vertically integrated merchandising and real estate holdings to sustain margin capture beyond game-day operations. AT&T Stadium in Arlington represents the largest revenue-per-seat infrastructure in North American sports.
New York Metro
The New York Yankees and Knicks compete through premium inventory control in the nation's largest media market. Madison Square Garden Entertainment anchors multi-venue hospitality ecosystems spanning Manhattan and Las Vegas. Barclays Center in Brooklyn demonstrates adaptive reuse of arena infrastructure for mixed programming.
North America Sports Team and Clubs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower value capture. The North America sports team and clubs market consolidates around league-chartered franchises with centralized revenue sharing, creating tiered competitive dynamics between large-market media hubs and mid-market operations. Three strategic archetypes dominate: vertically integrated real estate holders, technology-enabled experience platforms, and premium inventory controllers. Franchise groups deploy M&A to acquire regional sports networks and expand through strategic partnerships with wagering and hospitality platforms.
Within the vertically integrated tier, the Dallas Cowboys and Golden State Warriors exemplify divergent capital deployment models. The Cowboys anchors Texas market expansion through captive real estate and merchandising infrastructure. The Warriors occupies a position in California technology convergence, representing venue experience platform leadership. The Toronto Maple Leafs sits within the premium inventory control archetype, anchoring hockey's most concentrated season-ticket market.
| Leading Market Players |
|---|
| Dallas Cowboys |
| Golden State Warriors |
| Los Angeles Rams |
| New York Yankees |
| Los Angeles Lakers |
| New England Patriots |
| New York Knicks |
| Toronto Maple Leafs |
| Chicago Cubs |
| Others |
Pricing and Supply Chain Analysis
Texas metropolitan clusters anchor North American venue infrastructure capacity, with Dallas-Fort Worth and Houston stadium development pipelines compressing regional construction labor markets and amplifying pricing power for specialized contractors serving NFL and NBA franchises.
Pricing Analysis
Corporate hospitality buyers anchor pricing structures across premium seating tiers. Three-tier pricing stratification separates club-level suites from lower-bowl reserved seats and upper-deck general admission, with differentiation driven by venue technology integration and proximity to biometric-enabled entry gates. Cost compression in mid-tier inventory intensifies as franchises unbundle traditional season packages into quarter-based offerings. Amateur recreational leagues exhibit highest price sensitivity, while Fortune 500 hospitality accounts demonstrate inelastic demand for controlled-access entertainment environments.
Supply Chain Analysis
Steel and concrete feedstock markets in the United States, Canada, and Mexico determine stadium construction cost baselines. Integrated surveillance systems, cashless payment infrastructure, and LED display technology represent critical component dependencies. Single-source vulnerability concentrates in specialized access control hardware sourced from limited certified vendors. Distribution runs through league-approved contractor networks with exclusive regional servicing rights, creating captive procurement channels for venue operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent scarcity in stadium operations technology constrains expansion velocity, as franchises compete for professionals with integrated security, hospitality, and digital platform expertise.
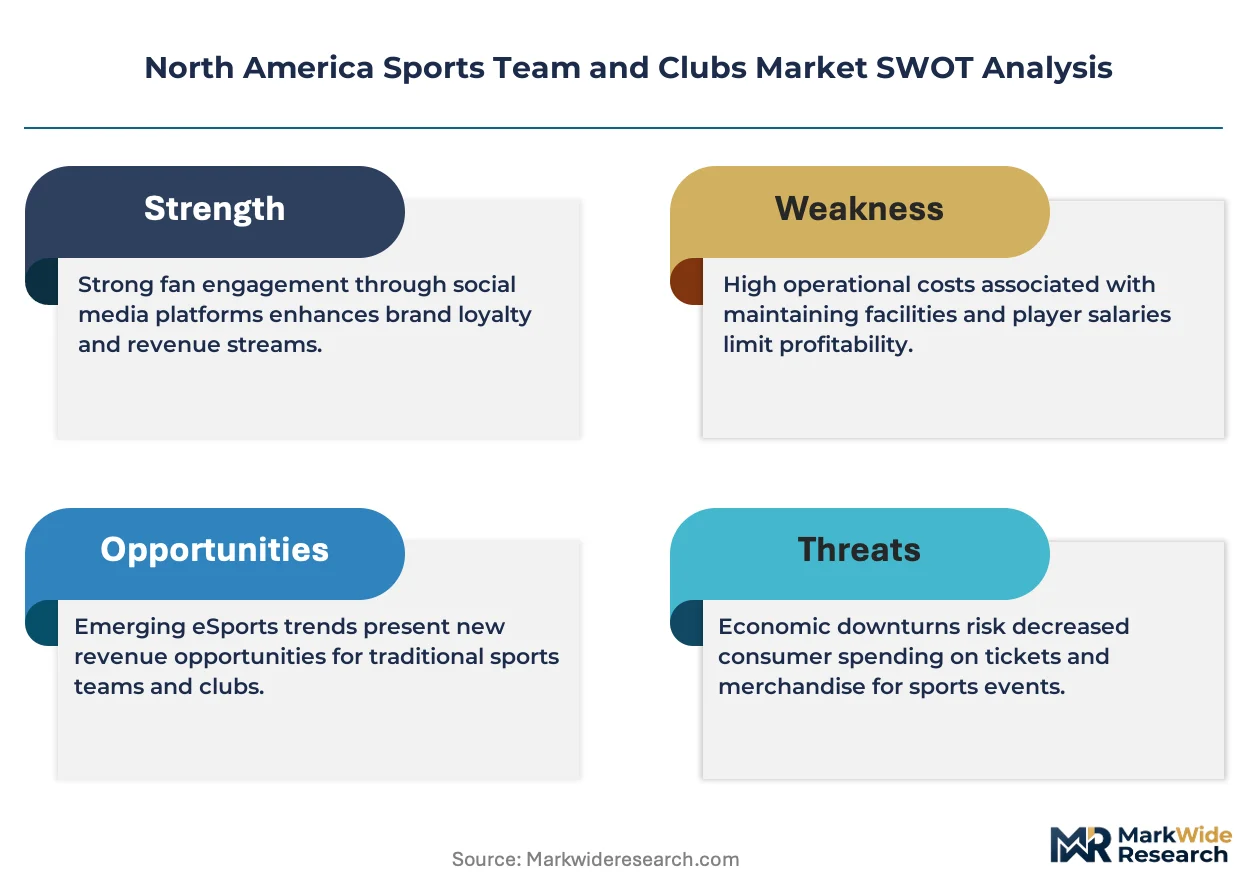
For Market Incumbents: Build regulatory compliance moats around SAFETY Act certification and state-level sports betting integration. Fortify position by acquiring regional sports network assets and embedding wagering partnerships directly into venue mobile applications. Counter emerging technology-enabled experience platforms through exclusive biometric data partnerships with hospitality vendors. For New Entrants and Emerging Players: Build out direct-to-fan membership architectures in Canadian markets where Competition Act transparency mandates have weakened incumbent ticketing intermediaries. Target Sacramento and San Diego expansion corridors where media market density exceeds current franchise presence. Penetrate through white-label venue technology platforms serving mid-market collegiate athletic departments. For Investors and Strategic Acquirers: Long-term, this sits as a real estate-anchored media play because franchise valuations increasingly derive from integrated property holdings and local sports network control rather than game-day operations alone. Focus acquisition screening on clubs with captive arena real estate and underexploited premium inventory. Monitor state-level sports betting authorization velocity as the inflection signal for venue revenue architecture transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Entry System Deployment | Facial recognition and palm-vein scanning at Chase Center and SoFi Stadium compress transaction friction while capturing behavioral data for hospitality targeting. |
| Real Estate Lease-Back Structuring | AT&T Stadium's captive Arlington development demonstrates how vertical property control sustains margin capture beyond eight annual home dates. |
| Direct-to-Fan Membership Platform | Scotiabank Arena's bypass of traditional ticketing intermediaries responds to Canadian Competition Act constraints while building proprietary customer data assets. |
| Mobile Wagering Integration | State-authorized in-venue betting partnerships create new revenue architectures for stadium operators with captive fan engagement during live events. |
| Regional Sports Network Acquisition | YES Network and Spectrum SportsNet control illustrates how local media rights provide the revenue floor supporting franchise debt financing structures. |
Research Methodology
Cross-validation between franchise financial disclosures and municipal bond prospectuses anchors the qualitative findings. Primary interviews with stadium operations directors, corporate hospitality procurement managers, league revenue-sharing administrators, and sports technology platform executives combined with secondary validation against SEC filings, state athletic commission records, and municipal infrastructure development databases. Bottom-up venue capacity and attendance modeling triangulates against top-down media rights contract value aggregation.
Calibration against historical franchise transaction multiples and stadium construction cost indices shapes the analytical framework across the projection horizon. Segmentation dimensions include organization type, revenue stream architecture, membership model structure, and sport-specific facility requirements. CAGRs derive from league media contract escalators, premium seating inventory expansion rates, and technology-enabled per-capita spending growth. Forecast inputs incorporate state-level sports betting authorization timelines and SAFETY Act compliance capital deployment schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sovereign wealth funds or private equity aggregators would shift outcomes beyond modeled ranges. Cross-checking against franchise valuation indices published by sports business research institutions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Padel Court Operator Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market