
 UK Sports Team and Clubs Market | 2026-2036
UK Sports Team and Clubs Market Size, Share, and Industry Trends Forecast 2026-2036
UK Sports Team and Clubs Market Insights
Multi-source talent development partnerships between academies and local schools is repositioning how English football clubs build player pipelines. Manchester United leverages its Carrington training complex to sustain youth-to-first-team pathways. Liverpool anchors its commercial operations through Anfield's expanded hospitality infrastructure. Chelsea competes on global brand licensing across Asian merchandise markets.
UK sports teams and clubs comprise organized competitive athletic entities operating licensed stadiums, training facilities, and commercial programs governed by sport-specific governing bodies and financial fair play protocols. These organizations generate revenue through matchday operations, media rights distribution, and intellectual property monetization while maintaining squad rosters and community development obligations. Professional Teams command the largest revenue pools through broadcasting rights concentration, while Grassroots Associations represent the fastest-growing membership category as local authority funding redirects toward community sport access. Merchandising margins exceed ticket sales profitability for established Premier League properties.
The Football Association, Sports Grounds Safety Authority, and UK Gambling Commission collectively shape operational standards, spectator safety mandates, and sponsorship restrictions across English football. Financial fair play regulations enforced by the Premier League limit squad expenditure ratios relative to commercial revenue, constraining mid-tier club spending flexibility. Stakeholders must monitor proposed independent football regulator legislation and its potential impact on club ownership tests and financial redistribution mechanisms.
Market Dynamics
The Sports Grounds Safety Authority licensing regime is tightening facility compliance requirements, forcing stadium operators to accelerate capital deployment into spectator safety infrastructure and crowd management systems.
Growth Catalysts
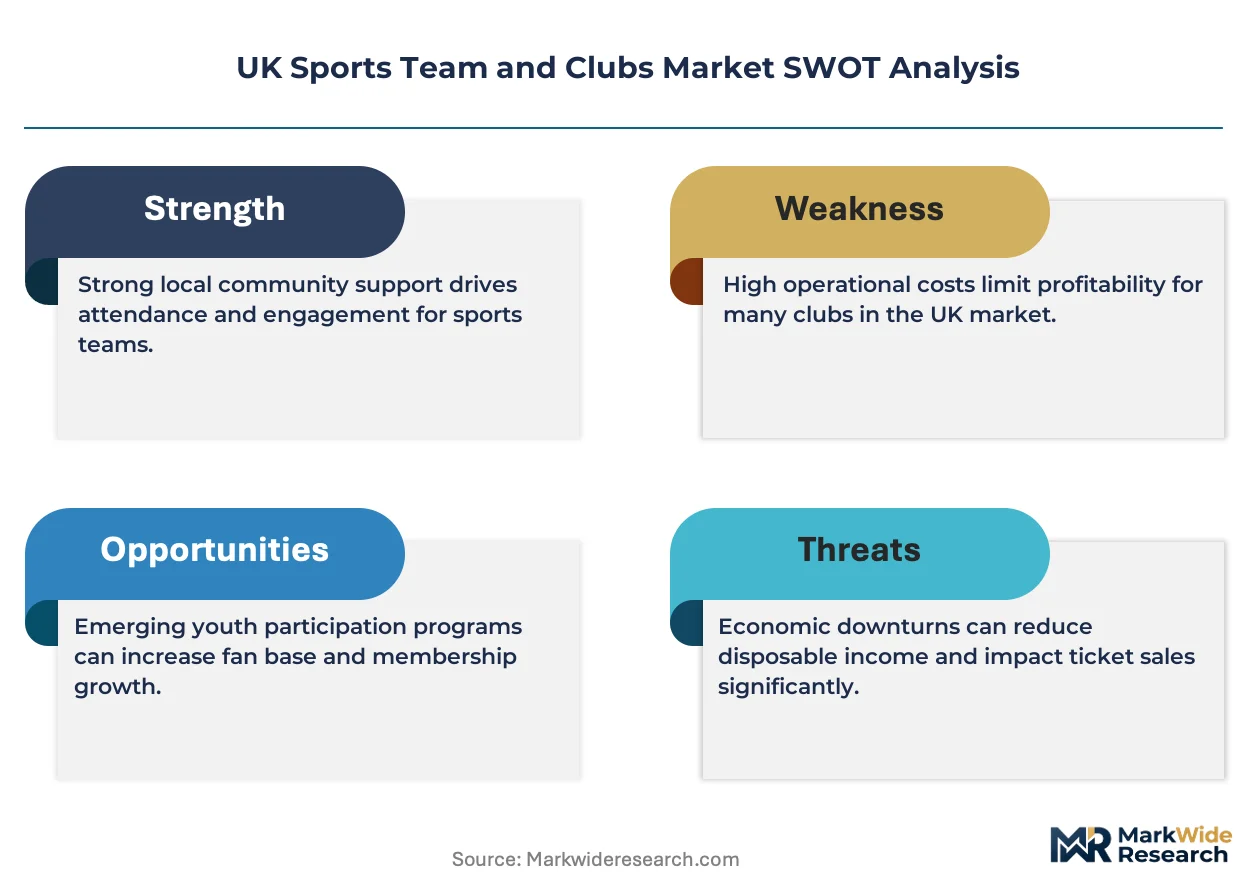
- Financial Fair Play Protocols:Premier League expenditure controls are compressing wage-to-revenue ratios at mid-tier clubs, redirecting investment toward commercial infrastructure and hospitality development.
- Corporate Hospitality Expansion:Professional football clubs are capturing premium revenue through executive box sales and matchday experience packages to financial services and technology sector buyers.
- Greater London Corridor:Demand concentration along the Premier League corridor is driving stadium redevelopment and transport infrastructure co-investment from local authorities.
Market Restraints
- Broadcasting Rights Concentration:Revenue pooling heavily favors six elite clubs, constraining competitive balance and mid-tier club commercial flexibility.
- Local Authority Funding Constraints:Grassroots facility maintenance depends on municipal budgets that face pressure from competing public service obligations.
- Gambling Sponsorship Restrictions:UK Gambling Commission advertising codes are limiting front-of-shirt revenue streams for Championship and League One operators.
Strategic Opportunities
- Community Sport Access Mandates:Local authority funding redirection toward grassroots participation creates facility partnership openings for professional club foundations.
- Asian Merchandise Markets:Brand licensing and direct-to-consumer digital platforms are penetrating underdeveloped fan bases in East Asian metropolitan markets.
- Stadium Hospitality Technology:Cashless payment integration and personalized mobile ordering are upgrading concession and premium seating monetization.
Industry Challenges
- Player Pipeline Talent Scarcity:Academy-to-first-team pathways require sustained investment in coaching infrastructure and school partnership networks.
- Legacy Stadium Compliance:Victorian-era grounds face structural retrofit costs to meet modern safety certification timelines from the Sports Grounds Safety Authority.
- Intellectual Property Licensing Complexity:Global brand partnerships demand coordinated trademark enforcement across fragmented jurisdictional frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Sports Team and Clubs Market |
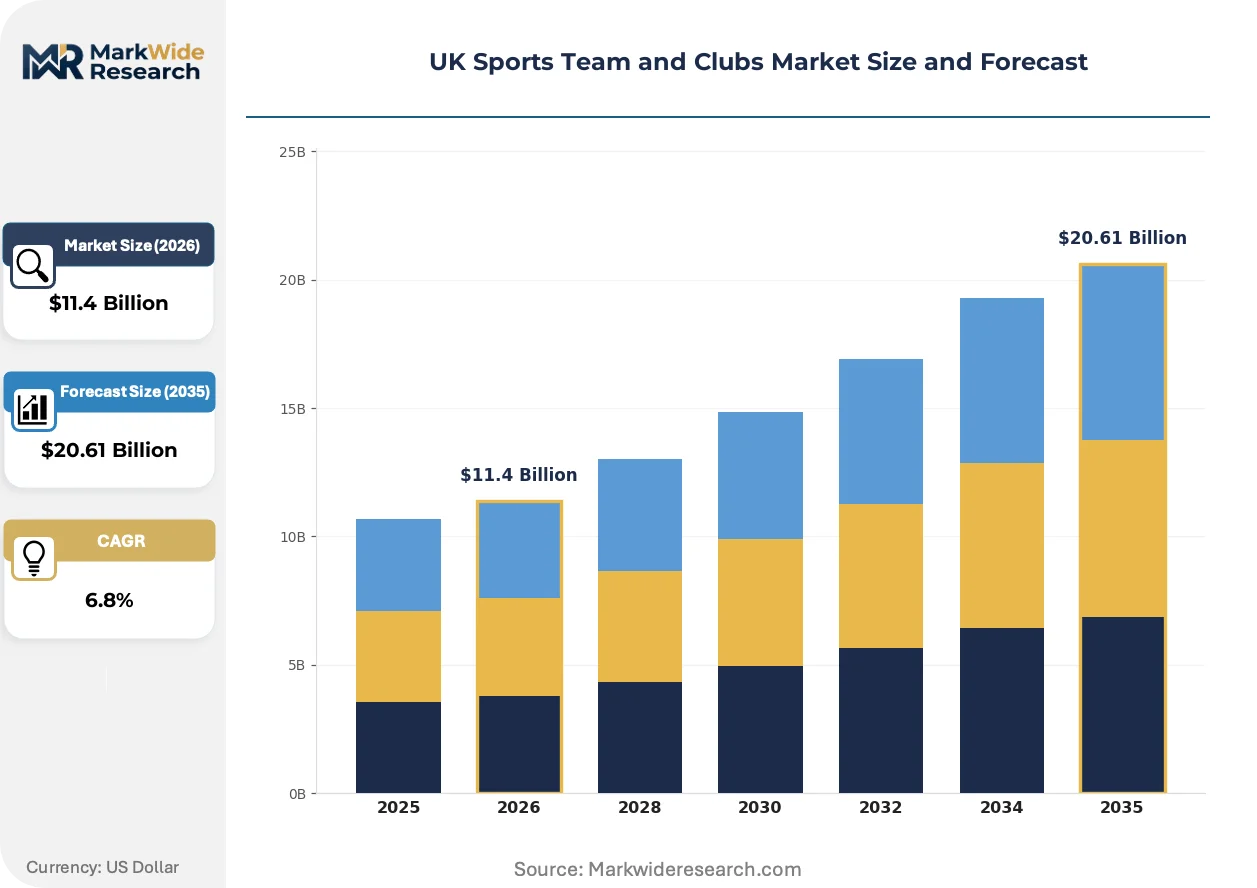
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Organization Type: Professional Teams, Amateur Clubs, Semi-Professional Teams, Grassroots Associations Revenue Stream: Ticket Sales, Merchandising, Sponsorships, Broadcasting Rights Membership Model: Season Ticket Holders, Fan Clubs, Youth Programs, Corporate Partnerships Sport Category: Football, Rugby, Cricket, Basketball |
| Companies Covered | Manchester United, Liverpool, Manchester City, Chelsea, Tottenham Hotspur, Arsenal, West Ham United, Newcastle United, Rugby Football Union, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Sports Team and Clubs Market Trends and Innovations
Digital infrastructure and regulatory pressure are simultaneously reshaping revenue architecture and operational compliance across English football's commercial ecosystem.
Stadium connectivity infrastructure is absorbing capital deployment from hospitality operators seeking to monetize real-time fan engagement through mobile ordering and personalized content delivery. Premier League properties are installing distributed antenna systems and Wi-Fi 6E networks to support these applications. The technology is absorbing matchday revenue that previously flowed through conventional concession and merchandise channels.
The UK's proposed independent football regulator legislation is mandating strengthened ownership fit-and-proper tests alongside financial redistribution mechanisms. Championship and League One clubs face heightened disclosure requirements and debt sustainability assessments. Clubs are responding by restructuring governance frameworks and diversifying revenue away from broadcast dependency.
Corporate buyers are consolidating hospitality procurement through multi-season partnership frameworks rather than transactional matchday purchases. Financial services and professional services firms are negotiating three-to-five-year executive box and lounge access agreements with top-tier properties. This concentration is most visible in Greater London, where technology and law sector demand has compressed availability at renovated stadiums.
UK Sports Team and Clubs Market Segmentation
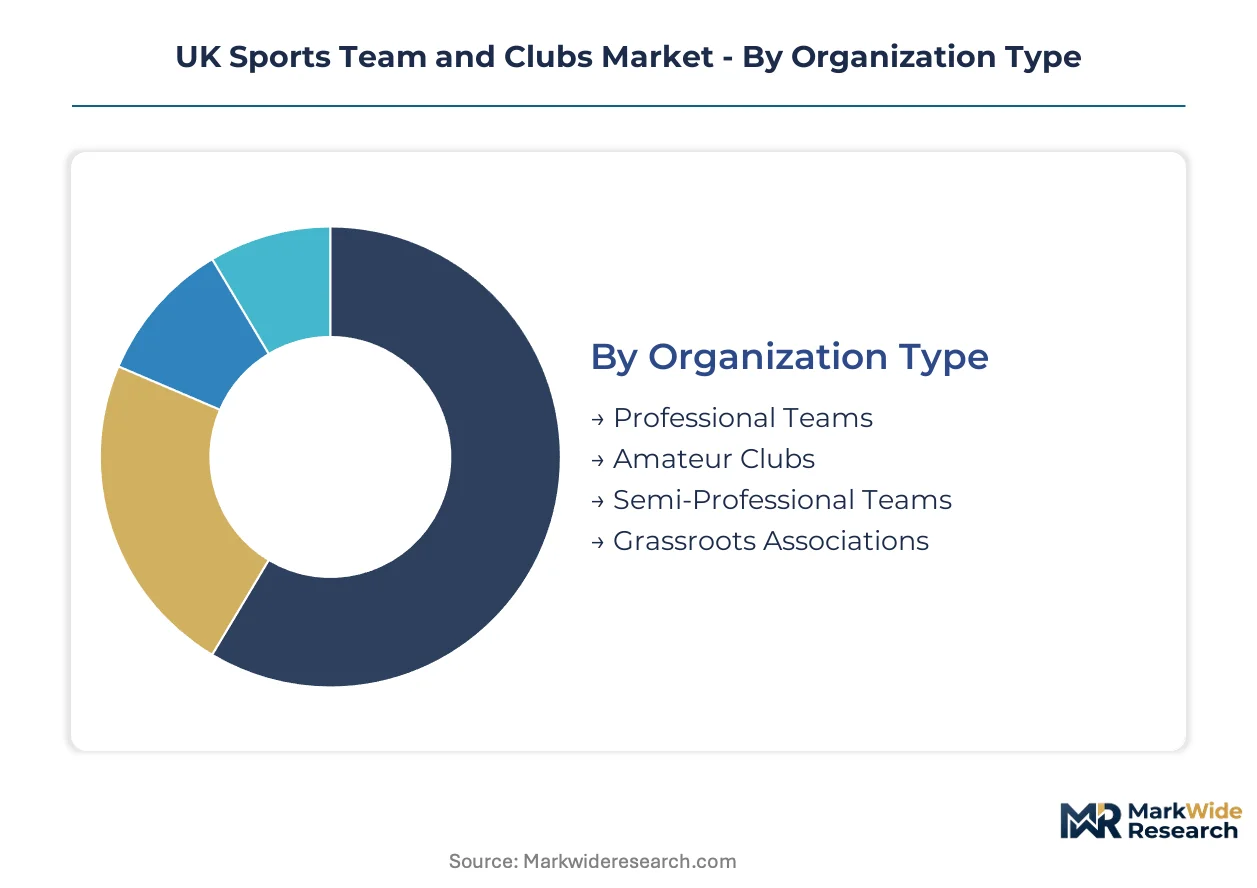
Segmentation reveals how revenue concentration and regulatory pressure distribute unevenly across English football's commercial architecture. Understanding these divisions exposes where capital deployment yields returns and where compliance costs erode margins.
Organization Type:
Supply concentration pools broadcasting revenue and hospitality infrastructure investment among a narrow tier of licensed operators with stadium assets and academy pipelines.
- Professional Teams:These entities operate licensed stadiums, training complexes, and commercial programs under Premier League or EFL governance. Broadcasting rights concentration and hospitality monetization in Greater London's Premier League corridor absorb the majority of sector capital deployment. The Sports Grounds Safety Authority licensing regime forces continuous facility reinvestment.
- Grassroots Associations:Community-level organizations deliver participation programs through local authority facility partnerships. Local authority funding redirection toward community sport access in England's metropolitan counties is expanding membership pools fastest, though maintenance budgets compete with broader public service obligations.
- Amateur Clubs:Volunteer-driven entities operating below the National League System threshold rely on municipal pitch access and minimal commercial infrastructure.
- Semi-Professional Teams:National League and regional tier operators balance part-time player contracts with limited hospitality revenue and local sponsorship.
Today's leader: Professional Teams. Tomorrow's challenger: Grassroots Associations.
Revenue Stream:
Cost tier differentiation separates capital-intensive infrastructure-dependent streams from scalable intellectual property monetization.
- Merchandising:Brand licensing, direct-to-consumer digital platforms, and retail partnerships monetize club intellectual property across domestic and Asian metropolitan markets. Margins exceed ticket sales profitability for established Premier League properties with global recognition.
- Broadcasting Rights:Collective selling arrangements pool Premier League and EFL media revenue, with distribution formulas heavily favoring six elite clubs. Revenue concentration constrains competitive balance and mid-tier club commercial flexibility.
- Ticket Sales:Matchday operations generate revenue through general admission, season tickets, and premium seating at licensed stadiums.
- Sponsorships:Front-of-shirt, sleeve, and training kit partnerships face UK Gambling Commission advertising code restrictions limiting revenue for Championship and League One operators.
Current margin leader: Merchandising. Regulatory pressure point: Sponsorships.
Membership Model:
Customer type stratification determines lifetime value capture and engagement depth across the supporter base.
- Corporate Partnerships:Multi-season hospitality frameworks with financial services and technology sector buyers generate premium revenue through executive boxes and lounge access. Procurement consolidation in Greater London has compressed availability at renovated stadiums.
- Season Ticket Holders:Core supporter commitment providing predictable matchday revenue and priority access to cup and European fixtures.
- Fan Clubs:Official membership schemes offering merchandise discounts, content access, and ballot priority for away tickets.
- Youth Programs:Academy and community foundation initiatives building player pipelines through school partnerships and talent identification networks.
Highest value concentration: Corporate Partnerships. Engagement foundation: Season Ticket Holders.
Sport Category:
Maturity differentiation separates established commercial ecosystems from developing revenue architectures.
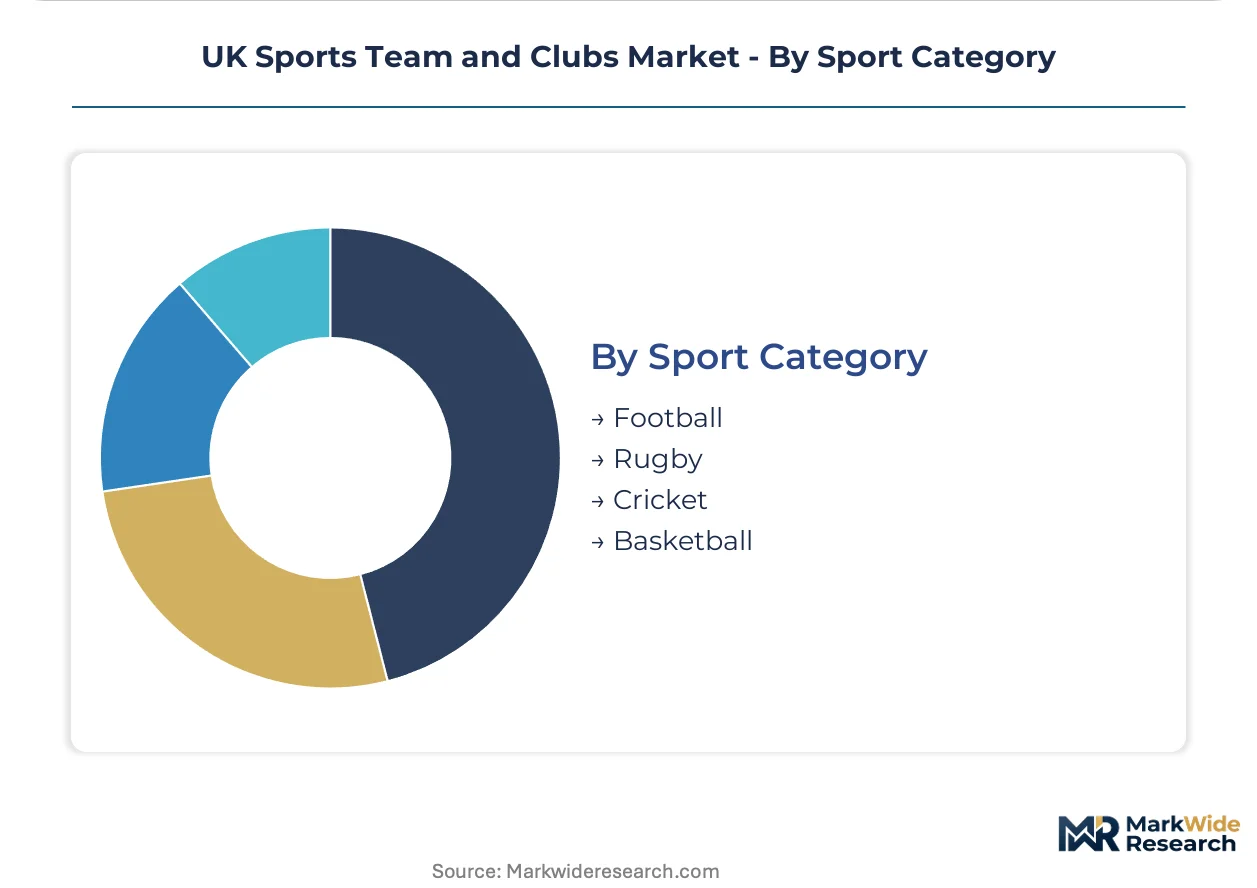
- Football:The dominant commercial ecosystem with concentrated broadcasting rights, global brand licensing, and stadium hospitality infrastructure governed by The Football Association and Premier League financial fair play protocols.
- Rugby:Premiership and Championship clubs operate within RFU governance with smaller but dedicated hospitality markets and limited international media revenue.
- Cricket:County championship and Hundred franchise models blend traditional membership with short-form broadcast innovation.
- Basketball:British Basketball League operates with minimal stadium infrastructure and broadcast visibility compared to football's commercial scale.
Established commercial architecture: Football. Format innovation testbed: Cricket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in UK sports infrastructure are minimal given the centralized governance of the Football Association and Sports Grounds Safety Authority. Capital deployment instead concentrates where hospitality revenue density and broadcasting rights valuations justify stadium reinvestment costs.
Greater London
Corporate hospitality procurement from financial services and technology firms compresses availability at renovated stadiums including Tottenham Hotspur Stadium and Emirates Stadium. The Greater London Authority coordinates transport infrastructure co-investment with club developers. West Ham United's London Stadium conversion exemplifies public-private facility partnerships.
North West England
Manchester United and Manchester City anchor broadcasting revenue concentration through academy-to-first-team pipelines and global brand licensing. The Football Association's financial fair play protocols constrain squad expenditure ratios for both clubs. Liverpool's Anfield Road expansion demonstrates hospitality infrastructure monetization in a heritage-constrained site.
West Midlands
Aston Villa and Wolverhampton Wanderers compete for mid-tier commercial revenue through executive box sales and regional sponsorship frameworks. Local authority funding redirection toward community sport access expands grassroots facility partnerships. Birmingham's Commonwealth Games legacy infrastructure supports multi-sport venue utilization.
North East England
Newcastle United's Saudi-led ownership has accelerated St James' Park hospitality development and commercial team expansion. The Sports Grounds Safety Authority licensing regime forces continuous spectator safety reinvestment. Sunderland's Stadium of Light operates below Premier League revenue thresholds despite comparable facility scale.
Scotland
Celtic and Rangers operate outside English football's financial fair play framework but face UEFA cost-control regulations for European competition. The Scottish Football Association governs facility standards with reduced capital requirements compared to Premier League counterparts. Glasgow's Hampden Park hosts national team fixtures with limited club-controlled hospitality revenue.
UK Sports Team and Clubs Market Competitive Landscape
Established Premier League clubs occupy the premium tier; emerging Championship and League One operators pursue stadium redevelopment and hospitality infrastructure to bridge revenue gaps. The market structures around broadcasting rights concentration that pools revenue unequally across six elite properties. Three archetypes dominate: heritage clubs with global brand licensing, state-backed ownership vehicles with capital-intensive facility investment, and community-trust models with local authority facility partnerships. Competitive moves center on multi-season corporate hospitality framework negotiations and Asian merchandise market penetration through direct-to-consumer digital platforms.
Within the heritage-club tier, Manchester United and Liverpool exemplify properties leveraging century-plus brand equity for international licensing revenue. Manchester City represents state-backed capital deployment into training infrastructure and hospitality technology. Chelsea occupies a transitional position following ownership change, with commercial operations pivoting toward Asian merchandise markets. These three anchors illustrate how revenue architecture diverges between broadcasting-dependent, hospitality-intensive, and licensing-focused strategies despite shared Premier League governance.
| Leading Market Players |
|---|
| Manchester United |
| Liverpool |
| Manchester City |
| Chelsea |
| Tottenham Hotspur |
| Arsenal |
| West Ham United |
| Newcastle United |
| Rugby Football Union |
| Others |
Pricing and Supply Chain Analysis
Corporate hospitality procurement consolidation across Greater London's Premier League corridor is compressing availability at renovated stadiums, forcing supply-side facility investment and reshaping how clubs structure multi-season partnership pricing. This demand concentration creates tiered access economics where financial services and technology sector buyers absorb premium inventory.
Pricing Analysis
Input-cost pass-through from Sports Grounds Safety Authority compliance mandates is elevating facility reinvestment requirements into hospitality rate structures. Three-tier pricing separates executive box packages from premium lounge access from general admission, with differentiation anchored in digital infrastructure quality and transport connectivity. Pricing pressure stems from broadcasting rights concentration favoring elite clubs, compressing commercial flexibility at mid-tier properties. Championship and League One operators exhibit highest price sensitivity due to gambling sponsorship restrictions limiting alternative revenue streams.
Supply Chain Analysis
Direct-to-corporate channels handle multi-season hospitality procurement from financial services and technology sector buyers, with distribution running through club commercial departments and hospitality agencies. Geographic supply concentration pools stadium development expertise in the United Kingdom, Spain, and the United States, with construction and technology vendors clustering around Premier League infrastructure projects. Raw material dependencies include steel for structural retrofit, distributed antenna systems for connectivity, and cashless payment hardware for concession modernization. Single-source vulnerability sits with specialized crowd management technology providers serving Victorian-era ground compliance timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Sports Team and Clubs Market functions as a regulatory compounder, with the proposed independent football regulator legislation mandating ownership fit-and-proper tests and financial redistribution mechanisms that will reshape capital deployment priorities.
For Market Incumbents: Hedge against broadcasting dependency by accelerating hospitality infrastructure monetization and Asian merchandise market penetration through direct-to-consumer digital platforms. Diversify revenue architecture toward corporate partnership frameworks and brand licensing to offset potential regulatory redistribution impacts. Vertical integration into academy-to-first-team coaching infrastructure secures player pipeline talent against wage-to-revenue compression from financial fair play protocols. For New Entrants and Emerging Players: Stadium hospitality technology vendors present a technology-first wedge for cashless payment integration and personalized mobile ordering systems at Championship and League One properties undergoing compliance-driven renovation. Grassroots facility partnerships with local authorities redirecting funding toward community sport access offer the most penetrable segment. Target multi-year service contracts with professional club foundations seeking operational efficiency. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier clubs possessing stadium asset bases and renovation permissions in Greater London corridor transport co-investment zones. Long-term viability hinges on regulatory adaptation capacity and hospitality revenue density rather than broadcasting pool dependence. Monitor independent football regulator legislation passage as the critical inflection signal for ownership test stringency and redistribution mechanism implementation.| Strategic Initiative | Industry Significance |
|---|---|
| Stadium Hospitality Technology Deployment | Cashless payment integration at Tottenham Hotspur Stadium upgrades concession monetization through personalized mobile ordering systems. |
| Asian Merchandise Market Licensing | Direct-to-consumer digital platforms penetrate underdeveloped East Asian metropolitan fan bases beyond traditional retail partnerships. |
| Grassroots Facility Partnership | Professional club foundations capture local authority funding redirection toward community sport access in England's metropolitan counties. |
| Corporate Hospitality Framework Negotiation | Multi-season executive box agreements with financial services buyers compress availability and secure premium revenue predictability. |
| Academy Infrastructure Investment | School partnership networks at Manchester United's Carrington complex sustain youth-to-first-team player pipeline development. |
Research Methodology
Coverage spans England, Scotland, Wales, and Northern Ireland, with primary inputs from each jurisdiction combined with secondary validation across regulatory and financial sources. Primary interviews incorporated club commercial directors, stadium operations managers, Sports Grounds Safety Authority licensing officers, local authority sport development leads, and hospitality procurement executives at financial services firms. Secondary sources included Football Association governance documentation, Premier League financial fair play filings, Sports Grounds Safety Authority compliance bulletins, and local authority budget allocation records. Bottom-up facility investment tracking and top-down broadcasting revenue pooling analysis provided triangulation.
Rate-of-change decomposition across the projection horizon separated matchday operations, media rights distribution, and intellectual property monetization into distinct growth trajectories. Segmentation dimensions modeled encompassed organization type, revenue stream, membership model, and sport category, with regional regulatory cluster differentiation between English football governance and Scottish Football Association frameworks. CAGRs derived from facility investment cycle analysis, hospitality capacity expansion timelines, and grassroots participation enrollment trends.
The model holds under stable regulatory implementation timelines; deviation in independent football regulator legislation passage schedules or accelerated Sports Grounds Safety Authority certification deadlines would shift capital deployment patterns and revenue recognition timing. Forecasts reflect documented assumptions regarding broadcasting rights renewal trajectories and corporate hospitality demand elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Smart Bike Trainers Market