
 France Sports Teams and Clubs Market | 2026-2036
France Sports Teams and Clubs Market Size, Share, and Industry Trends Forecast 2026-2036
France Sports Teams and Clubs Market Insights
Digital subscription and streaming access layers is broadening what French sports clubs monetize beyond match-day attendance. Paris Saint Germain leverages its content platform to control direct-to-consumer engagement across international markets. Olympique de Marseille anchors its commercial strategy in regional brand loyalty throughout Provence-Alpes-Côte d'Azur. LOSC Lille competes through disciplined player development and transfer-market positioning that sustains operating margins.
France sports teams and clubs comprise organized competitive entities operating under federation charters with stadium assets, player contracts, and multi-channel revenue architectures; their primary function centers on delivering live sporting entertainment while extracting value from broadcast rights, sponsorship inventory, and licensed merchandise. Ticket sales and broadcast rights dominate revenue composition for professional football organizations, while amateur clubs and youth programs generate more stable but lower-margin membership flows. Merchandise and sponsorship segments are expanding fastest as clubs develop direct retail channels and regional partnership tiers.
The DNCG, France's national professional football financial regulator, enforces solvency ratios that constrain debt-funded squad investment, while the Ministry of Sport oversees safety certifications for stadium infrastructure renewal. CSRD disclosure requirements are pressing larger clubs toward audited sustainability reporting that affects sponsor eligibility and public funding access. Stakeholders must track how digital rights fragmentation and evolving fiscal oversight reshape capital allocation between sporting performance and commercial infrastructure.
Market Dynamics
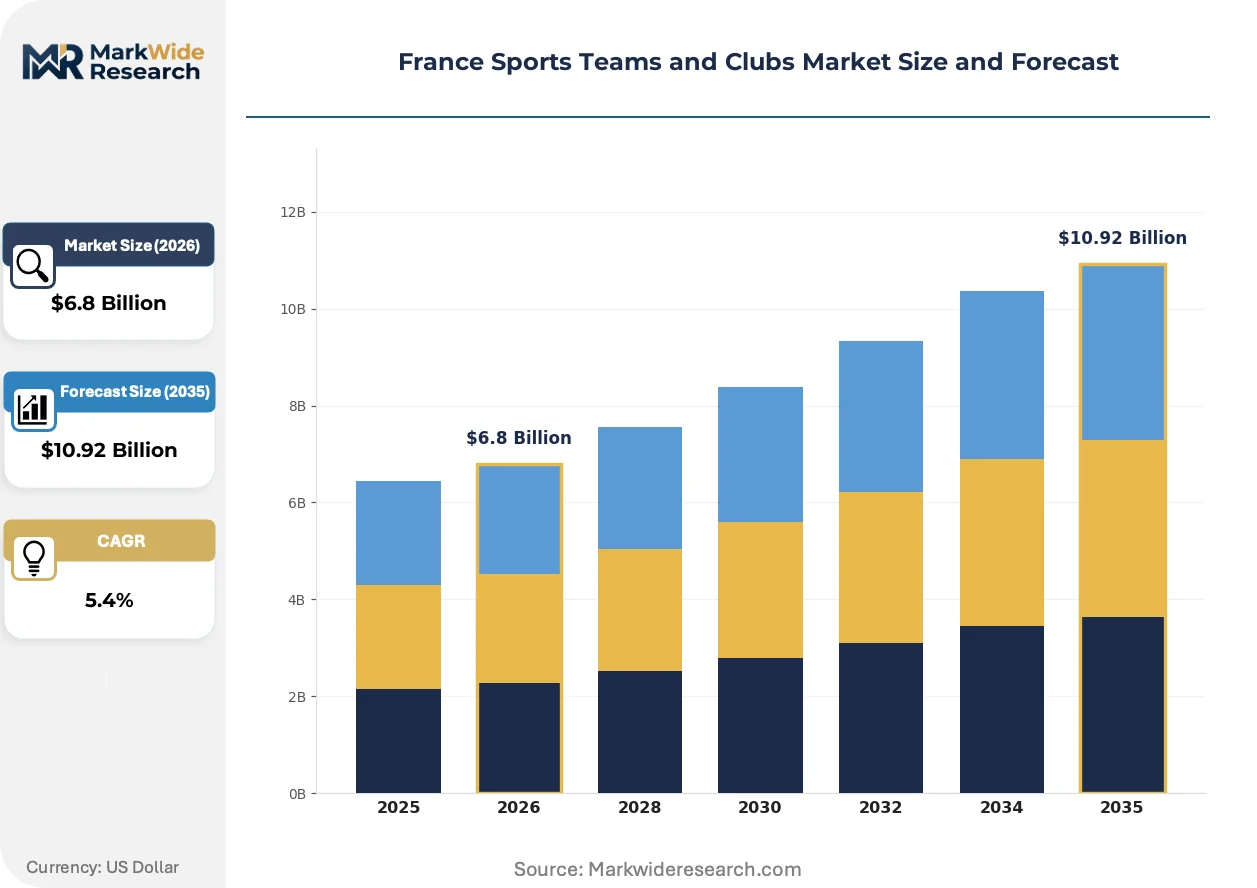
France's DNCG solvency framework is compressing debt-funded squad investment while CSRD disclosure mandates force clubs to reallocate capital toward audited sustainability infrastructure. This regulatory dual pressure is restructuring how sporting performance and commercial revenue architectures interlock.
Growth Catalysts
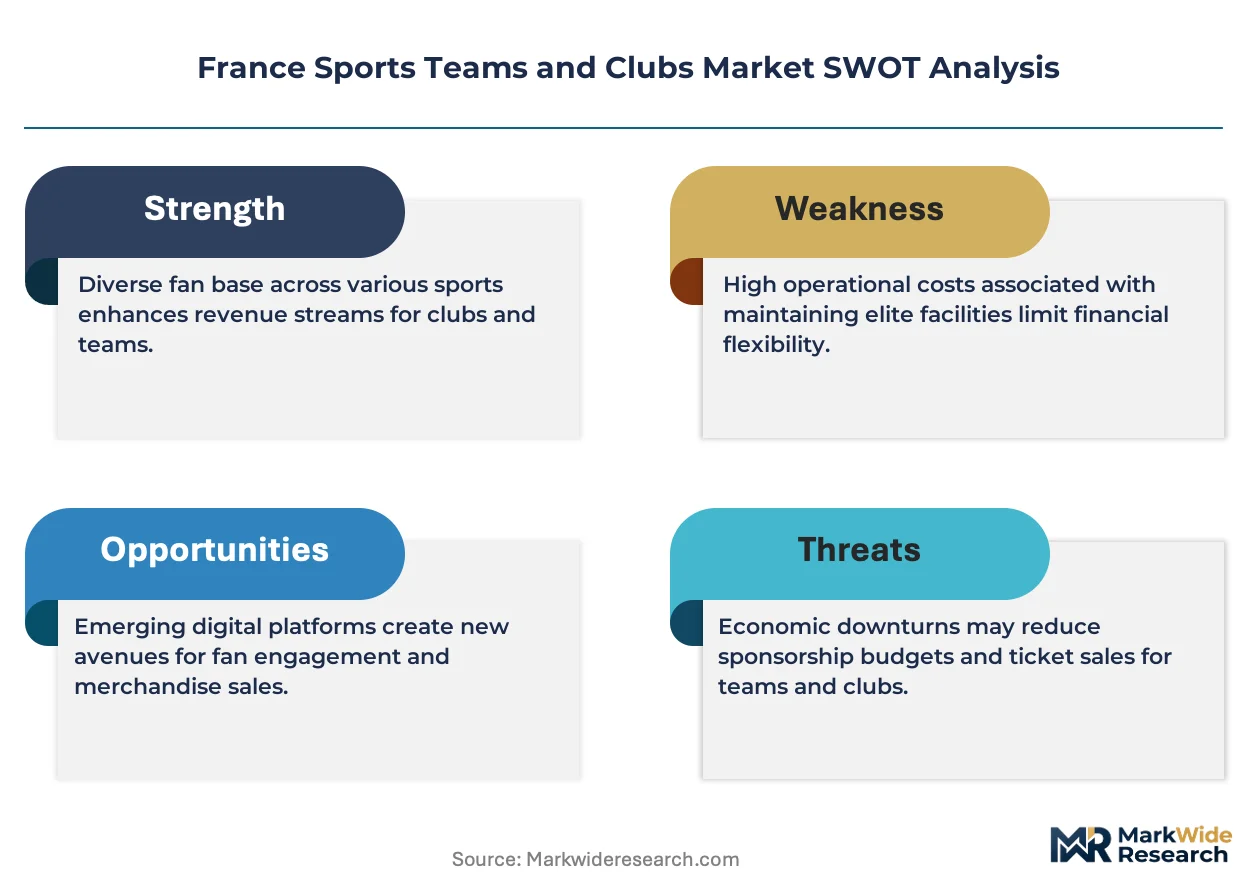
- DNCG Financial Oversight:France's national professional football regulator enforces debt-to-revenue ratios that reward disciplined clubs with licensing advantages. Solvent organizations gain preferential access to federation-controlled broadcast revenue pools.
- Stadium Mixed-Use Redevelopment:Paris and Lyon metropolitan clusters anchor entertainment district construction. These projects expand match-day monetization beyond ticketing into hospitality and retail concessions.
- Digital Subscription Tiering:Direct-to-consumer streaming platforms enable clubs to bypass traditional broadcast intermediaries. International fan bases generate recurring revenue detached from domestic attendance cycles.
Market Restraints
- Player Transfer Valuation Volatility:Squad asset values fluctuate with performance and injury risk. DNCG accounting rules require mark-to-market provisions that constrain balance sheet leverage.
- Broadcast Rights Concentration:Domestic league media contracts cluster among two primary distributors. Clubs outside the top tier face dependency on centralized revenue allocation formulas.
- Stadium Infrastructure Depreciation:Aging stands in secondary cities require safety certifications under Ministry of Sport oversight. Compliance capex diverts funds from sporting operations.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Regional Loyalty:Olympique de Marseille's brand equity remains undermonetized in digital channels. Supporter engagement outside match windows offers white space for subscription products.
- CSRD Sustainability Reporting:Mandatory disclosure creates sponsor eligibility tiers. Clubs with verified environmental credentials access corporate partnership budgets tied to ESG mandates.
- Youth Academy Licensing:Player development pipelines generate transfer-market returns. Federation-chartered training centers produce assets with minimal acquisition cost against premium sale valuations.
Industry Challenges
- Sporting Director Talent Scarcity:Dual-competency executives who balance financial discipline with squad construction remain rare. Clubs compete for professionals fluent in DNCG compliance and analytics-driven recruitment.
- Legacy Stadium Debt Restructuring:Municipal financing obligations from 1990s construction waves burden mid-tier clubs. Refinancing negotiations with regional authorities consume executive bandwidth.
- Cross-Platform Content Integration:Fragmented digital rights across streaming, social, and gaming channels complicate fan data unification. Technical architecture investments lag commercial strategy ambition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Sports Teams and Clubs Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Organization Type: Professional Teams, Amateur Clubs, Non-profit Organizations, Federations Revenue Stream: Ticket Sales, Merchandise, Sponsorship, Broadcast Rights Membership Model: Season Pass Holders, Casual Fans, Youth Programs, Corporate Sponsors Sport Category: Football, Rugby, Basketball, Handball |
| Companies Covered | Paris Saint Germain, AS Monaco FC, Olympique Lyon, Olympique de Marseille, Stade Rennais FC, LOSC Lille, Stade Reims, Toulouse FC, FC Nantes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Sports Teams and Clubs Market Trends and Innovations
French sports clubs are rearchitecting revenue models around direct fan relationships and regulatory-compliant infrastructure. Technology convergence and disclosure mandates are compressing traditional boundaries between sporting operations and commercial platforms.
Integrated data platforms are unifying ticketing, merchandise, and streaming interactions into single fan identity profiles. Top-tier clubs deploy these systems to personalize pricing and predict churn. The technology is unifying previously siloed revenue departments under chief digital officers with P&L authority.
France's CSRD transposition is mandating audited sustainability disclosures for clubs above revenue thresholds. The regulation forces infrastructure investment tracking and carbon footprint verification across stadium operations. Larger organizations are responding by embedding ESG metrics into executive compensation and sponsor contract negotiations.
Fan consumption patterns are fragmenting across mobile-first content snippets and full-match streaming. Younger demographics in the Île-de-France and Auvergne-Rhône-Alpes regions prioritize highlight access over season ticket commitments. Clubs are responding with micro-subscription tiers and gamified engagement apps that capture attention outside live fixtures.
France Sports Teams and Clubs Market Segmentation
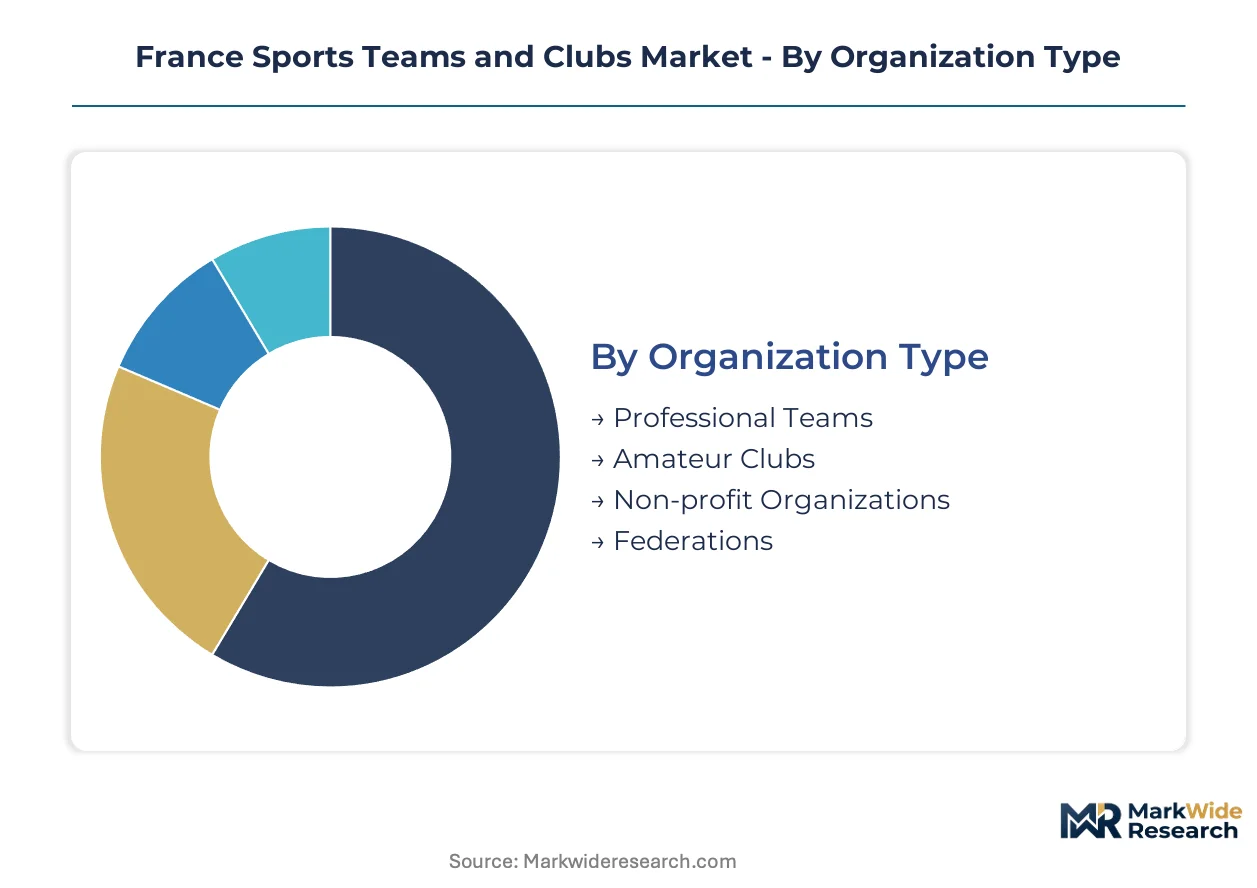
Segmentation in the France sports teams and clubs market reveals how revenue architecture varies dramatically across organizational maturity levels and fan relationship depth. Professional football organizations operate capital-intensive models with broadcast-dependent cash flows, while amateur federations sustain through membership fees and municipal subsidies. Understanding these structural divides informs where DNCG oversight applies and where digital monetization potential concentrates.
Organization Type:
Standardization dominates licensing and governance, yet customization persists in commercial strategy and stadium asset deployment across this category.
- Professional Teams:These entities operate under DNCG financial oversight with federation charters mandating audited solvency ratios. Paris and Lyon metropolitan clusters concentrate the highest revenue concentration, where stadium redevelopment into mixed-use entertainment districts expands match-day monetization beyond ticketing into hospitality and retail concessions.
- Amateur Clubs:Municipal financing and regional federation subsidies sustain operations with lower capital intensity. Provence-Alpes-Côte d'Azur and Auvergne-Rhône-Alpes regions host dense networks where local brand loyalty anchors community engagement but limits broadcast rights access.
- Non-profit Organizations:Social mission charters prioritize participation access over profit extraction, with revenue flowing from membership dues and grant funding rather than commercial exploitation.
- Federations:Governing bodies charter competition formats and control centralized revenue pools including broadcast rights distribution and national team commercialization.
Leading the category by volume: Amateur Clubs. Growing fastest: Professional Teams.
Revenue Stream:
Margin profiles diverge sharply between fixed-capacity physical assets and infinitely scalable digital inventory across this category.
- Ticket Sales:Stadium seating capacity constrains this revenue stream to match-day events with high fixed cost bases for security and operations. Île-de-France venues command premium pricing through hospitality packaging and corporate suite tiering.
- Merchandise:Direct-to-consumer retail channels and licensed partnerships generate recurring revenue detached from fixture schedules. Olympique de Marseille and Paris Saint-Germain anchor regional and international brand penetration through controlled distribution networks.
- Sponsorship:Corporate partnership tiers range from kit branding to stadium naming rights, with ESG-mandated budgets increasingly filtering toward CSRD-compliant clubs.
- Broadcast Rights:Domestic league media contracts cluster among two primary distributors, with federation-controlled allocation formulas favoring top-tier finishers.
Dominating revenue share: Broadcast Rights. Expanding most quickly: Merchandise.
Membership Model:
Engagement frequency and lifetime value separate stable subscription bases from transactional attendance patterns across this category.
- Season Pass Holders:Committed supporters provide predictable cash flow and priority access allocation, forming the core demographic for stadium redevelopment financing in Lyon and Paris clusters.
- Casual Fans:Match-by-match purchasers respond to fixture significance and pricing promotions, with digital platforms now capturing this segment through micro-subscription tiers and highlight access.
- Youth Programs:Federation-chartered training centers generate player development pipelines with minimal acquisition cost against premium transfer-market valuations.
- Corporate Sponsors:Hospitality packages and executive entertainment access command premium pricing, with ESG disclosure requirements reshaping eligibility criteria under CSRD mandates.
Highest retention rates: Season Pass Holders. Steepest expansion trajectory: Corporate Sponsors.
Sport Category:
Commercial infrastructure maturity and international broadcast appeal create divergent revenue ceilings across this category.
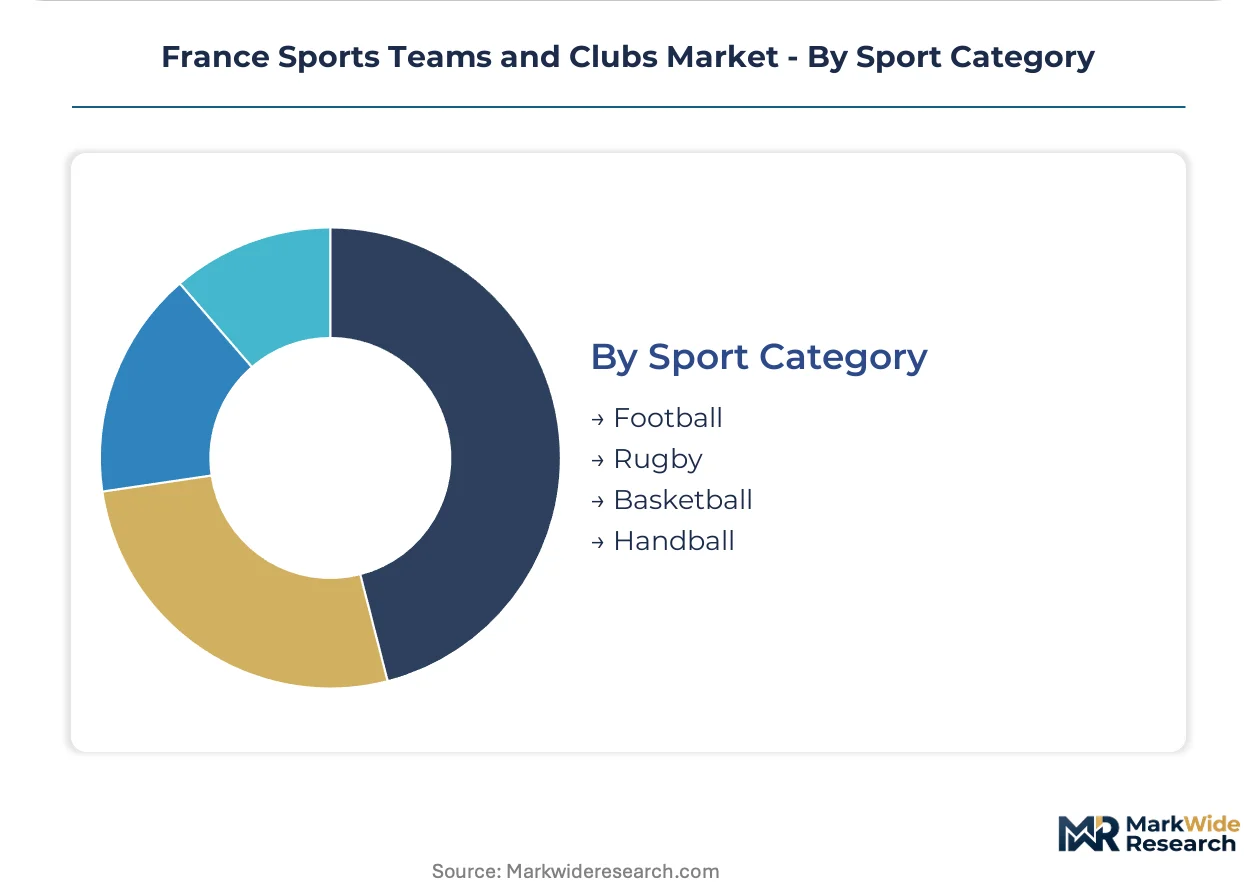
- Football:Ligue 1 and Ligue 2 operations command the full DNCG regulatory framework with stadium safety certifications under Ministry of Sport oversight. Domestic broadcast contracts and international streaming rights generate the dominant revenue share within French sports.
- Rugby:Top 14 clubs operate professional structures with distinct federation governance, where regional identity in Occitanie and Nouvelle-Aquitaine sustains strong season ticket loyalty despite lower media rights valuations.
- Basketball:LNB Pro A organizations leverage smaller arena footprints with lower capital intensity, concentrating in urban centers with strong youth participation pipelines.
- Handball:Starligue operations maintain professional standards with federation-controlled licensing, though commercial scale remains constrained by narrower international broadcast distribution.
Commanding revenue concentration: Football. Gaining share fastest: Basketball.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's sports clubs cluster where consumption density meets infrastructure investment capacity, creating sharp divides between metropolitan revenue engines and peripheral membership-based operations. Île-de-France and Auvergne-Rhône-Alpes absorb the dominant share of commercial capital, while secondary cities struggle with legacy stadium debt and constrained broadcast access.
Île-de-France
Corporate hospitality demand and international brand positioning drive revenue concentration in the Paris metropolitan cluster. The DNCG financial oversight framework applies full solvency requirements to professional clubs operating here. Stadium redevelopment into mixed-use entertainment districts at Parc des Princes and surrounding venues expands match-day monetization beyond seating capacity into retail and premium concessions.
Auvergne-Rhône-Alpes
Groupama Stadium anchors a regional commercial ecosystem where season ticket loyalty and corporate partnership tiers sustain professional football operations. The Ministry of Sport oversees safety certifications for infrastructure renewal across Lyon and surrounding municipalities. Mixed-use district construction around the stadium complex integrates hospitality, retail, and residential components that diversify revenue beyond fixture schedules.
Provence-Alpes-Côte d'Azur
Regional brand loyalty throughout southern France sustains supporter engagement despite lower international media visibility than Paris-based competitors. Olympique de Marseille exemplifies digital undermonetization, with subscription product development lagging behind physical attendance capture. The Orange Vélodrome renovation under municipal oversight demonstrates how public-private financing structures enable mid-tier market infrastructure modernization.
Hauts-de-France
Youth academy pipelines and player development economics concentrate in LOSC Lille's training infrastructure, generating transfer-market returns that subsidize operating budgets. The DNCG's mark-to-market accounting rules constrain balance sheet leverage for clubs in this region. Stadium capacity limitations in secondary cities restrict hospitality revenue expansion compared to Lyon and Paris benchmarks.
Nouvelle-Aquitaine
Amateur federation networks and municipal subsidies sustain lower-capital-intensity operations across southwestern France. FC Girondins de Bordeaux's historical commercial infrastructure illustrates legacy debt challenges from 1990s construction waves. Regional federation charters prioritize participation access over profit extraction, limiting professional broadcast rights penetration in this cluster.
France Sports Teams and Clubs Market Competitive Landscape
Top-tier vendors anchor the capital-intensive professional tier, while membership-sustained amateur clubs occupy the long tail of fragmented community participation. The market structure concentrates revenue and regulatory scrutiny in federation-licensed professional entities, with DNCG oversight creating licensing advantages for solvent organizations. Three archetypes dominate: global brand platforms with international streaming reach, regional loyalty anchors with underdeveloped digital channels, and disciplined player development specialists optimizing transfer-market economics. Competitive positioning hardens around stadium asset control and direct-to-consumer subscription architecture, with mixed-use district development and CSRD-compliant sustainability infrastructure emerging as differentiation vectors.
Within the global brand platform tier, Paris Saint-Germain exemplifies direct-to-consumer engagement architecture across international markets. Olympique de Marseille occupies a position as the regional loyalty anchor throughout Provence-Alpes-Côte d'Azur, with digital monetization white space remaining unexploited. LOSC Lille represents the disciplined development specialist archetype, sustaining operating margins through transfer-market positioning rather than stadium-scale hospitality infrastructure.
| Leading Market Players |
|---|
| Paris Saint Germain |
| AS Monaco FC |
| Olympique Lyon |
| Olympique de Marseille |
| Stade Rennais FC |
| LOSC Lille |
| Stade Reims |
| Toulouse FC |
| FC Nantes |
| Others |
Pricing and Supply Chain Analysis
CSRD sustainability disclosure mandates gate qualified supplier access and premium-tier pricing eligibility for French sports clubs. Clubs with verified environmental credentials command corporate hospitality premiums, while non-compliant organizations face sponsor budget exclusion and municipal financing restrictions.
Pricing Analysis
Pricing pressure intensifies in secondary city markets as DNCG solvency requirements compress debt-funded investment capacity. Three-tier pricing structure across premium hospitality, standard seating, and economy general admission dominates match-day revenue architecture. Price differentiation rests on stadium asset quality and CSRD compliance certification. Mid-tier clubs in Hauts-de-France exhibit highest price sensitivity due to transfer-market dependency and limited corporate sponsor density.
Supply Chain Analysis
Logistics and freight cost volatility affects merchandise and kit supply chains sourcing from Portugal, Turkey, and Southeast Asian manufacturing hubs. Raw material dependencies span technical polyester fabrics, sustainable cotton certifications, and RFID-enabled inventory tracking components. Single-source vulnerability concentrates in licensed apparel production where federation-controlled trademark enforcement limits supplier switching. Distribution runs through club-controlled retail channels, third-party e-commerce platforms, and stadium match-day concession operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stadium infrastructure capacity constraints in Paris and Lyon metropolitan clusters prop premium pricing power across the French sports clubs market. DNCG licensing bottlenecks limit professional tier expansion, sustaining incumbent revenue concentration.
For Market Incumbents: Lock in stadium asset control through long-term municipal lease renegotiations before CSRD disclosure mandates reshape public financing eligibility. Secure backward integration into hospitality service operations to capture margin leakage from third-party concessionaires. Counter emerging digital-native competitors by consolidating direct-to-consumer subscription architecture under unified fan identity platforms. For New Entrants and Emerging Players: The mid-market pricing gap between Olympique de Marseille's regional loyalty base and Paris Saint-Germain's global premium positioning offers white-space opportunity. Target Provence-Alpes-Côte d'Azur digital undermonetization through micro-subscription products for highlight access and gamified engagement outside match windows. Deploy federated youth academy partnerships as low-capital entry into player development economics. For Investors and Strategic Acquirers: DNCG enforcement actions against leveraged clubs are the leading indicator that distressed asset availability will expand across the analysis window. Long-term viability favors organizations with mixed-use district development rights and verified sustainability infrastructure. Monitor CSRD audit completion timelines as the signal for sponsor-eligibility tiering and corresponding valuation adjustments.| Strategic Initiative | Industry Significance |
|---|---|
| Stadium Mixed-Use Redevelopment | Transforms fixed-capacity venues into year-round entertainment districts with hospitality and retail revenue streams. |
| Direct-to-Consumer Platform Launch | Bypasses broadcast intermediaries to capture international fan subscription revenue detached from domestic attendance cycles. |
| Youth Academy Infrastructure Investment | Generates transfer-market returns through federation-chartered training centers with minimal player acquisition costs. |
| CSRD Compliance Certification | Unlocks corporate sponsor budgets tied to ESG mandates and municipal public funding access. |
| Integrated Data Architecture Deployment | Unifies ticketing, merchandise, and streaming interactions into single fan identity profiles for personalized pricing. |
Research Methodology
Multi-period observation of DNCG licensing decisions, stadium infrastructure investment flows, and broadcast rights allocation patterns anchored the trend analysis, supplemented by interviews with club financial directors, federation licensing officers, stadium operations managers, and corporate sponsorship executives. Secondary validation drew from LFP financial disclosures, Ministry of Sport safety certification records, municipal planning authority filings, and professional football league revenue distribution reports. Bottom-up club-level financial modeling triangulated against top-down federation revenue pool analysis.
Segment-weighting across organization type, revenue stream, membership model, and sport category dimensions structured the analytical framework. CAGRs were derived through regression analysis of historical revenue trajectories and projected infrastructure capacity expansion across the modeling period. Forecast inputs incorporated DNCG solvency ratio enforcement intensity, CSRD disclosure mandate rollout timelines, and digital subscription adoption curves in international fan markets.
Underlying measurement precision varies by segment; professional team financials carry tighter precision than amateur club operations due to audited disclosure requirements. Forecasts reflect assumptions about regulatory enforcement consistency and sponsor budget allocation to ESG-mandated partnerships. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
Padel Court Operator Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
Stadium and Arena Management Solution Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
North America Sports Team and Clubs Market