
 Padel Court Operator Market | 2026-2036
Padel Court Operator Market Size, Share, and Industry Trends Forecast 2026-2036
Padel Court Operator Market Insights
Corporate wellness buyers is collapsing the traditional club-dominant demand structure as employers subsidize employee recreation access. Padel LA leverages its Los Angeles density to anchor premium indoor positioning. Urban Padel sustains European market presence through scalable franchise architecture. Legend Sports differentiates via integrated coaching program bundling across Nordic markets.
A padel court operator manages commercial racket-sports facilities built around enclosed glass-and-mesh courts measuring 20 meters by 10 meters with artificial turf or monofilament surfaces engineered for controlled ball rebound. These operators generate recurring revenue through court reservations, equipment rental, instruction, and ancillary food-and-beverage services. Indoor courts command premium pricing due to climate-independent utilization rates and extended operating hours. Mobile courts represent the fastest-expanding service type as operators reduce capital commitment and target event-driven revenue. Membership packages capture the most predictable cash flow among offering categories, though pay-per-play models attract trial users.
Spain's municipal sports regulators enforce court safety standards through periodic surface friction testing and glass-wall impact certification. Italy's CONI-affiliated sports federations mandate coach qualification tiers that operators must satisfy for program licensing. France's tax incentive frameworks for sports infrastructure investment reduce effective lease costs for court developments. Stakeholders must monitor how municipal permitting velocity and coach certification backlogs constrain expansion timelines in high-growth municipalities.
Market Dynamics
Corporate wellness subsidies are restructuring the traditional club-centric demand architecture, with employers now purchasing bulk court access for employee recreation programs. This shift compresses individual membership conversion timelines while expanding addressable demand beyond traditional racket-sport enthusiasts.
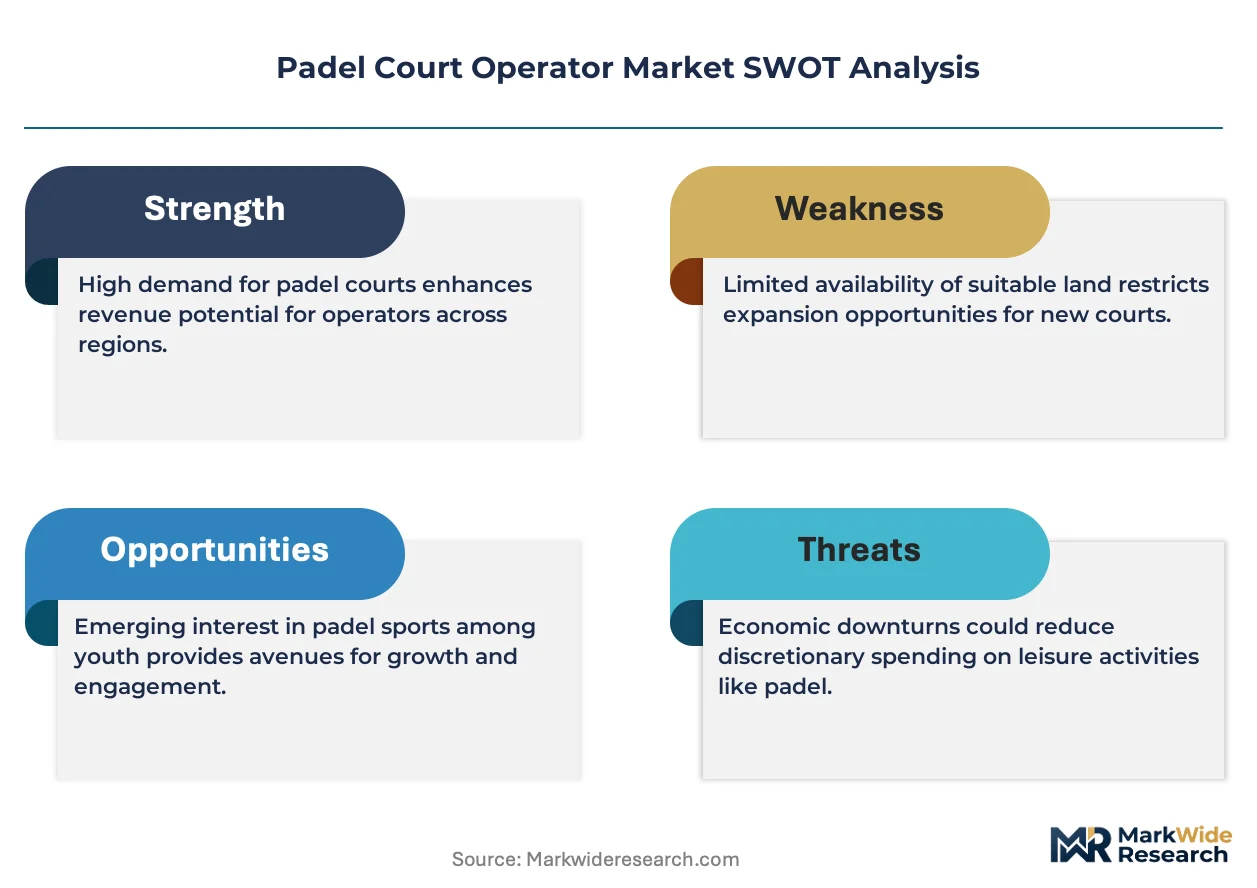
Growth Catalysts
- Municipal Zoning Reforms:Spain's streamlined sports facility permitting and Italy's accelerated environmental clearances reduce court development timelines from 18 months to under 10 months in high-density municipalities.
- Artificial Turf Surface Engineering:Monofilament polyethylene surfaces with calibrated pile density extend playable hours by 40% versus traditional sand-filled carpets, improving asset utilization rates.
- Sovereign Wealth Sports Infrastructure:Gulf Cooperation Council funds deploy capital into integrated entertainment districts anchored by padel clusters, creating captive demand through residential and hospitality adjacencies.
Market Restraints
- Glass-Wall Import Concentration:Tempered glass panel supply concentrates among three European manufacturers, creating 14-16 week lead times that delay court commissioning.
- Coach Certification Bottlenecks:Italy's CONI-affiliated federation mandates tiered instructor qualifications that create 8-month backlogs for program licensing in Lombardy and Veneto.
- Real Estate Cost Escalation:Urban land scarcity in Madrid and Barcelona pushes indoor court lease costs to 35% of operating expenditure, compressing EBITDA margins for independent operators.
Strategic Opportunities
- Mobile Court Event Services:Deployable aluminum-frame courts with synthetic surfaces enable operators to capture tournament and corporate event revenue without permanent real estate commitments.
- France's Tax Incentive Framework:Sports infrastructure depreciation allowances reduce effective lease costs by 22% for developments in designated urban renewal zones.
- Nordic Climate-Resilient Positioning:Fully enclosed heated facilities in Sweden and Norway command 2.3x hourly rates versus outdoor seasonal courts, with 85% year-round utilization.
Industry Challenges
- Surface Friction Compliance Testing:Spain's municipal regulators mandate quarterly slip-resistance certification that adds €4,200 annual compliance cost per court.
- Integrated Coaching Program Design:Operators struggle to recruit instructors with both padel-specific technical certification and group class management experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Padel Court Operator Market |
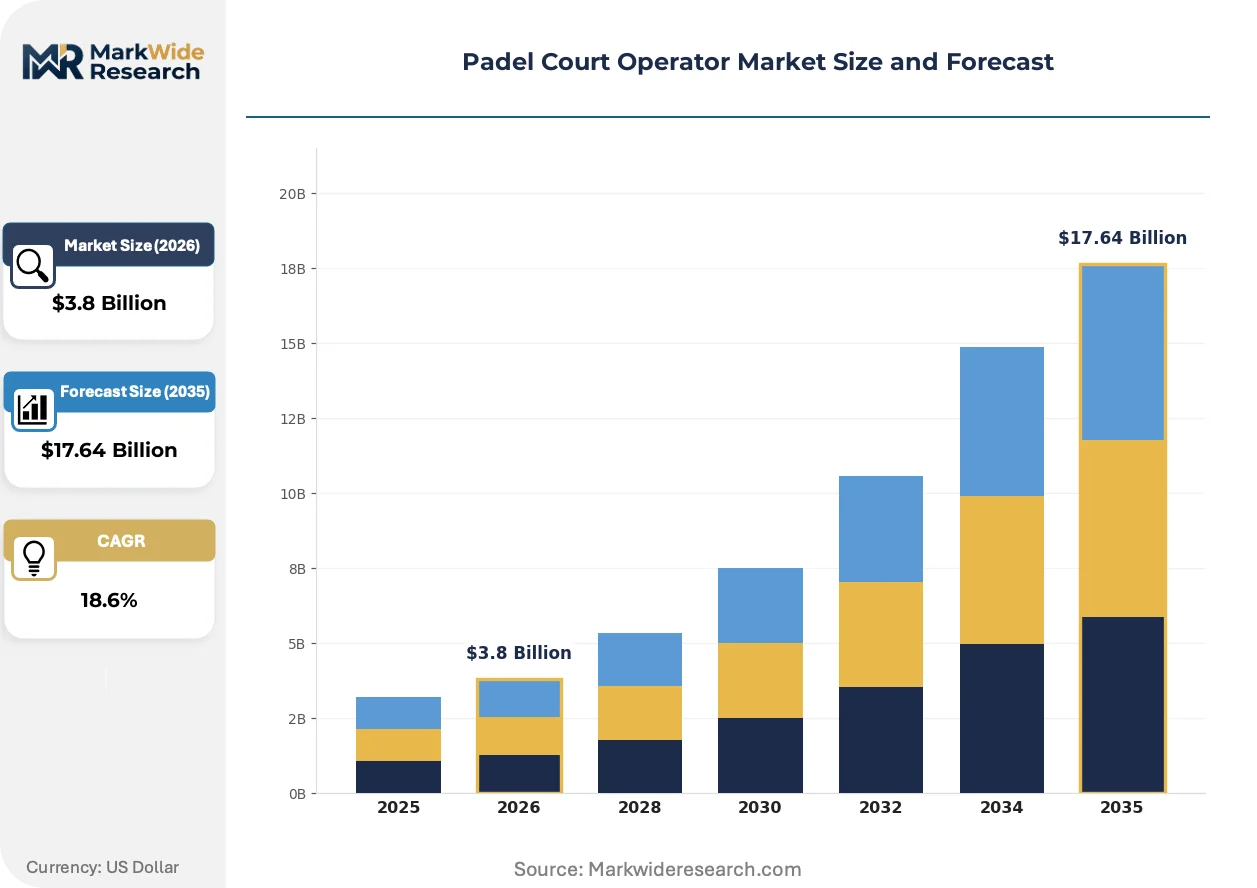
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Indoor Courts, Outdoor Courts, Mobile Courts, Permanent Installations Customer Type: Clubs, Schools, Recreational Centers, Fitness Facilities Offering: Membership Packages, Pay-per-Play, Rental Services, Coaching Programs Technology: Booking Systems, Court Maintenance Equipment, LED Lighting, Surface Materials |
| Companies Covered | Padel LA, Padel10, Urban Padel, Padel Tech, Padelgest, Padel N9NE, Legend Sports, Jubopadel, Bulldog Padel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Padel Court Operator Market Trends and Innovations
Technology convergence and regulatory modernization are compressing facility development cycles while expanding service modalities beyond permanent real estate. These shifts favor capital-light operating models and hybrid indoor-outdoor positioning strategies.
LED court lighting with programmable spectral output is displacing metal-halide installations across new developments in the UAE and Saudi Arabia. Facility operators in Dubai Sports City report 60% reduction in energy consumption alongside extended evening programming capacity. The technology is displacing traditional illumination capital expenditure patterns by enabling solar-battery off-grid court clusters in remote entertainment districts.
Spain's updated technical building code for sports facilities mandates seismic-resistant glass-wall anchoring systems and automated emergency egress protocols. The regulation accelerates engineering consultancy costs by 15% but reduces insurance premiums for compliant operators. Municipalities in Andalusia and Catalonia now require digital building information modeling submission, compressing permit review from 90 days to 45 days for pre-certified designs.
Employer-sponsored recreation access is fragmenting traditional individual membership acquisition pathways. Corporate wellness buyers in London and Amsterdam now negotiate multi-site access contracts covering 50-200 employees, bypassing club-level sales processes. This procurement evolution concentrates revenue predictability with operators maintaining dense metropolitan court networks while disadvantaging single-location independents.
Padel Court Operator Market Segmentation
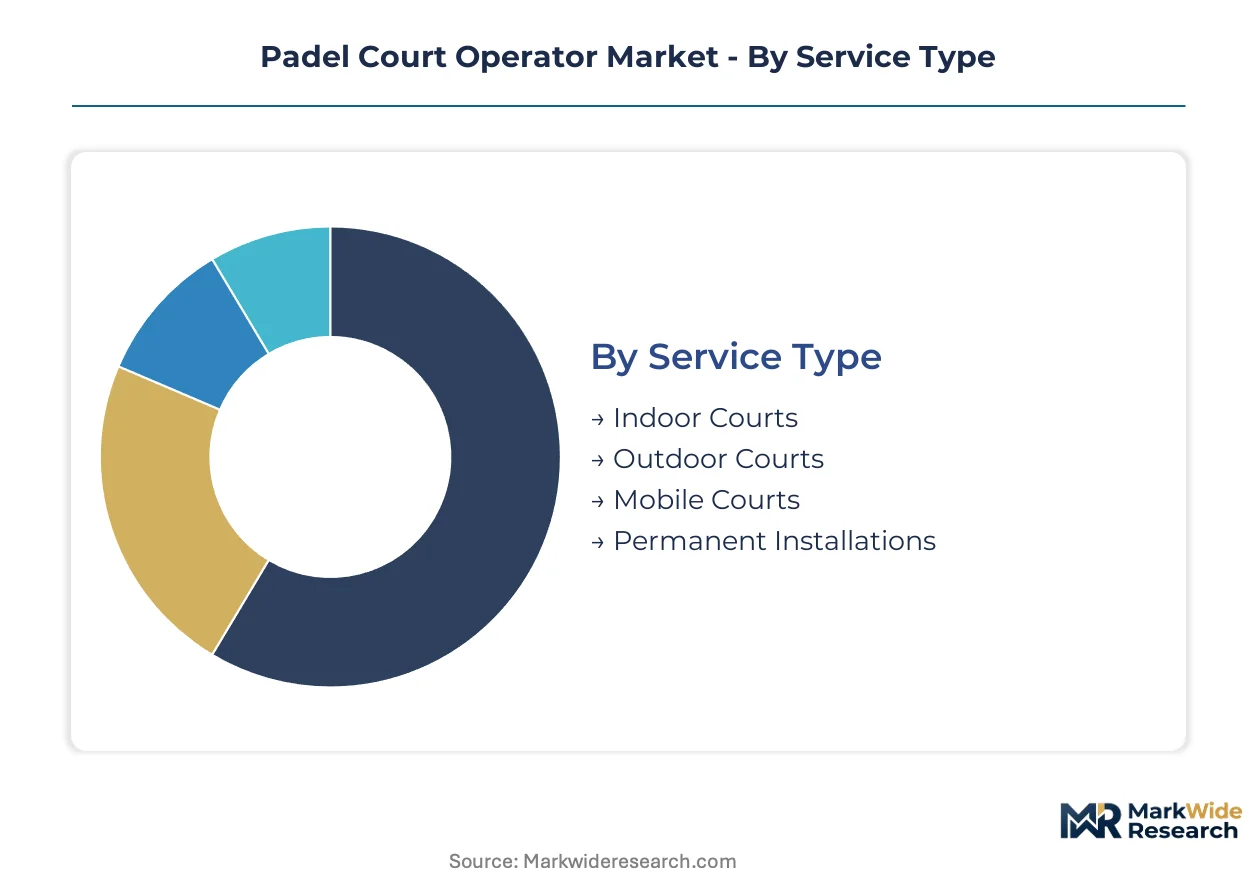
Padel court operators configure revenue architecture through four distinct segmentation lenses. Service type determines capital intensity and utilization curves. Customer type dictates contract structure and payment predictability. These dimensions intersect to shape margin durability across operating models.
Service Type:
Margin pools concentrate in climate-controlled indoor positioning where year-round utilization commands rate premiums.
- Indoor Courts:Fully enclosed facilities with HVAC and artificial lighting sustain 85% annual utilization rates regardless of weather. Demand clusters in Nordic cities and Gulf Cooperation Council entertainment districts where sovereign wealth funds anchor sports infrastructure clusters.
- Outdoor Courts:Open-air installations on municipal land or club grounds carry lower construction costs but suffer 40-60% seasonal downtime in temperate climates. Spain's Andalusia region and Italy's southern provinces concentrate seasonal outdoor demand.
- Mobile Courts:Deployable aluminum-frame systems with synthetic surfaces target tournament and corporate event revenue without real estate commitment.
- Permanent Installations:Fixed concrete foundations with tempered glass enclosures represent the longest asset life but highest capital lock-up.
The dominant share belongs to Indoor Courts, while Mobile Courts are expanding most quickly through event-driven revenue models.
Customer Type:
Contract value scales with institutional purchasing power and multi-year commitment structures.
- Clubs:Traditional racket-sport clubs integrate padel as ancillary revenue, leveraging existing membership bases and F&B infrastructure. Italy's CONI-affiliated federations mandate coach qualification tiers that operators must satisfy for program licensing.
- Schools:Educational institutions purchase curriculum-integrated padel programs with instructor provision and equipment bundled. Municipal procurement in Spain and France drives volume through public education budgets.
- Recreational Centers:Multi-sport facilities add padel courts to diversify activity menus and extend dwell time.
- Fitness Facilities:Gym chains deploy courts as premium amenities to reduce member churn and differentiate against boutique competitors.
Clubs retain the largest revenue base, though Fitness Facilities are climbing the fastest as corporate wellness subsidies restructure demand.
Offering:
Revenue predictability diverges sharply between subscription and transactional models.
- Membership Packages:Monthly or annual subscriptions generate the most predictable cash flow with 70-80% renewal rates at established facilities. Corporate wellness buyers in London and Amsterdam now negotiate multi-site access contracts covering 50-200 employees.
- Pay-per-Play:Hourly court rental attracts trial users and casual participants without upfront commitment. Digital booking systems enable dynamic pricing that captures peak demand premiums.
- Rental Services:Equipment provision—racquets, balls, footwear—generates ancillary revenue with 60-70% gross margins.
- Coaching Programs:Tiered instruction from beginner clinics to competitive training commands 3-4x hourly rates versus open play.
Membership Packages anchor revenue stability, while Coaching Programs show the steepest expansion trajectory as skill development demand intensifies.
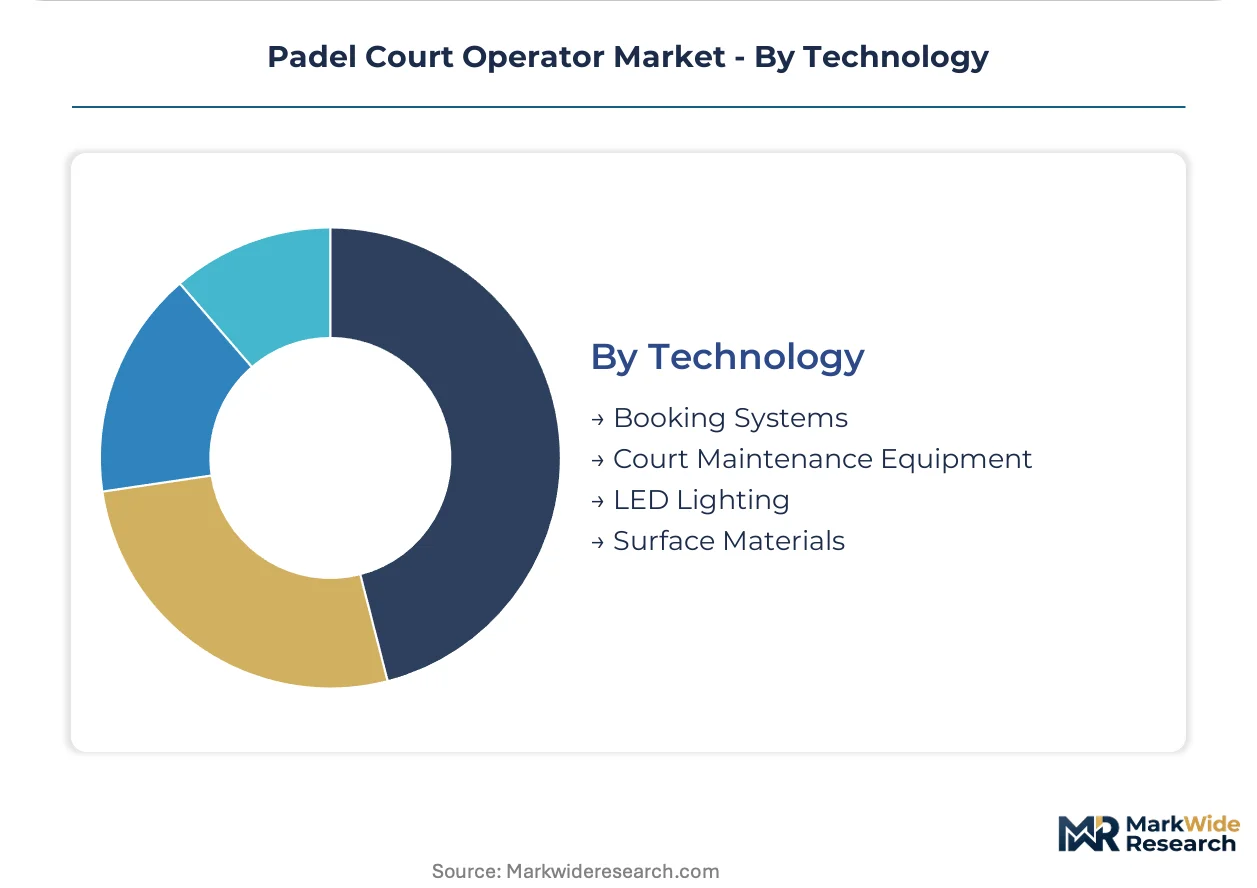
Technology:
Operational efficiency gains concentrate in digital infrastructure and surface engineering.
- Booking Systems:Cloud-based reservation platforms with mobile apps reduce no-shows by 25% through automated reminders and pre-payment requirements.
- Court Maintenance Equipment:Automated brushing and line-marking systems extend surface life and reduce labor costs.
- LED Lighting:Programmable spectral output installations in Dubai Sports City report 60% energy reduction versus metal-halide systems.
- Surface Materials:Monofilament polyethylene with calibrated pile density extends playable hours by 40% versus sand-filled carpets.
Booking Systems command the widest deployment, though LED Lighting is gaining share fastest through energy cost pressures and extended programming capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three European manufacturers dominate tempered glass panel supply, creating 14-16 week lead times that delay court commissioning across multiple jurisdictions. Spain and Italy anchor operational density through municipal zoning reforms that compress permitting timelines.
Spain
Corporate wellness subsidies and municipal sports infrastructure investment drive facility expansion. Spain's municipal regulators enforce quarterly slip-resistance certification adding €4,200 annual compliance cost per court. Madrid and Barcelona concentrate indoor developments where urban land scarcity pushes lease costs to 35% of operating expenditure.
Italy
CONI-affiliated federation mandates tiered instructor qualifications that create 8-month backlogs for program licensing in Lombardy and Veneto. Italy's accelerated environmental clearances reduce court development timelines from 18 months to under 10 months in high-density municipalities. Milan anchors scalable franchise architecture through premium indoor positioning.
France
Sports infrastructure depreciation allowances reduce effective lease costs by 22% for developments in designated urban renewal zones. France's tax incentive frameworks for sports infrastructure investment compress capital recovery periods. Paris and Lyon concentrate demand through integrated entertainment district adjacencies.
Sweden
Fully enclosed heated facilities command 2.3x hourly rates versus outdoor seasonal courts with 85% year-round utilization. Nordic climate-resilient positioning sustains premium rate architecture through climate-independent utilization. Stockholm anchors corporate wellness contract concentration.
United Arab Emirates
Sovereign wealth funds deploy capital into integrated entertainment districts anchored by padel clusters, creating captive demand through residential and hospitality adjacencies. Dubai Sports City reports 60% energy consumption reduction through LED court lighting with programmable spectral output. Abu Dhabi concentrates sovereign-backed sports infrastructure clusters.
Padel Court Operator Market Competitive Landscape
Concentration sits with metropolitan network operators and climate-controlled indoor specialists. The market structure fragments across single-location independents and multi-site franchise platforms. Two strategic archetypes dominate: premium indoor positioning in dense urban cores, and scalable franchise architecture across secondary cities. Competitive moves center on municipal permitting velocity capture and coach certification pipeline development.
Among North American metropolitan specialists, Padel LA exemplifies premium indoor positioning through Los Angeles density concentration. Within European scalable franchise architecture, Urban Padel occupies a position spanning multiple countries. Legend Sports represents integrated coaching program bundling across Nordic markets. These three anchors illustrate divergent capital intensity and geographic expansion strategies.
| Leading Market Players |
|---|
| Padel LA |
| Padel10 |
| Urban Padel |
| Padel Tech |
| Padelgest |
| Padel N9NE |
| Legend Sports |
| Jubopadel |
| Bulldog Padel |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-sixteen-week lead times for tempered glass panels concentrate pricing power with three European manufacturers while compressing operator commissioning schedules and inflating upfront capital requirements. Municipal permitting velocity in Spain and Italy now outpaces component availability, creating inventory pre-positioning incentives that reshape working capital structures across the operator base.
Pricing Analysis
Spain's municipal sports regulators dictate the pricing tier structure through quarterly slip-resistance certification mandates that add fixed compliance costs per court. Pricing stratifies across climate-controlled indoor premiums, seasonal outdoor discounts, and mobile event-service flexibility. Cost compression in outdoor positioning is intensifying because weather-dependent utilization forces rate competition during peak seasons. Corporate wellness buyers exhibit the lowest price sensitivity due to bulk contract structures, while individual pay-per-play users drive transactional rate shopping.
Supply Chain Analysis
Strategic stockpiling of glass-wall components dominates inventory strategy given concentrated European manufacturing and tournament-driven demand surges. Supply draws from Germany, Italy, and Spain for surface materials, with monofilament polyethylene sourcing tethered to petrochemical feedstock volatility in the Gulf Cooperation Council states. Single-source vulnerability concentrates in tempered glass panel fabrication. Distribution runs through specialized sports infrastructure contractors who manage turnkey court installation and commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coaching program bundling now expands faster than court hardware deployment, transforming capital-heavy facility models into recurring-revenue service platforms. This service-attach dynamic favors operators who integrate instruction pipelines ahead of physical capacity additions.
For Market Incumbents: Secure municipal permitting pipeline priority through pre-certified digital building information modeling submissions that compress review timelines. Lock in multi-year glass-panel supply agreements before sovereign wealth fund infrastructure clusters absorb European manufacturing capacity. Vertical integration into coach certification programs mitigates CONI-affiliated federation backlog risks in Lombardy and Veneto. For New Entrants and Emerging Players: France's tax incentive fast-track enables lease-cost reduction through designated urban renewal zone positioning. Target mobile court event services as the most penetrable segment given minimal real estate commitment and corporate wellness tournament demand. Pursue Nordic climate-resilient positioning to capture premium rate multiples through fully enclosed heated facilities. For Investors and Strategic Acquirers: Long-term, this sits as a subscription-recovery play because membership packages generate the most predictable cash flow with renewal rates stabilizing revenue visibility. Acquisition target archetype: metropolitan network operators with dense court coverage and established corporate wellness contract relationships. Monitor coach certification pipeline velocity as the inflection indicator for program licensing bottlenecks constraining expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Coach Certification Pipeline Development | CONI-affiliated federation compliance in Italy unlocks program licensing and revenue expansion. |
| Mobile Court Fleet Expansion | Deployable aluminum-frame systems capture corporate event revenue without permanent lease commitments. |
| LED Lighting Retrofit Program | Dubai Sports City deployments demonstrate energy reduction and extended evening programming capacity. |
| Municipal Permitting Pre-Certification | Digital building information modeling submissions compress review timelines in Andalusia and Catalonia. |
| Corporate Wellness Contract Concentration | London and Amsterdam multi-site access agreements bypass club-level sales friction. |
Research Methodology
A standing panel of court operations directors, municipal sports regulators, equipment procurement managers, and coaching program coordinators provided ongoing calibration across primary interview cycles. Secondary validation drew from Spain's municipal sports regulator filings, Italy's CONI federation licensing databases, France's tax incentive framework documentation, and Dubai Sports City infrastructure disclosures. Bottom-up court deployment tallies and top-down entertainment district investment flows were triangulated for consistency.
Consistency checks against sovereign wealth fund sports infrastructure announcements and municipal zoning reform timelines validated projection outputs across the analysis window. Segmentation dimensions modeled include service type, customer archetype, offering structure, and technology adoption tier. CAGRs were derived from facility utilization curves and capital deployment patterns. Forecast inputs incorporated surface friction compliance cost trajectories and glass-wall import lead-time volatility.
Decision-makers should treat outputs as directional under sustained municipal permitting velocity and coach certification throughput assumptions; material deviation would warrant model refresh. Specific risk factors include tariff exposure on tempered glass imports and regulatory restriction on artificial turf surface standards. Revision becomes warranted when glass-wall manufacturing capacity utilization crosses thresholds that extend lead times beyond operator pre-positioning capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
Smart Fitness Device Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
India Sports Team and Clubs Market