
 UK Sports Promoters Market | 2026-2036
UK Sports Promoters Market Size, Share, and Industry Trends Forecast 2026-2036
UK Sports Promoters Market Insights
The UK sports promotion landscape is repositioning around a widening gap between premium experiential packages and standard ticket commodities. Matchroom Sport leverages its broadcast-first model to capture higher-margin pay-per-view audiences, while The Jockey Club sustains its dominance across heritage racing venues with members-only hospitality tiers. Queensberry Promotions anchors its growth in boxing's resurgent pay-per-view segment, competing directly with Boxxer's younger-demographic streaming partnerships.
Sports promoters are commercial entities that secure venue rights, negotiate athlete or team contracts, and orchestrate event production to generate ticket, broadcast, and sponsorship revenue. Their operations hinge on multi-year venue licensing agreements and real-time demand pricing algorithms that optimize yield per seat. Event management and sponsorship activation services generate the deepest margin pools, whereas pure consultancy engagements face compression from in-house brand teams. Ticket sales remain the largest revenue stream by volume, though merchandise and advertising are expanding faster as clubs build direct-to-fan digital channels.
The UK's Competition and Markets Authority scrutinizes ticketing platform fees under consumer protection mandates, while the Information Commissioner's Office enforces GDPR compliance on fan data monetization. These frameworks elevate compliance costs but also create barriers against unlicensed secondary market operators. Stakeholders must track how the Digital Markets, Competition and Consumers Act reshapes platform fee structures and direct sales obligations.
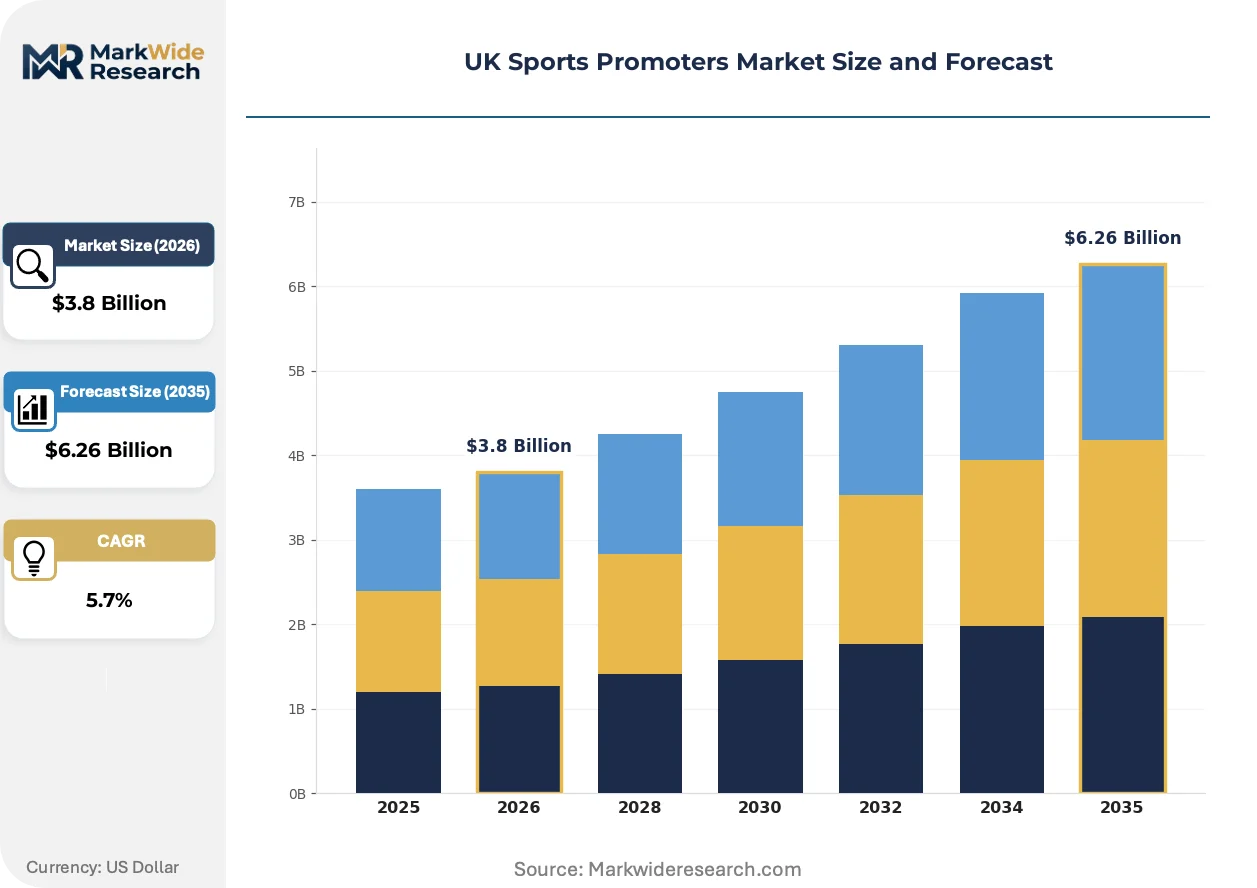
Market Dynamics
The UK's Digital Markets, Competition and Consumers Act is forcing ticketing platforms to restructure fee disclosures and direct sales obligations, compressing intermediary margins while elevating compliance burdens for promoters negotiating venue access.
Growth Catalysts
- Corporate hospitality recovery:Live-event sponsorship budgets are rebounding post-pandemic, with premium experiential packages commanding stronger uptake across London's venue ecosystem and Manchester's emerging infrastructure.
- Pay-per-view streaming expansion:Boxing and combat sports promoters are capturing higher-margin digital audiences through broadcast-first models that bypass traditional gate-revenue dependence.
- GDPR-compliant data monetization:The Information Commissioner's Office enforcement framework creates barriers against unlicensed secondary market operators, protecting licensed promoters' fan database value.
Market Restraints
- Venue licensing concentration:Multi-year agreements with heritage racing estates and Premier League stadia limit new entrant access to calendar slots and prime locations.
- Broadcast rights inflation:Escalating fees for exclusive pay-per-view and streaming carriage compress promoter margins even as audience reach expands.
- Secondary market fragmentation:Unlicensed ticket resale platforms persist despite regulatory pressure, eroding primary market yield and fan trust.
Strategic Opportunities
- Scotland and Wales venue development:Underpenetrated regional markets outside London and Manchester present first-mover advantages for promoters establishing recurring event calendars.
- Direct-to-fan digital channels:Clubs and rights holders are building proprietary membership platforms that capture merchandise and advertising revenue streams previously ceded to intermediaries.
- Heritage venue hospitality tiers:Members-only experiences at established racing and cricket grounds offer pricing power insulated from standard ticket commodity pressures.
Industry Challenges
- Real-time yield optimization:Promoters face execution complexity implementing demand-pricing algorithms across fragmented seat inventory while maintaining fan satisfaction.
- Cross-platform data integration:Synchronizing fan profiles across ticketing, broadcast, and merchandise systems requires capital investment in legacy infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Sports Promoters Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultancy, Event Management, Sponsorship Activation, Marketing Client Type: Professional Teams, Clubs, Athletes, Corporations Revenue Stream: Ticket Sales, Merchandise, Advertising, Sponsorship Engagement Model: Direct Deals, Brokers, Partnerships, Affiliations |
| Companies Covered | Matchroom Sport, Queensberry Promotions, Premier League, Rugby Football Union (RFU), The Jockey Club, Boxxer, Sportfive, IMG, Wasserman, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Sports Promoters Market Trends and Innovations
Digital distribution channels are compressing traditional gate-to-broadcast windows, with promoters resequencing revenue capture around pre-event engagement rather than matchday attendance alone.
Dynamic pricing algorithms is overtaking static tier structures in venue seat allocation. Promoters at Wembley Stadium and Old Trafford deploy machine-learning models that adjust prices hourly based on inventory velocity and competitor events. This technology is compressing the margin gap between sellouts and soft demand nights that previously eroded profitability.
The Digital Markets, Competition and Consumers Act mandates fee transparency and restricts platform self-preferencing. Secondary ticketing marketplaces must now disclose total costs upfront and grant promoters direct sales alternatives. Small-to-mid-tier event organizers gain leverage in platform negotiations previously dominated by volume-based gatekeepers.
Fan purchasing patterns are fragmenting across subscription, single-event, and hybrid membership models. Younger demographics in combat sports favor streaming bundles over venue attendance, while heritage racing audiences retain premium hospitality commitment. Manchester's emerging venue cluster shows this divergence most acutely, with promoters running parallel pricing architectures for the same fixture.
UK Sports Promoters Market Segmentation
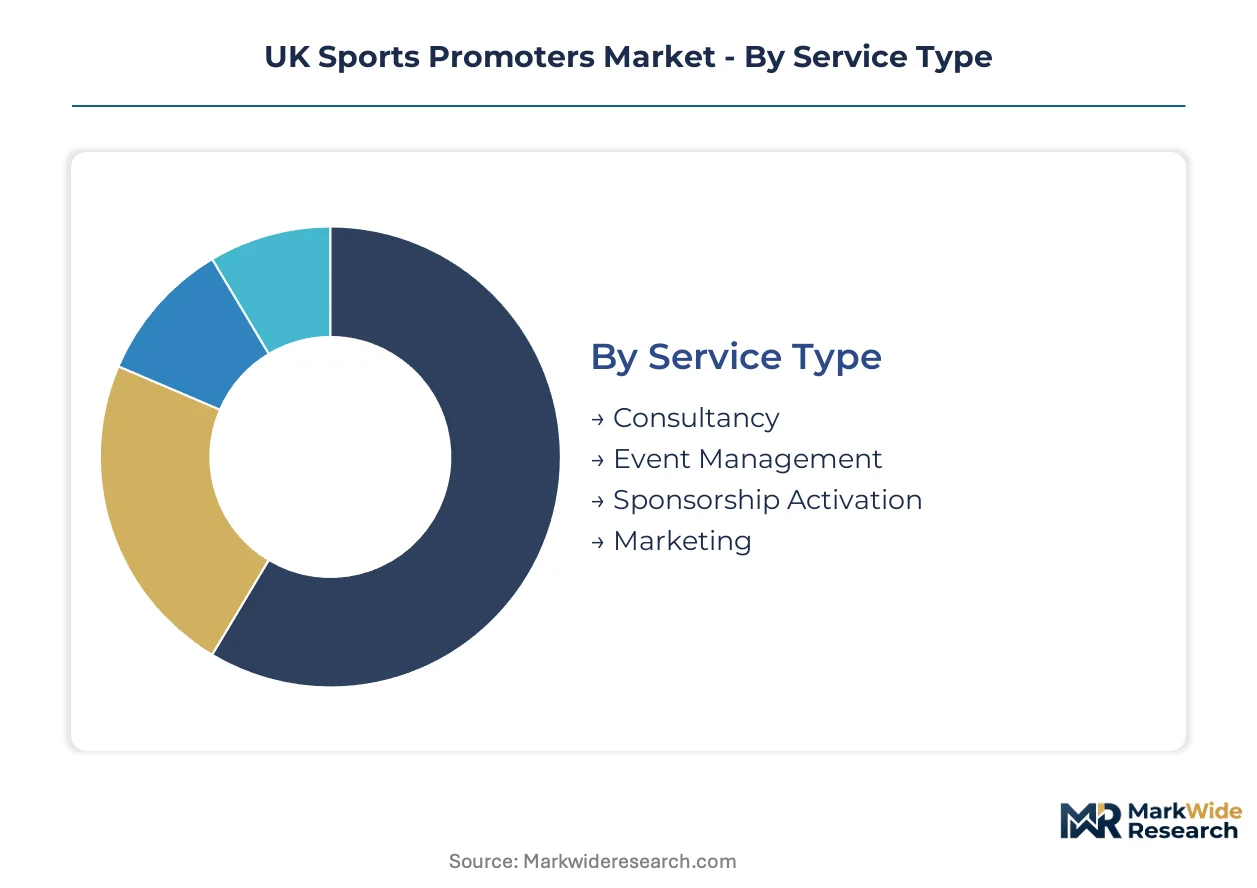
Promoters in the UK market configure their operations around distinct service portfolios, client relationships, and revenue architectures. Segmentation reveals how margin concentration varies across event production depth versus advisory-only engagements, and whether revenue derives from gate receipts or recurring sponsorship contracts.
Service Type:
Cost tiers separate promoters who own event infrastructure from those renting capabilities on a project basis.
- Event Management:Full-cycle production encompassing venue logistics, athlete contracting, and broadcast coordination. Demand clusters with boxing and combat sports fixtures in Manchester's emerging venue cluster, where promoters capture gate-plus-ancillary revenue streams rather than flat fees.
- Sponsorship Activation:Brand integration services spanning hospitality suite design, on-ground experiential zones, and digital content licensing. Corporate hospitality budgets at London's heritage racing estates sustain premium pricing power unavailable to standard ticket promoters.
- Consultancy:Advisory-only engagements covering market entry strategy, rights valuation, and regulatory navigation. Compression from in-house brand teams at Premier League clubs has pushed independent consultants toward niche federation mandates.
- Marketing:Campaign execution across paid media, organic social, and influencer networks. The Jockey Club and comparable heritage operators build proprietary fan databases that reduce reliance on external marketing vendors.
Volume sits with Event Management; growth tilts toward Sponsorship Activation.
Client Type:
Application complexity escalates with the number of stakeholder layers a promoter must reconcile.
- Professional Teams:Multi-year representation agreements covering fixture scheduling, commercial rights bundling, and venue licensing. Premier League football clubs in London and Manchester demand integrated broadcast-plus-gate optimization that smaller promoters cannot resource.
- Corporations:Bespoke property creation for brand-owned events rather than third-party rights acquisition. Financial services and automotive sectors dominate corporate hospitality procurement at Wembley Stadium and Twickenham.
- Clubs:Lower-division football, rugby, and cricket entities lacking in-house commercial departments. Scotland and Wales present underpenetrated addressable markets where first-mover promoters establish recurring calendar relationships.
- Athletes:Individual representation spanning contract negotiation, personal brand licensing, and appearance fee optimization. Boxing promoters at Matchroom Sport and Queensberry Promotions structure athlete deals around pay-per-view upside participation.
Professional Teams generate the deepest revenue per engagement; Athletes represent the steepest expansion trajectory as individual rights unbundle from collective bargaining.
Revenue Stream:
Margin profiles diverge sharply between one-time transactional capture and recurring relationship-based income.
- Ticket Sales:Primary market distribution through proprietary platforms and licensed ticketing partners. The Digital Markets, Competition and Consumers Act mandates fee transparency that compresses intermediary margins while elevating direct sales obligations for promoters.
- Sponsorship:Multi-year brand partnerships integrating naming rights, kit placement, and hospitality access. Live-event sponsorship budgets have rebounded post-pandemic, with premium experiential packages commanding stronger uptake.
- Merchandise:Direct-to-fan retail through proprietary e-commerce and matchday concessions. Clubs building captive digital channels capture apparel and accessory revenue previously ceded to wholesale intermediaries.
- Advertising:Stadium digital signage, program placement, and broadcast integration. Dynamic inventory management allows real-time yield adjustment based on fixture significance and competitor event scheduling.
Sponsorship delivers the most predictable cash flows; Merchandise is climbing the fastest as clubs invest in membership platform infrastructure.
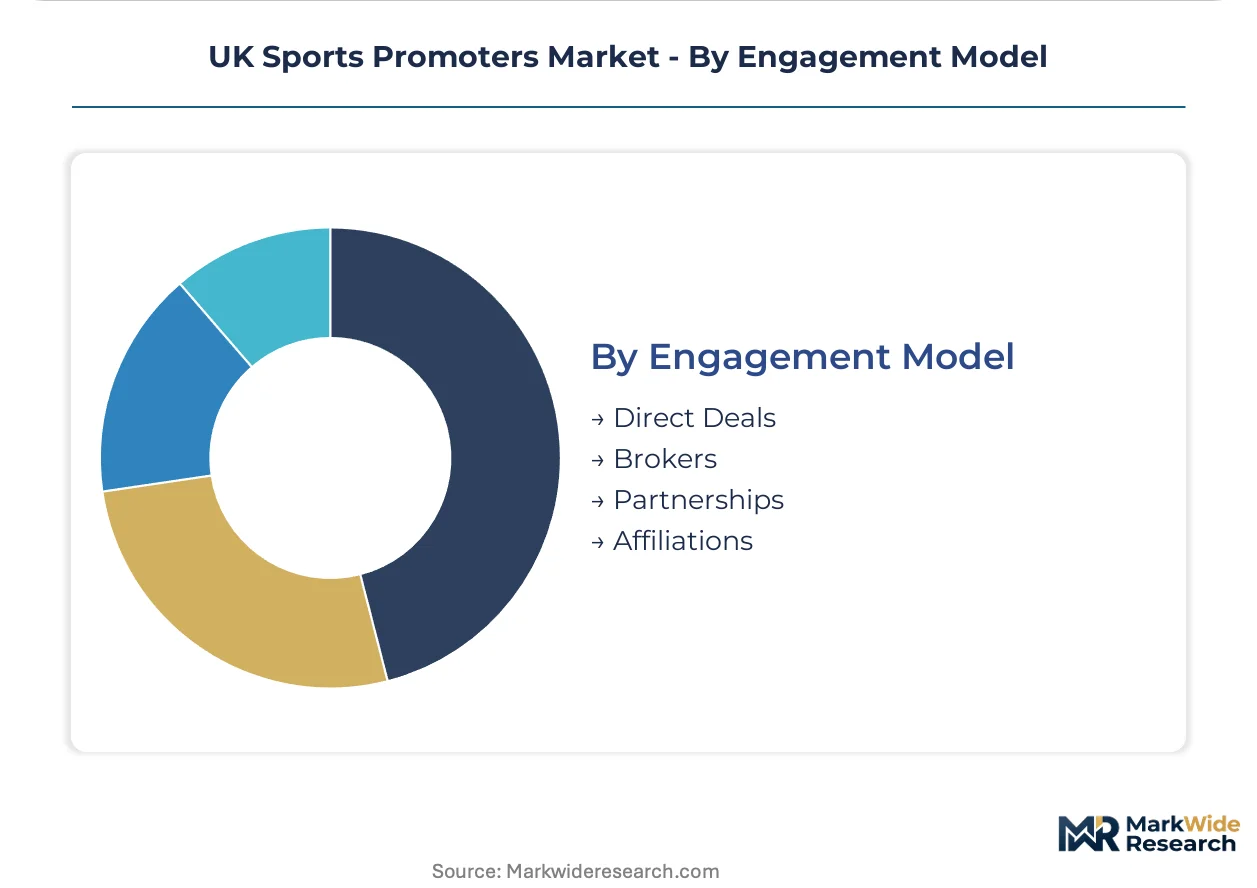
Engagement Model:
Supply concentration among platform gatekeepers determines which promoters retain pricing autonomy.
- Direct Deals:Promoter-to-venue or promoter-to-rights-holder contracting without intermediary facilitation. Large-cap operators at Wembley and Old Trafford leverage volume to secure exclusive calendar slots unavailable to smaller competitors.
- Partnerships:Formal alliances with complementary service providers spanning catering, security, and broadcast production. Manchester's emerging venue cluster shows particular density of partnership-based event assembly.
- Brokers:Intermediary-facilitated access to venue inventory and athlete availability. Secondary market fragmentation persists despite Information Commissioner's Office enforcement, eroding primary market yield.
- Affiliations:Loose network relationships enabling geographic or disciplinary expansion without capital commitment. Scotland and Wales venue development relies heavily on affiliation structures for promoter market entry.
Direct Deals anchor revenue concentration; Partnerships are gaining share fastest as operational complexity exceeds single-firm capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's premium venue ecosystem anchors UK sports promotion activity, with Wembley Stadium and Twickenham commanding the deepest corporate hospitality spend and broadcast-first event pipelines.
London and the Southeast
Corporate hospitality budgets concentrate at heritage racing estates and Premier League stadia, with financial services and automotive sectors driving premium experiential package procurement. The Digital Markets, Competition and Consumers Act mandates fee transparency for ticketing platforms operating across Greater London. Promoters at Wembley Stadium deploy machine-learning pricing models that adjust seat values hourly based on inventory velocity.
North England
Manchester's emerging venue infrastructure attracts boxing and combat sports fixtures seeking pay-per-view streaming expansion outside saturated London calendar slots. The Information Commissioner's Office enforces GDPR compliance on fan data monetization across northern promoter operations. Manchester Arena and surrounding hospitality clusters show parallel pricing architectures for streaming-bundled younger demographics alongside traditional gate audiences.
Midlands
Heritage racing venues sustain members-only hospitality tiers insulated from standard ticket commodity pressures, with The Jockey Club's operational footprint concentrated across Warwickshire and Gloucestershire estates. Competition and Markets Authority scrutiny of secondary market operators protects licensed promoters' primary market yield. Promoters leverage multi-year venue licensing agreements at Cheltenham and Stratford-upon-Avon to secure recurring calendar relationships.
Scotland
Underpenetrated regional markets present first-mover advantages for promoters establishing recurring event calendars in football and rugby fixtures outside England's dominant venue concentration. The UK's consumer protection mandates apply uniformly, elevating compliance costs but creating barriers against unlicensed secondary market entrants. Glasgow and Edinburgh venue clusters show early partnership-based event assembly density as operational complexity exceeds single-firm capabilities.
Wales
Lower-division football and rugby entities lacking in-house commercial departments create addressable markets for affiliation-structured promoter entry without capital commitment. Regulatory frameworks from the Competition and Markets Authority and Information Commissioner's Office extend fully to Welsh operations. Cardiff's Principality Stadium anchors national team fixtures while regional promoters target club-level recurring revenue through direct-to-fan digital channel development.
UK Sports Promoters Market Competitive Landscape
Premium-margin players sit above commodity-margin players across broadcast rights ownership and venue licensing depth, with tiered concentration reflecting multi-year estate agreements versus project-based rental operations. The vendor base stratifies between heritage venue operators with captive hospitality infrastructure and digital-native promoters capturing pay-per-view upside. Three archetypes dominate: broadcast-first aggregators, estate-anchored heritage operators, and athlete-centric representation specialists. Competitive moves concentrate on exclusive venue calendar locking and proprietary fan database construction through direct-to-fan platform investment.
Within the heritage estate tier, The Jockey Club represents multi-venue hospitality integration, while Matchroom Sport and Queensberry Promotions exemplify broadcast-first models capturing higher-margin pay-per-view audiences. These three entities occupy distinct competitive positions: estate-anchored pricing power versus digital distribution scale versus athlete contract upside participation. Each archetype faces pressure from the Digital Markets, Competition and Consumers Act's restructuring of platform fee disclosures and direct sales obligations.
| Leading Market Players |
|---|
| Matchroom Sport |
| Queensberry Promotions |
| Premier League |
| Rugby Football Union (RFU) |
| The Jockey Club |
| Boxxer |
| Sportfive |
| IMG |
| Wasserman |
| Others |
Pricing and Supply Chain Analysis
Corporate hospitality procurement consolidation at heritage racing estates and Premier League stadia is forcing promoters to restructure venue access negotiations and absorb elevated compliance costs from the Digital Markets, Competition and Consumers Act, compressing intermediary margins while elevating direct sales infrastructure investment.
Pricing Analysis
Yield-per-seat optimization anchors pricing architecture across Wembley Stadium and Old Trafford, where machine-learning models adjust values hourly based on inventory velocity and competitor event scheduling. Three-tier pricing structure across premium, standard, and economy levels separates members-only hospitality tiers at The Jockey Club from streaming-bundled younger demographics in Manchester's combat sports fixtures. Cost compression in standard ticket commodities is intensifying because unlicensed secondary market platforms erode primary market yield. Corporate buyers at Twickenham and Cheltenham show lowest price sensitivity; lower-division football clubs in Wales and Scotland face acute budget constraints.
Supply Chain Analysis
Technical crew and event production talent availability in Greater London, Greater Manchester, and the West Midlands determines promoter capacity to execute simultaneous fixtures across fragmented calendars. Raw material and service inputs draw from broadcast equipment leasing, temporary infrastructure fabrication, and hospitality catering procurement. Single-source vulnerability concentrates in exclusive venue licensing agreements with heritage estates that lock competitors out of prime calendar slots. Distribution runs through proprietary ticketing platforms, licensed intermediary partnerships, and direct-to-fan membership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where the Digital Markets, Competition and Consumers Act's compliance burden forces undercapitalized operators toward acquisition or exit.
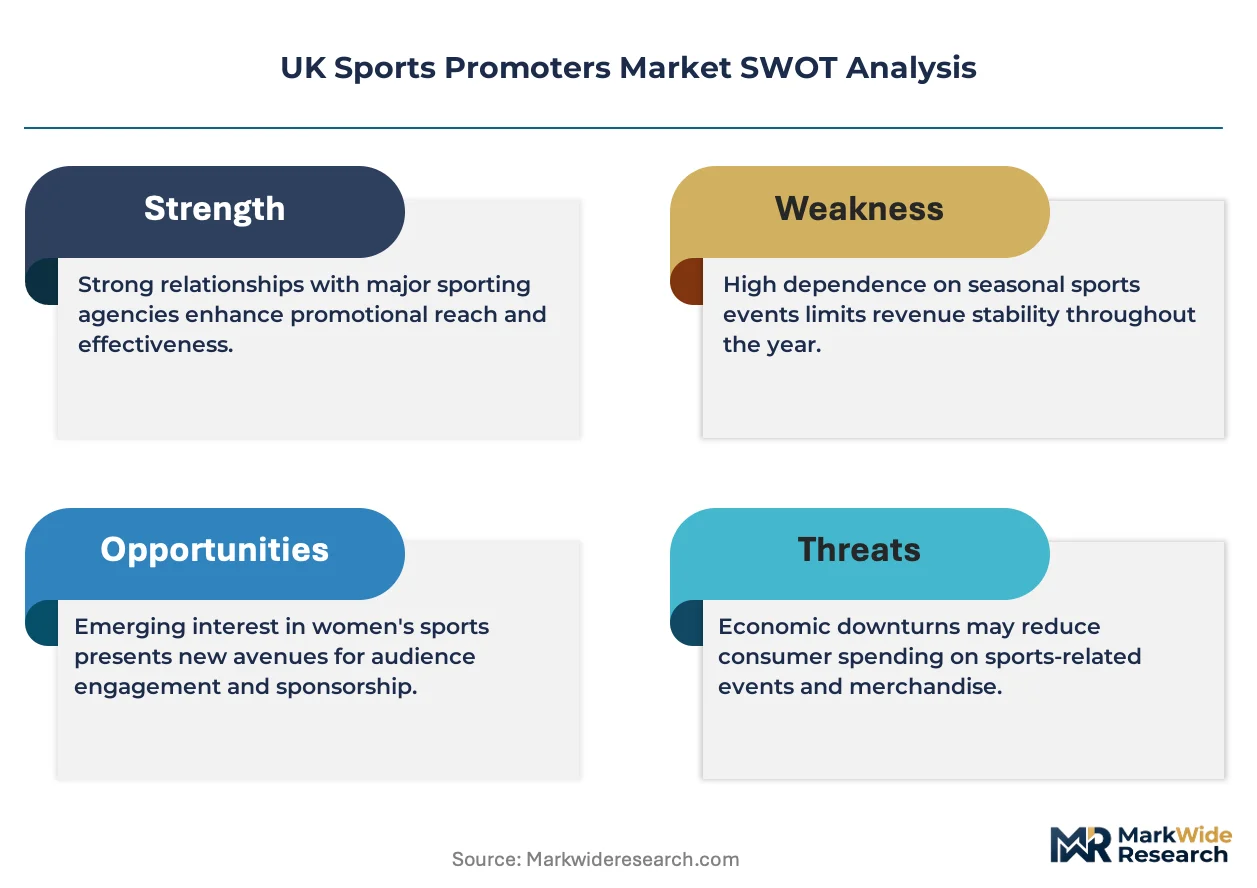
For Market Incumbents: Deploy exclusive venue calendar locking to secure multi-year licensing agreements at Wembley Stadium and Manchester Arena before regulatory fee transparency mandates erode negotiating leverage. Matchroom Sport's broadcast-first model demonstrates how proprietary pay-per-view infrastructure insulates against platform gatekeeper dependence. Channel control through direct-to-fan digital membership platforms captures merchandise and advertising revenue streams previously ceded to intermediaries. For New Entrants and Emerging Players: Direct-to-fan streaming bundles offer the most penetrable route into boxing and combat sports audiences outside saturated London calendar slots. Scotland and Wales present underpenetrated regional markets where first-mover promoters establish recurring event calendars without capital-intensive venue ownership. Partnership-based event assembly with complementary catering and security providers reduces fixed cost exposure. For Investors and Strategic Acquirers: The window for entry favors estate-anchored heritage operators with captive hospitality infrastructure and proprietary fan databases. Long-term viability hinges on regulatory compliance capabilities that create barriers against unlicensed secondary market entrants. Watch for Information Commissioner's Office enforcement intensity as the inflection signal determining licensed operators' data monetization runway.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Venue Licensing | Multi-year agreements at Wembley Stadium lock competitors out of premium calendar slots. |
| Direct-to-Fan Platform Launch | Proprietary membership channels capture merchandise revenue from wholesale intermediaries. |
| Broadcast-First Model Investment | Pay-per-view infrastructure reduces gate-revenue dependence for combat sports promoters. |
| GDPR-Compliant Data Infrastructure | Information Commissioner's Office alignment protects fan database value against unlicensed operators. |
| Regional Market Entry | Scotland and Wales venue development offers first-mover recurring calendar advantages. |
Research Methodology
Multi-period observation of ticketing platform fee structures, corporate hospitality procurement patterns, and pay-per-view subscriber migration anchored the trend analysis, supplemented by interviews with venue licensing directors, broadcast rights negotiators, hospitality procurement managers at financial services firms, and compliance officers at heritage racing estates. Secondary validation drew from Competition and Markets Authority filings, Information Commissioner's Office enforcement notices, Digital Markets, Competition and Consumers Act regulatory guidance, and venue operator annual disclosures. Bottom-up event-level revenue modeling and top-down sector expenditure estimates were triangulated.
Input-output matrices mapped service type, client relationship depth, and revenue stream architecture across the projection horizon. Segmentation dimensions modeled include event production intensity, rights holder category, and geographic venue cluster. CAGRs were derived from iterative reconciliation of historical expenditure trajectories with forward-looking fixture scheduling density and sponsorship budget recovery patterns. Broadcast carriage fee inflation and GDPR compliance cost escalation were incorporated as industry-specific forecast inputs.
The model holds under stable regulatory enforcement intensity and continued corporate hospitality budget recovery; deviation in Competition and Markets Authority intervention severity or secondary market platform fragmentation would shift volume and value distributions. A small set of named triggers warrants ongoing watch: Digital Markets, Competition and Consumers Act implementation pace, pay-per-view subscriber churn rates, and heritage estate licensing renewal negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
Stadium and Arena Management Solution Market
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
Global Sports Management Software Market
Sports & Fitness Technology
Smart Trainers Market
Sports & Fitness Technology
Padel Court Operator Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Crossfit Apparel Market