
 Home Fitness Equipment Market | 2026-2036
Home Fitness Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Home Fitness Equipment Market Analysis
Aftermarket service revenue is narrowing as manufacturers bundle subscription content directly with hardware purchases. Peloton Interactive leverages its proprietary streaming platform to capture recurring revenue beyond initial equipment sales. Johnson Health Tech sustains manufacturing scale across multiple price tiers through vertically integrated production in Asia. Technogym differentiates through premium commercial-grade engineering adapted for luxury residential installations.
Home fitness equipment encompasses mechanically or electronically powered apparatus designed for cardiovascular, strength, or flexibility training within residential or semi-private settings, typically constructed from welded steel frames, thermoplastic housings, and elastomeric cushioning systems rated for repetitive cyclic loading. Treadmills and exercise bikes retain the largest installed base among product types, though margin pools increasingly concentrate in smart equipment and connected machines where software integration commands premium pricing. Resistance bands and fabric-based accessories compete at lower price points but serve expanding demand for portable, storage-efficient solutions in dense urban housing.
The U.S. Consumer Product Safety Commission mandates stability testing and pinch-point guarding for motorized equipment, while the EU's CE marking framework enforces electromagnetic compatibility and machinery safety directives for imported units. China's SAMR administers national GB standards for electrical safety and mechanical endurance that shape design requirements for manufacturers targeting domestic distribution. Stakeholders must monitor evolving cybersecurity protocols as connected machines collect biometric data subject to GDPR in Europe and emerging state-level privacy statutes in the United States.
Market Dynamics
Subscription bundling with hardware is collapsing the traditional aftermarket service model, forcing manufacturers to capture lifetime value through recurring content revenue rather than one-time equipment sales.
Growth Catalysts
- China's GB Standards:National electrical safety and mechanical endurance requirements under SAMR administration accelerate domestic adoption of certified connected machines in urban apartment settings.
- Biometric Data Frameworks:GDPR compliance in Europe and emerging state-level privacy statutes in the United States create structured demand for cybersecurity-hardened equipment with encrypted data transmission.
- Welded Steel Frame Engineering:Advances in robotic welding and thermoplastic composite molding reduce production cycle times for cardiovascular equipment destined for dedicated residential workout spaces.
Market Restraints
- Semiconductor Supply Concentration:Microcontroller and sensor dependency on concentrated Asian foundry capacity creates input volatility for smart equipment production schedules.
- CE Marking Compliance Burden:Electromagnetic compatibility and machinery safety directive testing adds certification friction for imported units entering European distribution channels.
- Resistance Band Substitution:Fabric-based portable alternatives compete aggressively on storage efficiency and price point in dense urban housing markets.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for electronics manufacturing attract component localization for connected fitness hardware targeting price-sensitive middle-class households.
- AI-Computer Vision Convergence:Real-time form correction and personalized coaching algorithms enable premium pricing tiers for strength training equipment without human personal trainers.
- Direct-to-Consumer Channel Expansion:Bypassing traditional sporting goods retail captures margin and enables subscription onboarding at point of hardware purchase.
Industry Challenges
- Firmware Integration Complexity:Legacy mechanical platforms require substantial re-engineering to accommodate streaming content delivery and over-the-air update capabilities.
- Biomechanical Certification Timelines:Ergonomic validation and repetitive cyclic loading testing extend time-to-market for new cardiovascular equipment models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Fitness Equipment Market |
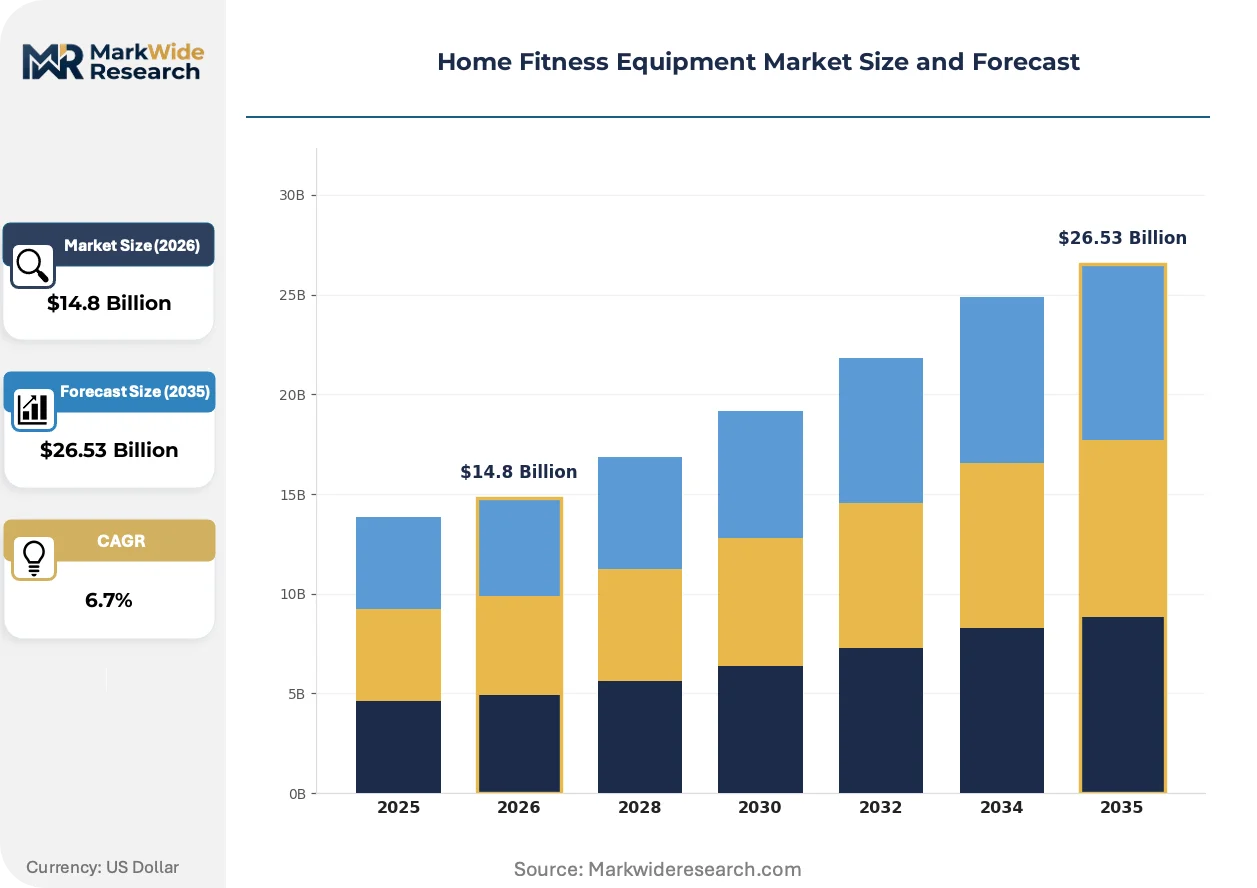
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmills, Exercise Bikes, Dumbbells, Resistance Bands Material: Steel, Plastic, Rubber, Fabric Technology: Smart Equipment, Traditional Equipment, Wearable Devices, Connected Machines End User: Individuals, Gyms, Fitness Studios, Trainers |
| Companies Covered | ICON Health & Fitness, Johnson Health Tech, Technogym, Life Fitness, Peloton Interactive, Core Health & Fitness, Nautilus, Precor, Tonal Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Fitness Equipment Market Emerging Trajectories
Software-hardware integration is compressing equipment lifecycles and redefining competitive advantage around content ecosystems rather than mechanical durability alone.
Embedded edge computing is collapsing the latency barrier between sensor input and real-time workout feedback. Residential consumers with dedicated workout spaces now expect sub-100 millisecond response times for form correction and resistance adjustment. This compression eliminates the competitive viability of cloud-dependent architectures that cannot guarantee local processing reliability.
The EU's CSRD disclosure requirements are extending sustainability reporting obligations to fitness equipment imports. Manufacturers must now document carbon intensity across welded steel frame production and thermoplastic housing supply chains. European distributors increasingly screen suppliers based on verified lifecycle assessments before contract execution.
Apartment dwellers in dense Chinese and Japanese cities are prioritizing foldable and wall-mounted configurations over traditional floor-standing equipment. Retailers report accelerated inventory turns for storage-efficient solutions that reclaim living space between workouts. This spatial constraint is driving industrial design investment in collapsible resistance systems and ceiling-suspended cardio platforms.
Home Fitness Equipment Market Segmentation
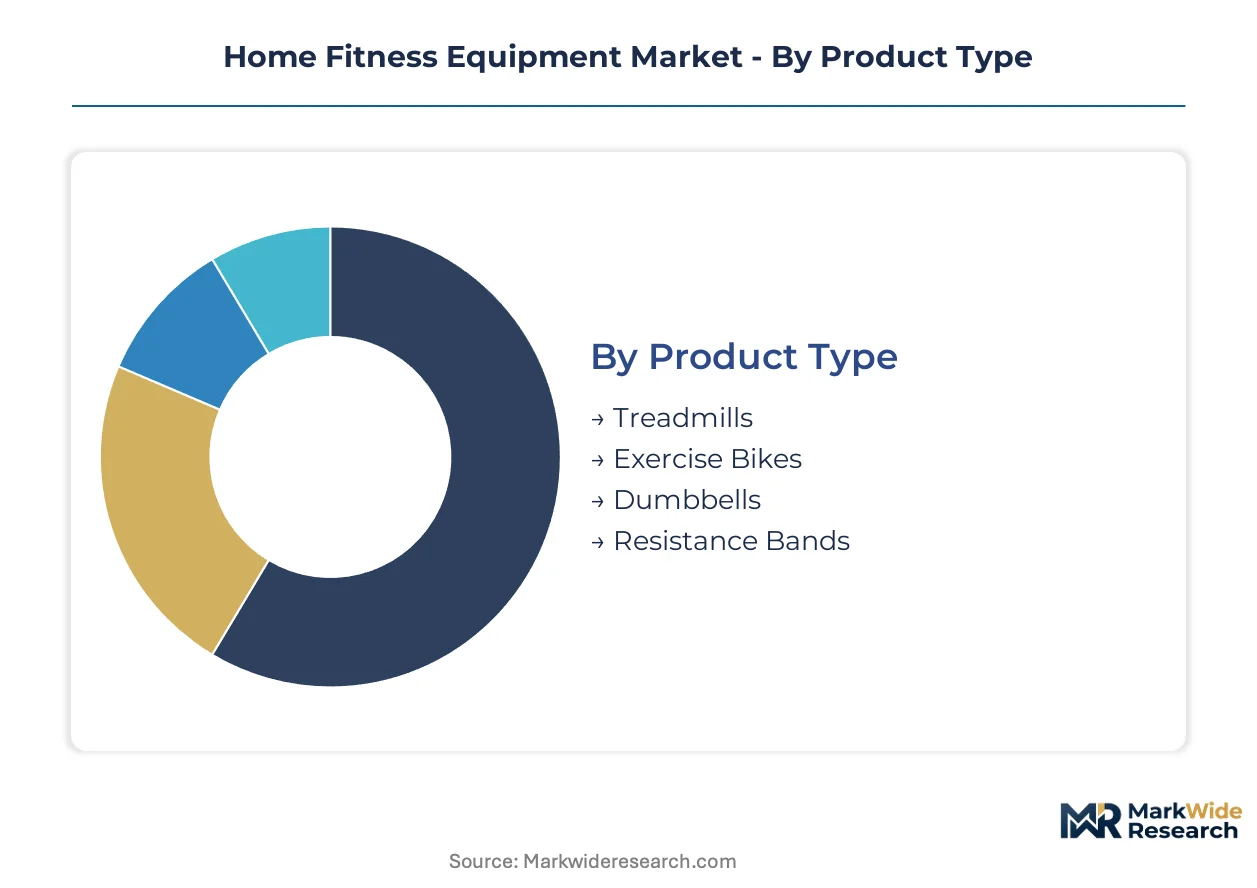
Segmentation in home fitness equipment determines service model design, from one-time hardware sales to recurring subscription revenue. Material choices and technology integration levels dictate manufacturing location, certification requirements, and margin structure across distribution channels.
Product Type:
After-sales service intensity varies dramatically across equipment categories, with motorized platforms demanding ongoing maintenance while free-weight systems require minimal post-purchase support.
- Treadmills:Motorized belt systems with welded steel frames and elastomeric cushioning demand periodic belt replacement and motor servicing. Dedicated residential workout spaces in suburban U.S. homes drive replacement cycles for aging installed base units.
- Exercise Bikes:Flywheel and magnetic resistance assemblies combine mechanical durability with connected content delivery potential. Urban Chinese apartment dwellers prioritize compact footprint models with integrated streaming capabilities for space-constrained installations.
- Dumbbells:Cast iron or steel hexagonal designs with knurled grips require no electrical maintenance and minimal warranty claims. Storage-efficient adjustable variants compete with fixed-weight sets in dense housing markets.
- Resistance Bands:Fabric and latex elastic systems offer zero service requirements and lowest total cost of ownership. Portable configurations displace floor-standing equipment in Japanese metropolitan apartments where space reclamation between workouts is essential.
By volume, Resistance Bands lead. By growth pace, Exercise Bikes is ahead.
Material:
Cost tier positioning aligns closely with raw material selection, from premium steel architectures to entry-level fabric solutions.
- Steel:Welded frame construction with powder-coated finishes provides maximum load-bearing capacity for strength equipment. Robotic welding advances in Taiwanese and Vietnamese manufacturing facilities reduce production cycle times for cardiovascular platforms.
- Plastic:Thermoplastic housings for console enclosures and cosmetic shrouds enable design flexibility at reduced unit weight. Housing suppliers face EU CSRD documentation requirements for carbon intensity verification before European distributor contract execution.
- Rubber:Elastomeric cushioning systems and grip coatings absorb repetitive cyclic loading in high-use residential settings. Formulation chemistry must satisfy GB standards electrical safety proximity requirements for motorized equipment sold in China.
- Fabric:Woven textile resistance systems and upholstery materials enable collapsible storage configurations. Japanese retailers report accelerated inventory turns for fabric-based portable solutions targeting space-constrained urban consumers.
By installed base, Steel dominates. By substitution pressure, Fabric is climbing the fastest.
Technology:
Margin concentration tracks technology integration depth, with software-enabled platforms commanding premium pricing over mechanical-only alternatives.
- Smart Equipment:Embedded sensors with edge computing capability deliver sub-100 millisecond feedback latency for form correction. GDPR-compliant encrypted data transmission architectures are mandatory for European market entry.
- Traditional Equipment:Purely mechanical platforms without electrical components avoid semiconductor supply volatility and cybersecurity compliance burdens. Price-sensitive middle-class households in India favor these configurations under PLI-influenced component localization.
- Wearable Devices:Wrist-worn biometric monitors integrate with residential equipment via Bluetooth protocols. India's electronics manufacturing incentives attract assembly localization for heart rate and motion tracking accessories.
- Connected Machines:Streaming content delivery with over-the-air firmware update capability collapses equipment lifecycles and shifts competitive advantage to content ecosystems. Subscription bundling with hardware purchases captures lifetime value beyond initial equipment sales.
By revenue concentration, Connected Machines leads. By expansion trajectory, Smart Equipment is gaining share fastest.
End User:
Customer type determines channel strategy, from direct-to-consumer subscription onboarding to institutional procurement with extended payment terms.
- Individuals:Residential consumers with dedicated workout spaces purchase through direct-to-consumer channels that enable subscription onboarding at point of hardware sale. Peloton Interactive's proprietary streaming platform exemplifies recurring revenue capture beyond initial equipment transactions.
- Gyms:Commercial fitness facilities demand commercial-grade engineering with extended warranty coverage and preventive maintenance contracts. Technogym's premium residential adaptations leverage this commercial heritage for luxury home installations.
- Fitness Studios:Boutique operators require equipment durability under high-frequency multi-user loading conditions. Johnson Health Tech sustains manufacturing scale across price tiers through vertically integrated Asian production.
- Trainers:Independent fitness professionals prioritize portable, client-transportable equipment for in-home sessions. Resistance band configurations serve this mobility requirement with minimal storage footprint.
By unit volume, Individuals leads. By contract value, Gyms is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for home fitness equipment varies sharply across geographies. Chinese urban buyers prioritize compact, technology-integrated solutions despite premium pricing, while Indian middle-class households remain highly price-sensitive and favor mechanical-only configurations. European consumers occupy a middle ground, accepting higher upfront costs for GDPR-compliant connected machines with documented sustainability credentials.
United States
Suburban residential consumers with dedicated workout spaces drive replacement cycles for aging treadmill and exercise bike installed bases. The Consumer Product Safety Commission enforces stability testing and pinch-point guarding standards that shape motorized equipment design requirements. Greater Boston anchors connected fitness software development, with streaming platform engineering talent clustering around venture-backed hardware startups.
China
Urban apartment dwellers in Shanghai, Beijing, and Shenzhen prioritize foldable, wall-mounted configurations that reclaim living space between workouts. SAMR-administered GB standards for electrical safety and mechanical endurance accelerate domestic certification of connected machines. The Yangtze River Delta manufacturing belt concentrates robotic welding and thermoplastic composite molding capacity for cardiovascular equipment exports.
Germany
CE marking compliance for electromagnetic compatibility and machinery safety directives filters imported equipment entering European distribution channels. The EU's CSRD disclosure requirements now extend sustainability reporting obligations to fitness equipment imports, with carbon intensity documentation required across welded steel frame supply chains. Baden-Württemberg hosts precision engineering clusters adapting commercial-grade equipment for luxury residential installations.
India
Price-sensitive middle-class households favor traditional mechanical platforms without electrical components, avoiding semiconductor supply volatility and cybersecurity compliance burdens. The PLI scheme for electronics manufacturing attracts component localization for connected fitness hardware targeting future upgrade cycles. Maharashtra and Karnataka industrial corridors develop assembly capacity for heart rate and motion tracking accessories under electronics manufacturing incentives.
Japan
Metropolitan Tokyo and Osaka apartment dwellers accelerate inventory turns for fabric-based portable solutions where space reclamation between workouts is essential. METI standards shape industrial design investment in collapsible resistance systems and ceiling-suspended cardio platforms. The Kanto region concentrates compact equipment R&D for single-occupancy housing configurations.
Home Fitness Equipment Market Vendor Landscape
Capability concentration sits with streaming-enabled content platforms; scale advantage sits with vertically integrated Asian manufacturers. The market structures around three tiers: proprietary ecosystem operators capturing recurring subscription revenue, multi-brand manufacturing conglomerates sustaining production across price points, and specialized component suppliers serving private-label distributors. Strategic moves center on direct-to-consumer channel expansion bypassing traditional sporting goods retail, and backward integration into captive steel frame and sensor production to compress cost structures.
Among ecosystem-centric operators, Peloton Interactive exemplifies the proprietary streaming platform archetype that captures lifetime value beyond initial hardware transactions. Johnson Health Tech and Technogym occupy positions spanning manufacturing scale and premium commercial-grade engineering adapted for residential applications. ICON Health & Fitness represents the multi-brand portfolio approach serving diverse price tiers through consolidated production infrastructure.
| Leading Market Players |
|---|
| ICON Health & Fitness |
| Johnson Health Tech |
| Technogym |
| Life Fitness |
| Peloton Interactive |
| Core Health & Fitness |
| Nautilus |
| Precor |
| Tonal Systems |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Taiwanese robotic welding facilities is compressing production schedules for cardiovascular equipment frames, forcing manufacturers to pre-commit volume through long-term offtake contracts while passing through capacity premiums to buyers of connected machines.
Pricing Analysis
Long-term offtake contracts dominate procurement for welded steel frame components, while spot purchasing persists for commodity thermoplastic housings. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-compliant connected machines with encrypted data transmission from mechanical-only platforms and portable fabric-based alternatives. Cost compression in economy tiers is intensifying because resistance band substitution erodes floor-standing equipment demand in dense urban housing. Price-sensitive middle-class households in India favor traditional mechanical configurations, while suburban U.S. residential consumers with dedicated workout spaces accept premium positioning for streaming-enabled content ecosystems.
Supply Chain Analysis
Export-control restrictions on advanced microcontroller architectures limit sensor component flows into Chinese assembly facilities, constraining smart equipment production scaling. Manufacturing gravity centers on Taiwan, Vietnam, and China for welded steel frame robotic welding, thermoplastic composite molding, and final assembly integration. Semiconductor supply draws from concentrated Asian foundry capacity, elastomeric cushioning formulations feed from Malaysian rubber processing, and console electronics rest on South Korean display panel output. Single-source vulnerability in microcontroller procurement creates input volatility for connected machine production schedules. Distribution runs through direct-to-consumer channels bypassing traditional sporting goods retail, enabling subscription onboarding at point of hardware purchase.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as proprietary streaming ecosystems displace mechanical durability as the primary value anchor, with interoperability between wearable biometric devices and residential equipment emerging as the decisive architecture shift.
For Market Incumbents: Build captive content moats through exclusive streaming platform investments that lock in subscriber lifetime value beyond initial hardware transactions. Deepen backward integration into sensor production and welded steel frame manufacturing to compress cost structures against emerging price competition. Defensive patent clustering around real-time form correction algorithms protects premium positioning against AI-computer vision entrants.
For New Entrants and Emerging Players: Pursue white-space penetration in India's price-sensitive middle-class households through PLI-influenced component localization for mechanical-only platforms. Target Japanese metropolitan apartment dwellers with fabric-based portable solutions optimized for space reclamation between workouts. Deploy direct-to-consumer channel expansion with subscription bundling at hardware purchase to capture recurring revenue without retail margin dilution.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across connected fitness hardware as edge computing architectures reduce cloud infrastructure dependency and semiconductor integration costs decline. Acquisition targets should exhibit captive steel frame production, established GDPR-compliant data architectures, and proven subscription retention mechanics. Watch for inflection signals in India's electronics manufacturing incentive uptake rates as indicators of future component localization viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Bypasses retail margin capture and enables subscription onboarding at Peloton-style hardware purchase moments. |
| Backward Integration into Sensor Production | Compresses input costs for smart equipment while reducing dependency on concentrated Asian foundry capacity. |
| GDPR-Compliant Data Architecture Investment | Unlocks European market entry for connected machines collecting biometric data under encrypted transmission protocols. |
| AI-Computer Vision Capability Buildout | Enables real-time form correction premium pricing without human personal trainer cost structures. |
| PLI-Aligned Component Localization | Positions manufacturers for India's price-sensitive middle-class demand under electronics manufacturing incentives. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with connected fitness platform executives, robotic welding facility managers in Taiwan and Vietnam, residential equipment procurement leads at European sporting goods distributors, and subscription content strategy directors. Secondary validation drew from U.S. Consumer Product Safety Commission enforcement records, EU CSRD sustainability disclosure filings, China's SAMR GB standards documentation, SEC 10-K equipment manufacturer filings, and customs trade data for welded steel frame imports. Bottom-up equipment shipment modeling triangulated against top-down consumer expenditure surveys.
Calibration against historical replacement cycles for treadmill and exercise bike installed bases anchored volume projections across the analysis window. Segmentation dimensions modeled include product type, material composition, technology integration depth, and end-user archetype with regional regulatory cluster overlays. CAGRs were derived from slope analysis of technology adoption curves and content subscription attach rates. Forecast inputs incorporated semiconductor supply volatility indices and urban housing density metrics as demand shapers for space-efficient configurations.
Sensitivities concentrate around semiconductor supply disruption duration, GB standards enforcement intensity in China, and resistance band substitution velocity in dense Asian housing markets. Forecasts reflect documented assumptions regarding subscription retention mechanics and regulatory compliance cost trajectories. Material shifts in export-control regime scope or EU cybersecurity protocol expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
China Outdoor Fitness Equipment Market
Fitness Equipment
Mexico Outdoor Fitness Equipment Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
Treadmill Motors Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Europe E-Commerce Home Fitness Products Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Pilates Reformer Market
Fitness Equipment
Fitness Ball Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
GCC Fitness Ring Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Hydrotherapy Treadmills Market