
 Smart Court (Sports) Market | 2026-2036
Smart Court (Sports) Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Court (Sports) Market Analytics
The EU Green Deal is restructuring procurement criteria for sports infrastructure across European venues, compelling facility operators to prioritize energy-efficient court lighting and embedded sensor networks. Hawk-Eye Innovations leverages decades of optical-tracking heritage to dominate elite tennis and cricket installations. Catapult Sports anchors wearable-to-fixed-system convergence by integrating athlete biometrics with court-based environmental data. PlaySight Interactive differentiates through cloud-native architecture that reduces on-premise hardware burdens for mid-tier facilities.
Smart Court (Sports) denotes integrated athletic environments employing distributed sensor arrays, edge-computing nodes, and computer-vision subsystems to capture ball trajectory, player kinematics, and environmental conditions with sub-centimeter precision, primarily serving competitive training optimization and broadcast augmentation. Video Analytics commands margin concentration due to recurring software licensing and premium broadcast-rights tie-ins, while IoT Solutions expand fastest as retrofit sensor kits penetrate educational and recreational budgets. Performance Monitoring Systems sustain steady uptake among professional teams seeking injury-risk quantification.
FCC equipment-authorization rules govern wireless sensor transmissions in US venues, while ISO 20121 event-sustainability standards shape European procurement specifications for new court construction. The EU AI Act introduces conformity obligations for automated officiating algorithms, potentially segmenting product roadmaps between explainable-AI architectures and legacy black-box systems. Stakeholders must monitor evolving liability frameworks for real-time injury-alert systems as courtside AI assumes greater athlete-safety responsibility.
Market Dynamics
Energy-efficiency mandates from the EU Green Deal are compressing facility upgrade cycles, forcing venue operators to bundle LED retrofits with IoT sensor networks rather than execute sequential capital projects.
Growth Catalysts
- EU Green Deal procurement rules:European sports infrastructure operators must meet binding energy-efficiency thresholds for new construction and major renovations, accelerating integrated smart court installations.
- Collegiate athletic programs:US universities are deploying performance analytics suites to attract recruiting talent and satisfy broadcast contract obligations with conference networks.
- Edge computing:Distributed processing architectures reduce latency for real-time officiating and injury-alert systems, expanding addressable venues beyond elite professional facilities.
Market Restraints
- Optical sensor component concentration:Specialized camera modules and LiDAR arrays depend on East Asian contract manufacturers, exposing lead times to geopolitical friction.
- EU AI Act conformity costs:Automated officiating algorithms face explainability requirements that fragment R&D roadmaps and extend certification timelines.
- Legacy court surface incompatibility:Retrofit sensor kits encounter adhesion and calibration failures on older hardwood and synthetic surfaces, limiting penetration of municipal recreation budgets.
Strategic Opportunities
- India municipal sports infrastructure:Smart city initiatives and Khelo India program funding create procurement pipelines for mid-tier sensor packages in district-level facilities.
- Wearable-to-fixed-system convergence:Integration of athlete biometric bands with court-based environmental sensors enables holistic load management platforms.
- ISO 20121 event-sustainability certification:Venue operators pursuing this standard must demonstrate measurable energy and resource efficiency, creating pull-through for smart environmental monitoring.
Industry Challenges
- Computer-vision engineering talent scarcity:Sub-centimeter trajectory tracking requires specialized expertise in optical physics and machine learning that concentrates in elite research institutions.
- Multi-vendor integration complexity:Facilities combining Hawk-Eye optical systems with third-party IoT networks face protocol mismatches and data siloing that degrade analytics utility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Court (Sports) Market |
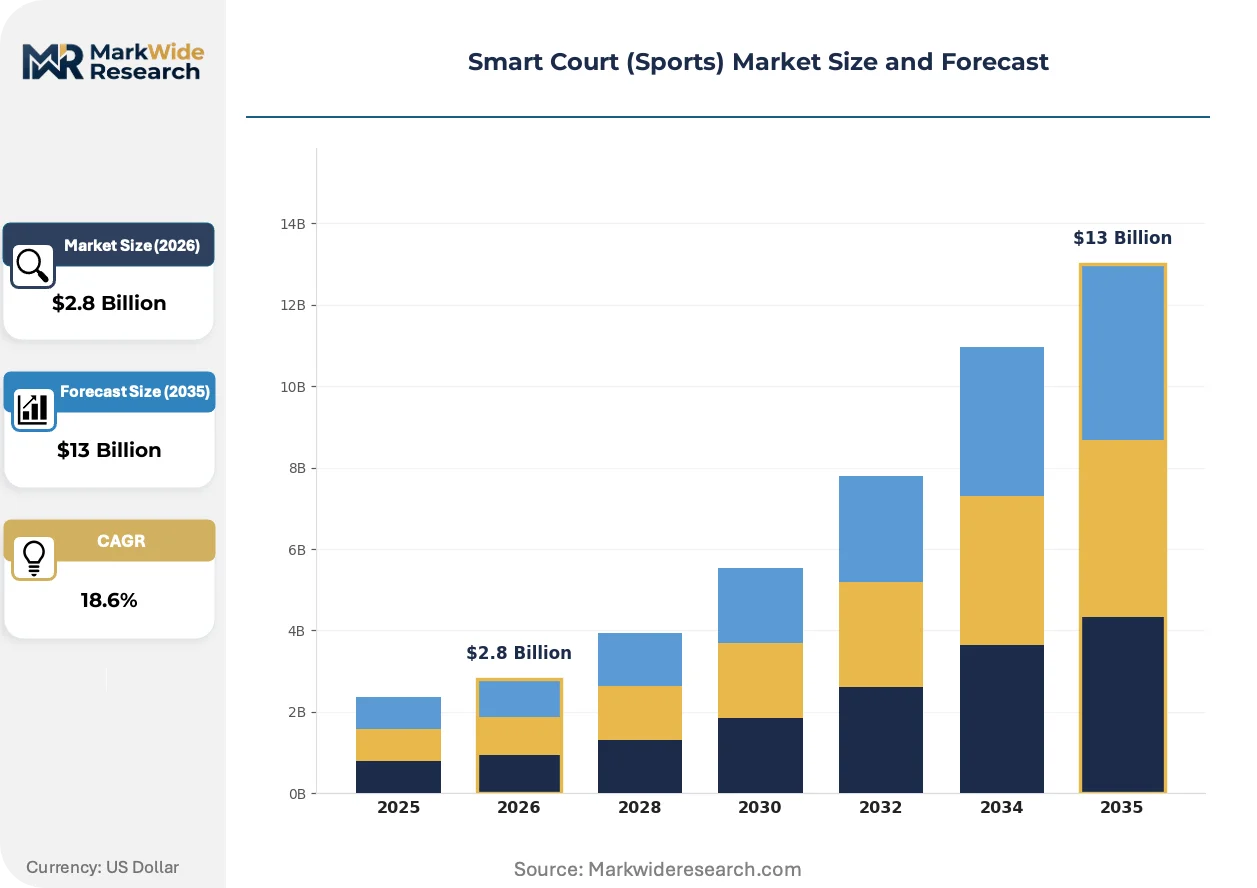
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Video Analytics, Court Lighting, Performance Monitoring Systems End User: Professional Teams, Educational Institutions, Sports Academies, Recreational Facilities Technology: IoT Solutions, AI Algorithms, Augmented Reality, Cloud Computing Application: Player Training, Match Analysis, Audience Engagement, Injury Prevention |
| Companies Covered | SmartCourts, Sportable, PlaySight Interactive, Bolt6, Hawk-Eye Innovations, Catapult Sports, Quidich Innovation Labs, OneCourt, ShotTracker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Court (Sports) Market Evolving Landscape
Real-time broadcast augmentation and athlete safety monitoring are converging on unified sensor platforms, collapsing the historical separation between production technology and training infrastructure.
Millimeter-wave radar arrays are electrifying player tracking by penetrating visual occlusions and eliminating dependency on line-of-sight camera positioning. NBA and EuroLeague franchises are piloting these systems for off-ball movement analytics. The technology is electrifying competitive differentiation between venues that can offer broadcast partners guaranteed tracking continuity.
EU AI Act algorithmic transparency requirements are forcing vendors to rearchitect automated officiating systems around interpretable decision trees rather than deep neural networks. This industrial consequence elevates engineering costs for European deployments. Cricket and tennis governing bodies in the United Kingdom, France, and Germany are responding by demanding vendor roadmaps that segregate explainable-AI products from legacy black-box installations.
Subscription-based software licensing is displacing perpetual hardware-plus-software bundles in mid-tier facility procurement. Municipal recreation centers and high school athletic departments now favor annual SaaS arrangements that spread capital requirements across operating budgets. This pattern is most visible across Texas, Florida, and California school districts where bond funding constraints favor operational expenditure structures.
Smart Court (Sports) Market Segmentation
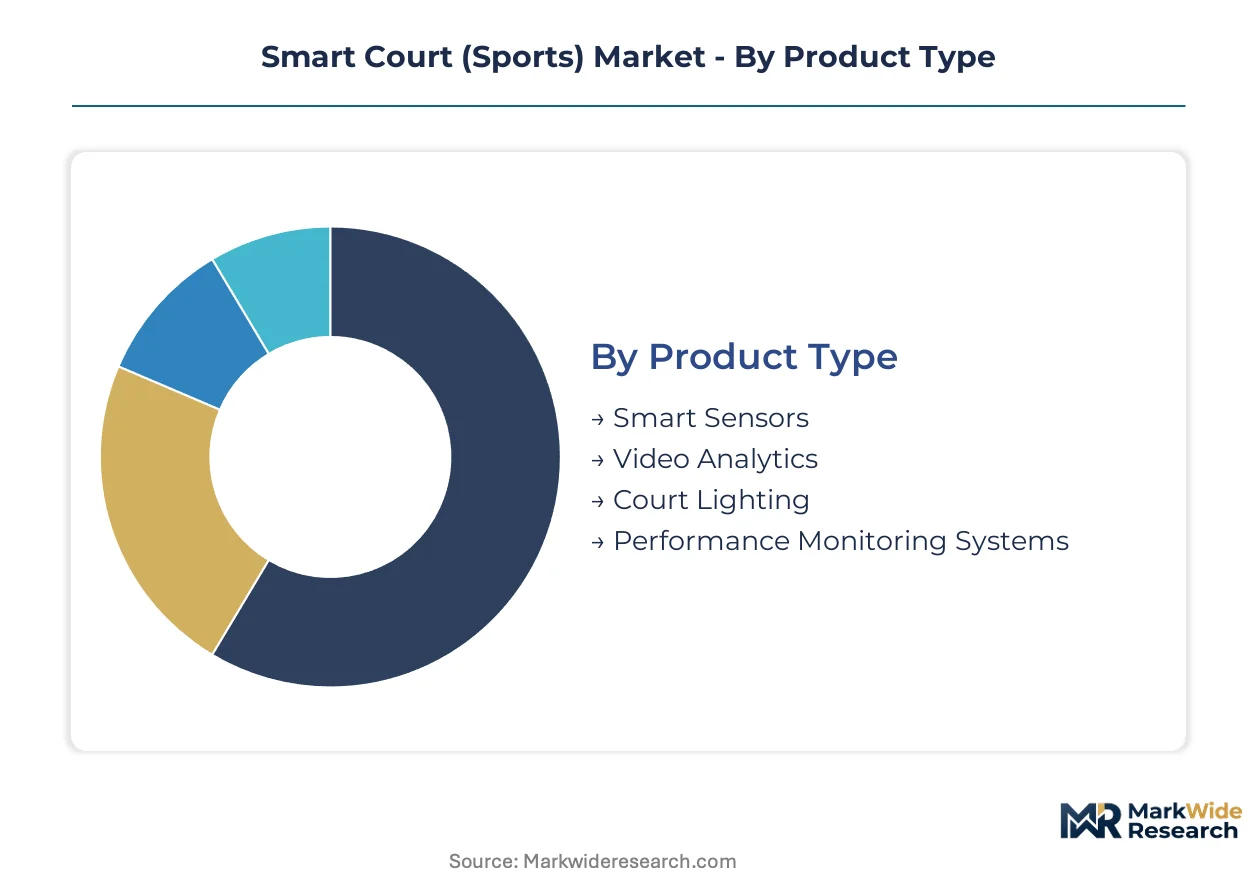
Smart court procurement diverges sharply across facility tiers, with professional franchises prioritizing broadcast-grade precision while educational and municipal buyers seek modular retrofit packages. Certification requirements from the EU AI Act and FCC equipment authorization create compliance moats that segment vendor competitiveness by product category.
Product Type:
Certification burdens concentrate in Video Analytics and Performance Monitoring Systems, where automated officiating algorithms face EU AI Act explainability mandates and FDA-style injury-alert liability frameworks.
- Video Analytics:Computer-vision subsystems processing ball trajectory and player kinematics through distributed camera arrays. Professional tennis and basketball franchises in the United States and United Kingdom drive procurement for broadcast augmentation and automated line-calling, constrained by escalating software licensing costs.
- Performance Monitoring Systems:Integrated athlete biometrics platforms fusing wearable data with court-based environmental sensors. Professional teams across Germany and France prioritize these for load management and injury-risk quantification, though calibration complexity limits municipal adoption.
- Smart Sensors:Distributed IoT arrays capturing environmental conditions and equipment status.
- Court Lighting:LED retrofits with embedded sensor networks meeting EU Green Deal efficiency thresholds.
Leading the category by volume: Smart Sensors. Growing fastest: Video Analytics.
End User:
Cost tier stratification separates perpetual-license professional deployments from SaaS-preferred institutional buyers spreading capital across operating budgets.
- Professional Teams:Elite franchises in the NBA, EuroLeague, and ATP Tour deploying unified sensor platforms for training and broadcast convergence. These buyers demand sub-centimeter precision and real-time latency, absorbing premium pricing for edge-computing architectures.
- Educational Institutions:US collegiate athletic programs and Indian universities under Khelo India funding procurement mid-tier sensor packages. Budget constraints favor cloud-native solutions reducing on-premise hardware burdens, with Texas and Florida school districts leading SaaS adoption.
- Sports Academies:Specialized training facilities requiring portable analytics for talent development pipelines.
- Recreational Facilities:Municipal centers facing legacy surface incompatibility challenges with adhesive sensor kits.
Dominating procurement value: Professional Teams. Expanding most quickly: Educational Institutions.
Technology:
Application maturity varies from production-grade IoT deployments to experimental AR integrations still seeking viable revenue models.
- IoT Solutions:Retrofit sensor kits penetrating educational and recreational budgets through modular hardware and annual subscription structures. EU Green Deal mandates accelerate LED-integrated IoT networks across French and German venue renovations.
- AI Algorithms:Automated officiating and injury-alert systems facing EU AI Act conformity costs that fragment R&D roadmaps. Cricket and tennis governing bodies in the United Kingdom, France, and Germany now demand explainable-AI architectures segregated from legacy black-box installations.
- Augmented Reality:Broadcast overlay and fan experience technologies piloting in select NBA and EuroLeague venues.
- Cloud Computing:Distributed processing reducing latency for real-time applications beyond elite facilities.
Widest installed base: IoT Solutions. Steepest expansion trajectory: AI Algorithms.
Application:
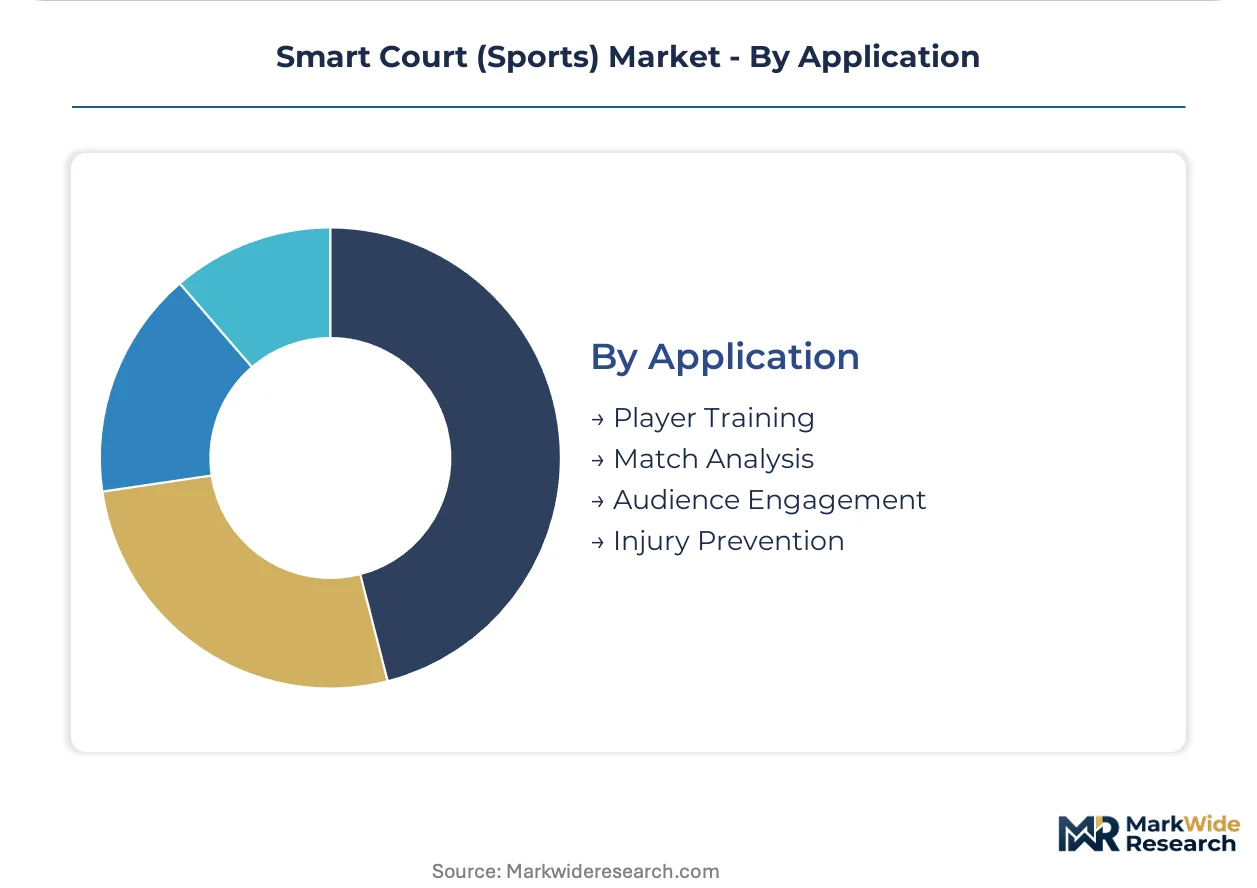
Customer type alignment pairs professional team budgets with match analysis and injury prevention, while educational buyers concentrate on player training modules.
- Player Training:Biomechanical feedback systems for skill development and technique refinement. US collegiate programs and Indian district-level facilities under smart city initiatives drive mid-tier procurement, constrained by computer-vision engineering talent scarcity.
- Match Analysis:Broadcast-grade trajectory tracking and tactical pattern recognition. Professional tennis and basketball franchises absorb premium pricing for guaranteed tracking continuity, with millimeter-wave radar pilots penetrating visual occlusions in NBA and EuroLeague venues.
- Audience Engagement:Second-screen and venue-integrated fan experience technologies.
- Injury Prevention:Real-time load monitoring and alert systems assuming greater athlete-safety responsibility.
Highest revenue concentration: Match Analysis. Gaining share fastest: Player Training.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth anchors North American smart court deployment momentum, where collegiate athletic programs and municipal recreation centers drive procurement volumes through bond-funded infrastructure cycles.
United States
NCAA Division I programs in Texas and Florida prioritize performance analytics suites to attract recruiting talent and satisfy broadcast obligations with conference networks. FCC equipment-authorization rules govern wireless sensor transmissions across venues. The Dallas-Fort Worth metroplex concentrates vendor pilot programs for millimeter-wave radar tracking systems.
Germany
EuroLeague franchises and Bundesliga basketball clubs demand edge-computing architectures for real-time officiating and injury-alert systems. EU Green Deal energy-efficiency mandates compress facility upgrade cycles in Bavaria and North Rhine-Westphalia. Munich-based sports infrastructure operators bundle LED retrofits with IoT sensor networks under binding procurement thresholds.
United Kingdom
ATP Tour venues and county cricket grounds sustain demand for broadcast-grade trajectory tracking with sub-centimeter precision. The UK Information Commissioner's Office applies GDPR frameworks to athlete biometric data processing. London and Manchester concentrate Hawk-Eye optical system installations for elite tennis and cricket competitions.
India
Khelo India program funding and smart city initiatives create procurement pipelines for mid-tier sensor packages in district-level facilities. BIS certification requirements shape hardware import specifications for municipal sports infrastructure. Maharashtra and Karnataka lead deployment of cloud-native court analytics under state-level athletic development schemes.
France
Roland Garros and Ligue Nationale de Basket venues drive premium installations for automated line-calling and tactical pattern recognition. EU AI Act conformity obligations fragment R&D roadmaps for explainable-AI officiating architectures. The Île-de-France region concentrates vendor certification activity for segregated product roadmaps between European and legacy black-box systems.
Smart Court (Sports) Market Competitive Landscape
The competitive structure tilts toward specialized technology providers with deep optical-tracking heritage and cloud-native platform developers. Vendor positioning separates into three archetypes: precision-tracking specialists leveraging decades of computer-vision expertise, wearable-to-fixed-system integrators fusing athlete biometrics with environmental data, and modular retrofit providers targeting mid-tier facilities through subscription pricing. Dominant competitive moves include strategic partnerships with broadcast rights holders and portfolio diversification into adjacent athlete safety monitoring applications.
Among precision-tracking specialists, Hawk-Eye Innovations occupies a position exemplifying optical-tracking dominance in elite tennis and cricket installations. Catapult Sports represents the wearable-to-fixed-system convergence archetype, integrating athlete biometrics with court-based environmental data for holistic load management platforms. PlaySight Interactive sits within the cloud-native tier, reducing on-premise hardware burdens for educational and municipal buyers through distributed processing architectures.
| Leading Market Players |
|---|
| SmartCourts |
| Sportable |
| PlaySight Interactive |
| Bolt6 |
| Hawk-Eye Innovations |
| Catapult Sports |
| Quidich Innovation Labs |
| OneCourt |
| ShotTracker |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up precision-tracking specialists now control three of the five dominant optical-system vendors, compressing procurement negotiations for collegiate athletic programs and municipal recreation centers while enforcing strict annual SaaS escalation clauses that tether pricing discipline to sensor hardware refresh cycles.
Pricing Analysis
Outcome-based pricing anchored to broadcast-rights revenue shares dominates professional franchise contracts, while educational buyers face three-tier pricing structure across premium, standard, and economy levels tied to NCAA Division I, Division II, and high school tiers respectively. Price differentiation separates FCC-authorized wireless sensor packages from uncertified retrofit kits, with EU AI Act conformity costs adding certification premiums to European deployments. Pricing pressure stems from municipal bond funding constraints in Texas and Florida school districts favoring operational expenditure structures. Recreational facilities exhibit highest price sensitivity due to legacy surface incompatibility risks, while NBA and EuroLeague franchises absorb premium edge-computing architectures with minimal negotiation leverage.
Supply Chain Analysis
Specialized camera modules and LiDAR arrays rest on East Asian contract manufacturers in Taiwan, South Korea, and Japan, creating single-source vulnerability for sub-centimeter optical tracking components. Millimeter-wave radar chips draw from German automotive sensor suppliers and Chinese RF component foundries. LED driver ICs hinge on Malaysian and Vietnamese assembly facilities subject to logistics chokepoint exposure through the Strait of Malacca. Distribution runs through direct vendor relationships with elite sports franchises, regional systems integrators for educational deployments, and municipal procurement frameworks for recreational facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over optical sensor fabrication and cloud-native software stacks determines margin capture across facility tiers.
For Market Incumbents: Lock in broadcast-rights holder partnerships through exclusive multi-year tracking service agreements that embed sensor hardware refresh obligations. Secure captive supply of specialized LiDAR arrays via backward integration into Taiwanese optical component vendors or long-term offtake contracts, insulating against geopolitical friction that disrupts East Asian manufacturing. Counter cloud-native challengers by bundling edge-computing hardware with perpetual software licenses that reduce switching costs for NCAA Division I programs. For New Entrants and Emerging Players: The gap between premium professional-tier pricing and economy municipal retrofit kits creates white-space entry points for mid-tier sensor packages targeting Indian district-level facilities under Khelo India funding and US high school athletic departments in bond-constrained California districts. Portable analytics systems for sports academies remain underpenetrated relative to fixed-installation saturation in elite venues. Pursue SaaS-first go-to-market positioning that spreads capital requirements across operating budgets, mirroring PlaySight Interactive's cloud-native architecture to reduce on-premise hardware burdens. For Investors and Strategic Acquirers: Distressed-cycle entries favor wearable-to-fixed-system convergence specialists in Germany and Australia where athlete biometric integration platforms face temporary valuation compression from EU AI Act conformity cost overruns. Long-term viability centers on vendors with explainable-AI officiating architectures that satisfy United Kingdom, France, and Germany regulatory roadmaps while maintaining legacy black-box revenue streams in non-European markets. Monitor BIS certification timelines for Indian municipal procurement as the inflection signal for mid-tier facility deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Taiwanese LiDAR module supply secures sub-centimeter tracking continuity for ATP Tour venues. |
| Explainable-AI Architecture Certification | EU AI Act conformity unlocks French and German automated officiating procurement while fragmenting legacy black-box roadmaps. |
| SaaS Platform Migration | Cloud-native subscription structures penetrate Texas and Florida school districts facing bond funding constraints. |
| Millimeter-Wave Radar Deployment | NBA and EuroLeague pilot programs eliminate line-of-sight dependency for off-ball movement analytics. |
| Wearable-to-Fixed System Convergence | Catapult Sports integration model enables holistic load management platforms spanning athlete biometrics and court environmental data. |
Research Methodology
Document review covered SEC filings from sports technology vendors, EU Green Deal procurement specifications, and FCC equipment authorization databases, complemented by interviews with facility operations directors at NCAA Division I programs, broadcast technology procurement leads at conference networks, and municipal recreation center administrators. Secondary validation drew from Hawk-Eye Innovations installation records, Catapult Sports biometric platform disclosures, and PlaySight Interactive cloud architecture documentation. Bottom-up facility deployment tallies triangulated against top-down market sizing from sensor hardware shipment data and software licensing revenue patterns.
Segment-level outputs across product type, end user, technology, and application dimensions were generated through structured analytical frameworks, with facility tier stratification and regional regulatory clustering as cross-cutting variables. CAGRs were derived from trend extrapolation of collegiate athletic program procurement cycles, EU Green Deal mandate implementation timelines, and smart city initiative funding trajectories. Industry-specific forecast inputs included NCAA broadcast contract renewal schedules, Khelo India program disbursement patterns, and millimeter-wave radar pilot program expansion signals from NBA and EuroLeague franchises.
Underlying measurement precision varies by segment; Video Analytics and Performance Monitoring Systems carry tighter precision than Smart Sensors and Court Lighting due to concentrated vendor disclosure practices. Forecasts reflect documented assumptions about regulatory implementation timelines, sensor component supply continuity, and municipal budget allocation priorities. A small set of triggers warrants ongoing watch: EU AI Act certification delays, East Asian optical component export restrictions, and Indian BIS hardware import specification revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Stadium and Arena Management Solution Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
Global Sports Management Software Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
UK Spectator Sports Market