
 Crossfit Apparel Market | 2026-2036
Crossfit Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Crossfit Apparel Market Outlook
Recycled polyester is rebalancing cost structures as virgin petroleum-based feedstocks face volatility and brand sustainability commitments harden. Nike Inc leverages its D2C platform and athlete co-design programs to sustain premium positioning in functional shorts and compression layers. Under Armour Inc anchors its North American wholesale relationships with moisture-wicking fabric technologies that dominate box retail. NOBULL competes through limited-drop scarcity models and Crossfit Games sponsorships that reinforce authenticity with core practitioners.
Crossfit apparel encompasses performance-engineered garments designed for high-intensity functional movement, typically incorporating four-way stretch fabrics with 15-25% elastane content, flatlock seam construction, and abrasion-resistant panels for rope climbs and barbell contact. The primary commercial purpose centers on delivering durability, thermoregulation, and unrestricted mobility during varied metabolic conditioning and Olympic lifting protocols. Polyester-spandex blends command the largest volume share due to superior sweat management and shape retention across repeated wash cycles. Gym boutiques and specialty stores capture the highest margin pools through personalized fitting services and community-based merchandising tied to local affiliate identities.
The US Federal Trade Commission monitors green marketing claims under its Green Guides, pressuring brands to substantiate recycled content percentages and biodegradability assertions. The EU Green Deal and REACH chemical restrictions are reshaping dyeing processes and antimicrobial treatments permitted in imported athletic textiles. California's SB 657 disclosure requirements and the EU's Corporate Sustainability Reporting Directive add compliance layers to multi-channel supply chains. Stakeholders must monitor how evolving extended producer responsibility frameworks in key demand centers will redistribute cost burdens between manufacturers, distributors, and end consumers.
Market Dynamics
Recycled polyester feedstock economics are compressing virgin material premiums while EU REACH chemical restrictions force reformulation of antimicrobial treatments across textile supply chains.
Growth Catalysts
- EU Green Deal compliance mandates:Extended producer responsibility frameworks in Germany and France are accelerating demand for certified recycled content in performance apparel, pushing brands to secure GRS-certified supply chains.
- Affiliate gym density concentration:The United States maintains over 5,000 Crossfit boxes with sustained membership growth, creating captive local merchandising channels for box-branded apparel and coach-endorsed product lines.
- Bio-based elastane breakthroughs:DuPont's Sorona polymer and similar plant-derived spandex alternatives are reducing petroleum dependency in four-way stretch fabrics while maintaining 15-25% elastane performance thresholds.
Market Restraints
- Petroleum feedstock volatility:Virgin polyester and spandex prices swing with crude oil markets, compressing margins for mid-tier brands unable to lock long-term recycled material contracts.
- Asian dyeing concentration:Over 70% of global textile dyeing capacity sits in China's Zhejiang and Guangdong provinces, exposing supply chains to water-use restrictions and power rationing under dual carbon goals.
- Antimicrobial treatment bans:EU REACH restrictions on triclosan and silver nanoparticles are eliminating legacy odor-control chemistries, forcing costly reformulation cycles.
Strategic Opportunities
- Australia affiliate expansion:Melbourne and Sydney box growth outpaces North American saturation, with lower brand clutter creating white space for premium positioning.
- Digital fitting integration:3D body scanning and AI size prediction are reducing return rates for direct-to-consumer functional apparel, compressing customer acquisition costs.
- US IRA clean manufacturing credits:Domestic recycled fiber production incentives are reshoring polyester chip capacity, shortening lead times for North American cut-and-sew operations.
Industry Challenges
- Technical pattern engineering:Flatlock seam construction for barbell abrasion zones requires specialized machinery and skilled operators scarce outside established manufacturing clusters.
- Multi-jurisdiction labeling compliance:California's SB 657 disclosure requirements, EU textile labeling directives, and Australia's ACCC consumer guarantees demand divergent packaging and documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crossfit Apparel Market |
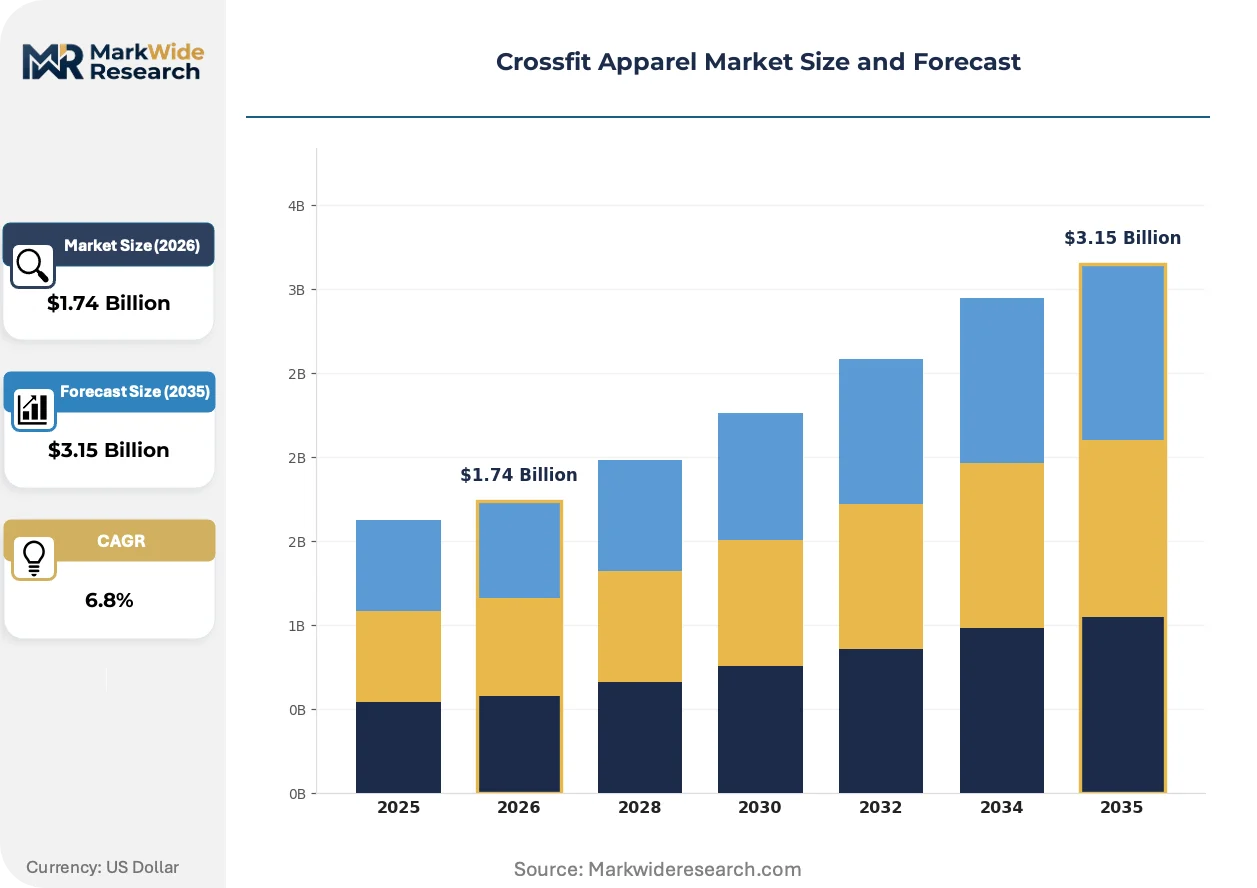
| Market Size in 2026 | $1.74 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shorts, T-Shirts, Tank Tops, Hoodies Material: Cotton, Polyester, Nylon, Spandex End User: Men, Women, Youth, Professionals Distribution Channel: Online Retail, Specialty Stores, Department Stores, Gym Boutiques |
| Companies Covered | Nike Inc, Adidas AG, Reebok International Ltd, Under Armour Inc, PUMA SE, NOBULL, ASICS Corporation, Columbia Sportswear Company, Patagonia Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crossfit Apparel Market Strategic Shifts
Material science convergence with regulatory chemistry restrictions is redefining performance benchmarks, while distribution fragmentation between wholesale box retail and direct-to-consumer channels accelerates.
Seamless knitting technology is integrating 3D jacquard construction that eliminates cut-and-sew assembly for compression layers. Tier-one manufacturers in Portugal and Turkey are adopting Stoll and Shima Seiki whole-garment machines to produce anatomically mapped ventilation zones without seam failure points. This compression of assembly steps is integrating localized production models that bypass Asian dyeing-house concentration.
REACH chemical restrictions are eliminating per- and polyfluoroalkyl substances from water-repellent finishes across imported athletic textiles. German and French customs authorities now require third-party certification for PFAS-free claims on performance shorts and outer layers. Mid-tier brands sourcing from non-EU dye houses face extended compliance timelines and reformulation costs that favor vertically integrated competitors with captive finishing capacity.
Athlete co-design platforms are displacing traditional seasonal wholesale buying cycles. Competitive Crossfit Games participants and affiliate owners now participate in limited-drop product development through Instagram and Strava-integrated feedback loops. This channel disintermediation is most visible in the United States, where NOBULL and smaller direct-to-consumer labels capture margin pools previously held by sporting goods retailers through scarcity-driven release calendars tied to competition seasons.
Crossfit Apparel Market Segmentation
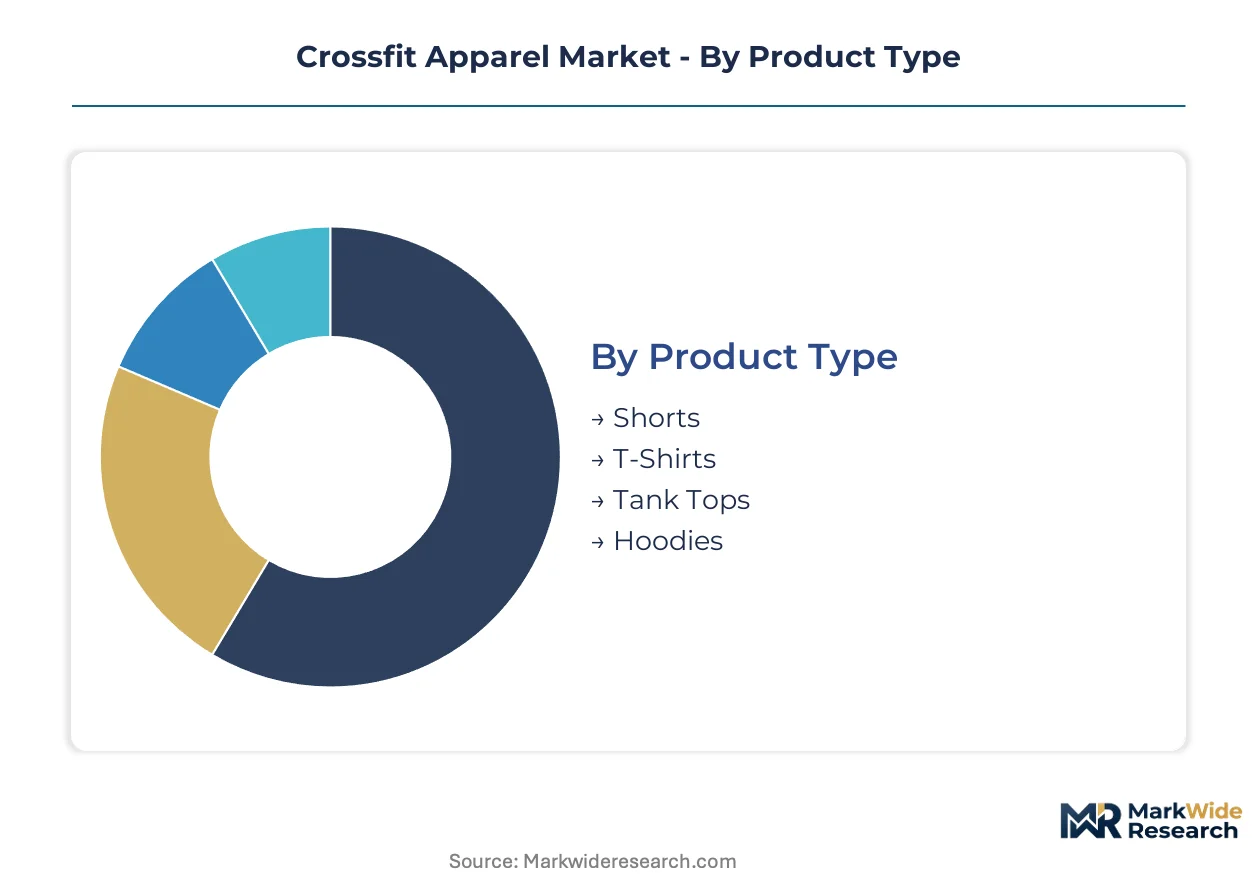
Crossfit apparel segmentation reflects the tension between performance engineering specifications and community-based distribution channels. Athletes select garments based on movement patterns, box affiliation identity, and competition requirements rather than conventional fashion cycles.
Product Type:
Four-way stretch engineering and abrasion resistance define competitive positioning across garment categories.
- Shorts:Compression-lined variants with 15-25% elastane content dominate box retail through reinforced barbell-contact panels and silicone waistband grips. Demand concentrates in United States affiliate channels where coach endorsement drives replacement cycles.
- T-Shirts:Moisture-wicking polyester-spandex blends with flatlock underarm construction command premium positioning. Australian box growth is accelerating technical fabric adoption among amateur competitors seeking Games-adjacent aesthetics.
- Tank Tops:Racerback designs with dropped armholes optimize overhead mobility for Olympic lifting protocols. German affiliate density supports specialized fitting services.
- Hoodies:Pre-shrunk cotton-poly fleece with reinforced kangaroo pockets addresses post-workout thermoregulation. Seasonal demand spikes in North American winter training cycles.
Mature deployment sits with Shorts. Newer deployment is concentrated in Hoodies as lifestyle crossover expands addressable occasions.
Material:
Raw material selection balances petroleum dependency against recycled feedstock certification requirements.
- Polyester:Recycled chip variants certified under Global Recycled Standard are compressing virgin material premiums. EU Green Deal compliance mandates in Germany and France are forcing mid-tier brands to secure GRS supply chains or exit premium positioning.
- Spandex:Bio-based elastane alternatives from DuPont Sorona polymer reduce crude oil exposure while maintaining four-way stretch thresholds. REACH chemical restrictions are eliminating legacy antimicrobial treatments bonded to spandex fibers.
- Cotton:Ring-spun combed variants retain box-branded merchandise share through natural fiber preference among recreational athletes. Water-intensive cultivation economics constrain margin expansion.
- Nylon:Cordura-reinforced panels target rope-climb abrasion zones in competitive athlete segments. Limited dye-house compatibility restricts color range versus polyester alternatives.
Volume concentration favors Polyester. Steepest expansion trajectory belongs to Spandex as bio-based chemistry matures.
End User:
Gender-specific pattern engineering and size grading create distinct technical requirements across participant categories.
- Men:Relaxed-fit shorts with 9-inch inseams and compression base layers dominate United States box retail. Coach-endorsed product lines sustain premium pricing through community credibility transfer.
- Women:High-waisted leggings with tummy-control panels and sports-integrated crop tops command direct-to-consumer margin pools. Melbourne and Sydney affiliate expansion is accelerating demand for inclusive size ranges.
- Youth:Scaled-down pattern blocks with reinforced knee panels address growth-spurt durability concerns. Parental purchase decisions prioritize value positioning over technical specification.
- Professionals:Games athletes and affiliate owners access co-design platforms and limited-drop scarcity models. Instagram-integrated feedback loops displace traditional wholesale buying cycles.
Revenue concentration rests with Men. Gaining share fastest is Women as female participation rates in functional fitness climb.
Distribution Channel:
Channel selection determines margin capture, inventory risk allocation, and brand authenticity signaling.
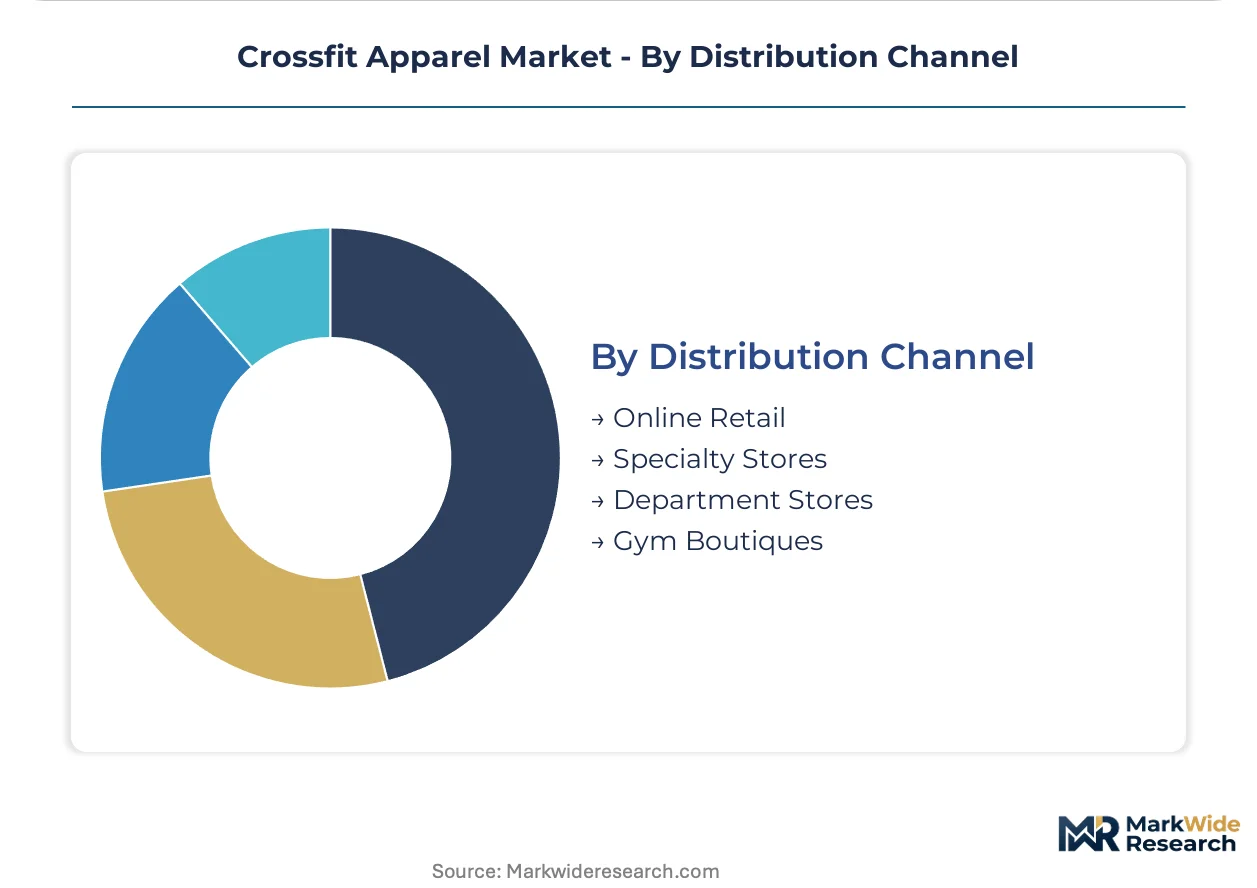
- Gym Boutiques:Personalized fitting services tied to local affiliate identity command highest margin pools. United States box density over 5,000 locations creates captive local merchandising channels for coach-endorsed lines.
- Online Retail:Direct-to-consumer platforms with AI size prediction compress return rates and customer acquisition costs. NOBULL and specialty labels capture margin pools previously held by sporting goods retailers.
- Specialty Stores:Curated functional fitness assortments with technical staff training support premium positioning. Urban concentration in Germany and Australia limits rural penetration.
- Department Stores:Mass-market accessibility through seasonal wholesale buying cycles sacrifices margin for volume scale. Athlete authenticity perception lags specialty channels.
Margin optimization centers on Gym Boutiques. Digital infrastructure investment is concentrating in Online Retail as 3D body scanning technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates where affiliate gym density and competition participation rates remain highest. The United States, Germany, and Australia anchor volume, with regulatory pressure and material innovation reshaping supply economics across these centers.
United States
Over 5,000 Crossfit boxes sustain captive local merchandising channels for coach-endorsed product lines. The FTC Green Guides pressure brands to substantiate recycled content claims under federal consumer protection authority. Domestic recycled fiber production incentives through IRA clean manufacturing credits are reshoring polyester chip capacity to shorten lead times for North American cut-and-sew operations.
Germany
Affiliate density in Berlin and Munich supports specialized fitting services tied to local box identities. EU REACH chemical restrictions and extended producer responsibility frameworks accelerate demand for GRS-certified recycled content in performance apparel. The ECHA enforcement of PFAS-free certification requirements at customs entry points favors vertically integrated competitors with captive finishing capacity.
Australia
Melbourne and Sydney box growth outpaces North American saturation, with lower brand clutter creating white space for premium positioning. The ACCC consumer guarantees framework imposes divergent documentation workflows alongside EU and US labeling regimes. Technical fabric adoption accelerates among amateur competitors seeking Games-adjacent aesthetics in Queensland and Victoria training clusters.
United Kingdom
London and Birmingham affiliate networks sustain demand for moisture-wicking compression layers through community-based merchandising. The EU Green Deal compliance mandates applicable through retained REACH regulations reshape dyeing process approvals for imported athletic textiles. Urban concentration limits rural penetration, concentrating specialty retail in metropolitan training corridors.
France
Paris and Lyon box expansion drives replacement cycles for abrasion-resistant shorts with reinforced barbell-contact panels. ANSM oversight of antimicrobial treatment safety profiles eliminates legacy odor-control chemistries from textile imports. The CSRD disclosure requirements add compliance layers to multi-channel supply chains serving French functional fitness practitioners.
Crossfit Apparel Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among athlete-authentic labels and volume scale captured by diversified sportswear conglomerates. The vendor base organizes around three strategic archetypes: global sportswear houses with D2C platforms and athlete co-design programs, vertically integrated specialists with limited-drop scarcity models, and sustainability-focused outdoor brands extending into functional fitness. Capacity expansion through seamless knitting technology adoption and strategic partnerships for recycled feedstock certification represent the dominant competitive vectors reshaping manufacturing economics.
Within the global sportswear tier, Nike Inc and Adidas AG exemplify scale-driven positioning anchored by wholesale box retail relationships and direct-to-consumer infrastructure. NOBULL occupies a specialist position representing athlete-authentic scarcity models tied to Crossfit Games sponsorships. Under Armour Inc sits within the North American wholesale vector, exemplifying moisture-wicking fabric technology dominance in affiliate channel distribution. These three anchors illustrate how brand credibility transfer through coach endorsement and competition proximity determines margin capture across divergent channel strategies.
| Leading Market Players |
|---|
| Nike Inc |
| Adidas AG |
| Reebok International Ltd |
| Under Armour Inc |
| PUMA SE |
| NOBULL |
| ASICS Corporation |
| Columbia Sportswear Company |
| Patagonia Inc |
| Others |
Value Chain & Pricing Dynamics
Specialized flatlock seam machinists in Portugal and Turkey command wage premiums that compress mid-tier brand margins and widen spreads between premium four-way stretch garments and economy polyester alternatives. Labor-cost differentials between established European manufacturing clusters and emerging cut-and-sew operations in North Africa directly shape three-tier pricing stratification across compression layers and abrasion-resistant shorts.
Pricing Analysis
Volume-mass positioning in economy polyester-spandex blends sacrifices margin for box retail scale, while premium bio-based elastane variants capture margin through GRS certification and limited-drop scarcity. Price differentiation hinges on recycled content verification and athlete co-design proximity, with standard-tier brands facing compression from both directions. Pricing pressure stems from petroleum feedstock volatility eroding mid-tier cost structures. Recreational athletes in youth and parent-driven segments exhibit highest price sensitivity; Games-adjacent professionals show least sensitivity to premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with China's Zhejiang and Guangdong provinces, where over seventy percent of global textile dyeing capacity faces water-use restrictions under dual carbon goals. Raw material flows draw from Taiwan for recycled polyester chip, Vietnam for cut-and-sew assembly, and Portugal for seamless knitting machinery. Supply chain risk centers on REACH chemical reformulation timelines disrupting antimicrobial treatment availability. Distribution runs through captive gym boutique channels in high-affiliate-density markets, supplemented by direct-to-consumer platforms with AI size prediction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over GRS-certified recycled feedstock and captive finishing capacity determines margin capture. Players are pursuing backward integration into polyester chip production to secure supply and compress lead times.
For Market Incumbents: Acquire seamless knitting machinery capacity in Portugal or Turkey to bypass Asian dyeing-house concentration and establish captive finishing for PFAS-free compliance. Consolidate box retail relationships through exclusive coach-endorsed product lines that transfer community credibility and defend against direct-to-consumer disintermediation. Lock long-term GRS-certified recycled polyester contracts before EU Green Deal mandates harden feedstock availability.
For New Entrants and Emerging Players: Begin with Melbourne and Sydney affiliate expansion, where lower brand clutter creates white space for premium positioning without incumbent saturation. Target women's high-waisted leggings and inclusive size ranges as the most penetrable segment given accelerating female participation rates. Launch through Instagram-integrated athlete co-design platforms to establish authenticity before wholesale channel investment.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated specialists possessing captive dyeing and finishing capacity given REACH enforcement acceleration at EU customs entry points. Long-term viability favors manufacturers with GRS certification and bio-based elastane chemistry partnerships over pure brand plays. Monitor ECHA PFAS-free certification requirement expansion as the inflection signal for competitive shakeout.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Production | Secures GRS-certified feedstock and shortens lead times for North American cut-and-sew under IRA incentives. |
| Seamless Knitting Technology Adoption | Stoll and Shima Seiki whole-garment machines eliminate seam failure points and bypass Asian dyeing concentration. |
| Athlete Co-Design Platform Launch | Instagram and Strava-integrated feedback loops displace seasonal wholesale cycles and capture premium margin pools. |
| PFAS-Free Finishing Certification | ECHA customs enforcement favors vertically integrated competitors with captive finishing capacity over mid-tier importers. |
| Australia Affiliate Channel Expansion | Melbourne and Sydney box growth outpaces North American saturation with lower brand clutter for premium positioning. |
Study Parameters
Multi-period observation of affiliate gym density, recycled feedstock pricing, and REACH regulatory enforcement anchored the trend analysis, supplemented by interviews with Crossfit box owners, apparel procurement managers at specialty retailers, textile chemists at dye houses, and sustainability compliance officers at branded manufacturers. Secondary validation drew from Global Recycled Standard certification databases, EU ECHA substance restriction updates, US FTC Green Guides enforcement actions, and customs trade records for polyester-spandex blend imports. Bottom-up affiliate channel surveys and top-down sportswear revenue triangulation cross-checked volume estimates.
Segment-weighting across product type, material composition, end-user gender category, and distribution channel shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating affiliate growth trajectories, material substitution rates, and regulatory compliance cost pass-through. Industry-specific inputs included DuPont Sorona polymer adoption curves, seamless knitting machinery installation counts, and digital fitting technology penetration rates.
Underlying measurement precision varies by segment; gym boutique channel data carries tighter precision than direct-to-consumer estimates due to affiliate density reporting. Forecasts reflect documented assumptions about recycled polyester cost compression and EU extended producer responsibility implementation timing. Macroeconomic volatility, petroleum price spikes, or accelerated antimicrobial treatment bans could materially revise trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
France Sports Teams and Clubs Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Smart Trainers Market
Sports & Fitness Technology
3D Motion Capture Market