
 Payment Processing Solutions Market | 2026-2036
Payment Processing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Payment Processing Solutions Market Analysis
Mid-market merchants and platform aggregators are redrawing procurement priorities across the payment stack. Stripe leverages developer-centric API architectures to anchor enterprise subscription billing workflows. Square sustains dominance in in-person commerce through integrated hardware-software ecosystems for small businesses. Adyen differentiates via single-platform global acquiring that navigates multi-currency settlement complexity.
Payment processing solutions encompass the hardware, software, and network infrastructure that authenticate, route, clear, and settle monetary transactions between buyers and sellers, operating on sub-second authorization latencies and tokenized data formats. These systems serve the commercial purpose of enabling frictionless exchange while managing fraud risk, regulatory compliance, and liquidity timing for merchants and financial institutions. Mobile payments and online transactions command the largest transaction volumes, though contactless and NFC technology segments are expanding fastest as tap-to-pay hardware penetrates transit and quick-service retail environments. Cloud-based integration solutions concentrate margin pools by reducing merchant IT overhead and accelerating feature deployment cycles compared to on-premise alternatives.
The US Federal Reserve and NACHA govern ACH network rules and real-time payment standards, while the European Banking Authority enforces PSD2 strong customer authentication requirements that reshape gateway authentication flows. India's RBI mandates tokenization protocols that limit raw card data exposure, directly influencing vaulting architecture decisions by processors. Stakeholders must monitor central bank digital currency pilots and instant payment network interoperability commitments that will determine next-generation routing infrastructure investments.
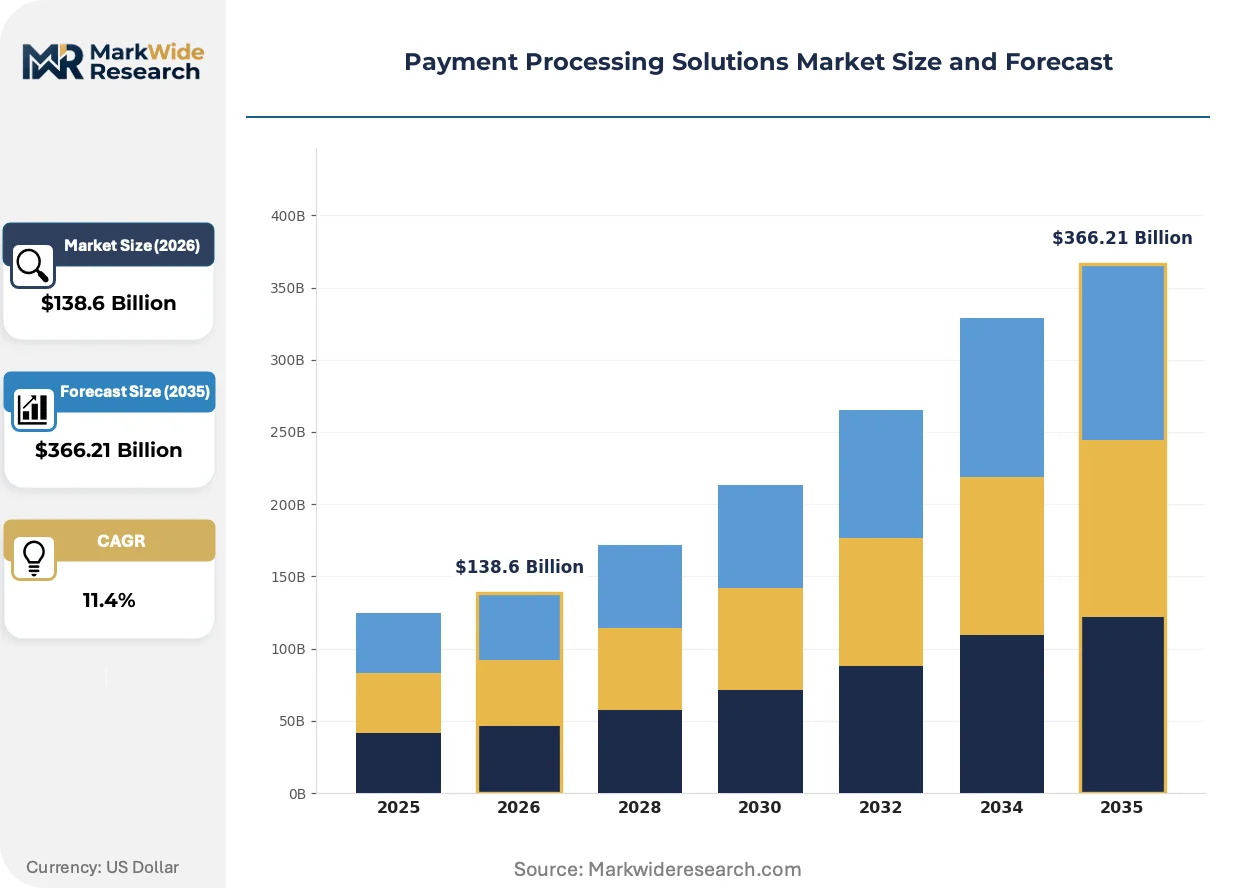
Market Dynamics
Merchant migration from legacy POS terminals to cloud-native orchestration layers is compressing hardware refresh cycles and redistributing margin pools toward software-centric platforms that embed fraud detection and working capital services.
Growth Catalysts
- India's UPI Rails:The National Payments Corporation of India has built real-time retail payment infrastructure that slashes merchant onboarding friction from weeks to hours, pulling millions of micro-merchants into formal digital acceptance networks.
- PCI DSS 4.0 Mandates:The Payment Card Industry Security Standards Council's updated compliance framework forces legacy processors to upgrade tokenization and encryption architectures, accelerating infrastructure replacement cycles.
- Embedded Finance Convergence:SaaS platforms are integrating payment acceptance with inventory management and lending, capturing merchant relationships that previously fragmented across separate vendors.
Market Restraints
- Interchange Fee Compression:Regulatory caps on swipe fees in the European Union and Australia squeeze acquirer margins, forcing volume-dependent business models that disadvantage smaller processors.
- Core Banking System Lock-in:Tier-1 banks in the United States and Germany maintain proprietary legacy cores that resist API integration, creating technical debt that slows real-time payment adoption.
- Fraud Liability Concentration:Chargeback dispute resolution costs concentrate disproportionately on mid-market merchants without sophisticated machine-learning fraud filters, raising effective processing costs.
Strategic Opportunities
- Brazil's Pix Instant Network:The Central Bank of Brazil's open instant payment rails enable non-bank fintechs to bypass traditional acquiring licenses, opening merchant segments previously captive to incumbent banks.
- SoftPOS Technology Diffusion:NFC-enabled smartphones are eliminating dedicated terminal hardware for micro-merchants, collapsing distribution costs and enabling direct-to-merchant software sales.
- EU Open Banking APIs:PSD2-mandated account-to-account payment initiation services bypass card networks entirely, creating alternative rail economics for high-ticket B2B transactions.
Industry Challenges
- Token Vault Interoperability:Network-specific tokenization schemes from Visa, Mastercard, and domestic schemes fragment card-on-file portability, forcing merchants to maintain redundant vault architectures.
- Cross-Border Settlement Latency:Correspondent banking relationships and FX hedging requirements stretch settlement timelines for multi-currency merchants, complicating working capital forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payment Processing Solutions Market |
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $366.21 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Payments, Online Transactions, In-Store Payments, Virtual Accounts Technology: Contactless, EMV, NFC, Blockchain Customer Type: Small Businesses, Enterprises, Freelancers, Non-Profits Integration Level: API-Based, Hosted Solutions, On-Premise Systems, Cloud Solutions |
| Companies Covered | Square, JPMorgan Chase, Stripe, Nuvei, Fiserv, PayPal, Worldpay, Global Payments, Adyen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payment Processing Solutions Market Emerging Trajectories
Payment infrastructure is decoupling from physical terminals, with software-defined orchestration layers absorbing functions previously locked in proprietary hardware stacks.
Tap-to-pay functionality on standard smartphones is miniaturizing the acceptance device footprint. Quick-service restaurants and transit operators in South Korea and the United Kingdom are piloting staff-free checkout lanes where consumer phones initiate proximity payments without dedicated POS hardware. This compression eliminates terminal procurement cycles and shifts merchant CapEx to SaaS subscription models.
India's RBI mandates card-on-file tokenization protocols that prohibit raw card number storage, forcing merchants and aggregators to re-architect data vaults. Payment gateways must now integrate with multiple token service providers, increasing integration complexity but reducing breach liability exposure. E-commerce platforms with large recurring billing bases face the steepest migration timelines.
Merchant procurement of payment services is consolidating through vertical software platforms that embed checkout as a feature rather than a standalone purchase. Restaurant management systems in the United States and property management software in Germany are bundling payment acceptance with core operational tools, displacing independent sales organizations that previously dominated merchant acquisition. This channel shift compresses sales cycles but raises platform dependency risks for processors.
Payment Processing Solutions Market Segmentation
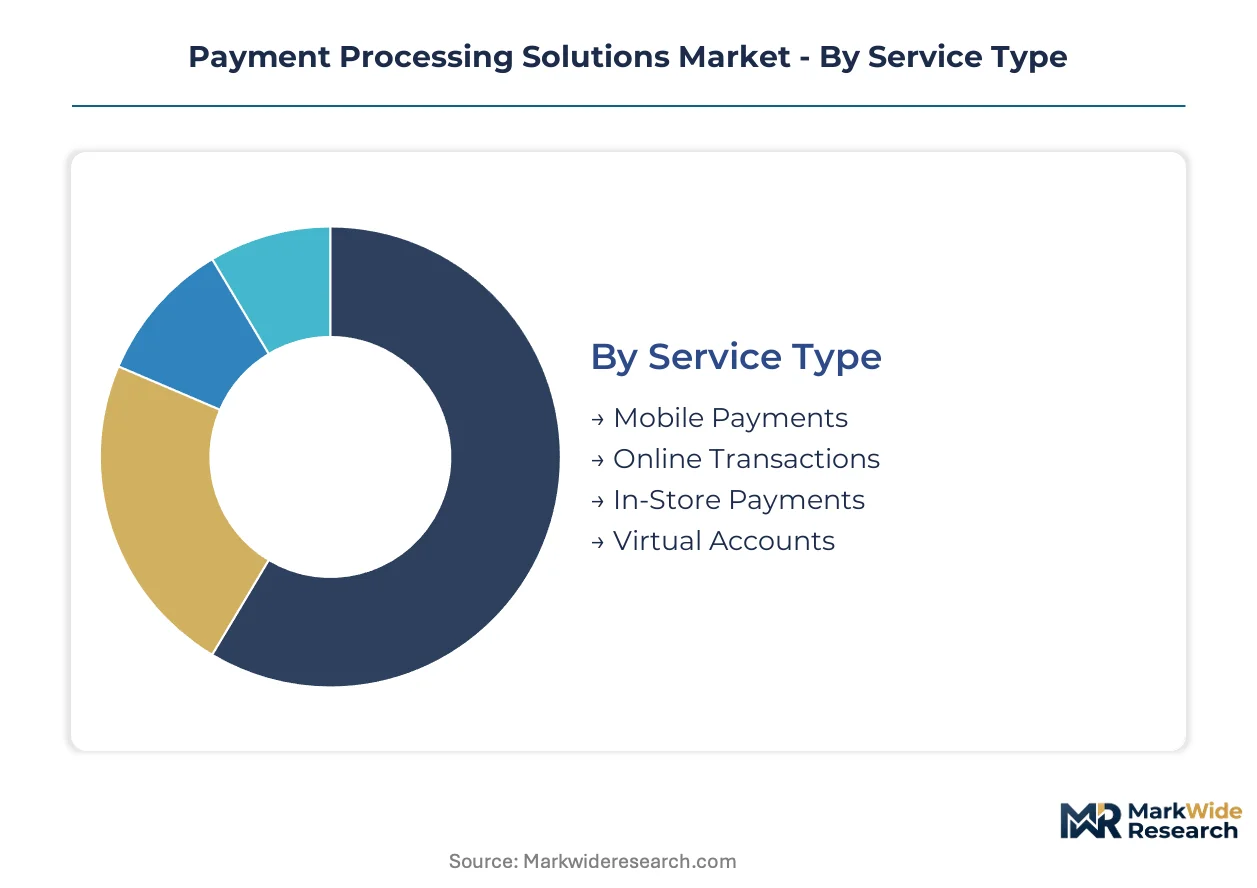
Payment processing solutions fragment across four structural dimensions that determine procurement economics. Service type and technology choices anchor transaction economics, while customer scale and integration architecture dictate platform selection criteria for merchants and financial institutions.
Service Type:
Margin pools concentrate in transaction volume density and interchange rate capture, with digital-native formats commanding premium economics over legacy rails.
- Mobile Payments:Smartphone-native transaction rails leveraging device biometrics and tokenized credentials for in-app and browser-based commerce. India's UPI infrastructure and Brazil's Pix network are pulling micro-merchants into mobile-first acceptance, compressing hardware requirements and accelerating onboarding velocity.
- Online Transactions:E-commerce gateway protocols handling card-not-present authentication, 3D Secure routing, and fraud scoring across merchant websites and marketplaces. Subscription billing platforms and cross-border marketplaces are driving demand for multi-currency settlement and recurring payment vaulting.
- In-Store Payments:Physical terminal and integrated POS systems processing card-present transactions with chip-and-PIN or signature verification. Quick-service retail and grocery chains maintain dominant volume share despite terminal refresh cycle compression.
- Virtual Accounts:Digital-only account structures enabling programmatic fund routing, escrow, and multi-party settlement without traditional banking infrastructure. B2B marketplaces and platform economies are adopting these for supplier payment orchestration.
The dominant share belongs to Online Transactions, while Mobile Payments is closing the gap fastest.
Technology:
Technology selection follows hardware deployment economics and regulatory authentication mandates, with proximity-based methods displacing magnetic stripe infrastructure.
- Contactless:Tap-to-pay protocols using RFID or NFC fields for sub-second transaction completion without physical card insertion. Transit authorities in South Korea and quick-service operators in the United Kingdom are eliminating cash handling through contactless-only lanes.
- NFC:Near-field communication standards enabling smartphone-to-terminal and phone-to-phone payment initiation. SoftPOS deployments are collapsing dedicated terminal requirements for micro-merchants in India and Southeast Asian markets.
- EMV:Chip-card authentication standards mandating dynamic cryptogram generation for counterfeit fraud prevention. Liability shift rules from card networks continue to force terminal upgrades in markets with lagging compliance.
- Blockchain:Distributed ledger settlement rails for cross-border remittance and stablecoin-based merchant payouts. Regulatory clarity gaps and volatility management limit mainstream merchant adoption outside specialized corridors.
Contactless infrastructure claims the largest installed base, though NFC-enabled SoftPOS is climbing the fastest as smartphone penetration eliminates hardware barriers.
Customer Type:
Customer segmentation reflects procurement complexity and service bundling requirements, with platform-embedded solutions capturing mid-market relationships.
- Small Businesses:Merchants with sub-$10M annual volume prioritizing all-in-one hardware-software bundles and flat-rate pricing transparency. Vertical SaaS platforms are displacing independent sales organizations through embedded checkout features.
- Enterprises:Large merchants and platforms requiring multi-acquirer routing, custom fraud rules, and international settlement across dozens of markets. Procurement concentrates on API flexibility and dedicated technical account management.
- Freelancers:Individual service providers needing invoicing-linked payment collection and rapid fund access. Mobile-first onboarding and instant payout features drive platform selection.
- Non-Profits:Donation-dependent organizations prioritizing low transaction fees and recurring giving automation. Grant compliance reporting and donor data portability shape vendor decisions.
Small Businesses generate the highest transaction count, while Enterprises concentrate revenue per relationship and platform stickiness.
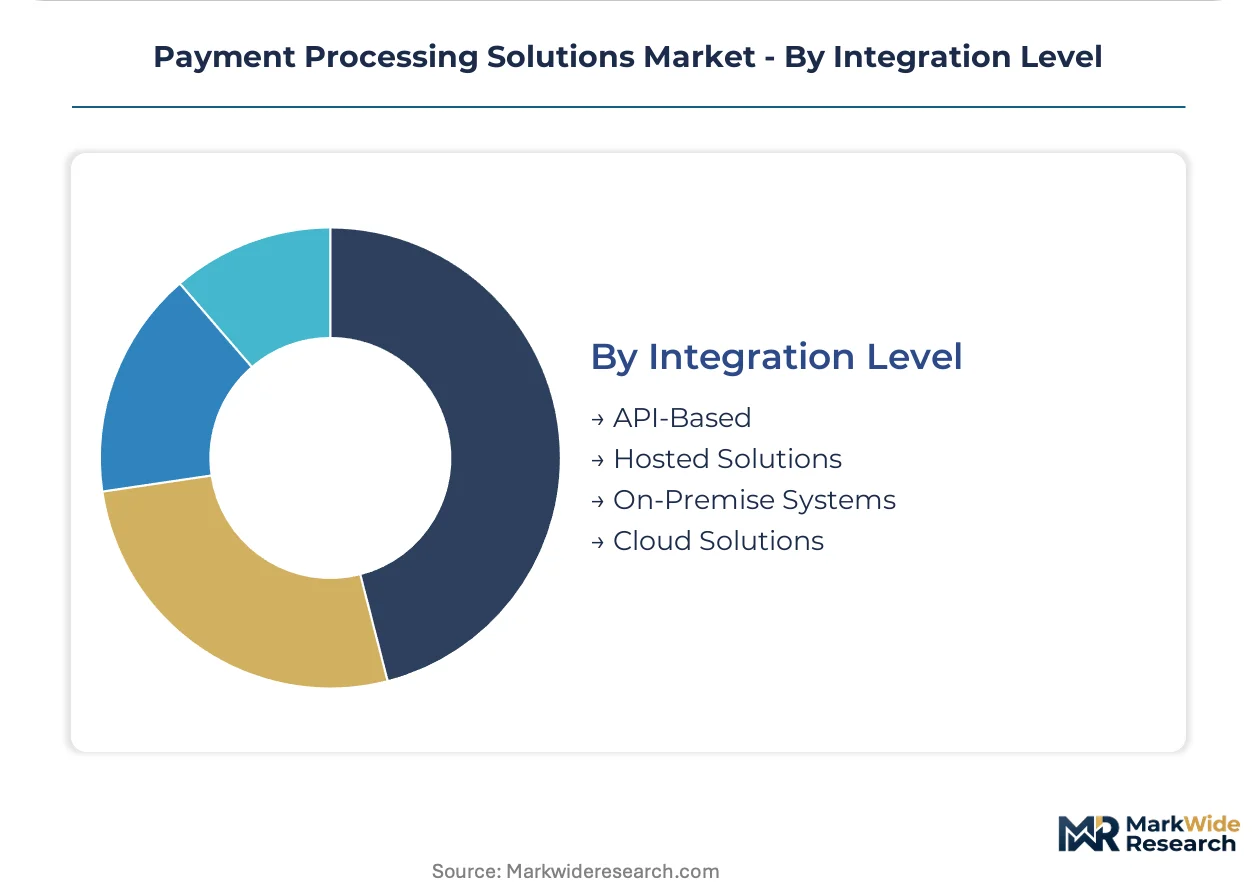
Integration Level:
Integration architecture determines merchant IT overhead and feature deployment velocity, with cloud-native options redistributing margin from legacy license models.
- Cloud Solutions:Multi-tenant SaaS platforms delivering automatic updates, elastic scaling, and reduced infrastructure management burden. Mid-market merchants are migrating from on-premise stacks to capture fraud model improvements and faster certification cycles.
- API-Based:Developer-centric integration patterns enabling custom checkout flows and embedded finance orchestration. Platform businesses and marketplaces require granular control over user experience and data routing.
- Hosted Solutions:White-labeled payment pages and redirect flows minimizing PCI DSS scope for smaller merchants. Redirect latency and branding limitations create friction for conversion-optimized e-commerce.
- On-Premise Systems:Locally installed software and hardware stacks retaining full data custody and customization control. Tier-1 retailers and regulated industries maintain these for legacy system integration and audit trail requirements.
Cloud Solutions hold the dominant deployment share, with API-Based integration gaining share fastest as platform businesses embed financial services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's UPI infrastructure exports processing architecture to Southeast Asian markets seeking real-time retail payment templates. Brazil's Pix network channels fintech investment from European venture capital into Latin American acquiring licenses. The United States maintains correspondent banking relationships that settle cross-border volumes for merchants in Canada and Mexico.
United States
Enterprise merchants and platform aggregators drive demand for multi-acquirer routing and subscription billing infrastructure. The Federal Reserve governs ACH network rules and instant payment standards through FedNow service specifications. New York and San Francisco host dense clusters of fintech infrastructure providers competing for mid-market merchant relationships.
India
Micro-merchants and quick-service retail operators migrate from cash to UPI-enabled acceptance at unprecedented velocity. The Reserve Bank of India mandates card-on-file tokenization protocols that prohibit raw card data storage in merchant systems. Mumbai and Bangalore concentrate payment gateway providers and token service provider integrations serving domestic e-commerce platforms.
Brazil
Non-bank fintechs and vertical SaaS platforms exploit instant payment rails to bypass traditional acquiring licenses. The Central Bank of Brazil's Pix network enables account-to-account settlement without card network intermediation. São Paulo anchors merchant acquiring competition as international processors establish local data residency compliance.
Germany
B2B marketplaces and industrial suppliers adopt virtual accounts for programmatic supplier payment orchestration. The European Banking Authority enforces PSD2 strong customer authentication requirements that reshape gateway authentication flows. Frankfurt and Berlin concentrate open banking API providers serving account-to-account payment initiation services.
United Kingdom
Transit authorities and quick-service operators pilot staff-free checkout lanes using consumer phone-initiated proximity payments. The Financial Conduct Authority regulates e-money issuance and payment institution licensing for fintech entrants. London hosts dense clusters of SoftPOS technology providers targeting European micro-merchant expansion.
Payment Processing Solutions Market Vendor Landscape
Listed leaders compete with private specialists across developer tooling and integrated hardware-software bundles. The market structures around three tiers: global acquiring platforms with multi-currency settlement capabilities, vertical SaaS providers embedding checkout as a feature, and regional processors serving compliance-intensive domestic markets. Dominant competitive moves include strategic partnerships with enterprise software platforms and geographic expansion through local acquiring license acquisition.
Within the developer-centric tier, Stripe and Square exemplify contrasting archetypes—API-first orchestration versus integrated terminal ecosystems. Adyen occupies a position bridging global acquiring and unified platform architecture. JPMorgan Chase anchors the bank-led segment through legacy correspondent relationships and commercial banking integration.
| Leading Market Players |
|---|
| Square |
| JPMorgan Chase |
| Stripe |
| Nuvei |
| Fiserv |
| PayPal |
| Worldpay |
| Global Payments |
| Adyen |
| Others |
Supply Flow & Price Mechanics
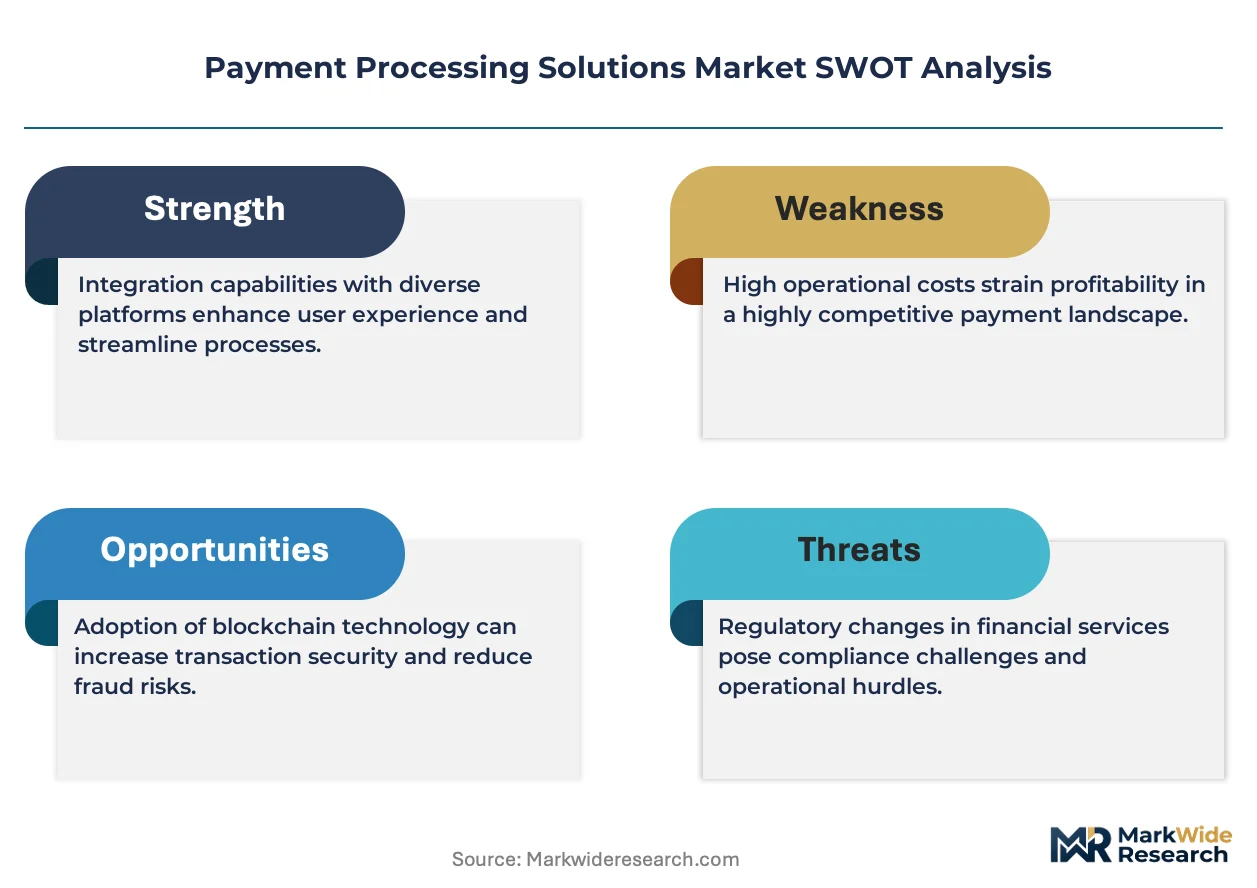
PCI DSS 4.0 certification gates both processor qualification and price differentiation simultaneously, as compliance investment requirements separate tier-1 acquirers from regional specialists while merchants pay premiums for tokenized vault architectures that reduce breach liability exposure.
Pricing Analysis
Current-gen cloud-native orchestration platforms command SaaS-tiered subscription premiums over prior-gen terminal-rental models, while next-gen SoftPOS deployments collapse hardware costs entirely. Three-tier pricing structure across enterprise API access, mid-market bundled solutions, and micro-merchant flat-rate tiers reflects volume scale and customization depth as primary differentiation drivers. Cost compression in the micro-merchant segment intensifies because SoftPOS eliminates terminal procurement, forcing processors to absorb hardware margin loss through software monetization. Small businesses exhibit highest price sensitivity to per-transaction rates, while enterprises prioritize API flexibility over marginal basis-point savings.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for NFC chipsets and terminal hardware components manufactured in Taiwan, South Korea, and Vietnam. Payment hardware supply draws from semiconductor foundries in Taiwan, plastic card manufacturing in China, and secure element production in Germany. Single-source vulnerability concentrates in EMV chip supply where three vendors dominate global certification. Distribution runs through authorized reseller networks and direct-to-merchant SaaS platforms, with vertical software partnerships capturing accelerating share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards scarce capabilities in real-time payment network integration and multi-currency settlement orchestration, creating acquisition premiums for teams with proven FedNow or UPI rail connectivity.
For Market Incumbents: Compound platform stickiness through embedded finance convergence, integrating lending and inventory management alongside core acceptance to raise switching costs for mid-market merchants. Deepen API documentation and sandbox environments to defend against developer-centric challengers. Prioritize local acquiring license acquisition in Brazil and India where regulatory data residency requirements gate market access. For New Entrants and Emerging Players: PCI DSS 4.0 fast-track certification programs in the European Union and Singapore open white-space entry for specialized token service providers serving e-commerce platforms with large recurring billing bases. Target India's micro-merchant segment where UPI onboarding friction has collapsed to hours but working capital services remain underdeveloped. Pursue vertical SaaS partnership channels rather than direct merchant acquisition to bypass incumbent ISO networks. For Investors and Strategic Acquirers: Central bank digital currency pilot announcements reshape the acquisition landscape by signaling which processors have invested in programmable money infrastructure. Long-term viability hinges on owning orchestration layers rather than commodity acquiring relationships. Monitor token vault interoperability standards as the signal for which processor architectures will retain merchant portability versus face disintermediation.| Strategic Initiative | Industry Significance |
|---|---|
| SoftPOS Technology Deployment | NFC-enabled smartphones eliminate dedicated terminal hardware for India's micro-merchant expansion. |
| Multi-Acquirer Routing Integration | Enterprise merchants demand failover capabilities across Stripe, Adyen, and regional processors. |
| Token Service Provider Partnership | RBI-mandated card-on-file tokenization forces gateway re-architecture for recurring billing platforms. |
| Embedded Finance Orchestration | Vertical SaaS platforms bundle payment acceptance with inventory and lending to capture relationships. |
| Local Acquiring License Acquisition | Brazil's Pix network and India's data residency rules require domestic infrastructure for market access. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with payment gateway CTOs, merchant acquiring executives, token service provider product leads, and vertical SaaS platform founders; and secondary validation against RBI circulars, ECB PSD2 implementation reports, NACHA operating rules, SEC 10-K filings from listed processors, and FedNow service specifications. Bottom-up merchant volume estimates triangulated against top-down payment network disclosure data.
Across the projection horizon, the analytical framework modeled service type, technology protocol, customer scale, and integration architecture dimensions alongside regional regulatory cluster variations. CAGRs derived from segment-level volume trajectories and pricing elasticity assumptions, with cross-border settlement latency and token vault migration timelines as key payment-specific forecast inputs.
Underlying assumptions cover central bank digital currency pilot progression timelines and instant payment network interoperability commitments, with deviation risk concentrated in regulatory interchange fee caps and core banking system modernization velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Tanzania Mobile Money Market
Payments
United States Payments Market
Payments
Instant Payments Market
Payments
UAE Card Payments Market
Payments
Blockchain Payments Software Market
Payments
Saudi Arabia Mobile Payments Market
Payments
Denmark Payments Market
Payments
Forex Cards Market
Payments
Sweden Mobile Payments Market
Payments
Asia-Pacific Digital Remittance Market
Payments
GCC Mobile Payment Market
Payments
Latin America Retail Cash Management Market
Payments
Europe Payment Analytics Software Market
Payments
Mobile Payment Security Market
Payments
Payment Orchestration Platform Market
Payments
China Virtual Cards Market