
 Latin America Bike Sharing Market | 2026-2036
Latin America Bike Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Bike Sharing Market Foresight
ISO 4210 bicycle safety certification is unwinding competitive barriers across Latin America, forcing fleet operators to upgrade hardware compliance before municipal tenders open. Tembici leverages its vertically integrated maintenance hubs to sustain ISO-compliant fleet rotation across Brazilian state capitals. Grow Mobility anchors its Colombian operations with localized assembly partnerships that reduce import duty exposure. Bird competes through diversified micromobility licensing, though its bike-sharing footprint remains narrower than dedicated regional specialists.
Bike sharing in Latin America encompasses docked, dockless, and hybrid bicycle rental systems deployed for short-distance urban transit, typically integrating GPS-enabled locks, mobile payment gateways, and IoT telemetry for fleet redistribution. These systems reduce last-mile congestion in dense metropolitan corridors where formal transit coverage gaps persist. The service type dimension shows dockless systems capturing disproportionate capital flow due to lower infrastructure capex requirements, while subscription-based models concentrate recurring revenue in university and corporate campus deployments. Technology segmentation reveals mobile app integration as the baseline entry requirement, with smart lock reliability emerging as the primary operational differentiator between incumbent and challenger fleets.
Brazil's ANTT federal transport guidelines, Mexico City's mobility regulatory framework, and Colombia's national sustainable urban development standards collectively shape fleet permitting, parking zone designation, and data-sharing obligations across the region. EMA-equivalent environmental benchmarks in select municipalities further constrain fleet electrification timelines and carbon-offset reporting. Stakeholders must monitor evolving sub-national procurement rules, as city-level concession terms increasingly mandate local employment quotas and open-data APIs as non-negotiable bid requirements.
Market Dynamics
Municipal sustainability mandates across Brazilian, Mexican, and Colombian capitals are forcing fleet operators to restructure deployment economics around ISO 4210 certification timelines and open-data API requirements before tender eligibility.
Growth Catalysts
- Dockless GPS Integration:GPS-enabled smart locks eliminate fixed station infrastructure costs, accelerating fleet deployment in dense urban corridors where formal transit coverage gaps persist.
- Brazil's ANTT Federal Guidelines:National transport standardization creates uniform permitting frameworks that reduce regulatory friction for interstate fleet operators.
- Corporate Campus Subscriptions:Recurring revenue models concentrate demand in São Paulo and Mexico City business districts, stabilizing utilization rates during off-peak commuter hours.
Market Restraints
- Import Duty Exposure:Non-localized assembly partnerships face 35-60% effective duty burdens on Chinese-manufactured hardware, compressing margin structures for new market entrants.
- Lithium-Ion Battery Supply Concentration:Fleet electrification timelines depend on East Asian cell suppliers, creating vulnerability to shipping cost volatility and customs processing delays.
- Colombia's Data-Sharing Obligations:Municipal open-data mandates impose telemetry infrastructure costs that disproportionately burden sub-scale operators.
Strategic Opportunities
- Peruvian Andean Corridor:Lima's expanding metro integration gaps and altitude-constrained private vehicle usage create white-space demand for pedal-assisted dockless networks.
- EMA-Equivalent Carbon Offset Mandates:Select municipalities in São Paulo state now require fleet-level carbon reporting, creating first-mover advantage for operators with verified offset partnerships.
- IoT-AI Convergence:Predictive redistribution algorithms layered on real-time lock telemetry reduce rebalancing labor costs by 20-30% versus rule-based dispatch systems.
Industry Challenges
- ISO 4210 Certification Timeline:Hardware compliance upgrades require 8-14 month validation cycles, forcing fleet rotation pauses that strain municipal contract renewal schedules.
- Smart Lock Reliability Variance:Bluetooth-GPS module failure rates above 12% annually trigger customer churn and maintenance hub congestion in high-humidity coastal deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Bike Sharing Market |
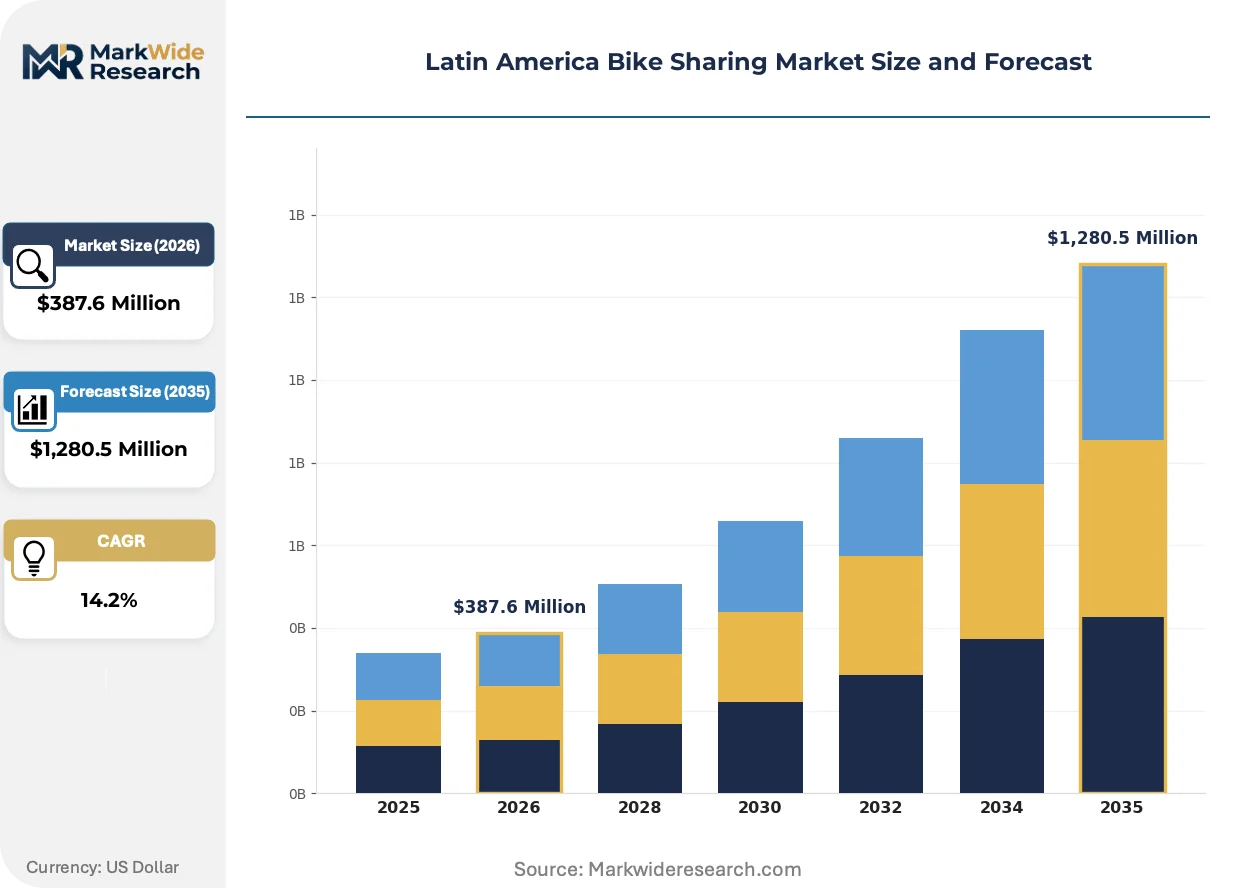
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Public Stations, Dockless, Hybrid, Subscription-Based End User: Commuters, Tourists, Universities, Government Agencies Operational Model: Free-Use, Pay-Per-Ride, Monthly Pass, Annual Membership Technology: Mobile App, GPS Tracking, Payment Integration, Smart Locks |
| Companies Covered | Tembici, Bim Bikes, Grow Mobility, Loop, Mobike, Ecobici, Wave, Bird, Encicla, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Bike Sharing Market Shifts & Advancements
Hardware standardization and predictive fleet management systems are compressing the operational gap between dedicated bike-sharing specialists and diversified micromobility platforms.
Modular battery-swappable e-bike architectures are decomposing the traditional fixed-battery fleet model. Municipal operators in São Paulo and Mexico City are piloting hot-swap stations that reduce vehicle downtime from 4-hour charging cycles to 90-second exchanges. This is decomposing capital intensity requirements for electrified fleets, enabling smaller operators to match incumbent range specifications without captive charging infrastructure.
Mexico City's mobility regulatory framework now mandates geofenced parking zones with automated fine issuance for non-compliant dockless deployments. The policy compresses sidewalk clutter incidents but forces operators to renegotiate hardware firmware with third-party lock suppliers. University and corporate campus segments face the steepest compliance costs due to fragmented zone boundary definitions across institutional properties.
Subscription-based procurement is displacing per-ride payment dominance in high-frequency commuter corridors. São Paulo's southeastern business district employers now bundle bike-sharing access into mobility benefit packages, bypassing app-store transaction fees. This shift concentrates revenue predictability among B2B channel partners rather than dispersed consumer wallets.
Latin America Bike Sharing Market Segmentation
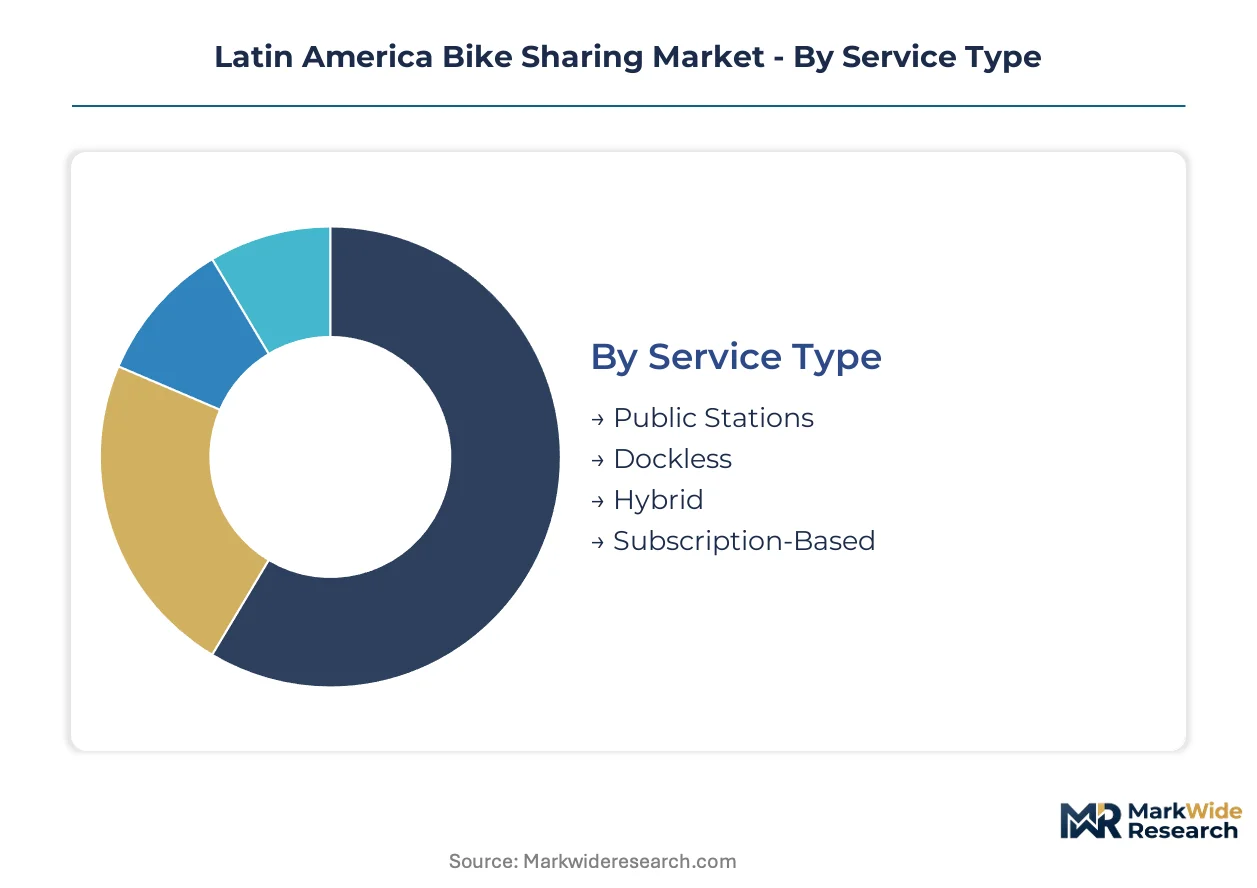
Segmentation in Latin America's bike sharing market reveals how capital efficiency, regulatory compliance, and user retention mechanics fragment across deployment archetypes. Fleet operators optimize around distinct margin structures that favor asset-light dockless models in dense urban cores versus subscription stability in institutional corridors.
Service Type:
Margin pools concentrate in dockless deployments where infrastructure capex elimination offsets higher per-unit hardware costs, while hybrid systems capture premium positioning through regulatory compliance arbitrage.
- Public Stations:Fixed docking infrastructure demands municipal concession agreements and dedicated right-of-way permits. São Paulo's southeastern corridor sustains this model through Tembici-operated networks where station density correlates with metro integration gaps.
- Dockless:GPS-enabled smart locks eliminate fixed infrastructure, enabling rapid fleet scaling in Bogotá and Mexico City corridors where sidewalk parking zones are geofenced. Lower capex thresholds attract challenger operators despite higher rebalancing labor intensity.
- Hybrid:Combines fixed stations with flexible drop-off zones, requiring dual compliance with municipal parking mandates and station maintenance obligations. Operational complexity limits this model to incumbent operators with established maintenance hub networks.
- Subscription-Based:Recurring revenue concentration in university and corporate campus deployments stabilizes utilization rates during off-peak hours. São Paulo business district employers increasingly bundle access into mobility benefit packages.
The dominant share belongs to Dockless, while Subscription-Based is closing the gap fastest through B2B channel expansion.
End User:
Customer acquisition costs and ride frequency patterns diverge sharply between daily commuters seeking predictable transit alternatives and institutional purchasers optimizing for bulk access.
- Commuters:Daily trip volumes concentrate in São Paulo, Mexico City, and Bogotá metropolitan corridors where formal transit coverage gaps persist. Peak-hour demand spikes require predictive redistribution algorithms to maintain vehicle availability.
- Tourists:Seasonal demand spikes in Rio de Janeiro and coastal Colombian municipalities strain fleet availability during high-traffic periods. Operators deploy supplemental seasonal fleets with simplified payment onboarding for international visitors.
- Universities:Campus-bound deployments benefit from captive demand density and simplified zone boundary definitions. Mexico City's institutional properties face fragmented compliance costs due to overlapping municipal and campus parking regulations.
- Government Agencies:Municipal procurement mandates local employment quotas and open-data APIs as non-negotiable bid requirements. ANTT federal guidelines in Brazil standardize permitting frameworks for interstate fleet operators serving public sector contracts.
Commuters generate the highest trip volumes, though Government Agencies are expanding fastest through tender-driven fleet modernization programs.
Operational Model:
Revenue predictability escalates from transactional per-ride payments toward locked-in subscription commitments, with hybrid pricing tiers capturing intermediate user segments.
- Free-Use:Limited pilot deployments in select Colombian municipalities where carbon offset mandates subsidize operational costs. Sustainability grant dependency creates revenue volatility for operators relying on this structure.
- Pay-Per-Ride:Dominates tourist and occasional user segments through app-store payment gateways. Transaction fee erosion and customer churn susceptibility compress margins for operators without subscription conversion pathways.
- Monthly Pass:Corporate campus and university procurement increasingly favors this tier for employee and student benefit packages. São Paulo employers bypass app-store fees through direct B2B billing relationships.
- Annual Membership:Highest retention rates among daily commuters with predictable route patterns. Upfront cash flow benefits operators with sufficient balance sheet capacity to absorb deferred revenue recognition.
Pay-Per-Ride retains volume leadership, yet Monthly Pass is gaining share fastest as employer-sponsored mobility benefits displace individual consumer subscriptions.
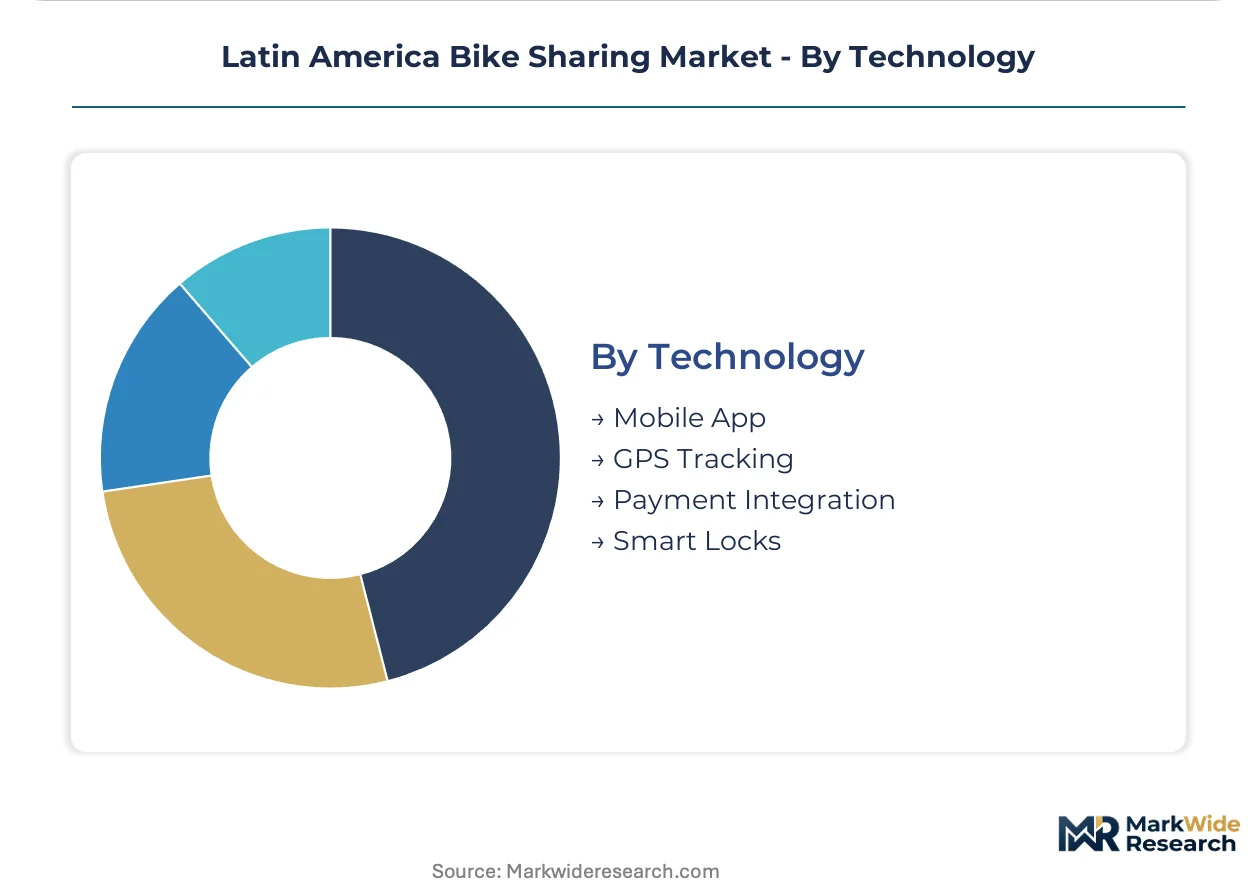
Technology:
Operational differentiation hinges on telemetry reliability and payment friction reduction, with smart lock failure rates emerging as the primary churn driver in high-humidity coastal deployments.
- Mobile App:Baseline entry requirement across all service types, with user experience optimization concentrating on route planning integration with formal transit networks. São Paulo operators prioritize real-time metro connection displays.
- GPS Tracking:Enables fleet redistribution algorithms and geofenced parking compliance. Mexico City's automated fine issuance for non-compliant dockless deployments depends on sub-meter positioning accuracy.
- Payment Integration:Localized gateway partnerships reduce transaction abandonment in markets with fragmented digital payment adoption. Brazilian operators integrate PIX instant payment protocols to bypass card network fees.
- Smart Locks:Bluetooth-GPS module reliability determines maintenance hub congestion and customer satisfaction scores. Failure rates above 12% annually trigger contract renewal risks in municipal tender evaluations.
Mobile App penetration is universal, though Smart Locks are climbing the fastest as predictive maintenance capabilities separate incumbent and challenger fleet performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal transport guidelines and municipal sustainability mandates across Brazilian, Mexican, and Colombian capitals are accelerating fleet modernization timelines and reshaping concession procurement criteria.
Brazil
São Paulo's southeastern business corridor drives fleet density through metro integration gaps and employer-sponsored mobility benefit packages. ANTT federal guidelines standardize interstate permitting frameworks for operators spanning multiple state capitals. Tembici-operated networks anchor deployment in Rio de Janeiro and Belo Horizonte, with ISO 4210 certification requirements forcing hardware upgrade cycles ahead of municipal tender renewals.
Mexico
Mexico City's mobility regulatory framework mandates geofenced parking zones with automated fine issuance, compressing sidewalk clutter incidents while increasing firmware compliance costs. The metropolitan area's expanding metro integration gaps sustain dockless demand in dense corridors where formal transit coverage remains incomplete. Corporate campus subscriptions concentrate recurring revenue in the capital's central business district through B2B channel partnerships.
Colombia
Bogotá's altitude-constrained private vehicle usage and fragmented formal transit coverage create sustained demand for pedal-assisted dockless networks. National sustainable urban development standards shape fleet permitting and data-sharing obligations, with municipal open-data mandates imposing telemetry infrastructure costs. Grow Mobility anchors operations through localized assembly partnerships that reduce import duty exposure on Chinese-manufactured hardware.
Chile
Santiago's expanding metro system integration gaps and municipal carbon offset reporting requirements create procurement opportunities for verified offset partnerships. The country's national sustainable urban development standards align with broader regional EMA-equivalent environmental benchmarks. Fleet operators pilot predictive redistribution algorithms to maintain vehicle availability during peak commuter hours across the capital's dense metropolitan corridor.
Peru
Lima's altitude-constrained private vehicle usage and incomplete formal transit coverage generate white-space demand for dockless pedal-assisted deployments. Municipal sustainability initiatives in the capital are beginning to mirror Colombian and Brazilian procurement frameworks. The Andean corridor's unique topography favors lighter fleet architectures that reduce rebalancing labor intensity across steep urban gradients.
Latin America Bike Sharing Market Competitive Landscape
Player mix skews toward vertically integrated regional specialists with captive maintenance hub networks and diversified micromobility platforms licensing multiple vehicle classes. Market structure concentrates around incumbent operators with established municipal concession relationships and challenger entrants leveraging lower dockless infrastructure thresholds. Two strategic archetypes dominate: dedicated bike-sharing specialists with ISO-compliant fleet rotation capabilities, and diversified mobility platforms integrating bikes into broader vehicle-as-a-service portfolios. Competitive moves center on municipal tender positioning through open-data API compliance and hot-swap battery infrastructure partnerships.
Within the dedicated specialist tier, Tembici and Grow Mobility exemplify contrasting geographic anchoring strategies. Tembici leverages its Brazilian corporate structure to sustain vertically integrated maintenance hubs across state capitals, while Grow Mobility occupies a position emphasizing localized assembly partnerships within Colombian operations. Bird represents the diversified platform archetype, competing through micromobility licensing breadth rather than dedicated bike-sharing depth. Ecobici anchors municipal concession relationships in Mexico City through public station infrastructure, contrasting with dockless-first challengers.
| Leading Market Players |
|---|
| Tembici |
| Bim Bikes |
| Grow Mobility |
| Loop |
| Mobike |
| Ecobici |
| Wave |
| Bird |
| Encicla |
| Others |
Supply & Pricing Matrix
ISO 4210 certification gates both supplier qualification and price differentiation across Latin American bike sharing procurement, forcing fleet operators to absorb 8-14 month validation cycles that compress margin structures while enabling certified incumbents to command municipal tender premiums. This regulatory overlay stratifies pricing power between hardware-compliant specialists and non-certified challengers facing exclusion from concession renewals.
Pricing Analysis
Cost-plus municipal contracts with Chinese hardware indexation dominate fleet procurement across Brazilian and Colombian state capitals. Three-tier pricing structure across premium-certified, standard-compliant, and economy non-compliant levels segments buyer access, with government agencies and corporate campuses showing least price sensitivity due to bundled mobility benefit structures. Pricing pressure stems from 35-60% effective import duty burdens on non-localized assembly, forcing margin compression in the economy tier where duty exposure concentrates.
Supply Chain Analysis
China anchors frame and smart lock manufacturing, while Taiwan supplies precision drivetrain components and South Korea provides lithium-ion cells for pedal-assisted fleets. Raw material dependencies span aluminum alloy tubing, GPS-Bluetooth modules, and battery cells tethered to East Asian suppliers. Single-source vulnerability in cell supply creates exposure to shipping cost volatility and customs processing delays. Distribution runs through regional maintenance hubs in São Paulo, Mexico City, and Bogotá that handle final assembly and firmware localization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of predictive fleet management capabilities—particularly IoT-AI redistribution algorithms—separates viable long-term operators from hardware-dependent challengers facing maintenance hub congestion. Municipal tender eligibility increasingly demands this operational technology stack as a baseline qualification.
For Market Incumbents: Consolidate maintenance hub networks across Brazilian state capitals to sustain ISO-compliant fleet rotation ahead of tender renewals, while deepening backward integration into localized assembly partnerships that reduce import duty exposure against challenger price undercutting. For New Entrants and Emerging Players: Employer-sponsored mobility benefit packages in São Paulo and Mexico City business districts represent an under-served service layer where incumbents rely on legacy app-store transaction models. White-space entry through direct B2B billing relationships bypasses consumer acquisition costs and concentrates recurring revenue predictability. For Investors and Strategic Acquirers: ANTT federal guideline standardization across Brazilian state capitals reshapes the acquisition landscape toward operators with interstate permitting frameworks already embedded. Target vertically integrated specialists with captive maintenance infrastructure and established municipal concession relationships, watching for carbon offset mandate adoption in São Paulo state as the inflection signal for EMA-equivalent environmental compliance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Swap Battery Infrastructure Partnership | Reduces vehicle downtime from charging cycles to 90-second exchanges in São Paulo and Mexico City pilots. |
| Predictive Redistribution Algorithm Deployment | Compresses rebalancing labor costs by 20-30% versus rule-based dispatch through real-time lock telemetry. |
| Localized Assembly Partnership | Mitigates 35-60% effective duty burdens on Chinese-manufactured hardware for Colombian and Peruvian operations. |
| Open-Data API Compliance Investment | Satisfies non-negotiable municipal tender requirements in Bogotá and Mexico City procurement frameworks. |
| Carbon Offset Partnership Verification | Captures first-mover advantage in São Paulo state municipalities mandating fleet-level carbon reporting. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, municipal mobility procurement officers, smart lock hardware engineers, and maintenance hub managers and refined through secondary validation across ANTT regulatory filings, Mexico City mobility framework documents, Colombian sustainable urban development standards, customs and trade data for bicycle component imports, and SEC disclosures from listed micromobility platforms. Bottom-up fleet deployment modeling triangulated against top-down metropolitan transit coverage gap analysis.
Variance-decomposition across the projection horizon isolates growth contributions from dockless GPS integration, subscription-based B2B channel expansion, and ISO 4210 certification compliance timelines. Segmentation dimensions span service type, end user archetype, operational model, and technology stack, with smart lock reliability metrics and rebalancing labor intensity serving as industry-specific forecast inputs. CAGRs derive from fleet density projections correlated with metro integration gap closure rates.
Material uncertainties—lithium-ion battery supply disruption, municipal procurement rule changes, and smart lock firmware compliance costs—sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and hardware certification timeline adherence. Recalibration cycles align with material shifts in ANTT guideline revisions and EMA-equivalent environmental mandate adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Cruiser Bikes Market
Bikes and Motorcycles
Spain E-Bike Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Mountain Bike Suspension Market
Bikes and Motorcycles
Motorsports Motorcycle Market