
 Textile Composites Market | 2026-2036
Textile Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Composites Market Analysis
Aerospace procurement is unwinding from legacy metal-centric platforms toward thermoplastic composite airframes. Owens Corning leverages its glass fiber manufacturing scale to anchor supply for next-generation aircraft programs. Toray Industries Inc dominates carbon fiber reinforcement supply through backward integration into precursor chemistry. Hexcel Corporation specializes in epoxy-impregnated prepregs that sustain qualification cycles with Boeing and Airbus.
Textile composites are fiber-reinforced materials in which woven, non-woven, or knitted textile structures are embedded within a polymer matrix to achieve directional strength-to-weight ratios exceeding 200 MPa per gram per cubic centimeter. Their primary purpose spans load-bearing structural substitution in transportation and protective equipment where mass reduction directly improves energy efficiency or human performance. Woven fabrics lead in aerospace qualification due to dimensional stability under autoclave processing, while non-woven fabrics capture fastest growth in automotive where stampable thermoplastic sheets cut cycle times. Hybrid composites concentrate margin pools where carbon-glass combinations balance cost and stiffness for sports equipment manufacturers.
FAA airworthiness directives and EASA certification standards govern material qualification timelines for aerospace applications, extending development cycles but creating barriers against unqualified entrants. The EU Green Deal's carbon border adjustments and REACH chemical registrations are reshaping matrix material selection toward lower-toxicity epoxy formulations and bio-based polyester alternatives. Stakeholders must monitor how EPA toxicity evaluations for vinyl ester resins interact with state-level extended producer responsibility laws in California and Washington to anticipate reformulation costs and regional supply reconfiguration.
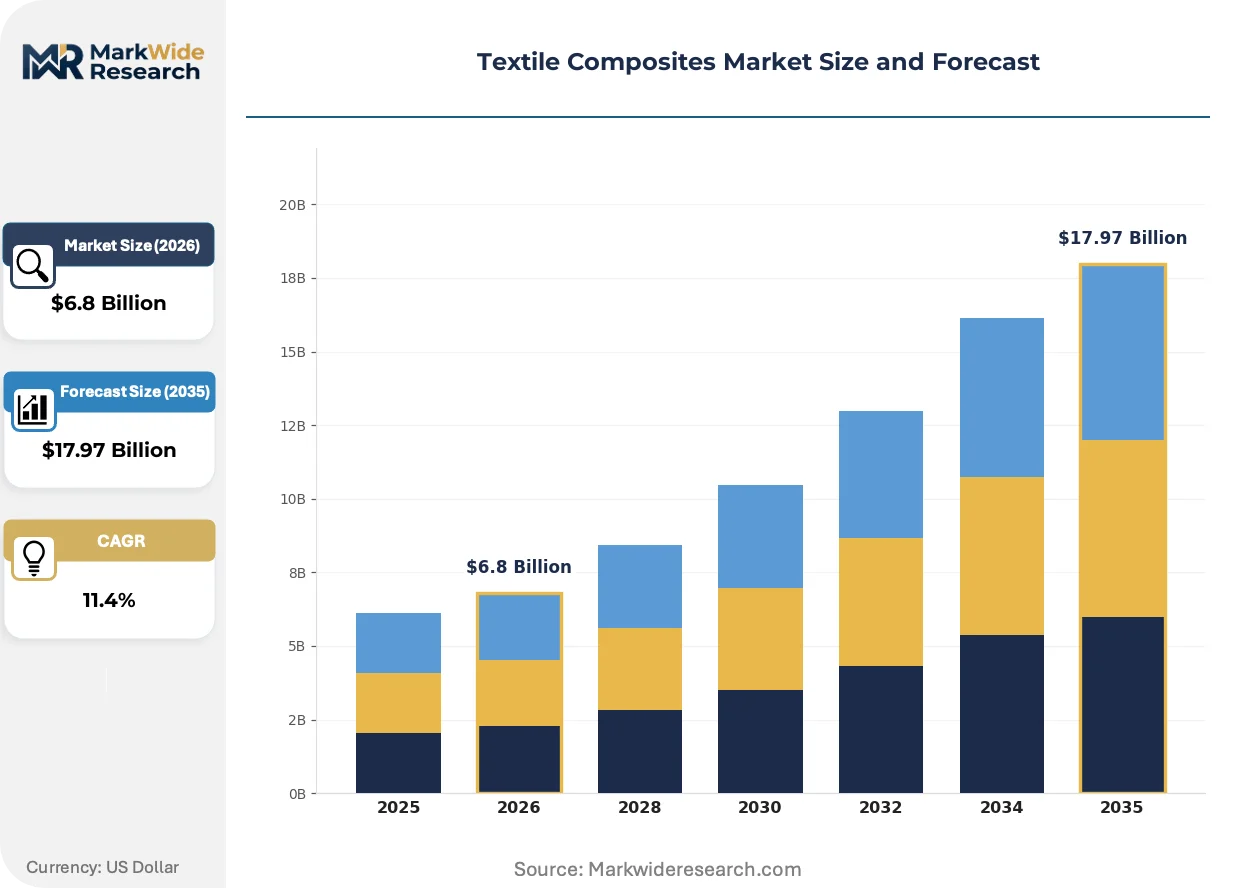
Market Dynamics
Automotive OEMs in Germany's manufacturing belt are forcing material substitution timelines forward as EU Green Deal embodied carbon rules tighten supply chain qualification requirements for lightweight structural panels.
Growth Catalysts
- EU Green Deal carbon border adjustments:Manufacturers serving Stuttgart and Wolfsburg automotive clusters must document embodied carbon in textile composite inputs, accelerating qualified supplier consolidation.
- Stampable thermoplastic sheets:Non-woven fabric formats cut automotive panel cycle times from minutes to seconds, capturing replacement demand from metal stampings in door modules and seat structures.
- FAA-EASA harmonized qualification pathways:Streamlined airworthiness certification for thermoplastic composite airframes reduces development barriers for next-generation narrowbody programs.
Market Restraints
- Precursor chemistry concentration:Carbon fiber reinforcement supply depends on captive acrylonitrile production concentrated in Asian chemical complexes, exposing buyers to feedstock volatility.
- REACH chemical registration costs:ECHA compliance for novel epoxy formulations and bio-based polyester alternatives imposes six-figure registration burdens that freeze SME formulation innovation.
- Autoclave processing bottlenecks:Woven aerospace fabrics require dimensional stability under thermal pressure cycles that limit throughput versus out-of-autoclave alternatives.
Strategic Opportunities
- India's PLI scheme for advanced materials:Domestic textile composite manufacturing incentives target automotive and renewable energy applications with production-linked subsidies through 2030.
- Sports equipment hybridization:Carbon-glass combinations balance stiffness and cost for bicycle frames and protective gear where performance tiers segment price positioning.
- California extended producer responsibility laws:State-level mandates for composite end-of-life management create first-mover advantage for recyclate-integrated prepreg suppliers.
Industry Challenges
- Qualification timeline compression:Boeing and Airbus sustain multi-year epoxy-impregnated prepreg certification cycles that conflict with accelerated program development schedules.
- Matrix material toxicity evaluations:EPA reviews of vinyl ester resin chemistries interact unpredictably with Washington state chemical hazard regulations, forcing parallel reformulation tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Composites Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Knitted Fabrics, Hybrid Composites Application: Aerospace, Automotive, Sports Equipment, Consumer Goods Matrix Material: Epoxy, Polyester, Polyurethane, Vinyl Ester Reinforcement Type: Carbon Fibers, Glass Fibers, Natural Fibers, Aramid Fibers |
| Companies Covered | Toray Industries Inc, Owens Corning, Hexcel Corporation, Teijin Limited, DuPont, Saertex GmbH & Co. KG, BGF Industries Inc, Chomarat Textile Industries, Milliken & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Composites Market Emerging Trajectories
Material processing pathways and regulatory chemistry requirements are actively rewiring competitive positioning across aerospace and automotive qualification tiers.
Thermoplastic composite welding is fragmenting traditional autoclave-dependent manufacturing. Automated fiber placement with in-situ consolidation eliminates tooling cycles for fuselage panels. Tier 1 aerostructures suppliers in Japan and Italy are adopting these lines for A320neo-family components, compressing capital recovery timelines from seven years to three.
REACH restrictions on diisocyanates and bisphenol-A derivatives are forcing matrix chemistry migration. Formulators must validate bio-epoxy alternatives without sacrificing glass transition temperatures above 180°C. German automotive suppliers near Wolfsburg report eighteen-month validation extensions as they retool resin transfer molding lines for compliant systems.
Sourcing committees at major aerospace primes now mandate recycled carbon fiber content minimums in non-structural applications. Tier 2 fabricators must demonstrate pyrolysis-derived fiber supply chains or forfeit contract eligibility. This specification shift concentrates procurement leverage with Owens Corning and Toray Industries, which have invested in European recyclate processing infrastructure.
Textile Composites Market Segmentation
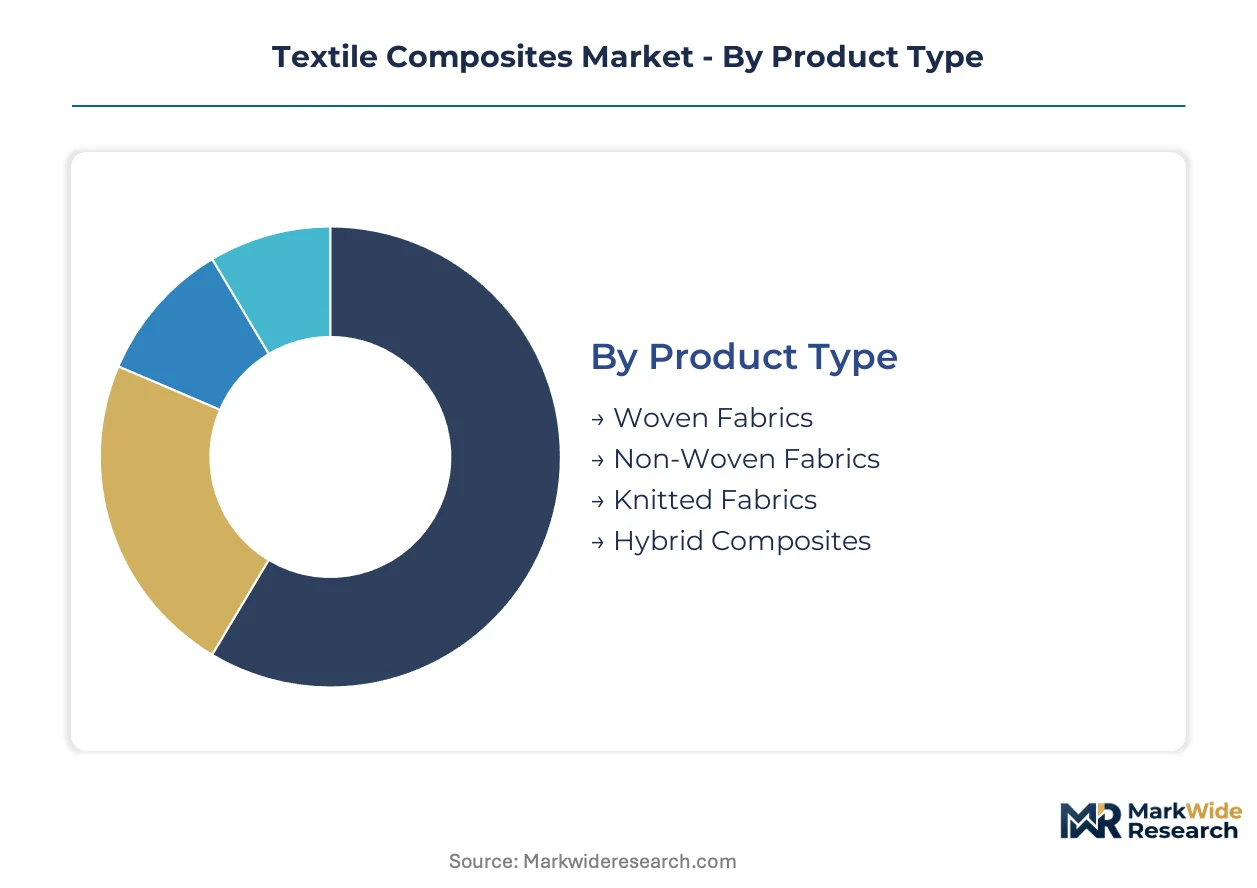
Segmentation in textile composites reveals how material format, end-use qualification requirements, and reinforcement chemistry create distinct margin pools. Each category channels procurement decisions toward different supplier capabilities and geographic sourcing strategies.
Product Type:
Woven fabrics flow through aerospace tier-1 suppliers demanding autoclave-stable dimensional tolerances, while non-woven formats reach automotive stampers through thermoplastic sheet distributors.
- Woven Fabrics:Interlaced fiber architectures deliver dimensional stability under thermal pressure cycles required for aerospace qualification. Demand concentrates around Stuttgart and Wolfsburg automotive clusters where EU Green Deal embodied carbon documentation favors established suppliers with certified prepreg lines.
- Non-Woven Fabrics:Random fiber orientation enables stampable thermoplastic sheet production with cycle times compressed from minutes to seconds. German automotive OEMs are forcing substitution timelines forward as lightweight structural panel requirements tighten.
- Knitted Fabrics:Loop-structured textiles conform to complex geometries for sports equipment and medical braces where multi-directional stretch matters.
- Hybrid Composites:Carbon-glass combinations balance stiffness and cost for protective gear manufacturers segmenting performance tiers across price positioning.
By volume, non-woven fabrics lead. By growth pace, hybrid composites are climbing the fastest as sports equipment manufacturers seek cost-optimized performance tiers.
Application:
Application segmentation separates qualification-intensive aerospace programs from high-volume automotive stampings with divergent margin structures and supplier certification burdens.
- Aerospace:Thermoplastic composite airframes demand FAA-EASA harmonized qualification pathways with multi-year epoxy-impregnated prepreg certification cycles. Boeing and Airbus sustain these timelines that conflict with accelerated program development schedules.
- Automotive:Door modules and seat structures drive replacement demand from metal stampings through stampable thermoplastic sheets. EU Green Deal carbon border adjustments force Stuttgart and Wolfsburg manufacturers to document embodied carbon in textile composite inputs.
- Sports Equipment:Bicycle frames and protective gear exploit carbon-glass hybridization where performance tiers segment price positioning across amateur and professional categories.
- Consumer Goods:Luggage shells and electronics housings absorb recycled carbon fiber content minimums in non-structural applications where sourcing committees mandate pyrolysis-derived fiber supply chains.
Aerospace commands the highest unit margins. Automotive delivers the steepest volume expansion as OEMs accelerate lightweight panel adoption.
Matrix Material:
Matrix chemistry selection channels through REACH compliance costs and EPA toxicity evaluations that reshape formulation portfolios across European and North American supply chains.
- Epoxy:High glass transition temperatures above 180°C sustain aerospace qualification cycles with Boeing and Airbus. REACH restrictions on bisphenol-A derivatives force eighteen-month validation extensions as German suppliers retool resin transfer molding lines.
- Polyester:Cost-optimized unsaturated formulations dominate automotive and marine applications where bio-based alternatives are gaining traction under EU Green Deal chemistry migration pressures.
- Polyurethane:Flexible matrix systems serve impact-absorbing sports equipment and medical devices where vibration damping properties outweigh thermal performance requirements.
- Vinyl Ester:Corrosion-resistant formulations target chemical processing and marine infrastructure where EPA toxicity evaluations interact unpredictably with Washington state chemical hazard regulations.
Epoxy retains the premium tier by certification value. Polyester expands most quickly as bio-based alternatives penetrate automotive qualification pipelines.
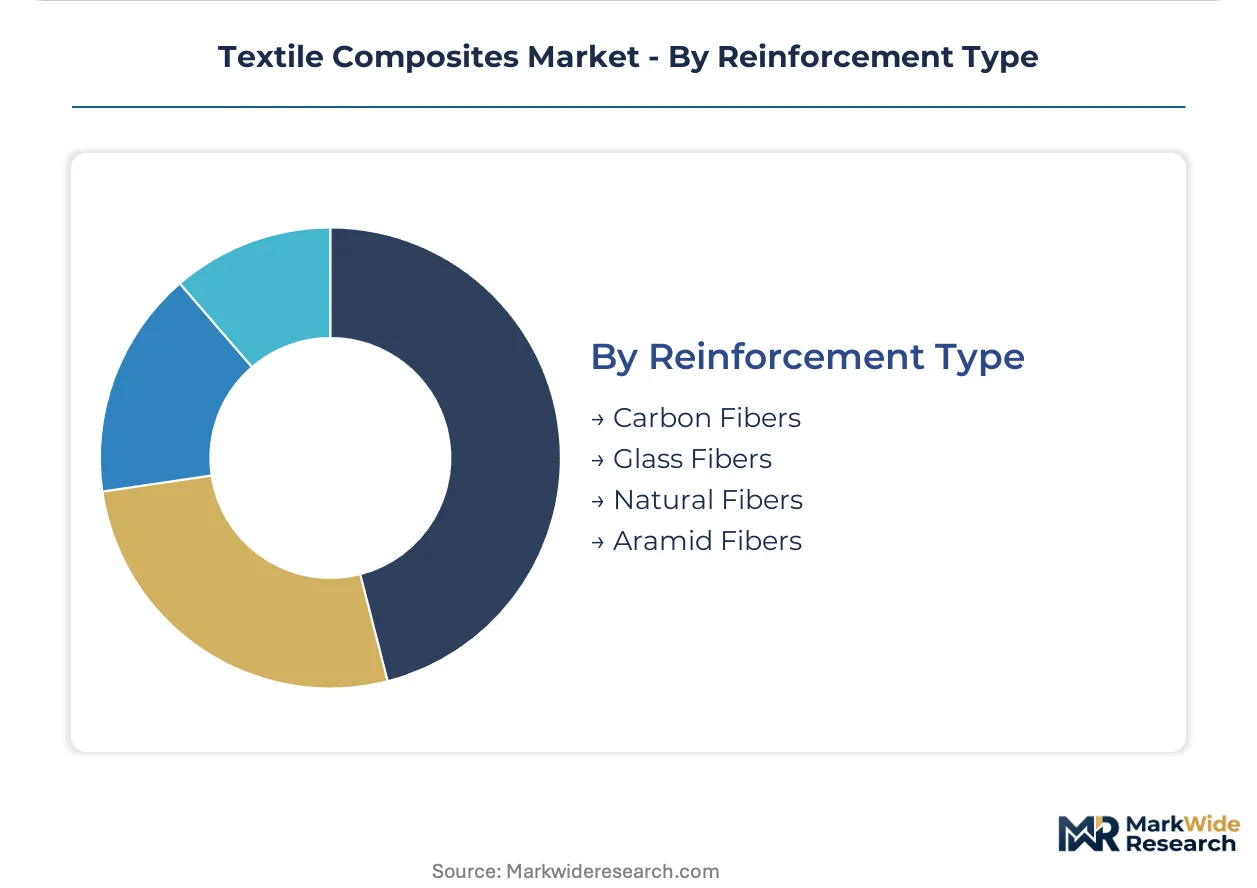
Reinforcement Type:
Reinforcement segmentation concentrates supply leverage through backward integration into precursor chemistry and captive fiber production assets.
- Carbon Fibers:Acrylonitrile-based precursors deliver strength-to-weight ratios exceeding 200 MPa per gram per cubic centimeter for aerospace load-bearing substitution. Asian chemical complexes concentrate precursor supply, exposing buyers to feedstock volatility.
- Glass Fibers:Owens Corning leverages manufacturing scale to anchor supply for next-generation aircraft programs and automotive structural panels where cost-positioning matters more than stiffness optimization.
- Natural Fibers:Flax and hemp reinforcements target bio-composite specifications in automotive interior panels and consumer goods where sustainability credentials drive procurement committee decisions.
- Aramid Fibers:Ballistic-grade performance serves military and law enforcement protective equipment where abrasion resistance and thermal stability justify premium positioning.
Glass fibers dominate by tonnage shipped. Carbon fibers gain share fastest as thermoplastic composite airframes displace legacy metal-centric platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German textile composite exports flow primarily into French and Italian aerospace assembly lines, while Japanese carbon fiber shipments supply Boeing's Washington state facilities and Airbus Hamburg operations.
Germany
Automotive OEMs around Stuttgart and Wolfsburg drive stampable thermoplastic sheet demand for door modules and seat structures. EU Green Deal embodied carbon rules force manufacturers to document supply chain inputs, consolidating procurement around qualified prepreg suppliers. The Baden-Württemberg automotive belt hosts resin transfer molding line retooling for REACH-compliant epoxy systems.
United States
Boeing and Airbus narrowbody programs sustain multi-year qualification cycles for epoxy-impregnated prepregs. FAA airworthiness directives govern material certification timelines, creating barriers against unqualified entrants. Washington state chemical hazard regulations interact unpredictably with EPA vinyl ester toxicity evaluations, forcing parallel reformulation tracks among Pacific Northwest suppliers.
Japan
Tier 1 aerostructures suppliers adopt automated fiber placement with in-situ consolidation for A320neo-family components. METI industrial policy supports next-generation aircraft material development through targeted R&D subsidies. The Nagoya aerospace cluster compresses capital recovery timelines from seven years to three through thermoplastic welding adoption.
China
Dual carbon goals accelerate lightweight structural panel substitution in domestic automotive programs. MIIT standards for advanced materials support textile composite manufacturing scale-up for electric vehicle platforms. The Yangtze River Delta concentrates glass fiber production capacity serving both domestic OEMs and export markets.
India
Domestic automotive and renewable energy applications absorb PLI scheme production-linked subsidies through 2030. BIS certification requirements for advanced materials create qualification pathways for textile composite suppliers. The Gujarat industrial corridor attracts prepreg manufacturing investments targeting export markets in Southeast Asia and the Middle East.
Textile Composites Market Vendor Landscape
Player mix skews toward vertically integrated fiber producers and specialized prepreg formulators. Market structure concentrates around three to five dominant suppliers with captive precursor chemistry assets, while mid-tier fabricators compete on regional qualification speed. Two strategic archetypes define competitive positioning: backward-integrated carbon fiber producers controlling acrylonitrile supply chains, and epoxy-impregnated prepreg specialists sustaining multi-year aerospace certification cycles. Dominant competitive moves include capacity expansion in Asian chemical complexes and strategic partnerships between fiber producers and Tier 1 aerostructures suppliers.
Among Japanese-based producers, Toray Industries Inc exemplifies the backward-integrated archetype through captive precursor chemistry control. Owens Corning anchors the glass fiber manufacturing tier with scale advantages in next-generation aircraft supply. Hexcel Corporation occupies a position within the epoxy-impregnated prepreg specialist tier, sustaining qualification relationships with Boeing and Airbus. These three companies represent distinct competitive vectors: upstream chemical integration, manufacturing scale, and aerospace certification depth.
| Leading Market Players |
|---|
| Toray Industries Inc |
| Owens Corning |
| Hexcel Corporation |
| Teijin Limited |
| DuPont |
| Saertex GmbH & Co. KG |
| BGF Industries Inc |
| Chomarat Textile Industries |
| Milliken & Company |
| Others |
Supply Flow & Price Mechanics
Ninety-day carbon fiber precursor inventory buffers concentrate pricing power with Asian acrylonitrile producers, while German automotive stampers compress thermoplastic sheet procurement cycles to under thirty days. This lead-time asymmetry between upstream chemical captives and downstream panel manufacturers reshapes margin extraction across the textile composites value chain.
Pricing Analysis
Prior-generation autoclave-dependent prepregs command premium positioning against stampable thermoplastic sheet alternatives, while next-generation welded thermoplastic airframe materials capture emerging price tiers. Three-tier pricing structure across aerospace-qualified, automotive-stamped, and consumer-grade specifications segments buyer segments by certification burden and volume scale. Cost compression in automotive stampable sheets intensifies as Wolfsburg and Stuttgart OEMs consolidate procurement around qualified European suppliers. Price sensitivity concentrates among sports equipment manufacturers sourcing carbon-glass hybrids, while aerospace primes absorb premium epoxy prepreg costs within multi-year program budgets.
Supply Chain Analysis
Strategic stockpiling of acrylonitrile precursor dominates carbon fiber supply strategy, contrasting with just-in-time thermoplastic sheet distribution serving German automotive clusters. Supply concentrates in Japan, Germany, and China for carbon fiber and glass fiber production, with precursor chemistry anchored in Asian petrochemical complexes. Raw material flows draw from petroleum-based acrylonitrile, bio-based polyester feedstocks, and recycled carbon fiber pyrolysis outputs. Single-source vulnerability in precursor supply exposes buyers to feedstock volatility. Distribution runs through Tier 1 aerostructures suppliers and automotive stamping distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs textile composite procurement as Boeing and Airbus harmonize thermoplastic qualification pathways, creating interoperability standards that favor suppliers with multi-program certification depth over single-platform specialists.
For Market Incumbents: Compound certification asset value by extending epoxy-impregnated prepreg qualifications across next-generation narrowbody platforms before accelerated development timelines compress approval windows. Deepen backward integration into precursor chemistry to defend margin position against Asian acrylonitrile volatility. Prioritize recyclate processing infrastructure investment as aerospace sourcing committees mandate pyrolysis-derived fiber minimums. For New Entrants and Emerging Players: Anchor in India's PLI scheme production-linked subsidies for domestic automotive and renewable energy applications, where BIS certification pathways create qualification on-ramps absent entrenched supplier relationships. Target sports equipment hybridization segments where carbon-glass combinations balance performance tiers with cost-optimized positioning. Pursue direct partnerships with Gujarat industrial corridor prepreg manufacturers to bypass established European distribution channels. For Investors and Strategic Acquirers: Long-term, this sits as a materials-platform consolidation play because aerospace-automotive qualification convergence will collapse the supplier base from fragmented regional fabricators toward three to five vertically integrated fiber-prepreg-chemistry players. Acquisition focus should center on European recyclate processing assets and automated fiber placement equipment specialists. Monitor FAA-EASA harmonization implementation velocity as inflection indicator for thermoplastic airframe adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | Captive acrylonitrile supply insulates carbon fiber producers from Asian petrochemical volatility. |
| Automated Fiber Placement Adoption | Tier 1 Japanese and Italian suppliers compress capital recovery timelines through in-situ consolidation. |
| Recyclate Processing Infrastructure | Pyrolysis-derived fiber capabilities satisfy aerospace sourcing committee mandates for non-structural content. |
| REACH-Compliant Formulation Migration | German automotive suppliers near Wolfsburg retool resin transfer molding lines for bio-epoxy alternatives. |
| PLI Scheme Manufacturing Scale-Up | Indian domestic production incentives attract prepreg investments targeting Southeast Asian export markets. |
Methodological Framework
The analysis maps woven aerospace fabrics, non-woven automotive stampables, knitted sports equipment textiles, and hybrid protective gear composites, each validated through procurement directors at Stuttgart and Wolfsburg OEMs, Tier 1 aerostructures engineers in Japan and Italy, prepreg formulator R&D leads, and ECHA regulatory compliance officers. Secondary sources include FAA airworthiness directive filings, EASA certification databases, EU Green Deal embodied carbon documentation, MIIT advanced materials standards, and customs trade flows for carbon fiber and glass fiber shipments. Bottom-up segment sizing triangulates against top-down macroeconomic drivers.
Consistency checks validated volume and value outputs against aircraft program delivery schedules, automotive lightweighting content-per-vehicle trajectories, and sports equipment manufacturer procurement disclosures across the projection horizon. Segmentation dimensions encompass product format, application qualification tier, matrix chemistry compliance status, and reinforcement type. CAGRs derive from regression analysis of historical substitution patterns and forward-looking adoption curves for thermoplastic composite airframes and stampable automotive panels.
Material uncertainties — precursor supply disruptions, REACH chemical registration delays, and harmonized airworthiness pathway implementation — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued EU Green Deal enforcement and FAA-EASA regulatory convergence. Revision becomes warranted when carbon border adjustment mechanisms expand beyond embodied carbon documentation to mandate recyclate content thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Ultraviolet Disinfection Equipment Market
Others
South America Automotive LED Lighting Market
Others
Managed Video As a Service Market
Others
Floor Cleaning and Mopping Machine Market
Others
Education and Learning Analytics Market
Others
Asia-Pacific Professional Scalp Treatment Products Market
Others
Global Microcontroller Embedded Systems Market
Others
United States Bean Bags Market
Others
Storage Dewar and Dry Shipper Market
Others
Europe Electric Forklift Market
Others
ISO Cylinder Market
Others
Pediatric Measuring Devices Market
Others
Global Smartphone ODM Market
Others
Double Card Mobile Phone Market
Others
DNA Data Storage Market
Others
Asia-Pacific Medical Simulation Market