
 DNA Data Storage Market | 2026-2036
DNA Data Storage Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Data Storage Market Analysis
The EU AI Act is broadening the cost-of-entry calculus for DNA data storage vendors serving European biomedical and cloud clients, as automated data classification rules force alignment between genomic data provenance and algorithmic traceability requirements. Twist Bioscience leverages silicon-based DNA synthesis workflows to sustain cost leadership in high-density archival encoding. Microsoft anchors its position through upstream control over software-defined encoding layers that interface with biological substrates. Illumina competes by extending its sequencing-throughput advantages into read-intensive retrieval architectures.
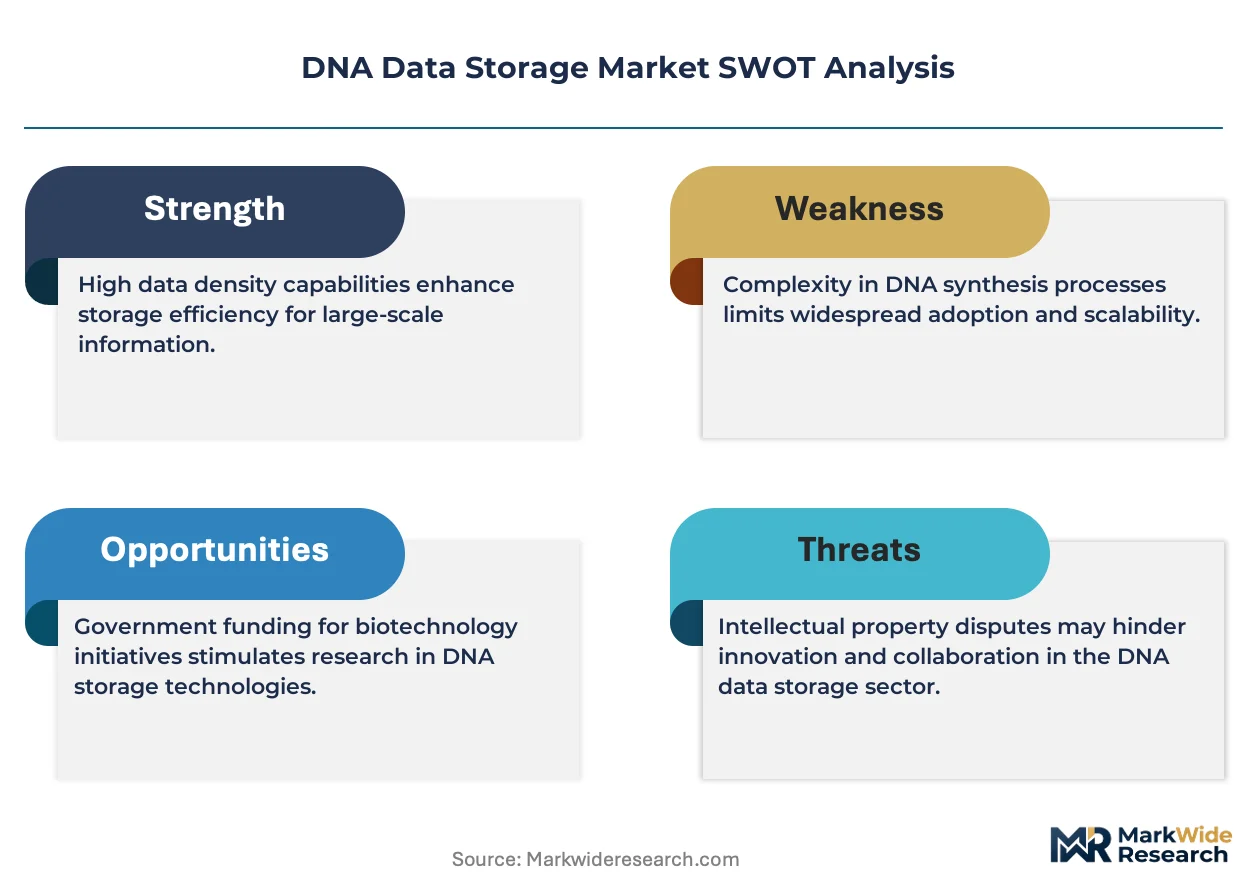
DNA data storage encodes digital information into synthetic nucleotide sequences—adenine, cytosine, guanine, and thymine—using phosphoramidite chemistry or enzymatic polymerization, achieving theoretical densities exceeding 10^15 bytes per cubic millimeter for century-scale archival retention. Its primary commercial purpose centers on replacing tape and optical media for cold data that must survive decades without refresh cycles. DNA synthesis dominates the storage medium dimension as the cost-critical bottleneck where margin pools concentrate, while DNA sequencing anchors retrieval economics. Data centers and research institutions represent the most active end-user segments, with archive storage and biomedical research applications absorbing the majority of pilot deployments.
FDA oversight of synthetic nucleotide materials used in biomedical research applications shapes purity and traceability standards that propagate upstream to storage-grade DNA manufacturing. The EPA monitors phosphoramidite waste streams from synthesis operations, while ISO 17025 accreditation requirements influence laboratory data integrity protocols for archival custody chains. NIST reference materials for DNA quantification further constrain vendor qualification pathways. Stakeholders must monitor which regulator first mandates retention-period guarantees for genomic data archives, as this will trigger procurement specification cascades across healthcare and defense verticals.
Market Dynamics
Enzymatic DNA synthesis is compressing per-byte costs and collapsing write latency timelines, forcing phosphoramidite chemistry incumbents to defend position through throughput scale rather than cost parity alone.
Growth Catalysts
- Archival storage demand from hyperscale data centers:Century-scale retention requirements without refresh cycles pull DNA encoding into pilot procurement pipelines.
- Federal research funding concentration in the United States:Cloud infrastructure investments cluster near national laboratory ecosystems, accelerating vendor qualification timelines.
- EU AI Act automated classification rules:Genomic data provenance requirements force alignment between algorithmic traceability and biological substrate custody chains.
Market Restraints
- Phosphoramidite waste stream disposal costs:EPA monitoring of synthesis operations adds compliance overhead that enzymatic methods avoid.
- DNA synthesis equipment supplier concentration:Silicon-based workflow hardware sources cluster in select manufacturing geographies.
- Tape and optical media substitution economics:Cold storage incumbents benefit from amortized infrastructure and established retrieval protocols.
Strategic Opportunities
- Biomedical research data archives:FDA oversight of synthetic nucleotide materials creates qualified vendor pathways for storage-grade DNA manufacturing.
- Defense vertical retention mandates:Procurement specification cascades await the first regulator-mandated guarantee for genomic data archive periods.
- Software-defined encoding layer convergence:Biological substrate interfaces with algorithmic error correction compress retrieval latency for read-intensive architectures.
Industry Challenges
- ISO 17025 accreditation timelines:Laboratory data integrity protocols extend vendor qualification pathways for archival custody chains.
- NIST reference material integration:DNA quantification standards constrain batch-to-batch consistency for storage-grade synthesis.
- Legacy tape infrastructure interoperability:Hybrid retrieval systems require bridging biological read mechanisms with existing data center access protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Data Storage Market |
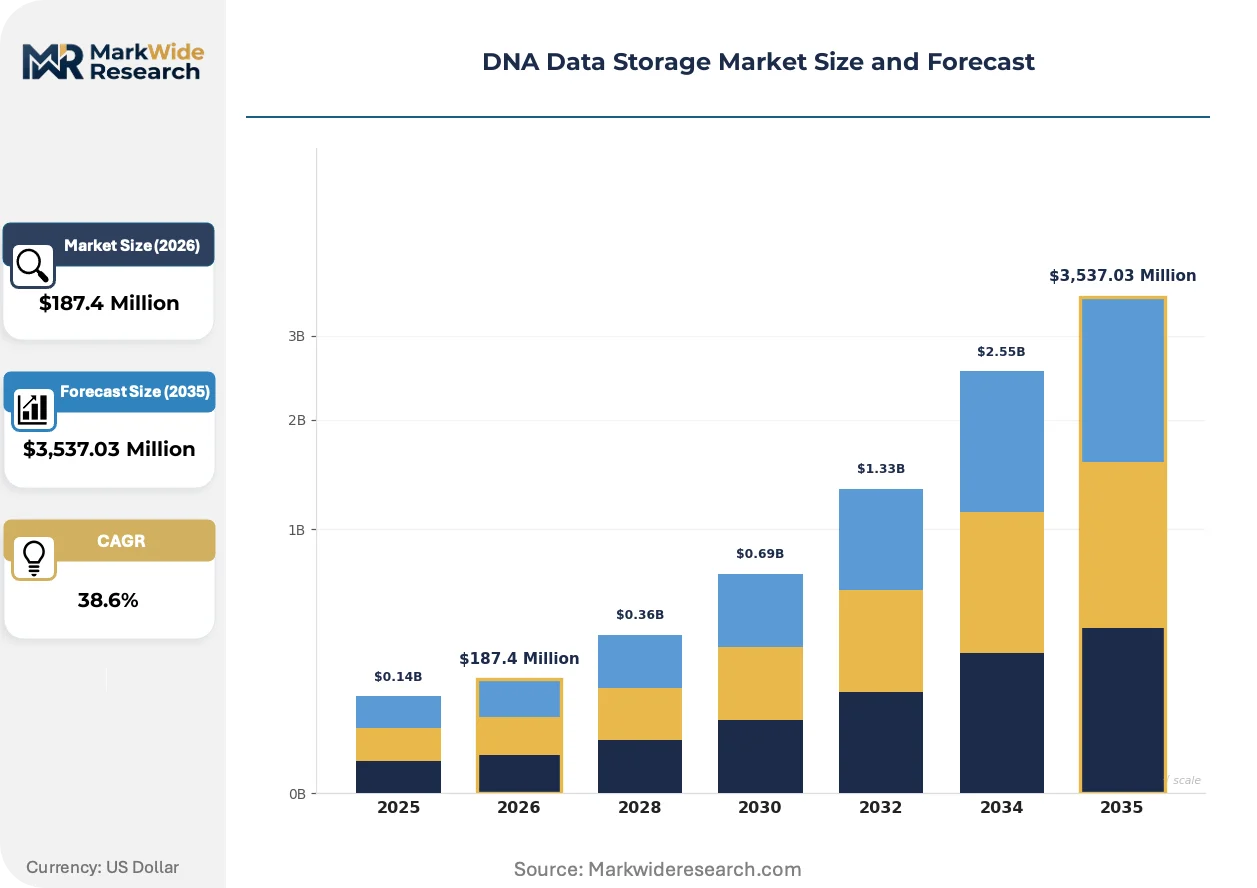
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $3,537.03 Million |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Medium: DNA Synthesis, DNA Sequencing, DNA Amplification, DNA Fragmentation End User: Biotechnology Companies, Research Institutions, Academic Organizations, Data Centers Application: Archive Storage, Cloud Storage, Data Backup, Biomedical Research Technology: Encoding Algorithms, DNA-based Storage Solutions, Retrieval Techniques, Data Management Systems |
| Companies Covered | Twist Bioscience, Illumina, Microsoft, Iridia, DNA Script, Evonetix, Catalog Technologies, Helixworks, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Data Storage Market Emerging Trajectories
Biological encoding methods are crossing threshold cost curves that separate laboratory curiosity from procurement-grade alternatives, with synthesis throughput and read latency now tracking toward tape parity.
Enzymatic polymerization is consolidating as the dominant synthesis modality for high-density archival encoding. Data center operators piloting cold storage alternatives adopt enzymatic workflows for their reduced chemical waste profiles and shortened cycle times. This modality shift is consolidating margin pools around enzyme engineering and reaction optimization rather than phosphoramidite chemistry hardware.
EU AI Act algorithmic traceability mandates are reshaping vendor qualification pathways for European biomedical clients. Automated data classification rules now require demonstrable provenance chains from biological substrate through encoding logic to retrieval verification. Cloud service providers serving EU healthcare verticals are restructuring procurement specifications to preempt compliance friction.
Buyer concentration among hyperscale operators is compressing vendor sales cycles toward direct qualification programs. Traditional channel intermediaries in laboratory supply chains face disintermediation as data center procurement teams establish direct vendor relationships. This pattern is most visible in the United States, where federal cloud infrastructure investments cluster near national research institutions with established DNA synthesis capabilities.
DNA Data Storage Market Segmentation
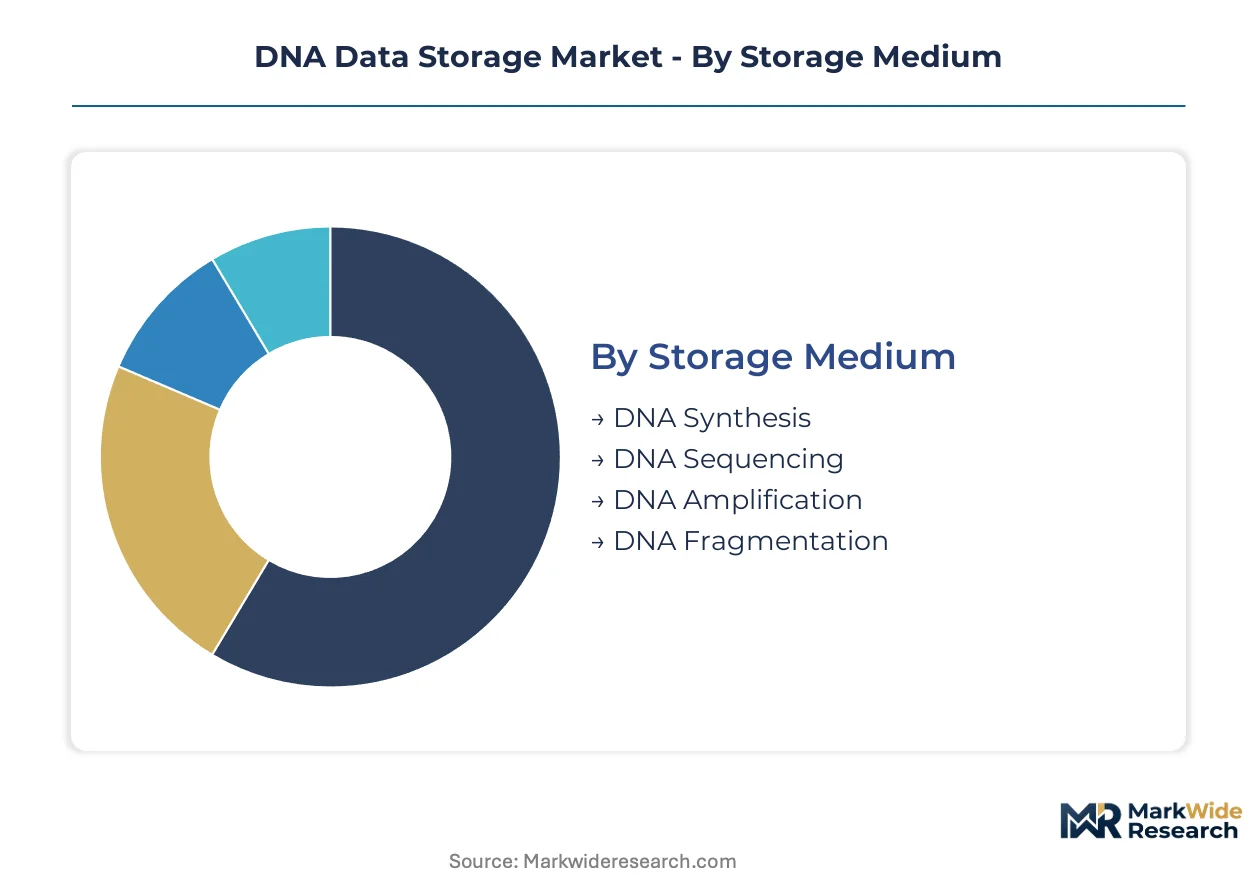
Capital allocation across DNA data storage segments concentrates where synthesis throughput and retrieval latency determine procurement economics. Vendors must map R&D spend against specific buyer workflows rather than treating the market as homogeneous.
Storage Medium:
Capital intensity peaks where enzymatic polymerization equipment and silicon-based synthesis workflows require specialized cleanroom infrastructure.
- DNA Synthesis:Phosphoramidite chemistry and enzymatic polymerization encode digital bits into nucleotide sequences. Data centers in the United States absorb the majority of pilot deployments as century-scale retention requirements displace tape refresh cycles.
- DNA Sequencing:High-throughput read architectures retrieve stored information through fluorescence-based or nanopore detection methods. Research institutions cluster procurement near national laboratory ecosystems with established sequencing infrastructure.
- DNA Amplification:Polymerase chain reaction multiplies sparse template copies for reliable readback. Academic organizations leverage existing laboratory thermal cycler fleets.
- DNA Fragmentation:Controlled strand breakage segments long sequences for parallel processing. Cloud storage operators pilot fragmentation protocols to compress retrieval latency.
DNA Synthesis absorbs the bulk of installed capacity; DNA Sequencing is expanding most quickly as read-intensive architectures mature.
End User:
Buyer procurement sophistication varies sharply between commercial operators optimizing cost-per-byte and research entities prioritizing experimental flexibility.
- Data Centers:Hyperscale operators pilot cold storage alternatives to eliminate tape refresh overhead. Federal cloud infrastructure investments in the United States accelerate direct vendor qualification timelines bypassing traditional laboratory supply channels.
- Biotechnology Companies:Genomic data archives drive qualified vendor pathways under FDA oversight of synthetic nucleotide materials. EU AI Act provenance requirements reshape procurement specifications for European biomedical clients.
- Research Institutions:National laboratory ecosystems anchor synthesis capability development near federal funding concentrations.
- Academic Organizations:University core facilities access shared enzymatic synthesis infrastructure through multi-institutional consortia.
Data Centers command the steepest expansion trajectory; Research Institutions hold the deepest installed synthesis expertise.
Application:
Retention-period guarantees and regulatory custody chains segment buyer requirements more sharply than raw capacity metrics.
- Archive Storage:Century-scale retention without refresh cycles targets tape substitution. Defense verticals await the first regulator-mandated guarantee for genomic data archive periods to trigger procurement specification cascades.
- Biomedical Research:FDA purity and traceability standards propagate upstream from therapeutic applications to storage-grade DNA manufacturing. ISO 17025 accreditation timelines extend vendor qualification pathways for archival custody chains.
- Cloud Storage:EU AI Act automated classification rules force alignment between algorithmic traceability and biological substrate custody chains.
- Data Backup:Hybrid retrieval systems bridge biological read mechanisms with existing data center access protocols.
Archive Storage dominates current pilot deployments; Biomedical Research is climbing the fastest as regulatory frameworks mature.
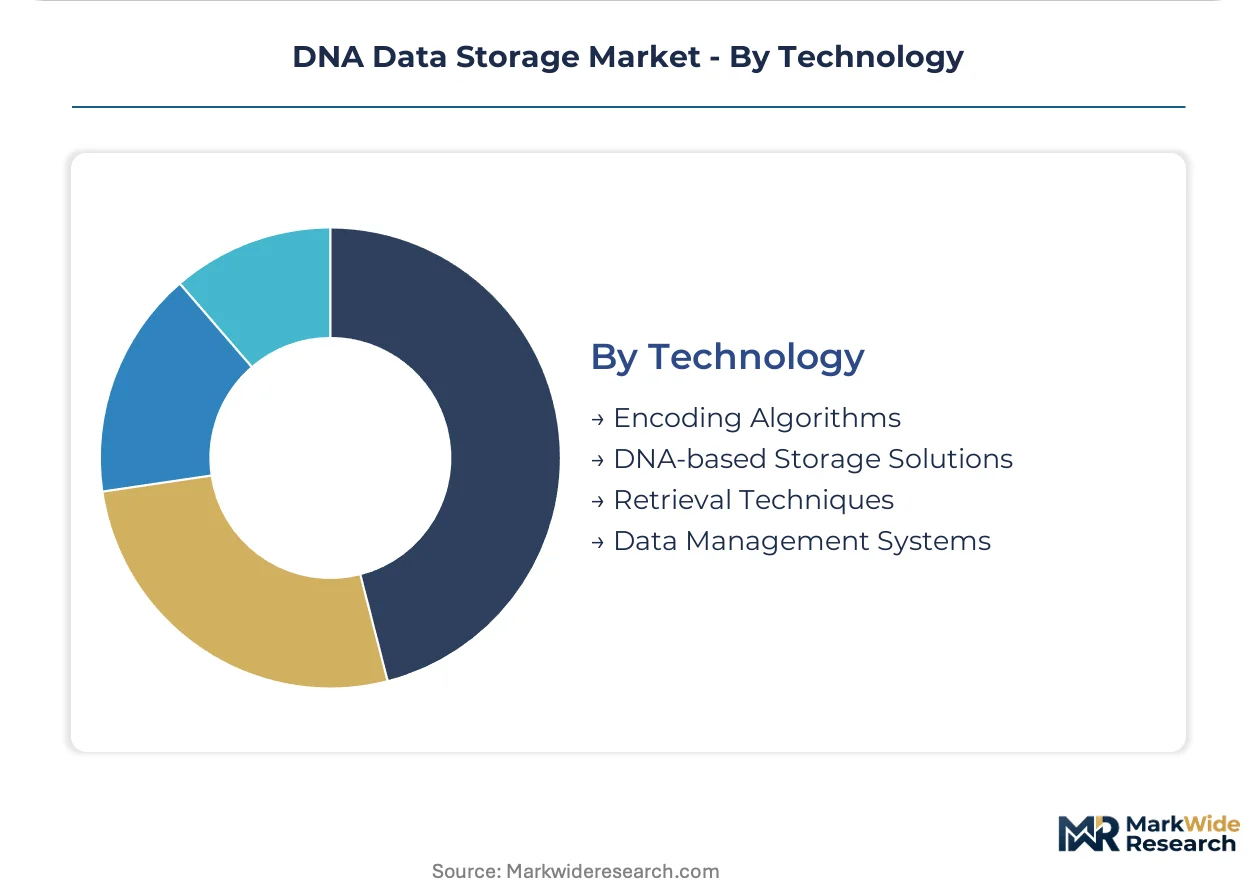
Technology:
Software-hardware interface layers concentrate margin pools where encoding logic converges with biological substrate control.
- Encoding Algorithms:Error correction schemes and base-4 translation protocols compress redundancy overhead. Microsoft anchors competitive position through upstream control over software-defined encoding layers.
- DNA-based Storage Solutions:Integrated synthesis-sequencing workflows package substrate handling with data management. Twist Bioscience leverages silicon-based DNA synthesis workflows to sustain cost leadership.
- Retrieval Techniques:Random access methods and selective amplification reduce read latency for non-sequential data recovery.
- Data Management Systems:Provenance tracking and custody chain verification satisfy EU AI Act algorithmic traceability mandates.
Encoding Algorithms capture the majority of venture funding; DNA-based Storage Solutions are gaining share fastest as integrated workflows reach procurement-grade reliability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal research zones and cloud infrastructure clusters concentrate DNA data storage demand across select national markets, with procurement pipelines forming near synthesis capability centers and regulatory approval pathways.
United States
National laboratory ecosystems and hyperscale cloud operators anchor pilot deployment volumes. FDA oversight of synthetic nucleotide materials shapes purity standards that propagate to storage-grade manufacturing. The San Francisco Bay Area and Boston corridor host the densest vendor qualification activity near federal funding concentrations.
Germany
Industrial research consortia and precision manufacturing clusters drive enzymatic synthesis equipment demand. ECHA monitoring of phosphoramidite waste streams elevates compliance costs for chemical-based workflows. The Munich-Stuttgart axis concentrates cleanroom infrastructure investments for silicon-based DNA synthesis workflows.
United Kingdom
Academic core facilities and national biobank initiatives absorb archival encoding pilot programs. MHRA alignment with FDA traceability standards accelerates qualified vendor pathways for biomedical research applications. The Cambridge-London corridor anchors multi-institutional synthesis infrastructure consortia.
China
Data center operators and state-backed genomics initiatives pilot cold storage alternatives to tape refresh cycles. MIIT standards for synthetic biology equipment shape domestic procurement specifications. The Yangtze River Delta cluster concentrates sequencing-throughput infrastructure near Shanghai biotech manufacturing zones.
Japan
Precision electronics manufacturers and pharmaceutical archives drive demand for century-scale retention solutions. PMDA oversight of nucleotide material traceability extends vendor qualification timelines for storage-grade applications. The Kanto region around Tokyo hosts the majority of integrated synthesis-sequencing workflow development.
DNA Data Storage Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across synthesis hardware, sequencing platforms, and software-defined encoding layers. The vendor base organizes into three strategic archetypes: silicon-based synthesis workflow providers, sequencing-throughput incumbents extending into retrieval architectures, and cloud-native operators controlling upstream encoding logic. Competitive moves concentrate on direct qualification programs with hyperscale data center buyers and enzymatic polymerization R&D partnerships that bypass phosphoramidite chemistry overhead.
Within the synthesis-specialist tier, Twist Bioscience and DNA Script exemplify divergent technology bets on silicon-based versus enzymatic polymerization workflows. Microsoft occupies a position as the dominant software-defined encoding layer provider, leveraging upstream control over error correction and base-4 translation protocols that interface with biological substrates. These three anchors represent the primary competitive vectors—substrate hardware, biological chemistry, and algorithmic control—where margin pools concentrate as the market transitions from laboratory curiosity to procurement-grade reliability.
| Leading Market Players |
|---|
| Twist Bioscience |
| Illumina |
| Microsoft |
| Iridia |
| DNA Script |
| Evonetix |
| Catalog Technologies |
| Helixworks |
| Agilent Technologies |
| Others |
Supply Flow & Price Mechanics
Phosphoramidite reagent costs cascade through enzymatic synthesis equipment pricing tiers, compressing margins for chemical-based workflow vendors while enzyme engineering specialists capture premium positioning. Data center procurement teams exploit this input-cost divergence to negotiate volume discounts against phosphoramidite incumbents.
Pricing Analysis
Short lead-time premiums for enzymatic synthesis equipment run 15-25 percent above spot-inventory phosphoramidite systems, reflecting enzyme engineering bottlenecks versus chemical hardware commoditization. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated synthesis platforms from laboratory-grade configurations. Pricing pressure stems from hyperscale buyer concentration forcing vendor consolidation around direct qualification programs. Academic organizations exhibit highest price sensitivity; defense contractors absorb premium tiers for traceability guarantees.
Supply Chain Analysis
Freight costs for silicon-based synthesis consumables concentrate margin erosion on vendors sourcing wafers from Taiwan and South Korea. Phosphoramidite precursor chemicals draw from Chinese and German specialty chemical suppliers, while enzyme engineering feeds from United States biotech fermentation clusters. Single-source vulnerability sits with photolithography equipment for silicon-based workflows. Distribution runs through laboratory supply channel intermediaries facing disintermediation by data center direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act creates a cost-of-compliance moat where automated data classification rules force vendor investment in provenance-tracking infrastructure, advantaging capitalized incumbents over bootstrap entrants.
For Market Incumbents: Deploy enzymatic polymerization R&D partnerships to bypass phosphoramidite chemistry overhead and neutralize emerging synthesis-specialist threats. Capture channel control through direct qualification programs with hyperscale data center buyers, consolidating position before tape-substitution economics mature. For New Entrants and Emerging Players: Cloud service providers serving EU healthcare verticals represent the most penetrable channel partner type, restructuring procurement specifications to preempt compliance friction. Target biomedical research archives under FDA oversight where qualified vendor pathways remain underdeveloped. Anchor go-to-market through multi-institutional academic consortia accessing shared synthesis infrastructure. For Investors and Strategic Acquirers: First regulator-mandated retention-period guarantee for genomic data archives is the leading indicator that defense vertical procurement cascades will trigger valuation step-functions for compliant storage-grade DNA manufacturers. Long-term viability centers on enzyme engineering and reaction optimization capability rather than phosphoramidite hardware. Target acquisition archetype: silicon-based workflow specialists with ISO 17025 accreditation progress and established national laboratory relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Platform Development | Reduces EPA-monitored phosphoramidite waste streams while collapsing write latency for data center buyers. |
| Software-Defined Encoding Layer Control | Microsoft anchors competitive position through upstream algorithmic interfaces with biological substrates. |
| EU AI Act Compliance Infrastructure | Automated provenance tracking satisfies algorithmic traceability mandates for European biomedical clients. |
| Direct Hyperscale Qualification Programs | Bypasses laboratory supply channel intermediaries facing disintermediation by data center procurement teams. |
| ISO 17025 Accreditation Investment | Extends archival custody chain credibility for FDA-regulated synthetic nucleotide material applications. |
Methodological Framework
SEC 10-K filings, ECHA chemical registration databases, and hyperscaler capex disclosures formed the secondary backbone, cross-referenced against primary interviews with DNA synthesis equipment procurement managers, enzymatic polymerization R&D directors, data center infrastructure planners, and FDA regulatory affairs specialists. Bottom-up and top-down triangulation validated vendor shipment estimates against federal funding allocation patterns and national laboratory ecosystem investments.
Bottom-up modeling segmented volume and value outputs across synthesis modality, end-user procurement sophistication, application retention requirements, and regional regulatory cluster intensity. CAGRs derived from enzymatic cost compression curves and tape-substitution threshold analysis. Forecast inputs incorporated phosphoramidite chemistry equipment depreciation schedules and enzyme engineering throughput improvement trajectories.
Caveats apply where EPA phosphoramidite waste stream enforcement intensity or EU AI Act implementation timelines could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Military Sensors Market
Others
Thermoformed Plastics Market
Others
Inflight Entertainment Solutions Market
Others
Mobile Computer Market
Others
Running Apparel Market
Others
Smart-Connected Power Plug Socket Market
Others
Education and Learning Analytics Market
Others
Safety Critical Software Testing Market
Others
Global Military Wearable Sensors Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
Europe Virtual Reality Gaming Market
Others
Europe Aircraft Lighting Systems Market
Others
Italy Smart Home Market
Others
Powder Coating Equipment Market
Others
Europe Polycarbonate Sheets Market
Others
Europe Postal Services Market