
 Shared Power Bank Market | 2026-2036
Shared Power Bank Market Size, Share, and Industry Trends Forecast 2026-2036
Shared Power Bank Market Insights
Lithium iron phosphate is hardening as the dominant cathode chemistry across shared power bank fleets, replacing lithium cobalt oxide variants that carried higher thermal runaway risks and shorter cycle lifespans. Anker Innovations leverages its GaN charging semiconductor expertise to sustain faster throughput per kiosk slot. Xiaomi anchors its position through ecosystem lock-in, embedding power bank access within its super-app infrastructure. Belkin International competes on enterprise channel control, securing placement contracts with North American hospitality chains and airport operators.
A shared power bank denotes a networked, temporarily accessible portable energy storage device, typically housed in modular docking stations with IoT connectivity, cell capacities ranging from 5000 mAh to 20000 mAh, and output protocols including USB-C PD and Qi wireless. These systems serve commercial environments where consumers experience battery depletion away from fixed charging infrastructure. Rental kiosks dominate installed base volumes while subscription-based deployment models capture recurring revenue streams with lower per-use friction. Fast charging technology leads hardware refresh cycles as venues prioritize turnover velocity during peak traffic windows.
China's SAMR enforces GB standards for portable lithium battery safety, mandating cell certification and traceability that filters out uncertified kiosk operators. The EU's RoHS and REACH frameworks restrict hazardous substances in electronics placed on European markets, elevating compliance costs for kiosk hardware imports. India's BIS certification requirement for lithium-ion products creates a procedural bottleneck for foreign kiosk entrants. Stakeholders must monitor how battery passport regulations and extended producer responsibility schemes reshape capital deployment timelines for fleet expansion.
Market Dynamics
Lithium iron phosphate chemistry is displacing conventional lithium-ion packs across kiosk fleets, cutting thermal runaway risks while extending cycle life beyond three thousand charges. This cell transition compresses hardware refresh timelines and reshapes supplier qualification criteria.
Growth Catalysts
- GB Standards Mandate:China's SAMR enforces portable lithium battery certification and traceability, filtering out uncertified operators and consolidating fleet ownership toward compliant deployers.
- Transit Hub Density:Urban rail stations and airport terminals in Shanghai, Beijing, and Shenzhen generate sustained rental velocity during peak commuting windows.
- GaN Semiconductor Adoption:Gallium nitride charging architectures enable faster slot turnover, reducing dwell time per device and lifting kiosk throughput during high-traffic periods.
Market Restraints
- Cell Supply Concentration:Lithium iron phosphate cathode production clusters in China's Hunan and Hubei provinces, exposing fleet operators to regional logistics disruptions and input price volatility.
- BIS Certification Bottleneck:India's Bureau of Indian Standards mandates sequential testing protocols for lithium-ion imports, extending kiosk deployment timelines by four to six months.
- Fixed Infrastructure Substitution:USB-C PD charging ports embedded in café furniture and hotel lobbies capture demand that power bank rentals previously served.
Strategic Opportunities
- Subscription Model Expansion:Monthly unlimited-use plans reduce per-transaction friction and improve customer lifetime value metrics compared to pay-per-use rental.
- RoHS Compliance Arbitrage:European REACH and RoHS frameworks restrict hazardous substances, creating first-mover advantage for kiosk operators with pre-certified hardware supply chains.
- Wireless Charging Convergence:Qi-enabled power banks paired with 5G small cell installations in smart city corridors open venue placement contracts beyond traditional retail.
Industry Challenges
- Battery Passport Implementation:EU battery passport regulations require cell-level traceability systems that demand capex-heavy fleet management software upgrades.
- Fire Suppression Integration:Kiosk manufacturers must redesign enclosure ventilation and thermal monitoring to satisfy evolving municipal safety inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shared Power Bank Market |
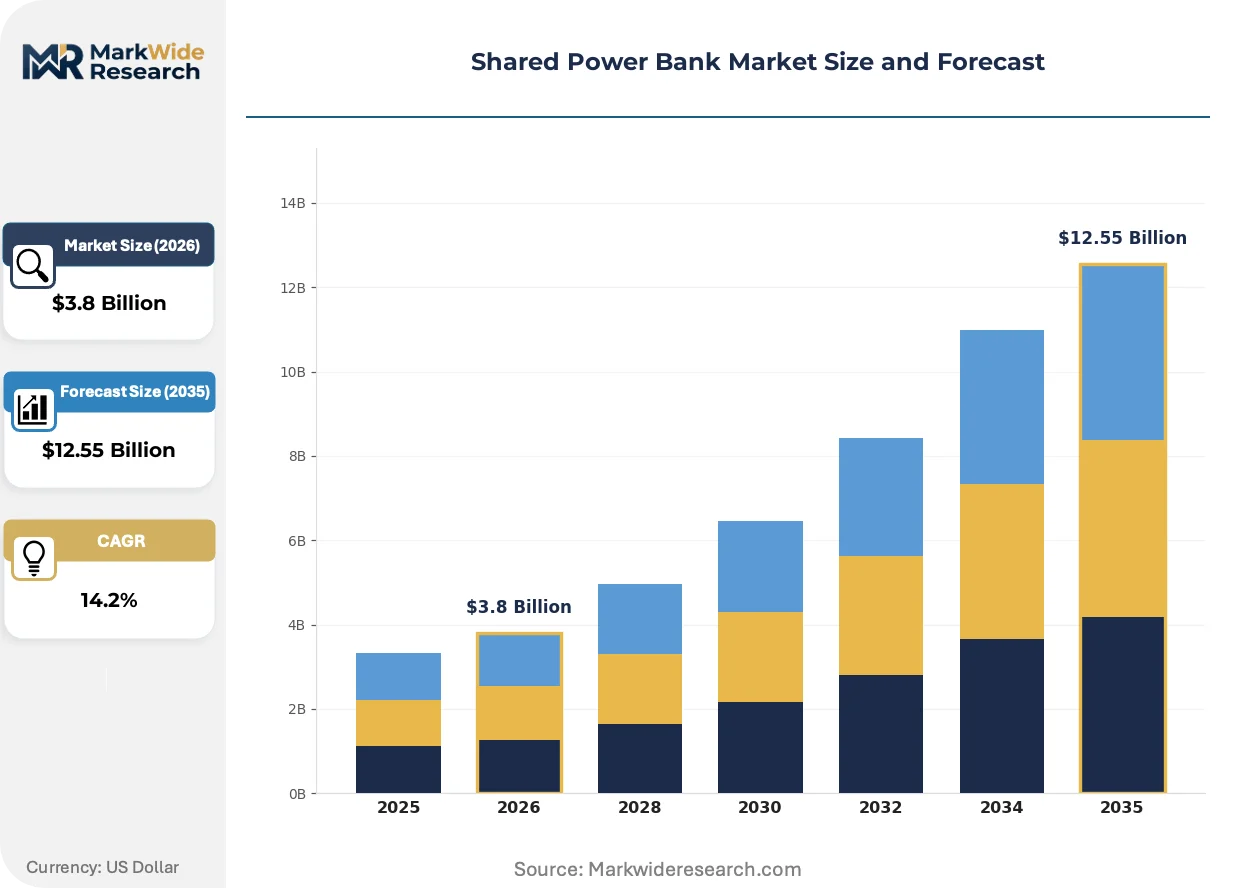
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chargers, Stationary Units, Rental Kiosks, Multi-Device Chargers Deployment Model: On-Demand, Subscription-Based, Pay-Per-Use, Event-Based Customer Type: Individuals, Businesses, Public Services, Events Charging Technology: USB-C, Wireless Charging, Fast Charging, Solar Powered |
| Companies Covered | Philips, Belkin International, Anker Innovations, Romoss, TP-Link, Xiaomi, RAVPower, Pisen, AUKEY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shared Power Bank Market Trends and Innovations
Hardware refresh cycles are compressing as venue operators prioritize turnover velocity during peak traffic windows. Three convergent developments are restructuring competitive positioning.
GaN charging semiconductors are integrating into kiosk slot architectures, enabling higher wattage output without thermal expansion. Shopping district operators in Guangzhou and Chengdu are retrofitting existing stations to capture this throughput gain. The technology is integrating faster payback periods into venue placement negotiations by demonstrating elevated daily rental volumes.
REACH substance restrictions are tightening import pathways for kiosk electronics entering European markets. Hardware vendors must reformulate solder compositions and casing polymers to maintain CE marking eligibility. Fleet operators targeting German airport concessions and French hospitality chains face elevated compliance documentation burdens.
Super-app embedding is altering consumer acquisition economics. Rental access triggered within payment or mapping applications reduces standalone app download friction. This pattern concentrates in China's tier-one cities, where ecosystem lock-in drives higher repeat usage rates than standalone kiosk interfaces.
Shared Power Bank Market Segmentation
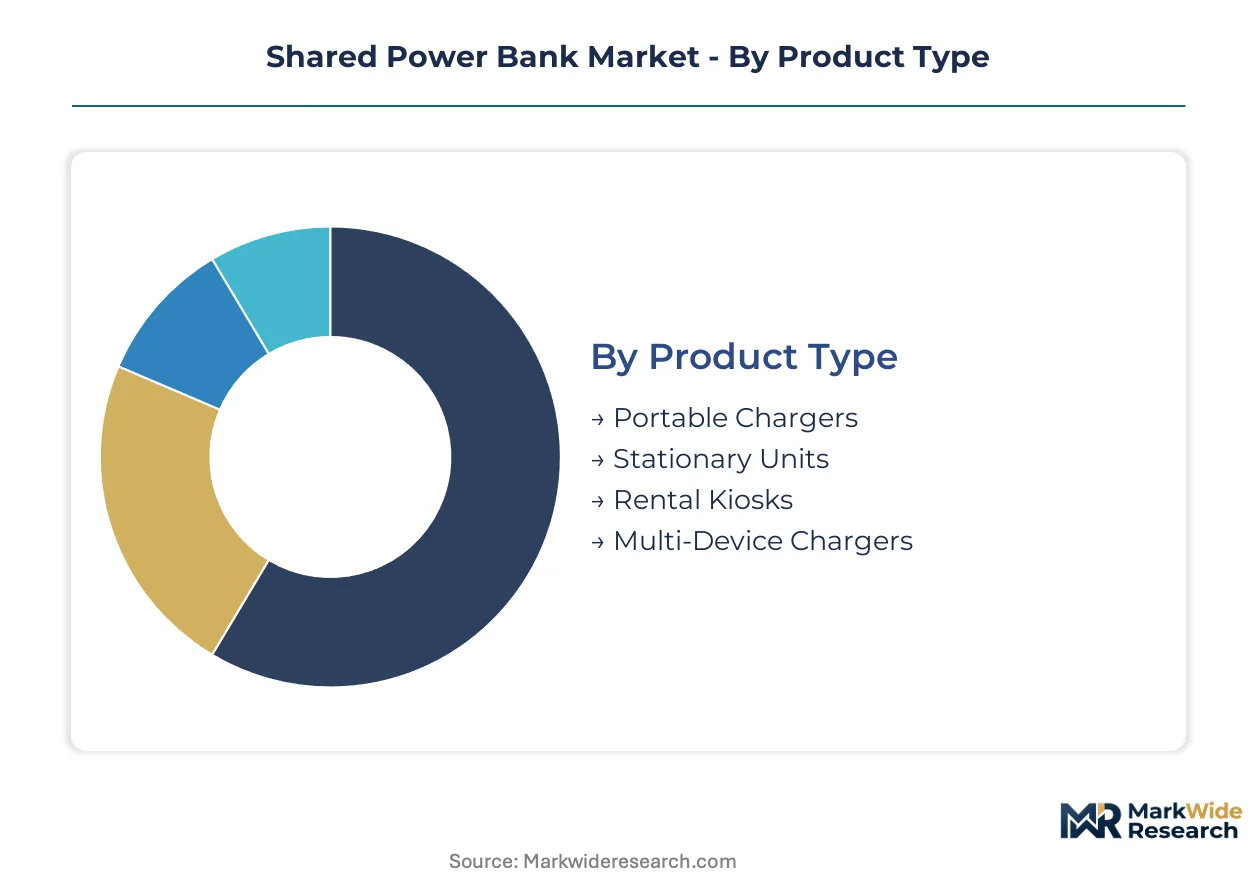
Segmentation in shared power banks determines capital deployment patterns, as certification burdens vary sharply between stationary infrastructure and portable fleet assets. Deployment models dictate recurring revenue predictability, while charging technology selections constrain hardware refresh cycles.
Product Type:
Rental Kiosks and Stationary Units carry the heaviest compliance loads under China's GB standards and India's BIS certification, while Portable Chargers navigate lighter traceability requirements.
- Rental Kiosks:Modular docking stations with IoT connectivity and 5000-20000 mAh cell banks. Demand concentrates in Shanghai and Beijing metro corridors, where SAMR certification filters out uncertified operators and consolidates fleet ownership toward compliant deployers.
- Portable Chargers:Handheld units distributed through venue partnerships rather than fixed infrastructure. Shenzhen manufacturers dominate production, with supply clustering in Guangdong province creating logistics exposure for operators sourcing at scale.
- Stationary Units:Wall-mounted or furniture-integrated charging points with embedded USB-C PD ports. Hotel lobbies in Chengdu and Guangzhou favor these for lower maintenance overhead compared to kiosk fleets.
- Multi-Device Chargers:High-capacity units serving simultaneous charging sessions. Airport terminals and convention centers deploy these to manage peak traffic windows without slot scarcity.
Leading the category by volume: Rental Kiosks. Growing fastest: Portable Chargers.
Deployment Model:
Revenue predictability separates subscription economics from transactional friction, with pay-per-use models dominating high-traffic venues while subscriptions capture commuter loyalty.
- Subscription-Based:Monthly unlimited-use plans with super-app embedding. China's tier-one cities show highest penetration, where ecosystem lock-in drives repeat usage rates above standalone kiosk interfaces.
- Pay-Per-Use:Per-minute or per-hour rental triggered at point of need. Transit hubs in Beijing and Shenzhen generate sustained velocity during peak commuting windows.
- On-Demand:Immediate rental without pre-registration through QR-code activation. Shopping districts in Guangzhou favor this for tourist foot traffic with low loyalty conversion.
- Event-Based:Temporary deployment for concerts, conferences, and sporting venues. Music festivals in Chengdu drive seasonal demand spikes with concentrated hardware logistics.
Subscription-Based captures the highest customer lifetime value. Pay-Per-Use shows the steepest expansion trajectory in transit-adjacent venues.
Customer Type:
Procurement authority and usage patterns diverge between individual consumers seeking convenience and enterprise buyers negotiating placement contracts.
- Individuals:End-users accessing power banks through retail or transit venues. Battery depletion anxiety drives adoption among smartphone-dependent commuters in dense urban corridors.
- Businesses:Corporate procurement for employee facilities and client amenities. Hospitality chains in North America negotiate multi-year placement contracts with fleet operators.
- Public Services:Government and municipal deployments in libraries, hospitals, and civic centers. India's BIS certification creates procedural bottlenecks for these installations.
- Events:Temporary organizers contracting fleet operators for duration-specific coverage. Outdoor music festivals require fire suppression integration under evolving municipal safety inspections.
Individuals account for the highest transaction frequency. Businesses deliver the most stable contract revenue.
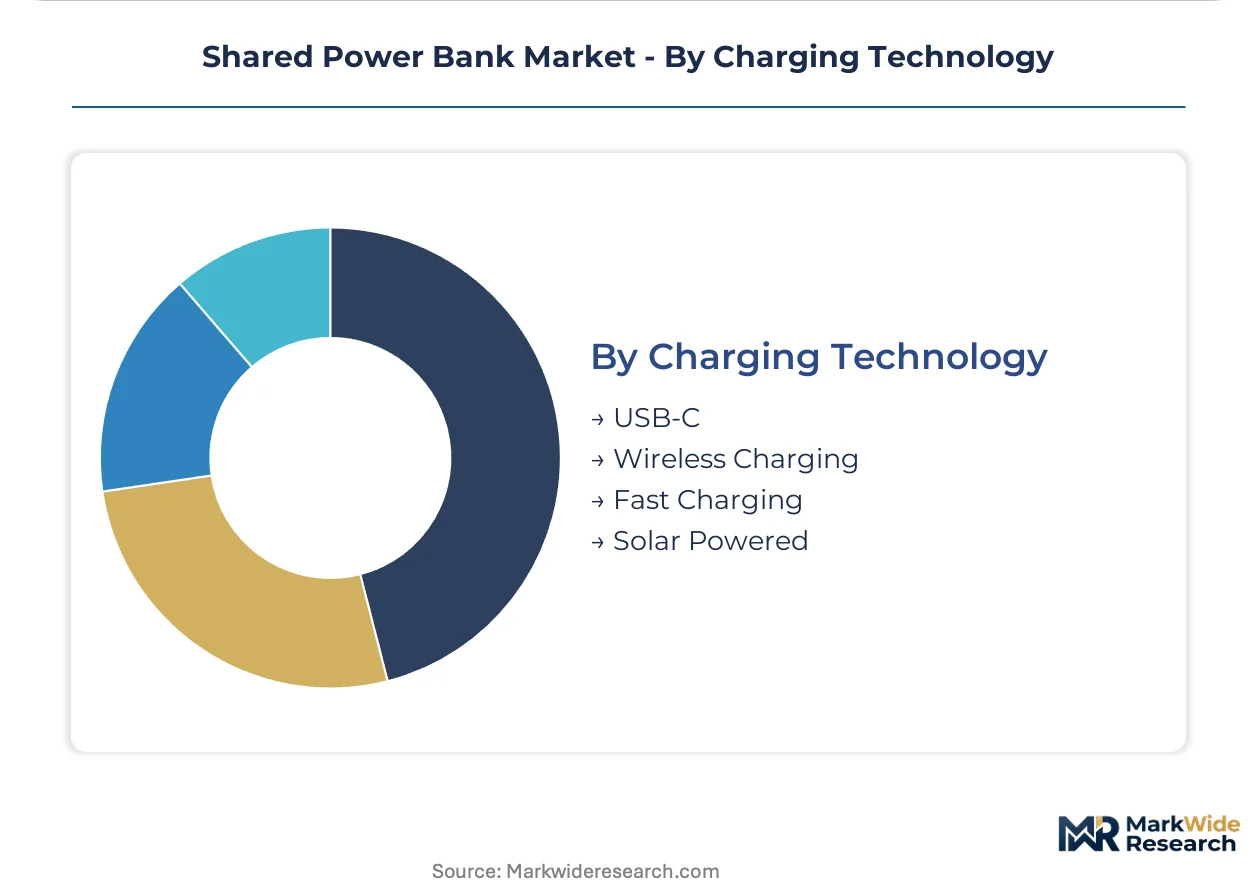
Charging Technology:
Throughput velocity and hardware cost tiers separate fast-charging architectures from baseline specifications, with GaN semiconductors enabling premium positioning.
- Fast Charging:GaN-based architectures delivering higher wattage without thermal expansion. Shopping district operators retrofit existing stations to capture turnover gains during peak traffic windows.
- USB-C:Universal Power Delivery protocol becoming baseline specification. Venue operators prioritize this for compatibility across device ecosystems.
- Wireless Charging:Qi-enabled pads eliminating cable friction. Smart city corridors pair these with 5G small cell installations for placement contracts beyond traditional retail.
- Solar Powered:Photovoltaic-integrated units for outdoor and off-grid deployment. Parks and pedestrian zones in Shenzhen pilot these for sustainability signaling.
USB-C leads by installed base. Fast Charging climbs the fastest as venues prioritize slot turnover velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's tier-one cities, where kiosk density exceeds other Asian markets. Transit corridors in Shanghai, Beijing, and Shenzhen generate sustained rental velocity during peak commuting windows. Regulatory frameworks and industrial clusters in four additional countries shape deployment economics elsewhere.
China
Urban transit hubs and shopping districts in Shanghai, Beijing, and Shenzhen drive adoption as consumers rely on on-demand charging. SAMR enforces GB standards for portable lithium battery safety, mandating cell certification and traceability that filters out uncertified kiosk operators. Lithium iron phosphate cathode production clusters in Hunan and Hubei provinces, exposing fleet operators to regional logistics disruptions.
United States
Enterprise procurement for hospitality chains and airport concessions sustains contract revenue stability. FCC certification requirements for IoT-connected kiosks create compliance documentation burdens for hardware imports. Silicon Valley and Austin technology corridors host fleet management software developers upgrading battery passport traceability systems.
Germany
REACH substance restrictions and RoHS frameworks restrict hazardous substances in electronics, elevating compliance costs for kiosk hardware imports. ECHA enforcement tightens import pathways for solder compositions and casing polymers. Frankfurt and Munich airport operators negotiate multi-year placement contracts with pre-certified hardware supply chains.
India
Battery depletion anxiety among smartphone-dependent commuters in dense urban corridors drives individual transaction frequency. BIS certification requirements for lithium-ion products create procedural bottlenecks extending kiosk deployment timelines. Mumbai and Delhi-NCR municipal deployments in transit-adjacent venues face sequential testing protocol delays.
Japan
Super-app embedding within payment and mapping applications reduces standalone app download friction. METI standards govern lithium battery safety in public infrastructure deployments. Tokyo and Osaka shopping districts favor Qi-enabled power banks paired with 5G small cell installations in smart city corridors.
Shared Power Bank Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with electronics conglomerates and pure-play power bank vendors occupying distinct tiers. The structure concentrates around ecosystem lock-in capabilities and semiconductor expertise rather than manufacturing scale alone. Three archetypes dominate: consumer electronics ecosystems, charging technology specialists, and enterprise channel operators. Consolidation pressures favor M&A activity around fleet management software capabilities and strategic partnerships securing venue placement contracts.
Among consumer electronics ecosystems, Xiaomi anchors positioning through super-app infrastructure integration. Anker Innovations exemplifies charging technology specialists leveraging semiconductor expertise for hardware differentiation. Belkin International represents enterprise channel operators securing North American hospitality and airport placement contracts. These three companies illustrate how competitive advantage derives from distinct capability sets rather than interchangeable manufacturing scale.
| Leading Market Players |
|---|
| Philips |
| Belkin International |
| Anker Innovations |
| Romoss |
| TP-Link |
| Xiaomi |
| RAVPower |
| Pisen |
| AUKEY |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between SAMR-compliant fleet operators and uncertified deployers manifests in both kiosk rental rates and supplier qualification timelines, with GB-standard hardware commanding placement premiums in Shanghai and Beijing transit corridors while uncertified units face exclusion from venue contracts.
Pricing Analysis
High-volume transit-adjacent kiosks trade margin for slot turnover velocity, while premium-tier subscription models embedded in super-app ecosystems capture superior lifetime value through reduced per-transaction friction. Price differentiation hinges on GaN semiconductor integration and SAMR certification tier, with faster-charging slots justifying rental premiums. Cost compression in baseline lithium cobalt oxide hardware is intensifying because LFP cell transitions compress refresh cycles. Individual commuters in tier-one cities show highest price sensitivity, whereas enterprise hospitality contracts demonstrate lowest sensitivity due to multi-year placement security.
Supply Chain Analysis
Freight cost exposure runs through lithium iron phosphate cathode shipments originating from Hunan and Hubei provinces to kiosk assembly clusters in Guangdong. Cell production draws from China, South Korea, and Japan, with LFP chemistry dependencies tethered to domestic Chinese mining and refining capacity. Lithium carbonate and cobalt-free cathode precursors constitute critical input categories. Single-source vulnerability concentrates in Hunan province cathode plants. Distribution runs through venue placement contracts negotiated directly with transit authorities, hospitality chains, and airport operators rather than retail channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as fleet operators pursue captive LFP cell supply to insulate against Hunan-Hubei logistics disruptions and input price volatility.
For Market Incumbents: Deploy super-app infrastructure lock-in to defend against standalone kiosk interface competitors. Consolidate fleet ownership through SAMR certification acquisition of uncertified operators. Fixed USB-C PD infrastructure substitution in hotel lobbies and cafés threatens rental velocity in premium venues. GaN semiconductor R&D investment preserves throughput differentiation against commodity hardware entrants. For New Entrants and Emerging Players: Wireless charging convergence with 5G small cell installations offers technology-first entry into smart city corridor placements underserved by traditional retail kiosk models. India's BIS certification bottleneck creates the most penetrable geographic white space, with sequential testing protocol delays extending incumbent deployment timelines. QR-code activated on-demand rentals targeting tourist foot traffic in Guangzhou shopping districts bypass subscription loyalty requirements. For Investors and Strategic Acquirers: Re-rating potential sits with fleet management software specialists given EU battery passport regulation catalysts demanding capex-heavy traceability system upgrades. Long-term viability favors operators with pre-certified hardware supply chains and venue placement contract backlogs. Battery passport implementation timelines serve as the critical inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Integration | Faster slot turnover lifts kiosk throughput during peak transit windows in Shanghai and Beijing. |
| LFP Cell Chemistry Transition | Reduced thermal runaway risks extend cycle life beyond three thousand charges per unit. |
| Super-App Embedding Partnership | Ecosystem lock-in drives repeat usage rates above standalone kiosk interface adoption. |
| EU Battery Passport Compliance | Cell-level traceability systems satisfy ECHA enforcement and secure German airport contracts. |
| Subscription Model Expansion | Monthly unlimited-use plans improve customer lifetime value metrics versus pay-per-use friction. |
Research Methodology
Independent corroboration across fleet operator executives, venue procurement managers, and LFP cell manufacturing engineers underwrites the qualitative findings. Primary interviews with IoT kiosk hardware specialists, transit authority contract officers, and hospitality chain facility directors combined with secondary validation from SAMR certification databases, BIS testing protocol disclosures, and ECHA REACH substance restriction filings. Bottom-up kiosk deployment counts triangulate against top-down addressable venue estimates.
Comparable-period anchoring to historical GB standard implementation phases and prior LFP chemistry adoption curves structured the projection horizon. Segmentation dimensions span deployment model, charging technology tier, customer procurement authority, and regional regulatory cluster. CAGRs derive from venue density saturation curves and slot turnover velocity modeling. Forecast inputs incorporate GaN semiconductor cost decline trajectories and battery passport compliance capex schedules.
Several conditions sit outside the modeled scope, including municipal fire suppression regulation evolution and fixed infrastructure substitution acceleration in hospitality segments. Forecasts reflect assumptions about LFP supply expansion and super-app ecosystem continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
Europe Advanced Distribution Management System Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
Building Energy Management Solution Market