
 Asia-Pacific Home Energy Management System Market | 2026-2036
Asia-Pacific Home Energy Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Home Energy Management System Market Insights
Smart grid engineering talent is rotating from traditional utilities toward software-centric home energy platforms, tightening supply for legacy infrastructure projects. Panasonic leverages its appliance manufacturing depth to sustain integrated thermostat-to-solar product ecosystems. Schneider Electric anchors its position through building automation expertise repurposed for residential energy control. Siemens competes with industrial-grade PLC technology scaled down for home load management applications.
Asia-Pacific Home Energy Management Systems comprise networked hardware and software that monitor, control, and optimize residential electricity consumption through real-time data analytics and automated device coordination, typically operating across 2.4 GHz wireless bands or powerline carrier frequencies between 3 kHz and 500 kHz. Their primary purpose is reducing household energy expenditure while enabling demand response participation with local utilities. Thermostat and smart meter segments dominate installed base volumes, though energy monitor hardware is recording the fastest replacement cycles as display technology costs decline. Control systems capture the deepest margin pools where property managers and real estate developers negotiate enterprise-scale deployments across multi-unit residential towers.
Japan's METI enforces home energy efficiency benchmarks that shape product certification timelines, while India's BIS and China's MIIT develop converging interoperability standards for smart meter communication protocols. Australia's Clean Energy Regulator and South Korea's KEMCO extend this framework through rebate structures tied to verified demand response performance. Stakeholders must decide whether to prioritize Wi-Fi ecosystem compatibility or Zigbee mesh reliability before regional standardization settles on a dominant protocol architecture.
Market Dynamics
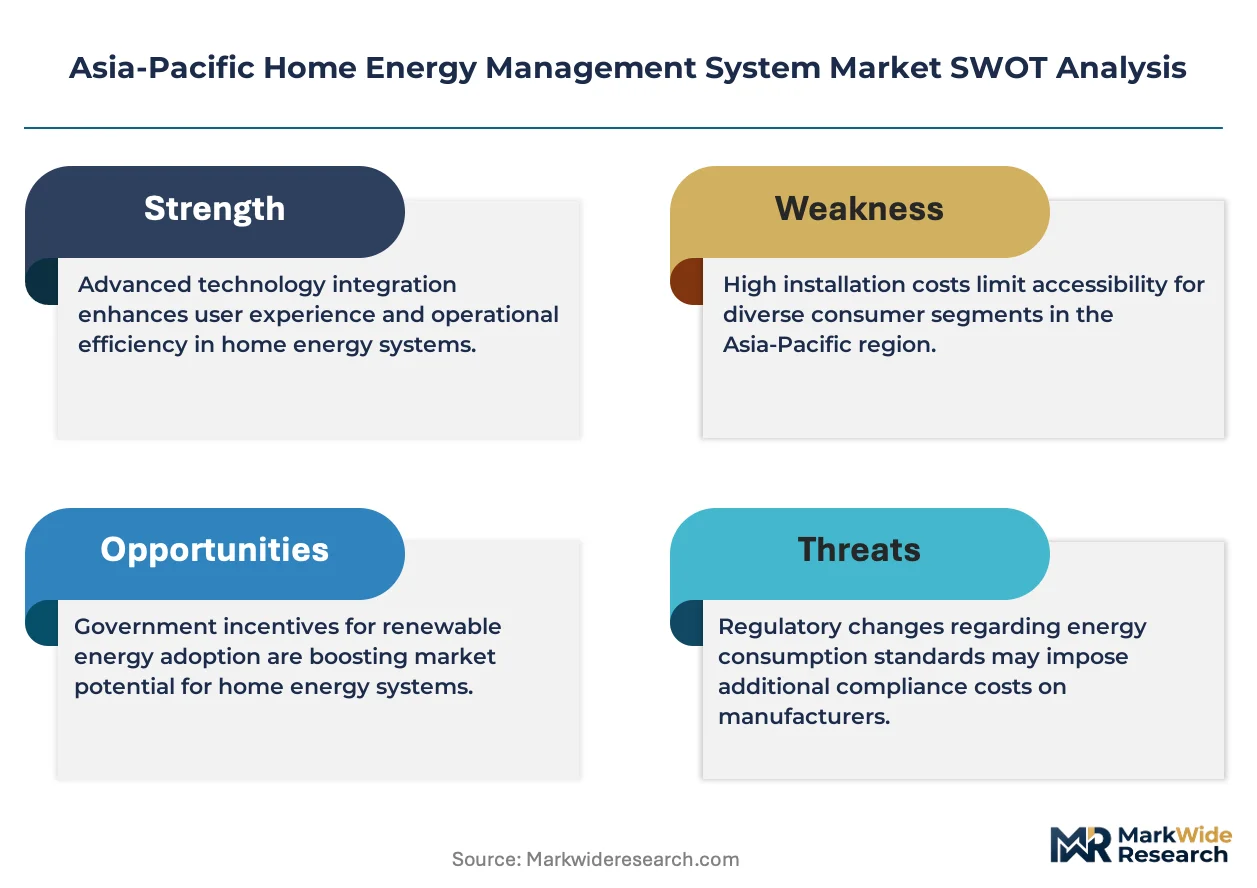
Grid modernization mandates across Japan, South Korea, and Australia are forcing hardware manufacturers to rearchitect control systems for bidirectional utility communication before regional interoperability standards solidify.
Growth Catalysts
- Japan's METI Efficiency Benchmarks:Mandatory home energy performance thresholds accelerate replacement of legacy HVAC controllers with networked systems that automatically modulate consumption during peak pricing windows.
- Apartment Complex Electrification:Southeast Asian property developers in Bangkok, Manila, and Ho Chi Minh City bundle HEMS installations into pre-sales marketing to differentiate premium residential towers.
- Powerline Carrier Resurgence:3 kHz to 500 kHz signal transmission through existing electrical wiring reduces retrofit installation costs in concrete high-rise structures where wireless propagation faces interference.
Market Restraints
- Semiconductor Supply Concentration:Discrete power management ICs for load control modules source predominantly from Taiwan and South Korea foundries, exposing manufacturers to single-geography disruption risk.
- Protocol Fragmentation:India's BIS smart meter communication standards diverge from China's MIIT specifications, forcing dual firmware development for cross-border product lines.
- Copper and Rare Earth Input Volatility:Neodymium magnet costs for smart meter relay actuators fluctuate with Chinese export quota adjustments, compressing hardware margins unpredictably.
Strategic Opportunities
- Vietnam's Underserved Urban Corridor:Da Nang and Hai Phong residential construction pipelines lack incumbent HEMS providers, creating first-mover positioning for integrated solar-storage-control bundles.
- KEMCO Rebate Structures:South Korea's demand response performance verification system pays residential aggregators for verified peak load reductions, enabling new revenue streams beyond equipment sales.
- Zigbee-WiFi Convergence:Dual-radio gateway architectures bridge utility-grade mesh reliability with consumer app ecosystem accessibility, capturing both property manager and homeowner preference sets.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for 2.4 GHz wireless stack optimization competes with automotive and medical device sectors for limited Asia-Pacific semiconductor design labor pools.
- Multi-Protocol Certification Timelines:Simultaneous BIS, MIIT, and METI approval processes extend product launch cycles by 8-14 months for manufacturers targeting three-country distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Home Energy Management System Market |
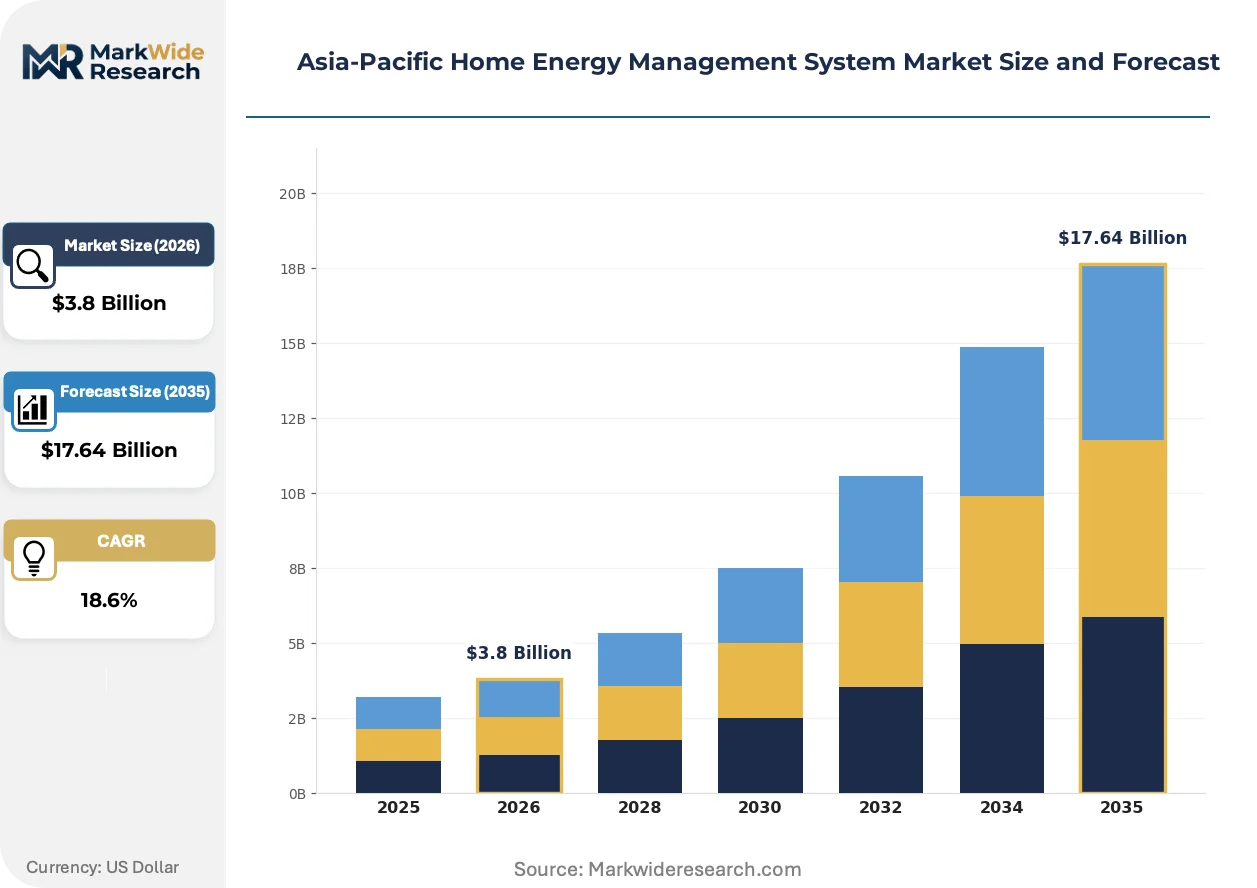
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostats, Smart Meters, Energy Monitors, Control Systems End User: Residential Users, Property Managers, Builders, Real Estate Developers Technology: Wi-Fi, Zigbee, Bluetooth, PLC Application: Automated Lighting, HVAC Control, Energy Tracking, Load Management |
| Companies Covered | IBM Corporation, Panasonic Corporation, General Electric Company, Schneider Electric, Honeywell International Inc., Siemens, Johnson Controls Inc, Eaton Corporation, Rockwell Automation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Home Energy Management System Market Trends and Innovations
Edge computing architectures are migrating load-balancing decisions from cloud servers to localized gateway processors, reducing latency for real-time demand response while complicating over-the-air update security protocols.
Artificial intelligence inference engines running on ARM Cortex-M class microcontrollers is supplanting rule-based thermostat scheduling across Japanese and Australian installations. Property managers in Osaka and Sydney are deploying these systems in 200-plus unit towers. The shift compresses energy savings payback periods from 4-6 years toward 2-3 years, accelerating replacement cycles for first-generation programmable controllers.
Australia's Clean Energy Regulator has tightened verification requirements for residential demand response claims, mandating third-party hardware attestation before rebate eligibility. This policy shift elevates compliance costs for software-only platform providers. Equipment manufacturers with embedded secure element certification capture disproportionate share of new South Wales and Victoria deployments.
Building managers increasingly specify outcome-based energy reduction contracts rather than capital equipment purchases, transferring performance risk to HEMS vendors. Schneider Electric and Panasonic have restructured Australian and Japanese sales teams around guaranteed savings offerings. The model concentrates in commercial-to-residential conversion projects where baseline consumption data supports accurate guarantee underwriting.
Asia-Pacific Home Energy Management System Market Segmentation
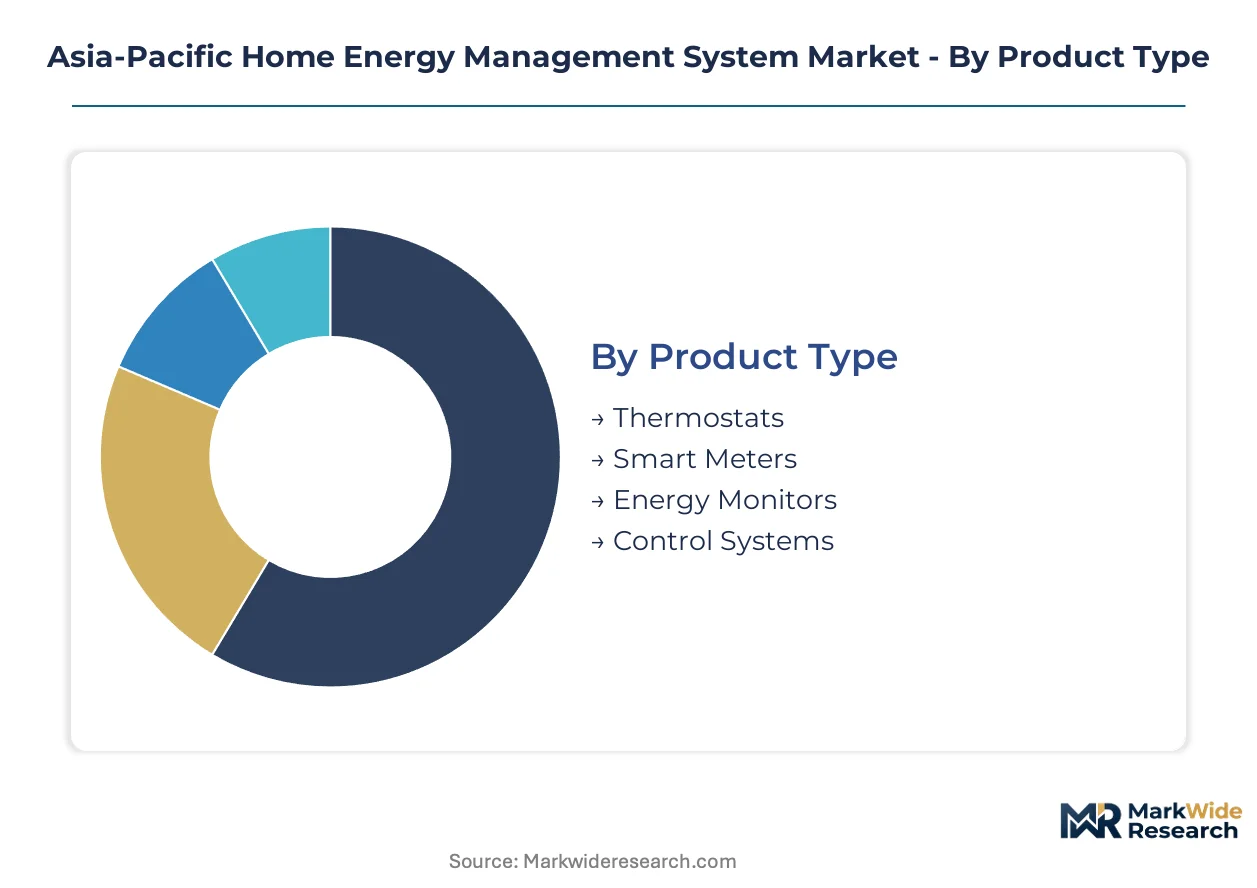
Product architecture and procurement authority diverge sharply across Asia-Pacific Home Energy Management System deployment contexts. Segment boundaries determine whether vendors compete on hardware certification cycles or software platform economics.
Product Type:
Substitution pressure intensifies as display technology commoditization erodes hardware margins and cloud-native platforms displace standalone controllers.
- Thermostats:Networked temperature controllers integrate occupancy sensors and weather APIs to modulate HVAC cycling. Japan's METI efficiency benchmarks accelerate replacement of legacy programmable units in Osaka and Tokyo prefectures where grid modernization programs are most advanced.
- Smart Meters:Bidirectional communication hardware enabling utility demand response participation. India's BIS certification mandates and China's MIIT protocol specifications force dual firmware development for cross-border product lines, extending launch timelines.
- Energy Monitors:Real-time consumption display hardware with declining unit economics.
- Control Systems:Centralized load management hubs commanding multiple end-point devices.
Smart meters anchor the volume base while energy monitors gain share at the steepest rate.
End User:
Procurement authority concentrates with entities controlling multi-unit deployment scale rather than individual household decision-makers.
- Residential Users:Individual homeowners purchasing standalone devices through retail channels. Australia's Clean Energy Regulator rebate structures shape purchase timing, while South Korea's KEMCO performance verification requirements elevate hardware certification importance over software-only solutions.
- Property Managers:Professional operators of multi-unit residential towers negotiating enterprise-scale installations. Bangkok and Ho Chi Minh City developers bundle HEMS into pre-sales marketing for premium apartment complexes, shifting procurement toward outcome-based energy reduction contracts.
- Builders:Construction firms specifying pre-installed systems during residential development.
- Real Estate Developers:Project sponsors financing integrated solar-storage-control bundles in Vietnam's Da Nang and Hai Phong corridors.
Property managers drive margin concentration through volume aggregation while real estate developers expand most quickly in underserved urban construction pipelines.
Technology:
Protocol fragmentation across national regulators fragments the addressable market for single-radio hardware architectures.
- Wi-Fi:Consumer-facing connectivity leveraging existing home internet infrastructure. Australia's residential demand response verification requirements favor Wi-Fi-enabled systems with embedded secure element certification for rebate eligibility in New South Wales and Victoria.
- Zigbee:Mesh networking protocol prioritized for utility-grade reliability. Japan's urban prefectures deploy Zigbee-enabled aggregators for verified peak load reduction participation, though firmware engineering talent scarcity competes with automotive and medical device sectors.
- Bluetooth:Short-range pairing for device commissioning and mobile app interfaces.
- PLC:Powerline carrier transmission through existing electrical wiring reduces retrofit costs in concrete high-rise structures across Southeast Asian markets where wireless propagation faces interference.
Zigbee dominates utility-facing deployments while dual-radio Wi-Fi/Zigbee gateways climb the fastest as vendors bridge consumer app accessibility with mesh reliability.
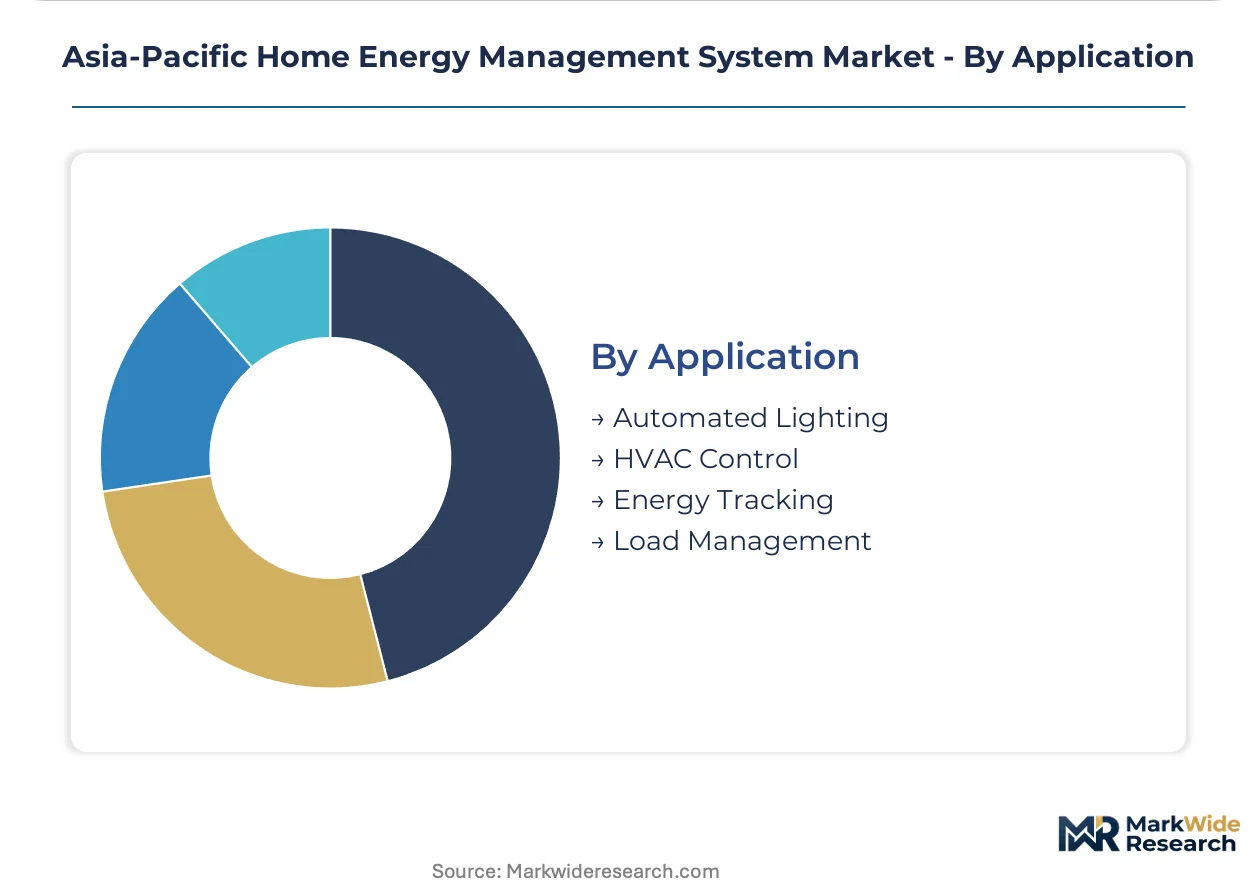
Application:
Functional integration determines whether deployments emphasize immediate cost reduction or grid-interactive revenue participation.
- Automated Lighting:Occupancy-based illumination control with shortest payback periods. AI inference engines on ARM Cortex-M microcontrollers supplant rule-based scheduling in Japanese and Australian installations, compressing energy savings payback toward two to three years.
- HVAC Control:Climate system optimization representing the largest single load category. METI mandatory performance thresholds force automatic consumption modulation during peak pricing windows, accelerating networked controller adoption.
- Energy Tracking:Consumption visibility and analytics without automated control intervention.
- Load Management:Active demand response enabling utility-directed curtailment events.
HVAC control captures the deepest installed base while load management expands most quickly as Australia's Clean Energy Regulator tightens verification requirements for residential demand response claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific region, with Japan and South Korea emphasizing utility-integrated demand response while Southeast Asian markets prioritize cost reduction through retrofit powerline carrier installations. India's regulatory-driven smart meter rollout follows a procurement-heavy model distinct from Australia's rebate-stimulated residential adoption.
Japan
Tokyo and Osaka prefectures concentrate deployment of networked HVAC controllers under METI mandatory efficiency benchmarks that force automatic consumption modulation during peak pricing windows. Grid modernization programs in these urban corridors accelerate replacement of legacy programmable thermostats with AI-enabled systems. Property managers in Kansai region towers negotiate outcome-based energy reduction contracts, transferring performance risk to equipment vendors.
South Korea
KEMCO rebate structures pay residential aggregators for verified peak load reductions, creating revenue streams beyond equipment sales in Seoul Capital Area apartment complexes. The Busan-Ulsan industrial corridor sees Zigbee mesh deployments prioritized for utility-grade reliability in multi-unit towers. Firmware engineering talent scarcity competes with automotive and medical device sectors for limited semiconductor design labor pools.
India
BIS certification mandates for smart meter communication protocols force dual firmware development for cross-border product lines, extending launch timelines by 8-14 months. Maharashtra and Gujarat states lead procurement volumes through state electricity distribution company tenders. Concrete high-rise construction in Mumbai and Ahmedabad drives powerline carrier adoption where wireless propagation faces interference.
Australia
New South Wales and Victoria deployments concentrate where the Clean Energy Regulator mandates third-party hardware attestation before rebate eligibility for residential demand response claims. Sydney and Melbourne property managers specify outcome-based energy reduction contracts rather than capital equipment purchases. Embedded secure element certification captures disproportionate share of new installations as software-only platform providers face elevated compliance costs.
Vietnam
Da Nang and Hai Phong residential construction pipelines lack incumbent HEMS providers, creating first-mover positioning for integrated solar-storage-control bundles. Bangkok and Ho Chi Minh City developers in neighboring markets bundle installations into pre-sales marketing, pressuring Vietnamese developers to match premium positioning. Powerline carrier transmission through existing electrical wiring reduces retrofit installation costs in concrete high-rise structures.
Asia-Pacific Home Energy Management System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with appliance manufacturers and building automation specialists commanding enterprise-scale deployments while component vendors compete on certification velocity. Panasonic leverages manufacturing depth for thermostat-to-solar product ecosystems. Schneider Electric anchors through building automation expertise repurposed for residential energy control. Siemens competes with industrial-grade PLC technology scaled down for home load management. Dominant competitive moves include strategic partnerships with property developers and geographic expansion into Vietnam's underserved urban corridors.
Within the integrated systems tier, Panasonic Corporation and Schneider Electric occupy positions bridging hardware certification depth with software platform economics. Among industrial technology providers, Siemens represents the archetype of scaled-down automation expertise entering residential markets. IBM Corporation sits within the data analytics and cloud infrastructure layer, exemplifying IT services firms extending into energy management software without manufacturing exposure.
| Leading Market Players |
|---|
| IBM Corporation |
| Panasonic Corporation |
| General Electric Company |
| Schneider Electric |
| Honeywell International Inc. |
| Siemens |
| Johnson Controls Inc |
| Eaton Corporation |
| Rockwell Automation |
| Others |
Pricing and Supply Chain Analysis
Powerline carrier modules replacing Zigbee radios in Southeast Asian retrofit installations simultaneously shift component sourcing toward Taiwan and South Korea foundries while compressing hardware margins through display technology commoditization. This substitution dynamic redistributes pricing power from wireless stack specialists toward power management IC integrators as property managers negotiate enterprise-scale deployments.
Pricing Analysis
Long-term offtake contracts dominate procurement between real estate developers and control system vendors, though spot purchasing persists for energy monitor hardware in retail channels. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels differentiates offerings, with METI and BIS certification tiers commanding substantial premiums. Cost compression in energy monitor hardware is intensifying because display panel costs decline faster than firmware development expenses. Property managers exhibit lowest price sensitivity due to outcome-based contract structures, while individual residential users in India and Vietnam drive hard bargaining on upfront equipment costs.
Supply Chain Analysis
Inventory lead times for discrete power management ICs stretch unpredictably as Taiwan and South Korea foundries prioritize automotive and medical device orders over residential energy components. Neodymium magnet supply for smart meter relay actuators draws from Chinese processing facilities, while ARM Cortex-M microcontroller production concentrates with Taiwanese semiconductor houses. Single-source vulnerability in rare earth magnet procurement exposes hardware margins to Chinese export quota adjustments. Distribution runs through building automation integrators in Japan and Australia, direct developer relationships in Southeast Asia, and state electricity distribution company tenders in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Home Energy Management System market sits in early-cycle recovery as grid modernization mandates across Japan, South Korea, and Australia force replacement of legacy HVAC controllers with networked systems.
For Market Incumbents: Fortify certification depth across BIS, MIIT, and METI approval pathways to extend product launch cycle advantages over challengers facing 8-14 month regulatory delays. Deepen captive supply of power management ICs through foundry partnerships in Taiwan and South Korea to offset semiconductor concentration risk. Control system vendors should expand outcome-based energy reduction contract capabilities to capture property manager procurement shifts in Sydney, Melbourne, and Osaka towers. For New Entrants and Emerging Players: Lead with integrated solar-storage-control bundles in Vietnam's Da Nang and Hai Phong corridors where incumbent presence remains minimal. Target KEMCO rebate-eligible Zigbee mesh deployments in Seoul Capital Area apartment complexes for verified peak load reduction revenue streams. Pursue white-label partnerships with Bangkok and Ho Chi Minh City property developers seeking pre-sales differentiation through bundled HEMS installations. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors vertically integrated hardware-software platforms over pure-play software providers facing Australia's Clean Energy Regulator hardware attestation requirements. Acquisition candidates with embedded secure element certification and multi-protocol firmware stacks offer strongest five-to-ten year viability as regional interoperability standards converge. Monitor BIS-MIIT protocol harmonization progress as inflection indicator for cross-border product line profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Protocol Certification Investment | Simultaneous BIS and METI approval captures cross-border distribution in India and Japan. |
| Outcome-Based Contract Restructuring | Guaranteed savings offerings align with Australian and Japanese property manager procurement preferences. |
| Foundry Partnership Deepening | Taiwan and South Korea semiconductor relationships secure power management IC allocation priority. |
| Edge Computing Architecture Migration | Localized gateway processors reduce latency for Japan's demand response participation requirements. |
| Vietnam Market Entry | First-mover positioning in Da Nang and Hai Phong construction pipelines lacks incumbent competition. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with smart grid engineering directors, property management procurement leads, BIS certification specialists, and utility demand response program managers. Secondary validation drew from METI efficiency benchmark filings, Australia's Clean Energy Regulator rebate disbursement records, KEMCO performance verification databases, and state electricity distribution company tender documents across Maharashtra and Gujarat. Bottom-up installation volume estimates triangulated against top-down addressable household projections.
Across the analysis window, forecasts model product type substitution dynamics, technology protocol adoption curves, and end-user procurement authority shifts. Segmentation dimensions include hardware versus software revenue mix, utility-integrated versus standalone deployment architecture, and new construction versus retrofit installation context. CAGRs derive from S-curve penetration modeling calibrated to regulatory mandate implementation timelines and rebate program budget trajectories.
Underlying assumptions cover grid modernization program continuity, rare earth magnet supply stability, and firmware engineering labor pool availability, with deviation risk concentrated in semiconductor foundry allocation decisions and cross-border protocol harmonization delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
AI Water Heater Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Global Data Center Energy Management Solution Market