
 Smart Bread Maker Market | 2026-2036
Smart Bread Maker Market Size, Share, and Industry Trends Forecast 2026-2036
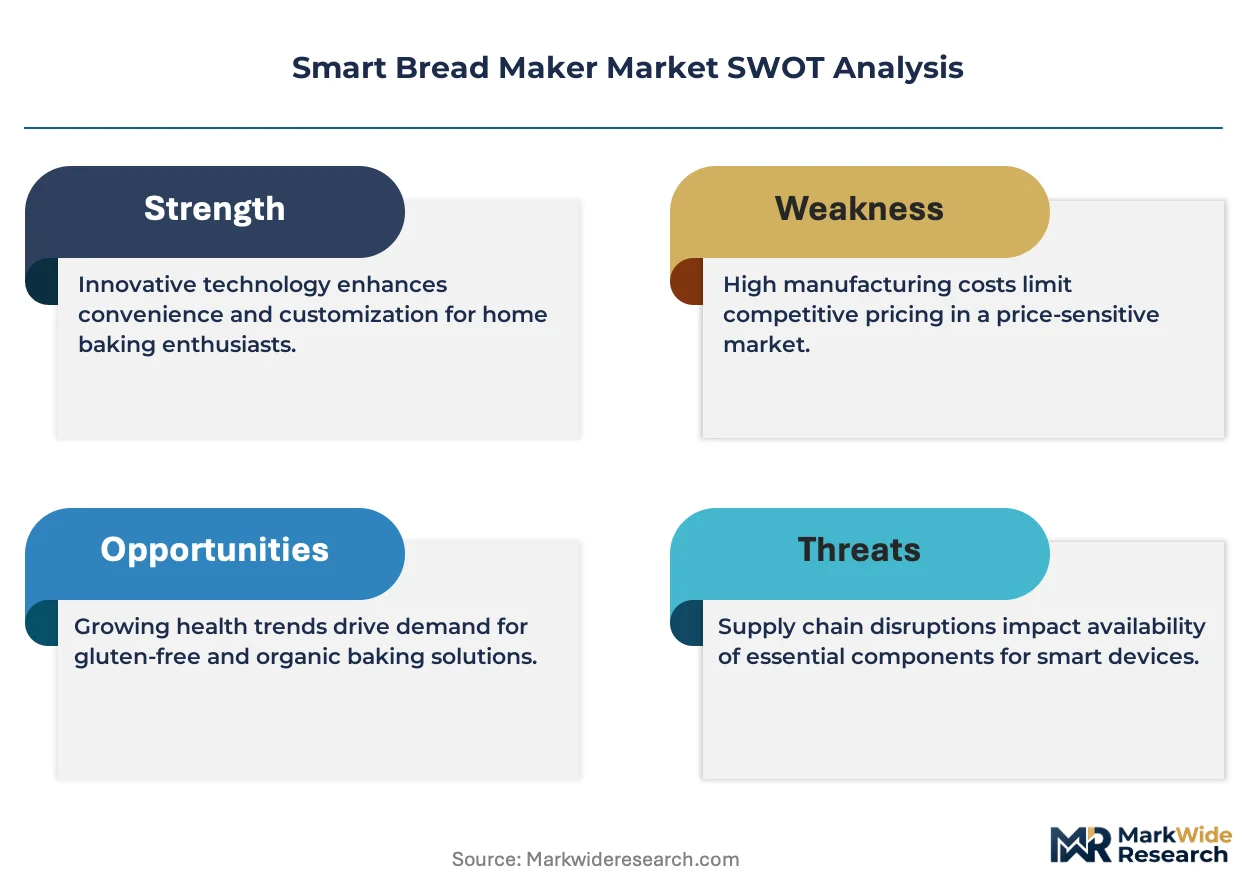
Smart Bread Maker Market Analysis
China is narrowing its component supply chain for smart bread maker motors and heating elements, consolidating domestic sourcing for export-oriented manufacturers. Panasonic Corporation leverages vertical integration across its appliance division to control sensor quality and firmware development. Zojirushi Corporation anchors premium positioning through precise temperature algorithm specialization in East Asian markets. Breville Group Limited competes on design-led differentiation and direct-to-consumer channel control in English-speaking markets.
A smart bread maker is an automated countertop appliance that mixes, kneads, proofs, and bakes bread through microprocessor-controlled thermal cycling, typically operating between 120°C and 230°C with programmable crust darkness and loaf size parameters. Its primary commercial purpose is to reduce manual intervention in bread preparation while standardizing output consistency for home and small commercial kitchens. Automatic and programmable product types dominate unit volume, though artisan models command disproportionate margin pools through specialized gluten-free and sourdough cycle portfolios. Wi-Fi connectivity and recipe integration features represent the fastest-expanding feature set, enabling remote start and cloud-based recipe libraries that lock users into manufacturer ecosystems.
The US Consumer Product Safety Commission and FCC regulate electrical safety and wireless transmission standards respectively, while the EU CE marking and RoHS directives govern material composition and electromagnetic compliance for European market access. These frameworks elevate compliance costs for new entrants but protect established manufacturers from low-quality imports. Stakeholders must monitor evolving energy efficiency labeling requirements and right-to-repair legislation that could mandate replaceable heating element designs.
Market Dynamics
The smart bread maker market is experiencing structural compression as connected kitchen ecosystems force appliance makers to choose between proprietary cloud platforms and third-party interoperability standards.
Growth Catalysts
- EU F-Gas Regulation:Compressor-based cooling component mandates are accelerating R&D investment in alternative thermal management systems for extended dough preservation features.
- Urban home bakers:Dense metropolitan households in Germany and Japan are adopting Wi-Fi-enabled units to automate bread preparation within constrained kitchen footprints.
- Gluten-free cycle specialization:Precision fermentation algorithms are attracting consumers with dietary restrictions who previously avoided homemade bread.
Market Restraints
- Heating element supply concentration:China dominates nichrome wire and ceramic heater production, creating input cost volatility for manufacturers outside East Asia.
- RoHS compliance friction:EU material composition directives elevate redesign costs for legacy product lines seeking CE marking renewal.
- Countertop appliance substitution:Multi-function air fryers and combi-ovens with bread modes capture price-sensitive consumers seeking unit consolidation.
Strategic Opportunities
- India's emerging smart home segment:BIS certification pathways and rising disposable incomes in Mumbai and Bangalore create first-mover positioning for connected appliance entrants.
- Cloud recipe subscription models:Recurring revenue streams from proprietary ingredient partnerships and personalized nutrition algorithms offset hardware margin compression.
- Right-to-repair legislative tailwinds:EU and US state-level mandates for replaceable heating elements and modular control boards favor manufacturers with serviceable design architectures.
Industry Challenges
- Firmware security certification:FCC wireless transmission standards and emerging IoT cybersecurity frameworks extend product launch timelines by 8-14 months.
- Legacy kitchen integration:Consumers with non-smart appliances resist ecosystem lock-in, forcing manufacturers to support fragmented voice assistant protocols.
- Artisan cycle calibration:Sourdough and long-fermentation modes require temperature algorithm expertise that concentrates among specialized engineering teams in Osaka and Stuttgart.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bread Maker Market |
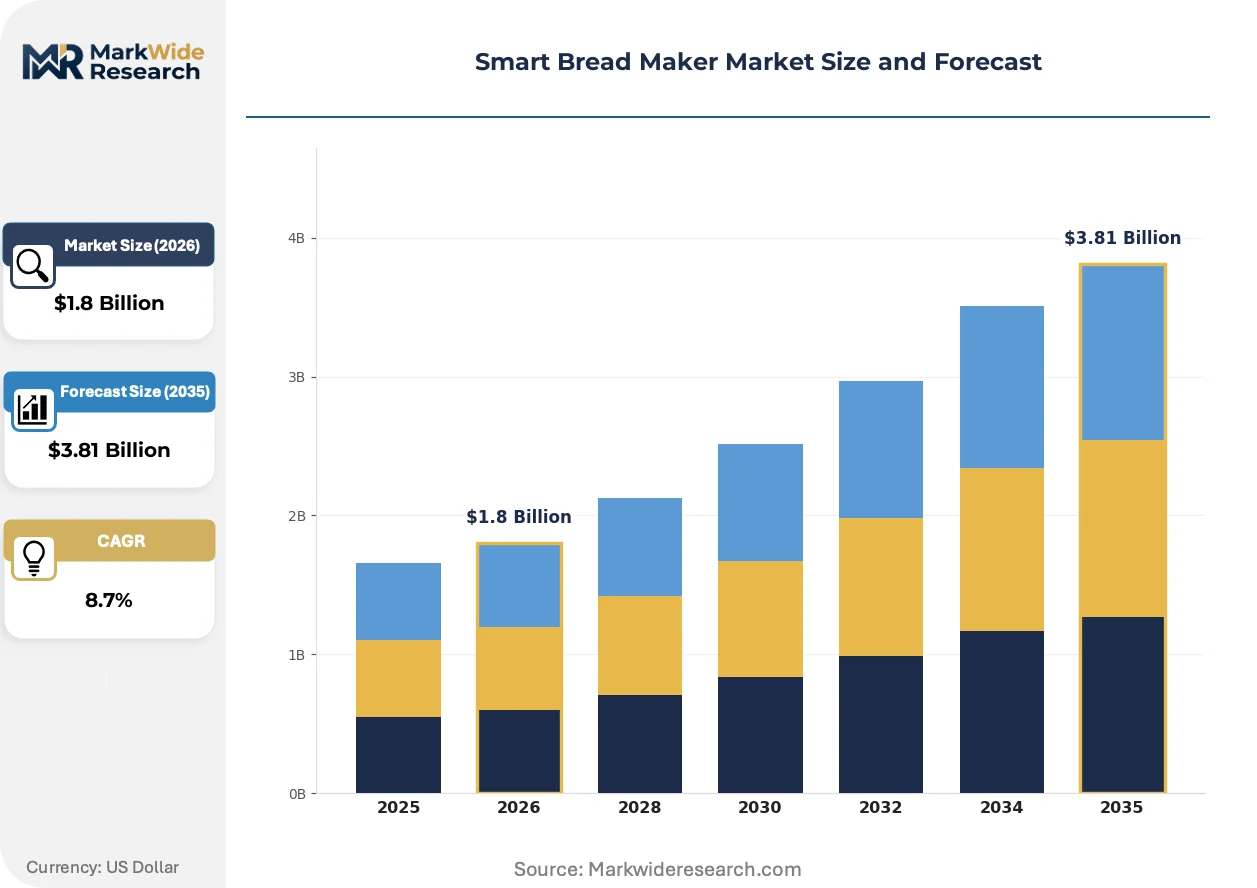
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Programmable, Compact, Artisan Feature: Wi-Fi Connectivity, Touchscreen, Recipe Integration, Self-Cleaning End User: Home Bakers, Professional Chefs, Restaurants, Bakeries Capacity: 1 lb, 2 lb, 3 lb, 4 lb |
| Companies Covered | Panasonic Corporation, Zojirushi Corporation, Midea Group, Koninklijke Philips N.V., Cuisinart, Breville Group Limited, Electrolux AB, Hamilton Beach, Jarden (Oster), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bread Maker Market Emerging Trajectories
Sensor fusion and thermal imaging are transforming how home bakers monitor dough development, compressing the skill gap between amateur and artisan output.
Precision temperature algorithms with multi-zone infrared sensing are digitizing crust formation control. Urban professionals in Seoul and Singapore are adopting these units at triple the rate of conventional programmable models. The technology is digitizing quality consistency metrics that previously required professional training, enabling premium pricing for entry-level users.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in compressor-based cooling modules. Manufacturers serving European markets must redesign thermal preservation subsystems using hydrocarbon or thermoelectric alternatives. German and French importers are accelerating supplier audits to ensure component traceability under the new quota allocation system.
Direct-to-consumer channel expansion is disrupting traditional appliance retail in English-speaking markets. Breville and specialist brands are bypassing big-box distributors through owned e-commerce and subscription bundling. Australia and the United Kingdom show the steepest channel shift, with online pure-play volumes now exceeding kitchen specialty store sales for premium SKUs.
Smart Bread Maker Market Segmentation
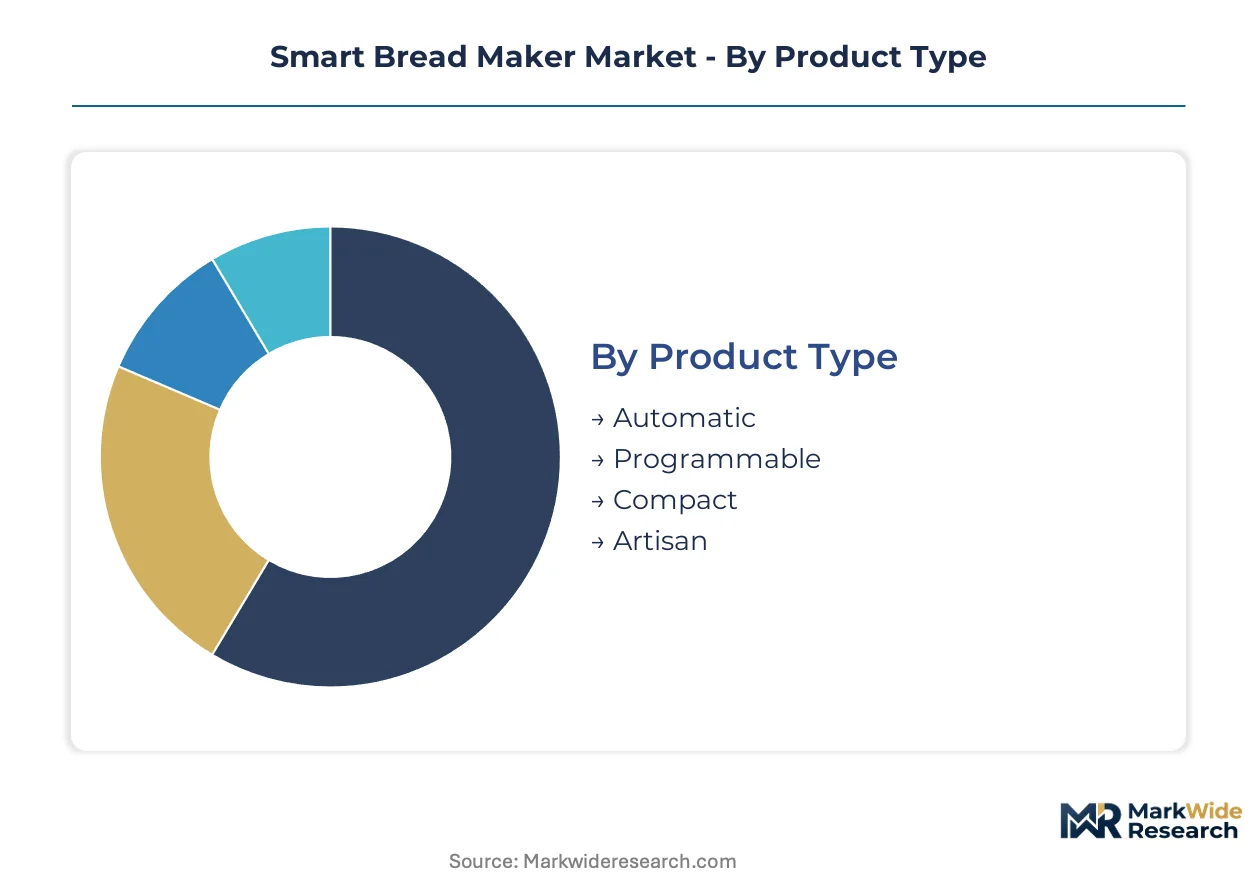
Smart bread maker manufacturers configure product portfolios around distinct usage intensities and technical sophistication levels. Segment boundaries determine warranty terms, firmware update cadence, and aftermarket revenue potential across installed bases.
Product Type:
Automatic models turn inventory fastest through mass retail channels, while artisan units sit longest in specialty stores awaiting discerning buyers. Cycle velocity directly shapes working capital requirements and promotional calendar density.
- Automatic:Microprocessor-controlled units with preset programs for white, wheat, and basic specialty breads dominate unit shipments through big-box retailers. German urban households favor these for weekday breakfast preparation where consistency trumps customization.
- Programmable:Units offering user-defined knead, rise, and bake parameters attract hobbyist bakers seeking recipe experimentation. Demand concentrates in Japan where METI energy efficiency labeling influences purchase decisions toward precise thermal control systems.
- Compact:Space-constrained designs target studio apartments and RV installations with reduced loaf capacity. Seoul and Singapore show disproportionate adoption rates among single-person households.
- Artisan:Extended fermentation cycles and steam injection capabilities serve sourdough enthusiasts. Premium positioning in French and Italian markets leverages CE marking compliance as a quality signal.
Automatic units anchor the volume base while artisan models gain share at the steepest rate through specialized gluten-free and long-fermentation portfolios.
Feature:
Hardware-software integration depth separates margin tiers, with connectivity modules adding BOM cost but enabling recurring revenue architectures. Feature bundling strategies vary by distribution channel and customer lifetime value projections.
- Wi-Fi Connectivity:Remote start and cloud synchronization capabilities transform bread makers into IoT kitchen nodes. FCC certification requirements extend development timelines for North American market entry.
- Touchscreen:Capacitive interfaces with recipe visualization command premium positioning in English-speaking direct-to-consumer channels. Interface localization costs fragment SKU economics across linguistic markets.
- Recipe Integration:Proprietary cloud libraries and ingredient partnership programs create ecosystem lock-in. Subscription monetization potential attracts venture-backed appliance startups.
- Self-Cleaning:Automated kneading blade and chamber maintenance cycles reduce user friction. RoHS compliance for cleaning agent reservoirs complicates EU market access.
Wi-Fi connectivity commands the highest attachment rates in new purchases while self-cleaning functions expand most quickly as a table-stakes expectation in premium tiers.
End User:
Usage intensity and replacement frequency diverge sharply between domestic and commercial applications, dictating service infrastructure investments and warranty pricing.
- Home Bakers:Residential consumers operating units 2-4 times weekly drive replacement cycles every 5-7 years. German and Japanese markets show highest per-capita penetration among metropolitan professionals.
- Professional Chefs:Restaurant kitchen deployments require NSF or equivalent food safety certifications and accelerated service response. Small-batch consistency needs favor programmable over automatic units.
- Restaurants:Front-of-house bread service programs in casual dining chains seek compact units with rapid cycle times. Volume constraints limit addressable market relative to central bakery supply.
- Bakeries:Micro-bakeries and retail storefronts use smart bread makers for test batches and limited specialty runs. EU F-Gas Regulation compliance for cooling-equipped models affects procurement specifications.
Home bakers provide the installed base foundation while professional chef adoption climbs fastest as culinary education programs integrate automated fermentation curricula.
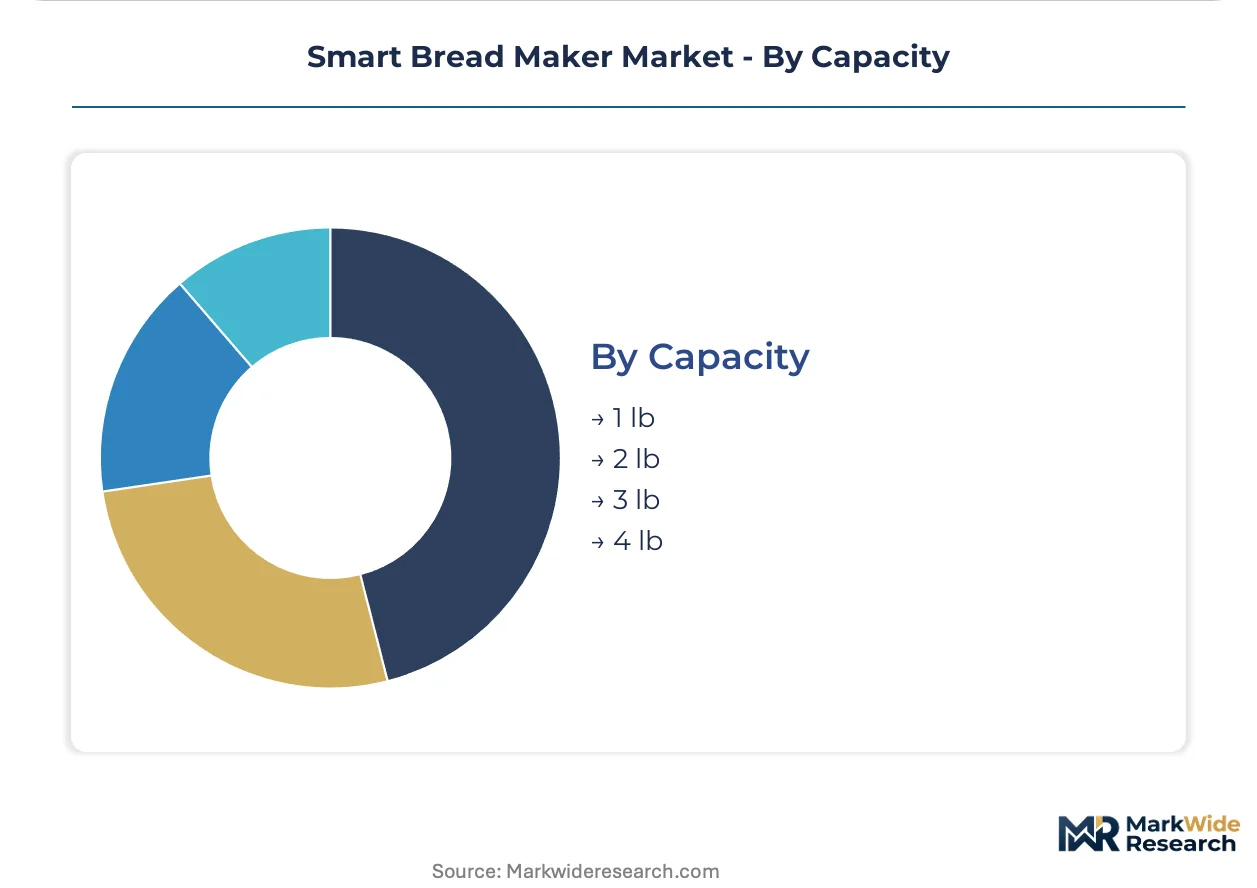
Capacity:
Loaf size selection correlates with household composition and storage constraints, with regional baking traditions influencing preferred formats.
- 1 lb:Single-serve and couple-oriented designs minimize countertop footprint and ingredient waste. Dense Asian urban markets favor this format for daily fresh bread consumption.
- 2 lb:Standard family-size output matches conventional slicing bread dimensions across North American and European markets. Highest SKU proliferation and promotional intensity.
- 3 lb:Extended family and small entertaining applications justify premium positioning. Limited distribution through specialty kitchen retailers.
- 4 lb:Maximum output configurations serve multi-generational households and intermittent bulk baking. Niche demand in rural markets and among meal-preparation communities.
Two-pound capacity maintains volume dominance while one-pound configurations expand most quickly through Asia-Pacific urban densification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European market access requirements, while metropolitan density and artisan baking traditions shape demand patterns across Germany, Japan, the United States, China, and India.
Germany
Urban professionals in Berlin and Munich automate weekday bread preparation through Wi-Fi-enabled units. The EU F-Gas Regulation mandates hydrocarbon alternatives in compressor-based cooling subsystems. Stuttgart engineering clusters specialize in precision temperature algorithm development for extended fermentation cycles.
Japan
METI energy efficiency labeling steers consumer preference toward precise thermal control systems. Compact 1-pound designs dominate Tokyo and Osaka studio apartment installations. Osaka-based engineering teams concentrate sourdough calibration expertise for premium artisan models.
United States
FCC wireless transmission certification extends development timelines for IoT-connected entrants. Direct-to-consumer channel expansion accelerates in California and New York metro areas. Seattle and Austin smart home ecosystems drive Wi-Fi connectivity attachment rates above national averages.
China
Domestic sourcing consolidation for motors and heating elements reduces export manufacturer input volatility. GB standards and MIIT regulations govern electromagnetic compliance for connected appliance certification. Shenzhen and Dongguan component clusters supply nichrome wire and ceramic heaters to global assembly networks.
India
Rising disposable incomes in Mumbai and Bangalore create first-mover positioning for connected appliance entrants. BIS certification pathways establish technical barriers for unqualified imports. Maharashtra and Karnataka urban households show accelerating adoption of programmable units for recipe experimentation.
Smart Bread Maker Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base spans Japanese precision engineering specialists, Chinese diversified appliance conglomerates, and English-speaking design-led brands. Three archetypes dominate: vertical integrators controlling sensor quality and firmware development; premium positioning specialists leveraging temperature algorithm expertise; and direct-to-consumer operators bypassing traditional retail channels. Competitive moves center on cloud platform ecosystem lock-in and modular serviceable design architectures responding to right-to-repair mandates.
Within the Japanese specialist tier, Panasonic Corporation and Zojirushi Corporation exemplify precision engineering anchoring. Chinese scale advantages concentrate with Midea Group. Among English-speaking design-led operators, Breville Group Limited occupies the premium direct-to-consumer position. These three company structures represent distinct strategic postures: captive supply chain control, algorithm specialization, and channel disintermediation respectively.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Zojirushi Corporation |
| Midea Group |
| Koninklijke Philips N.V. |
| Cuisinart |
| Breville Group Limited |
| Electrolux AB |
| Hamilton Beach |
| Jarden (Oster) |
| Others |
Supply Flow & Price Mechanics
Shanghai-Ningbo container freight corridors transmit cost volatility from Chinese heating element clusters to German and Japanese assembly plants, compressing margins for non-integrated manufacturers while amplifying price spreads between captive-supply and contract-assembled units.
Pricing Analysis
Price spreads between Wi-Fi-enabled artisan models and basic automatic units widen as FCC certification costs and METI efficiency labeling requirements layer compliance premiums onto connected SKUs. Three-tier pricing structure across premium, standard, and economy levels separates algorithm-specialized Japanese units from design-led English-speaking brands and mass-market Chinese OEMs. Pricing pressure stems from multi-function air fryer substitution in entry-level segments. Home bakers in dense Asian metros show least price sensitivity for compact connected units, while North American big-box shoppers drive economy-tier commoditization.
Supply Chain Analysis
Shenzhen and Dongguan electronics manufacturing services anchor global control board and sensor module assembly for Panasonic, Midea, and Breville production networks. China dominates nichrome wire and ceramic heater output; Japan and Germany concentrate precision temperature sensor fabrication. Supply chain risk centers on single-source vulnerability for RoHS-compliant ceramic substrates under EU quota allocation. Distribution runs through direct-to-consumer e-commerce platforms in Australia and the United Kingdom, with kitchen specialty retailers retaining artisan-model positioning in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud recipe subscription revenue streams expand faster than hardware shipments, transforming smart bread maker economics from unit transactional to service-attach recurring models.
For Market Incumbents: Pre-empt multi-function appliance substitution by bundling extended fermentation algorithms with ingredient partnership programs. Panasonic and Zojirushi should deepen upstream control over sensor calibration to defend against Midea's cost-positioned connected units. Certification investment in EU F-Gas Regulation compliance creates switching costs for European distribution access. For New Entrants and Emerging Players: India's BIS certification pathways and underdeveloped connected appliance penetration in Maharashtra and Karnataka represent the most penetrable entry point for Wi-Fi-enabled compact designs. Direct-to-consumer channel origination bypasses entrenched retail slotting fees. Cloud recipe subscription bundling offsets hardware margin compression while building installed base lock-in. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified appliance conglomerates seeking to monetize non-core precision thermal control engineering teams. Five-to-ten-year viability hinges on firmware security certification capabilities and modular serviceable design architectures. Monitor right-to-repair legislative progression across EU member states and US statehouses as inflection indicator for service-revenue multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Recipe Subscription Launch | Recurring revenue from proprietary ingredient partnerships offsets hardware margin compression for Breville and Panasonic ecosystems. |
| EU F-Gas Compliance Redesign | Hydrocarbon thermal preservation subsystems enable continued CE marking access for German and French market penetration. |
| Direct-to-Consumer Channel Expansion | Owned e-commerce bypasses big-box distributor margins in Australia and United Kingdom premium SKU segments. |
| Modular Serviceable Architecture Investment | Replaceable heating element designs anticipate EU and US state-level right-to-repair mandate enforcement. |
| India BIS Certification First-Mover Positioning | Mumbai and Bangalore smart home adoption curves reward early connected appliance entrants with distribution lock-in. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across appliance brand managers, category buyers at kitchen specialty retailers, control board procurement leads, and aftermarket service heads. Primary interview findings triangulated against SEC 10-K filings, customs trade records for heating element and motor shipments, METI energy efficiency labeling databases, and EU F-Gas Regulation quota allocation disclosures. Bottom-up SKU volume aggregation and top-down macroeconomic calibration validated segment-level projections.
Calibration across the analysis window employed product type, feature integration depth, end-user intensity tier, capacity format, and regional regulatory cluster as segmentation dimensions. CAGRs derived from installed base replacement cycle modeling and connected feature attachment rate trajectory analysis. Forecast inputs incorporated smart home ecosystem penetration curves and RoHS compliance cost pass-through elasticity.
Practitioners should monitor FCC certification backlog duration and EU F-Gas refrigerant quota price volatility for early signals of launch timeline compression or input cost spikes. Quarterly review of cloud recipe subscription churn rates and right-to-repair legislative committee markup activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Electric Kebab Machine Market
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Food Irradiation Equipment Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Dehydrators Market
Food Processing Equipment
Bread Maker Market