
 Softgel Encapsulation Machine Market | 2026-2036
Softgel Encapsulation Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Softgel Encapsulation Machine Market Outlook
Qualified technician availability for rotary die softgel operations is collapsing across mature manufacturing hubs, forcing equipment vendors to embed self-diagnostic software and remote service architectures into new machine designs. Syntegon Technology GmbH leverages its Stuttgart engineering base to sustain integrated line solutions spanning encapsulation through coating and inspection. Romaco Group anchors Central European demand through its Karlsruhe facility, which specializes in containment-ready configurations for potent compound handling. Changsung competes aggressively on cost-optimized automatic machine platforms for mid-scale nutraceutical producers in Asia.
Softgel encapsulation machines form precision dosing systems that extrude molten gelatin ribbons around liquid or suspension fills using counter-rotating die rolls, typically operating at fill weights between 100 milligrams and 1,500 milligrams per capsule for pharmaceutical and nutraceutical applications. Automatic machines dominate capital expenditure flows among pharmaceutical manufacturers seeking continuous operation modes with output rates exceeding 100,000 capsules hourly. Laboratory machines represent the fastest-growing product category as contract development organizations scale micro-batch capabilities for early-phase clinical trials. Thermal technology occupies the largest installed base, though non-thermal platforms are gaining traction for heat-sensitive active pharmaceutical ingredients where gelatin shell integrity must be preserved below 40 degrees Celsius.
FDA cGMP guidelines and EMA Annex 15 qualification standards enforce rigorous installation, operational, and performance validation protocols that extend equipment procurement cycles but lock in vendor relationships for decade-long service horizons. ISO 9001 quality management and REACH-compliant lubricant specifications further constrain material selections and supplier qualification processes for European machine builders. Buyers must weigh total cost of ownership against throughput flexibility as batch sizes contract toward personalized medicine formats.
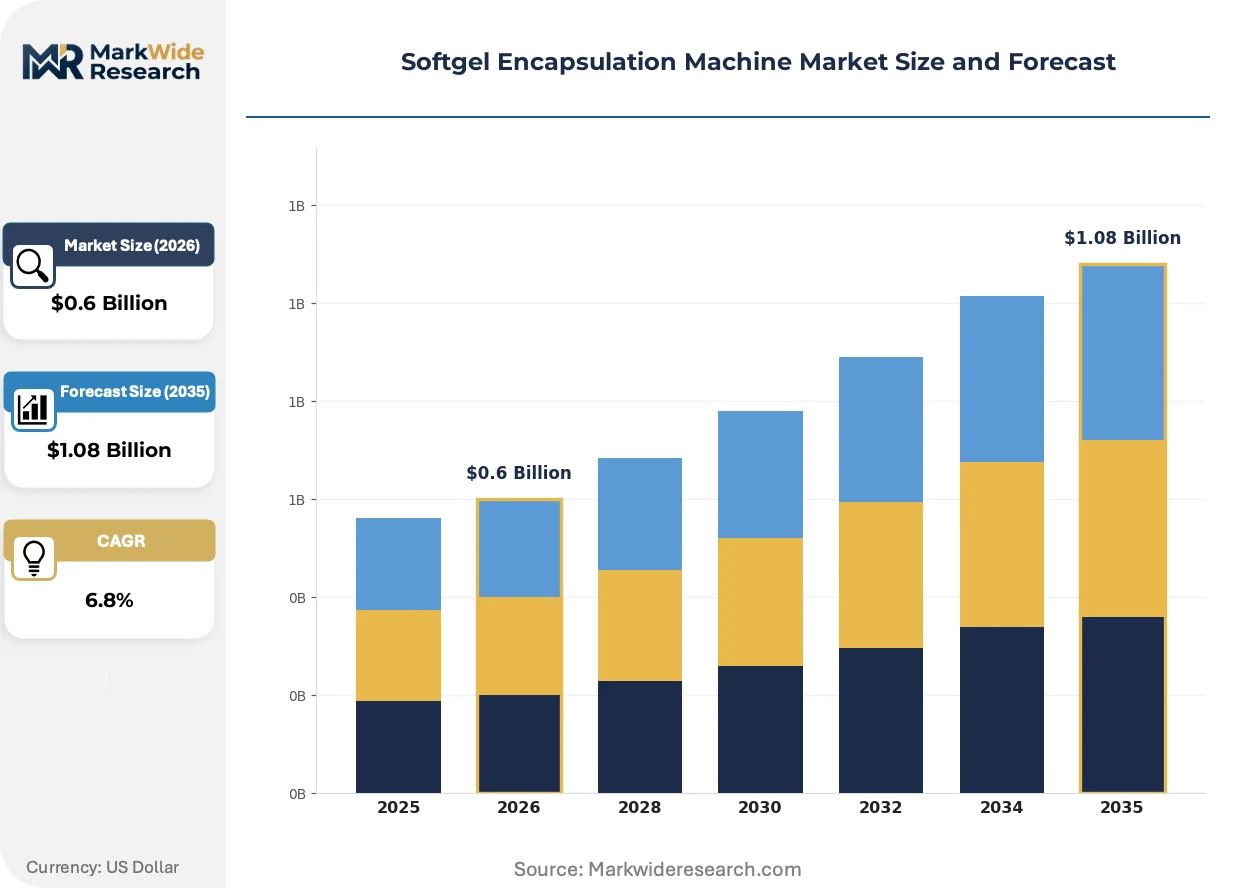
Market Dynamics
Pharmaceutical contract manufacturers are consolidating softgel production around continuous manufacturing platforms that compress batch cycle times from hours to minutes while satisfying FDA process analytical technology mandates for real-time release testing.
Growth Catalysts
- Oral dosage form preference:Patient adherence programs across chronic disease management favor softgels over tablets for swallowing ease, pulling demand from cardiology and neurology therapeutic areas.
- FDA cGMP modernization:The agency's 2023 guidance on advanced manufacturing technologies accelerates capital deployment toward integrated encapsulation-coating-inspection lines with embedded process analytical technology.
- Nutraceutical omega-3 expansion:Fish oil and algal DHA softgel volumes in Asia-Pacific manufacturing hubs are scaling automated encapsulation capacity to serve private-label contract manufacturing demand.
Market Restraints
- Gelatin raw material volatility:Bovine and porcine gelatin supply from South American rendering facilities faces price pressure from competing food and photographic industry offtake.
- Specialized technician scarcity:Rotary die maintenance and die roll refurbishment skills are concentrating among aging workforces in Stuttgart and Karlsruhe engineering clusters.
- Non-thermal platform validation burden:EMA Annex 15 qualification timelines for room-temperature encapsulation systems extend equipment acceptance periods by eight to fourteen months versus thermal alternatives.
Strategic Opportunities
- Cell-cultured gelatin substitution:Laboratory-derived collagen matrices from precision fermentation bypass religious dietary restrictions and zoonotic pathogen risks in Middle Eastern and Southeast Asian markets.
- Micro-batch clinical trial supply:Contract development organizations are commissioning laboratory-scale encapsulation systems for Phase I pharmacokinetic studies requiring fifty to five hundred unit batches.
- EU Green Deal machinery standards:REACH-compliant lubricant specifications and energy efficiency mandates are creating specification gaps that favor European machine builders with established environmental management certifications.
Industry Challenges
- Die roll refurbishment bottlenecks:Precision grinding of chrome-plated die cavities requires specialized CNC equipment that third-party service providers are retiring without replacement.
- Legacy DCS integration friction:Brownfield pharmaceutical facilities running Siemens or Rockwell automation stacks face protocol translation costs when connecting new encapsulation lines to existing manufacturing execution systems.
- Containment validation complexity:Potent compound handling configurations for hormone and cytotoxic APIs demand isolator integration that extends factory acceptance testing schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Softgel Encapsulation Machine Market |
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Machines, Automatic Machines, Semi-Automatic Machines, Laboratory Machines End User: Pharmaceutical Manufacturers, Nutraceutical Companies, Cosmetic Producers, Research Laboratories Application: Dietary Supplements, Pharmaceuticals, Cosmetics, Veterinary Products Technology: Thermal Technology, Non-Thermal Technology, Solvent-Based Technology, Others |
| Companies Covered | Romaco Group, Syntegon Technology GmbH, Bosch Packaging Technology, Changsung, Technophar, IMA Group, SaintyCo, Schaefer Technologies, Sejong Pharmatech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Softgel Encapsulation Machine Market Strategic Shifts
Equipment architectures are converging toward modular subsystems that permit rapid reconfiguration between batch and continuous modes without full line replacement, compressing capital deployment risk for multi-product facilities.
Micro-dosing pump technology is miniaturizing fill weight control precision from milligram to sub-milligram resolution, enabling softgel formats for high-potency low-dose oncology compounds. Early-phase biopharma sponsors in Boston and Basel are piloting these systems for targeted kinase inhibitors. The technology is miniaturizing the minimum viable batch size for commercial validation, allowing virtual pharmaceutical companies to retain manufacturing flexibility without committing to dedicated high-volume lines.
EMA's 2024 revision to Annex 15 computer system validation requirements is mandating audit trail integrity and electronic signature workflows that legacy encapsulation controllers cannot satisfy without controller replacement. European contract manufacturers are prioritizing equipment vendors with pre-validated software packages to compress qualification timelines. The regulation is accelerating obsolescence of fifteen to twenty-year-old installed bases that lack cybersecurity-hardened architectures.
After-sales service unbundling is fragmenting vendor-customer relationships as pharmaceutical procurement teams negotiate remote diagnostics subscriptions separately from spare parts agreements and field technician dispatch. German and Swiss equipment builders are responding with tiered service portfolios that separate software maintenance from mechanical support. The shift is most pronounced among mid-scale nutraceutical producers in India and Brazil seeking to decouple capital expenditure from ongoing operating cost commitments.
Softgel Encapsulation Machine Market Segmentation
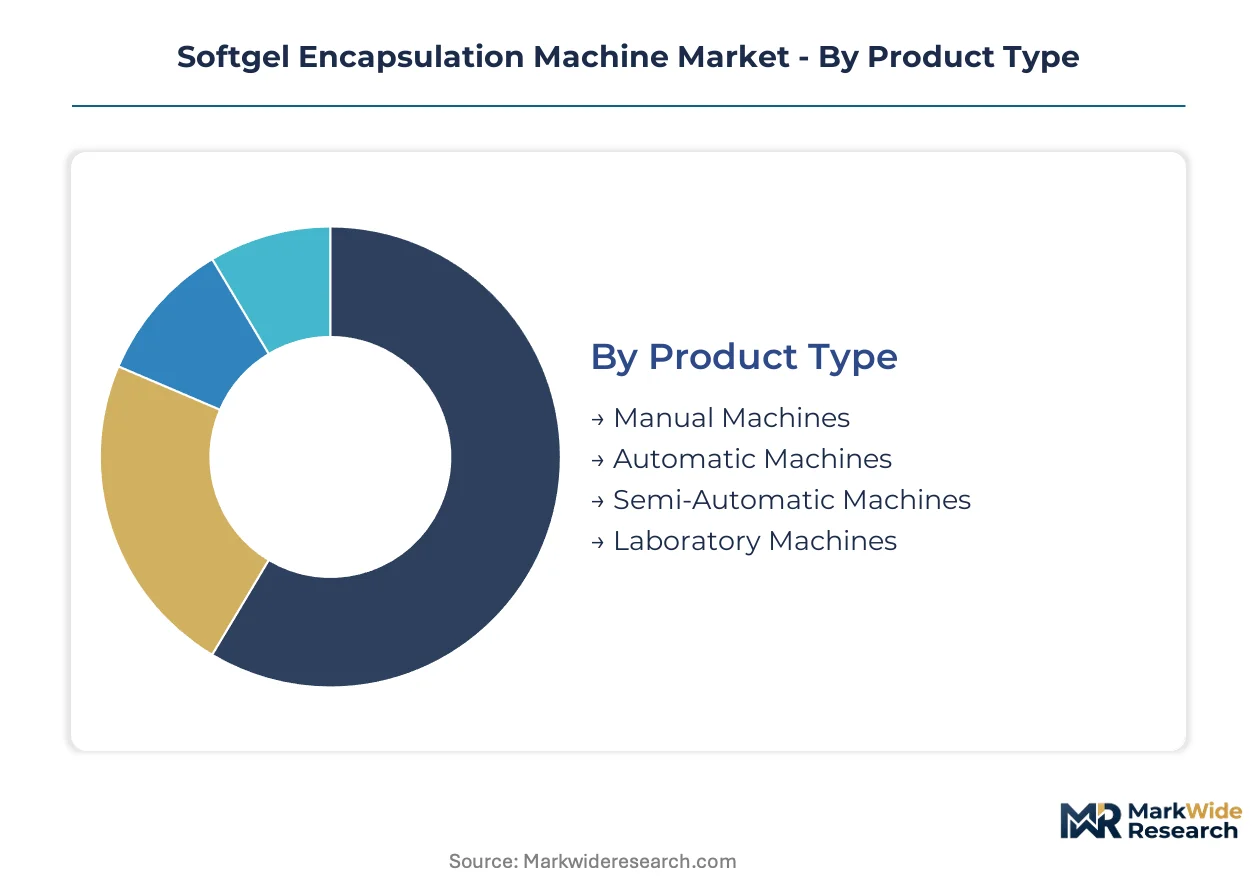
Softgel encapsulation machine procurement channels diverge sharply by operational scale and regulatory burden. Pharmaceutical contract manufacturers route capital expenditure through integrated line vendors, while nutraceutical mid-scale producers favor modular platforms with unbundled service contracts.
Product Type:
Channel strategy splits between continuous manufacturing platforms for high-volume pharmaceutical contracts and laboratory-scale systems serving development-stage biopharma sponsors.
- Automatic Machines:Continuous operation architectures deliver output rates exceeding 100,000 capsules hourly through counter-rotating die roll configurations. Pharmaceutical manufacturers in Germany and Switzerland deploy these for FDA cGMP-compliant commercial supply, with procurement cycles extending 18-24 months due to IQ/OQ/PQ validation protocols.
- Laboratory Machines:Micro-batch capabilities enable 50-500 unit production runs for Phase I pharmacokinetic studies. Contract development organizations in Boston and Basel are scaling these systems fastest as virtual pharmaceutical companies retain manufacturing flexibility without dedicated high-volume line commitments.
- Manual Machines:Entry-level platforms for artisanal nutraceutical producers and educational institutions with limited batch frequency requirements.
- Semi-Automatic Machines:Mid-scale configurations bridging batch flexibility with partial automation for regional contract manufacturers.
Automatic machines dominate installed base. Laboratory machines are where expansion concentrates.
End User:
Customer type determines specification intensity, with pharmaceutical buyers demanding containment-ready configurations and nutraceutical purchasers prioritizing throughput economics.
- Pharmaceutical Manufacturers:Containment-integrated encapsulation lines for hormone and cytotoxic APIs require isolator configurations that extend factory acceptance testing. EMA Annex 15 qualification standards and FDA cGMP modernization guidance lock these buyers into decade-long vendor relationships.
- Nutraceutical Companies:Omega-3 fish oil and algal DHA softgel volumes are scaling automated capacity across Asia-Pacific private-label contract manufacturing hubs. These buyers negotiate remote diagnostics subscriptions separately from spare parts agreements to decouple capital expenditure from operating commitments.
- Cosmetic Producers:Beauty supplement softgel formats drive demand for visually differentiated shell aesthetics and fragrance encapsulation.
- Research Laboratories:Academic and government facilities utilize scaled-down systems for formulation feasibility studies and training applications.
Pharmaceutical manufacturers command specification leadership. Nutraceutical companies are climbing the fastest as omega-3 volumes expand.
Application:
Application focus determines fill chemistry compatibility and shell formulation requirements, with dietary supplements and pharmaceuticals representing divergent validation burdens.
- Pharmaceuticals:High-potency low-dose oncology compounds require micro-dosing pump technology with sub-milligram resolution. Early-phase biopharma sponsors pilot these for targeted kinase inhibitors, compressing minimum viable batch sizes for commercial validation.
- Dietary Supplements:Fish oil and algal DHA softgels anchor volume demand in Asia-Pacific manufacturing hubs. Private-label contract manufacturing growth pulls capacity expansion toward continuous platforms with real-time release testing capabilities.
- Cosmetics:Beauty-from-within formulations prioritize shell clarity and aesthetic differentiation over bioavailability metrics.
- Veterinary Products:Palatability-enhanced softgels for companion animal supplements operate with relaxed regulatory validation compared to human pharmaceutical standards.
Dietary supplements hold volume leadership. Pharmaceuticals show steepest expansion trajectory as micro-dosing technology matures.
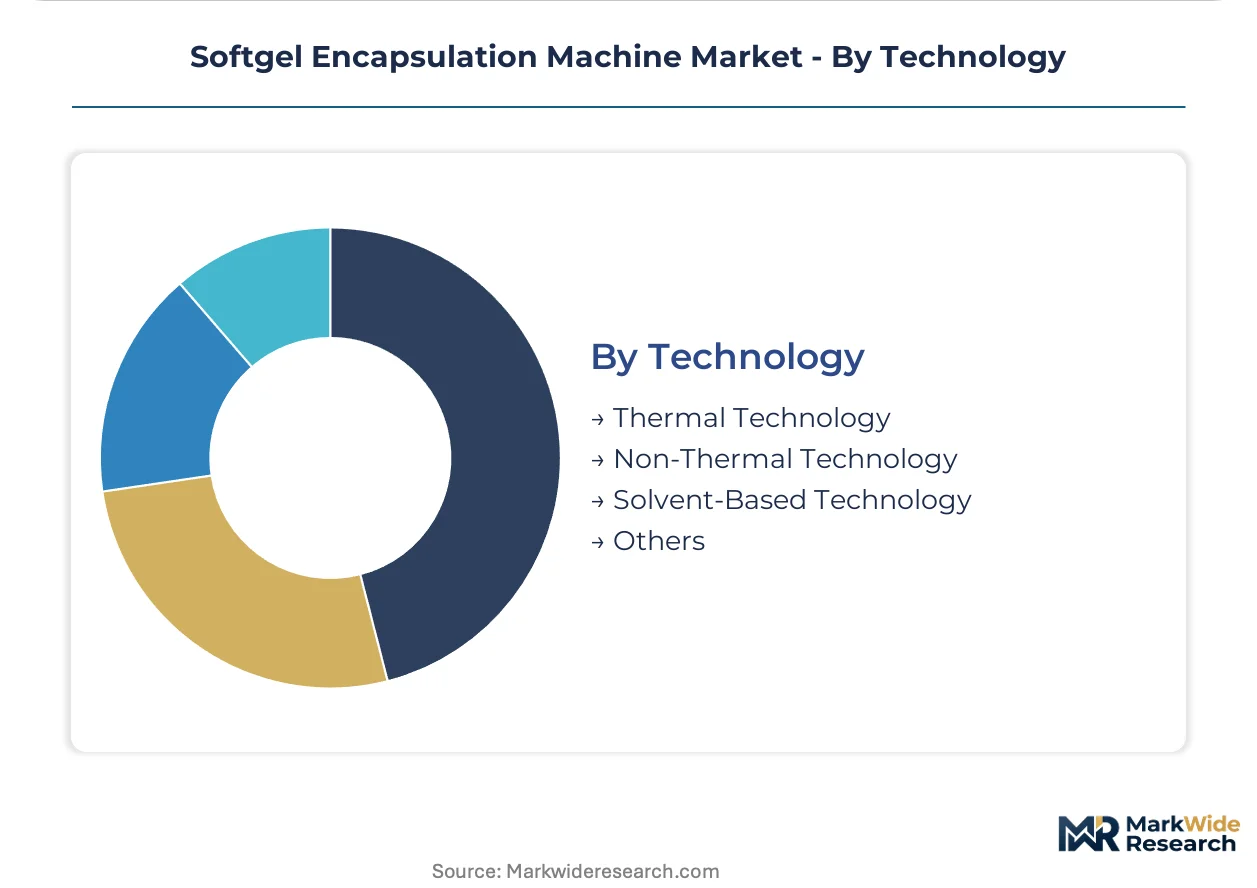
Technology:
Technology selection balances gelatin shell integrity against active pharmaceutical ingredient thermal sensitivity, with regulatory validation timelines varying dramatically by platform.
- Thermal Technology:Molten gelatin ribbon extrusion around liquid fills occupies the largest installed base through proven reliability. Standard operating temperatures between 35-45 degrees Celsius suit stable active pharmaceutical ingredients with established degradation profiles.
- Non-Thermal Technology:Room-temperature encapsulation preserves gelatin integrity below 40 degrees Celsius for heat-sensitive APIs. EMA Annex 15 qualification timelines extend equipment acceptance periods by eight to fourteen months versus thermal alternatives, constraining adoption despite technical advantages.
- Solvent-Based Technology:Alternative shell formation chemistry for specialized fill matrices requiring non-aqueous processing environments.
- Others:Emerging platform architectures including precision fermentation-derived collagen matrices bypassing conventional gelatin supply chains.
Thermal technology dominates installed base. Non-thermal platforms are gaining share fastest as heat-sensitive biologic formulations multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP modernization and EMA Annex 15 qualification standards anchor equipment procurement cycles across the dominant German and Swiss pharmaceutical manufacturing clusters, while Asia-Pacific nutraceutical expansion and North American biopharma outsourcing reshape regional demand patterns.
Germany
Pharmaceutical contract manufacturers in Stuttgart and Karlsruhe drive demand for fully automated continuous manufacturing platforms with embedded process analytical technology. EMA Annex 15 validation requirements extend equipment acceptance periods but lock buyers into decade-long vendor relationships. The Baden-Württemberg precision engineering corridor hosts Syntegon Technology GmbH and Romaco Group facilities specializing in containment-ready configurations for potent compound handling.
Switzerland
Swissmedic regulatory standards enforce rigorous installation and operational qualification protocols that favor European machine builders with established quality management certifications. The Basel biopharma cluster generates concentrated demand for laboratory-scale encapsulation systems serving early-phase clinical trials. Contract development organizations in the region are commissioning micro-batch equipment for Phase I pharmacokinetic studies requiring fifty to five hundred unit batches.
United States
FDA's 2023 guidance on advanced manufacturing technologies accelerates capital deployment toward integrated encapsulation-coating-inspection lines in Boston and New Jersey pharmaceutical corridors. Virtual pharmaceutical companies retain manufacturing flexibility without committing to dedicated high-volume lines, pulling demand for modular laboratory machines. The agency's process analytical technology mandates for real-time release testing compress batch cycle times from hours to minutes.
China
NMPA regulatory harmonization with international standards drives equipment upgrades among domestic pharmaceutical manufacturers seeking export certification. The Yangtze River Delta nutraceutical manufacturing hub scales automated encapsulation capacity to serve private-label contract manufacturing demand for omega-3 fish oil and algal DHA softgels. Mid-scale producers in the region negotiate remote diagnostics subscriptions separately from spare parts agreements to decouple capital expenditure from operating commitments.
India
CDSCO quality enforcement and FSSAI dietary supplement regulations push equipment procurement toward ISO 9001-certified platforms with REACH-compliant lubricant specifications. Maharashtra and Gujarat pharmaceutical clusters concentrate demand for cost-optimized automatic machines serving regional contract manufacturing growth. Private-label nutraceutical exporters in the region prioritize throughput economics over containment-ready configurations required for potent pharmaceutical compounds.
Softgel Encapsulation Machine Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through decade-long service relationships locked in by regulatory validation requirements. The middle tier fragments across geography-based engineering clusters and application-specific specializations. Three strategic archetypes dominate: German-Swiss precision engineering houses with full-line integration capabilities, Asian cost-optimized fabricators serving mid-scale nutraceutical demand, and Korean-Japanese specialists in containment and micro-dosing technologies. Competitive moves concentrate on unbundling after-sales service portfolios and embedding self-diagnostic software to address collapsing qualified technician availability.
Among German engineering houses, Syntegon Technology GmbH and Romaco Group exemplify the integrated-line archetype spanning encapsulation through coating and inspection. Changsung occupies a position within the cost-optimized tier serving Asia-Pacific nutraceutical volume expansion. These three anchors illustrate how vendor strategies diverge between regulatory-intensive pharmaceutical markets and throughput-driven dietary supplement manufacturing.
| Leading Market Players |
|---|
| Romaco Group |
| Syntegon Technology GmbH |
| Bosch Packaging Technology |
| Changsung |
| Technophar |
| IMA Group |
| SaintyCo |
| Schaefer Technologies |
| Sejong Pharmatech |
| Others |
Value Chain & Pricing Dynamics
Rotary die refurbishment capacity concentration in Stuttgart and Karlsruhe engineering clusters anchors price floors for precision maintenance services, while gelatin raw material volatility from South American rendering facilities compresses margin buffers across equipment tiers. Pharmaceutical contract manufacturers absorb premium pricing for containment-ready configurations, whereas nutraceutical mid-scale producers in Asia-Pacific manufacturing hubs negotiate unbundled service contracts to isolate capital expenditure from recurring operating commitments.
Pricing Analysis
German-Swiss engineering corridors command 40-60% premiums over Asian cost-optimized fabricators for equivalent throughput specifications, with FDA cGMP and EMA Annex 15 certification tiers creating stratified pricing bands. Price differentiation centers on validation documentation depth and embedded process analytical technology capabilities. Cost compression in mid-scale automatic machine tiers intensifies as Changsung and domestic Chinese vendors compete for Asia-Pacific nutraceutical contract manufacturing demand. Nutraceutical private-label producers exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize total cost of ownership over unit capital expenditure.
Supply Chain Analysis
Container availability constraints on Hamburg-Singapore trade lanes elevate inbound logistics costs for precision-engineered components sourced from Baden-Württemberg manufacturing clusters. Die roll manufacturing concentrates in Germany, South Korea, and Japan, with chrome-plated cavity grinding equipment drawing from specialized CNC suppliers in Switzerland and Italy. Single-source vulnerability in precision fermentation-derived collagen matrices threatens cell-cultured gelatin substitution timelines. Distribution runs through integrated line vendors for pharmaceutical contract manufacturers and modular platform distributors for mid-scale nutraceutical producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hard capsule and tablet compression technologies pose persistent substitution threats as oral dosage form preferences fragment across patient adherence programs, forcing softgel equipment vendors to defend bioavailability differentiation and swallowing-ease positioning.
For Market Incumbents: Shield installed base relationships by embedding self-diagnostic software architectures that address collapsing qualified technician availability in mature manufacturing hubs. Capture backward integration into precision die roll refurbishment capabilities before third-party CNC service providers complete equipment retirement. Defend against Korean-Japanese micro-dosing specialists by accelerating laboratory-scale platform development for Boston and Basel biopharma clusters. For New Entrants and Emerging Players: Lead with unbundled remote diagnostics subscriptions targeting India and Brazil nutraceutical producers seeking to decouple capital expenditure from operating commitments. Penetrate the micro-batch clinical trial supply segment serving virtual pharmaceutical companies in North American outsourcing corridors. Position through precision fermentation-derived collagen matrix partnerships that bypass conventional gelatin supply chain volatility for Middle Eastern and Southeast Asian markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors European machine builders with established environmental management certifications capturing EU Green Deal machinery standard specification gaps. Long-term viability hinges on software-enabled service revenue streams overtaking hardware margin dependence. Watch for EMA Annex 15 computer system validation revision compliance rates as inflection indicator for legacy installed base replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Die Roll Refurbishment Integration | Captures scarce CNC grinding capacity before third-party service provider retirement concentrates. |
| Self-Diagnostic Software Architecture Deployment | Addresses qualified technician scarcity collapsing across Stuttgart and Karlsruhe engineering clusters. |
| Cell-Cultured Gelatin Partnership Formation | Bypasses South American rendering facility volatility and religious dietary restriction market barriers. |
| Micro-Dosing Pump Technology Miniaturization | Enables sub-milligram resolution for high-potency oncology compounds in Boston and Basel trials. |
| Unbundled Service Portfolio Tiering | Matches India and Brazil nutraceutical procurement teams decoupling capex from operating commitments. |
Study Parameters
A standing panel of pharmaceutical manufacturing executives, contract development organization procurement leads, precision engineering maintenance directors, and nutraceutical private-label operations managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA cGMP guidance documents, EMA Annex 15 qualification standards, ISO 9001 certification registries, and REACH-compliant lubricant specification databases. Bottom-up equipment shipment tracking and top-down pharmaceutical capital expenditure surveys were triangulated to anchor market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type tier, end-user regulatory burden intensity, application fill chemistry compatibility, and technology thermal sensitivity classification. CAGRs were derived from installed base replacement cycles and greenfield capacity expansion announcements. Forecast inputs incorporated EMA computer system validation revision compliance timelines and FDA process analytical technology mandate implementation rates.
Underlying assumptions cover sustained pharmaceutical outsourcing growth and gelatin supply chain stability, with deviation risk concentrated in precision fermentation scale-up delays and qualified technician training pipeline failures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Automatic Evisceration System Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Beverage Processing Equipment Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Canada Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
Dough Processing System Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market