
 North America Ginger Processing Market | 2026-2036
North America Ginger Processing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ginger Processing Market Intelligence
Multi-source agricultural procurement is recalibrating how processors secure raw ginger supply across North America. Spice World Inc. leverages its established procurement networks across multiple growing regions to reduce single-source dependency. McCormick and Co. Inc. anchors its processing scale through backward integration into quality-controlled sourcing partnerships. Frontier Co-op differentiates via certified organic and fair-trade supply chains that command premium positioning in specialty retail channels.
North America Ginger Processing encompasses the cleaning, drying, grinding, extraction, and packaging of Zingiber officinale rhizomes into standardized ingredient formats for industrial and consumer applications, with oil extraction typically yielding 2-4% essential oil by dry weight through steam distillation. The primary commercial purpose centers on delivering consistent pungency profiles, measured by gingerol and shogaol content, to food and beverage manufacturers requiring batch-to-batch uniformity. Ginger oil and extract segments capture disproportionate margin pools due to concentrated bioactive compounds and pharmaceutical-grade certification requirements. The beverage industry end-use channel exhibits the fastest structural expansion, driven by kombucha, functional soda, and craft cocktail formulation trends. Dried ginger maintains mature volume leadership in baking and spice blend applications where cost efficiency outweighs freshness premiums.
The FDA enforces Current Good Manufacturing Practice regulations and Food Safety Modernization Act traceability mandates that elevate processing facility compliance costs while restricting informal supplier entry. USDA organic certification and Non-GMO Project verification function as de facto market access requirements for premium distribution channels across the United States and Canada. Stakeholders must monitor evolving EPA wastewater discharge standards for extraction facilities and anticipate how state-level hemp-cannabis regulatory frameworks might influence ginger bioactive research funding and competitive ingredient positioning.
Market Dynamics
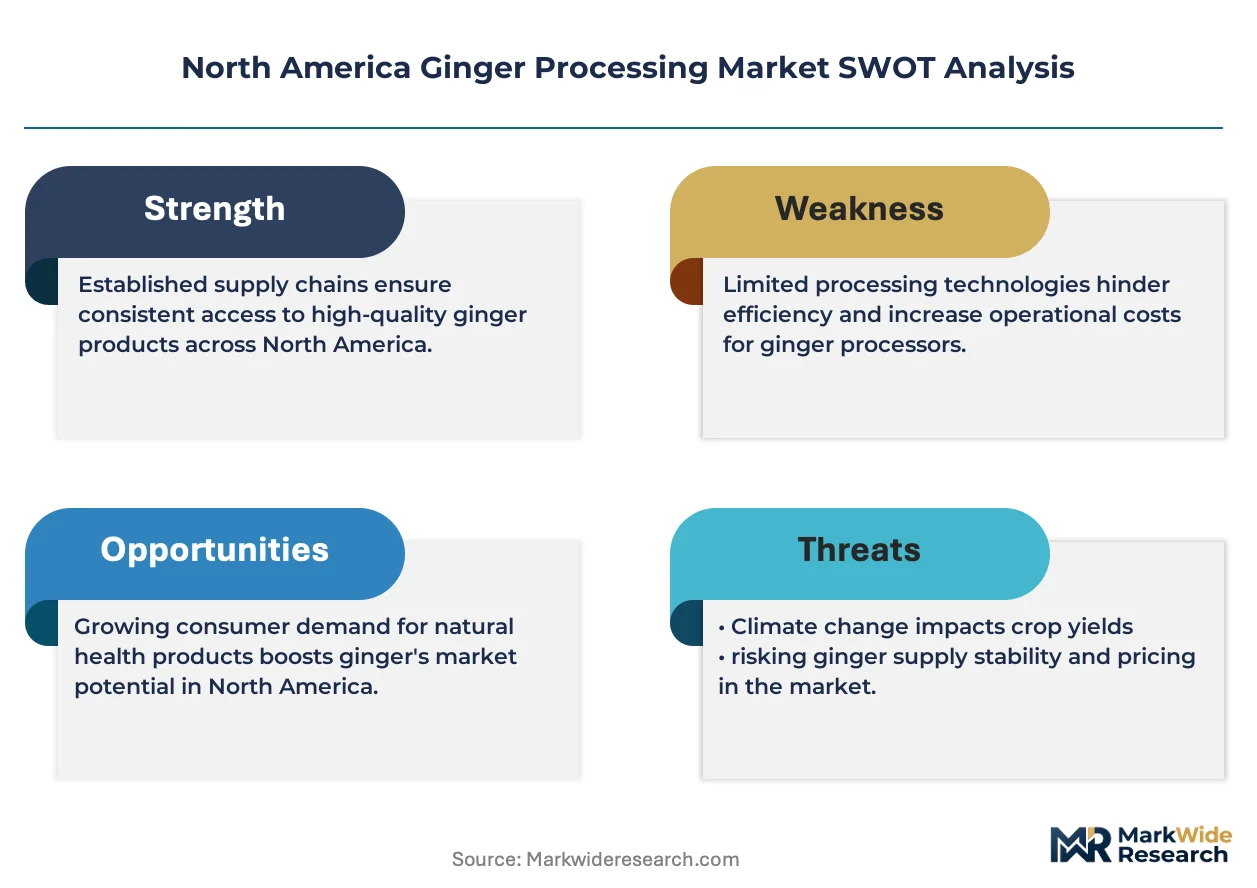
Supercritical CO2 extraction technology is compressing processing timelines while elevating bioactive compound recovery rates, forcing traditional steam distillation facilities toward capital-intensive upgrades or specialty niche positioning.
Growth Catalysts
- FSMA Section 204 Traceability Mandates:FDA enforcement is accelerating facility modernization investments as processors retrofit lines for lot-level digital tracking to maintain market access.
- Functional Beverage Formulation:Kombucha and craft cocktail manufacturers are pulling concentrated ginger extract volumes as they standardize pungency profiles across batch production.
- California Central Valley Cluster:Processing infrastructure concentration near Fresno and Bakersfield is reducing inbound logistics costs for West Coast distribution networks.
Market Restraints
- Peruvian and Chinese Import Dependency:Raw ginger supply concentrates in coastal growing regions vulnerable to El Niño precipitation disruptions and port congestion.
- Organic Certification Cost Barrier:USDA three-year transition requirements and annual audit expenses block small-scale processors from premium channel access.
- Steam Distillation Yield Ceiling:Conventional oil extraction caps at 4% dry weight recovery, creating margin pressure against supercritical CO2 competitors achieving 6-8% yields.
Strategic Opportunities
- Florida Organic Ginger Cultivation:Emerging acreage in Immokalee and Palmetto regions offers domestic certified-organic feedstock reducing import exposure.
- Pharmaceutical-Grade Certification:USP and NSF standards unlock contract manufacturing for dietary supplement brands seeking bioactive consistency guarantees.
- Direct-to-Processor Sourcing Platforms:Digital procurement marketplaces are disintermediating traditional spice brokers for mid-size beverage manufacturers.
Industry Challenges
- Extraction Engineer Talent Scarcity:Supercritical CO2 system operation requires specialized training unavailable through standard food technology programs.
- Legacy Drying Equipment Retrofit Complexity:Convection oven installations from prior decades resist integration with automated moisture monitoring and HACCP documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ginger Processing Market |
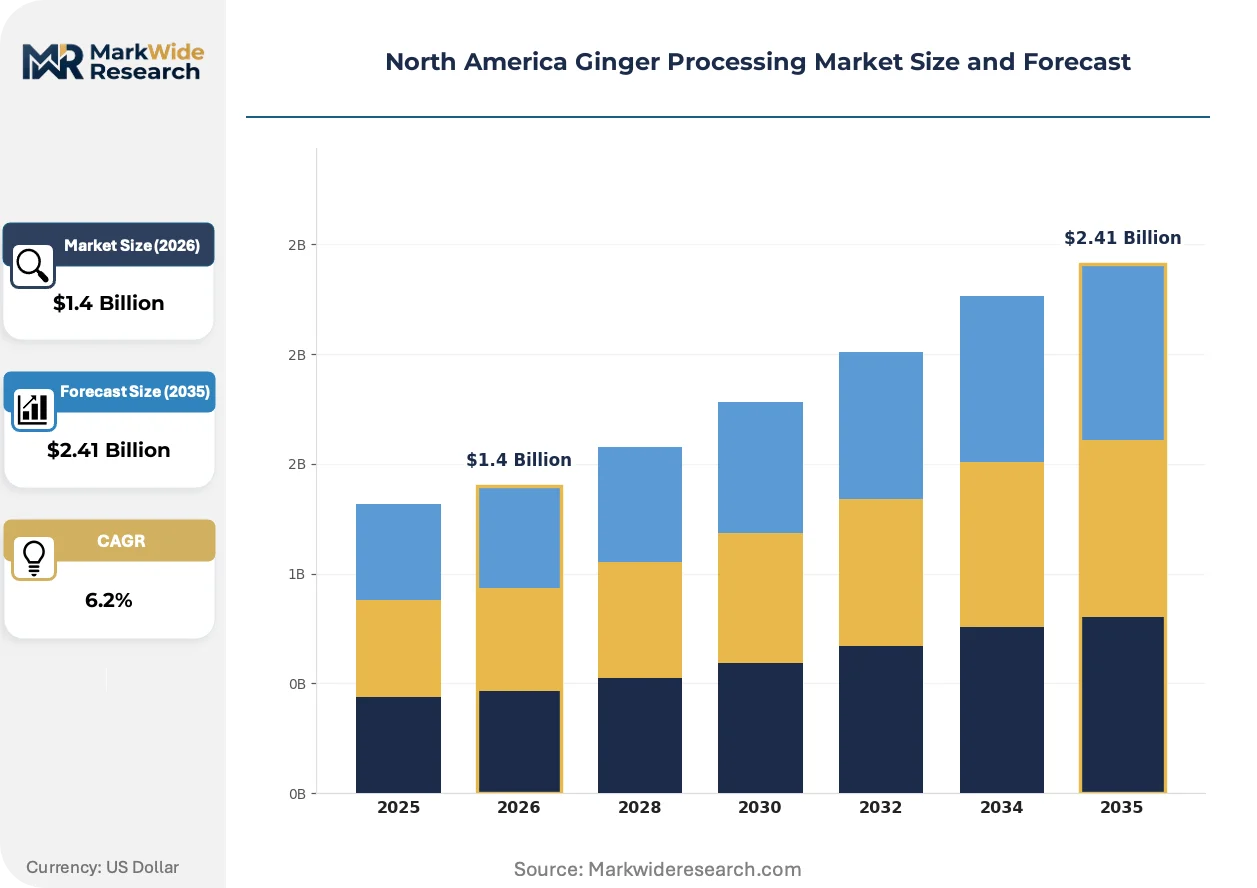
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Ginger, Dried Ginger, Ginger Powder, Ginger Oil End User: Food Industry, Beverage Industry, Pharmaceutical Industry, Cosmetic Industry Form: Whole, Sliced, Ground, Extract Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Frontier Co-op, Buderim Ginger, The Ginger People, Vera Herbals LLC, Olam Group Ltd., Spice World Inc., McCormick and Co. Inc., Monterey Bay Herb Co., Fisherville Finest, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ginger Processing Market Strategic Shifts & Innovations
Processing technology convergence with pharmaceutical manufacturing standards is elevating capital requirements while compressing batch-to-batch variability tolerance. Equipment suppliers are embedding inline spectroscopy for real-time gingerol monitoring.
Supercritical CO2 extraction is electrifying ginger oil recovery economics by eliminating thermal degradation of heat-sensitive shogaol compounds. Premium extract manufacturers in California and Florida are adopting these systems to supply pharmaceutical-grade certification demand. The technology is compressing traditional steam distillation into commodity spice oil production while reserving high-potency extracts for functional ingredient premiums.
FDA's updated Food Safety Modernization Act enforcement is mandating electronic traceability records for high-risk foods including ginger by January 2026. Processing facilities must implement lot tracking from raw receipt through packaged shipment. Smaller operators in Mexico and Central American supply zones face exclusion from US-bound supply chains absent compliance infrastructure investment.
Beverage manufacturer procurement is consolidating around long-term offtake agreements with certified processors capable of standardized pungency specifications. Kombucha brands are bypassing traditional spice distributors to contract directly with extraction specialists. This disintermediation concentrates volume with processors owning captive organic supply or pharmaceutical-grade certification, visible across California's central valley processing cluster.
North America Ginger Processing Market Segmentation
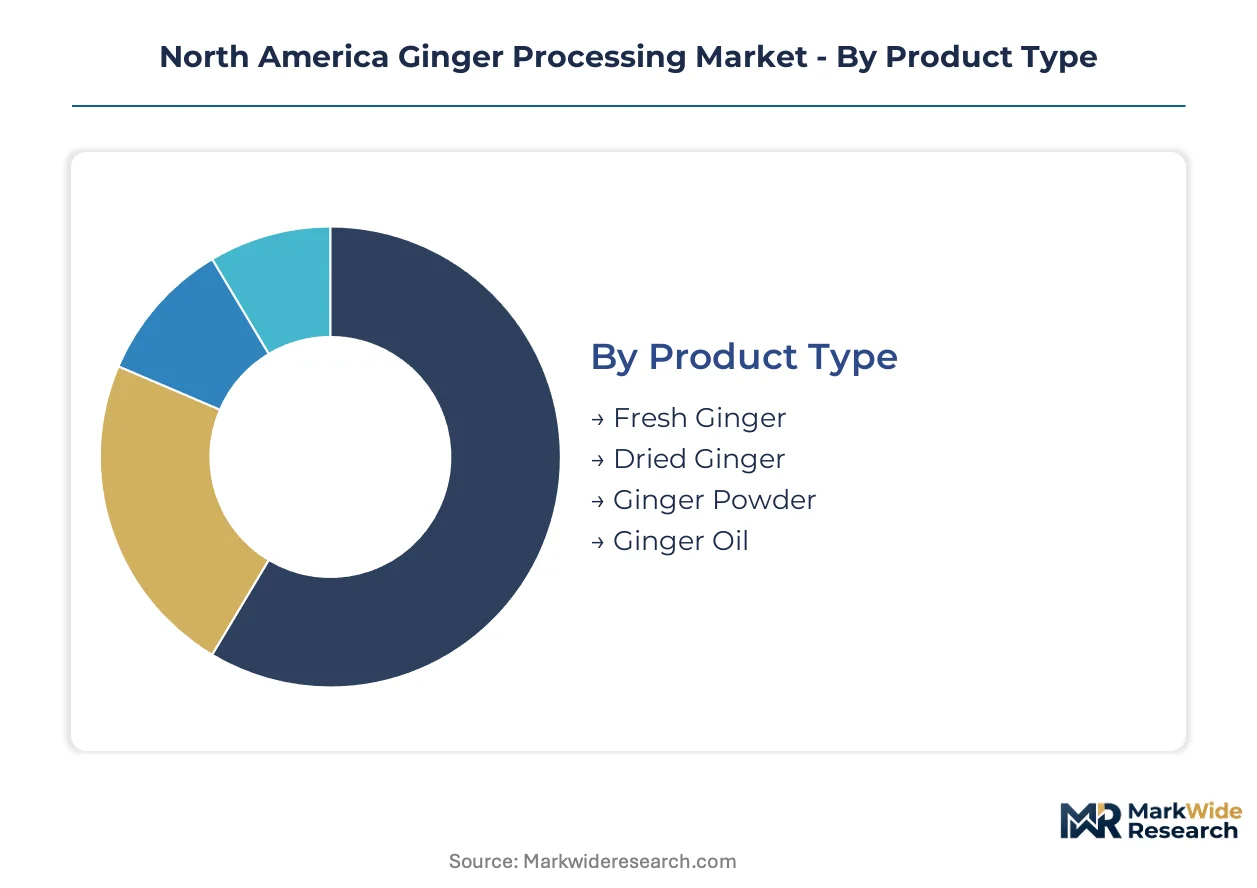
Segmentation in North American ginger processing reveals how extraction technology upgrades and certification requirements are reshaping procurement patterns across product formats. Processors must align capital deployment with the specific pungency consistency and traceability demands of each end-use channel.
Product Type:
Equipment replacement cycles vary dramatically across product categories, with oil extraction systems requiring the most frequent capital reinvestment to maintain competitive yields.
- Ginger Oil:Supercritical CO2 extraction yields 6-8% bioactive recovery versus 2-4% for steam distillation, commanding pharmaceutical-grade premiums in California's central valley processing cluster where dietary supplement manufacturers concentrate procurement.
- Ginger Powder:Standardized particle size distributions (80-200 mesh) serve industrial baking and spice blend manufacturers requiring batch-to-batch gingerol consistency; FDA FSMA traceability mandates are accelerating automated grinding line upgrades.
- Fresh Ginger:Minimal processing preserves volatile compound profiles for foodservice distributors and ethnic grocery channels in Florida's emerging organic operations.
- Dried Ginger:Convection and solar drying methods dominate mature applications where cost efficiency outweighs freshness premiums in conventional retail distribution.
Volume placements concentrate in Dried Ginger; the faster expansion belongs to Ginger Oil.
End User:
Cost tier differentiation separates commodity spice sales from certified organic and pharmaceutical-grade contract manufacturing.
- Beverage Industry:Kombucha, functional soda, and craft cocktail formulators pull concentrated extracts requiring standardized pungency profiles; long-term offtake agreements are consolidating procurement around certified processors in California's central valley cluster.
- Pharmaceutical Industry:USP and NSF certification requirements for dietary supplement ingredients impose batch testing protocols that exclude smaller processors lacking analytical laboratory infrastructure.
- Food Industry:Baking, sauce, and spice blend manufacturers prioritize cost-efficient dried and powdered formats with moderate gingerol specifications.
- Cosmetic Industry:Essential oil applications in personal care formulations demand preservative-free extraction methods and organic certification for premium positioning.
Food Industry maintains volume leadership; Beverage Industry climbs the fastest as functional formulation trends accelerate.
Form:
Application requirements dictate form selection, with extraction and grinding technologies determining feasible output specifications.
- Extract:Liquid and powdered concentrates deliver precise bioactive dosing for beverage and pharmaceutical applications; supercritical CO2 systems in Florida and California facilities are displacing traditional solvent extraction.
- Ground:Particle size standardization enables uniform dispersion in baking mixes and seasoning blends; automated milling lines integrate inline spectroscopy for real-time quality verification.
- Whole:Minimal processing preserves rhizome integrity for foodservice peeling and grating operations in ethnic cuisine channels.
- Sliced:Dehydrated formats serve tea blending and decorative garnish applications with intermediate processing intensity.
Ground form dominates current volume; Extract gains share fastest on pharmaceutical and functional beverage demand.
Distribution Channel:
Customer type and order scale determine channel selection, with procurement digitization reshaping mid-size manufacturer access.
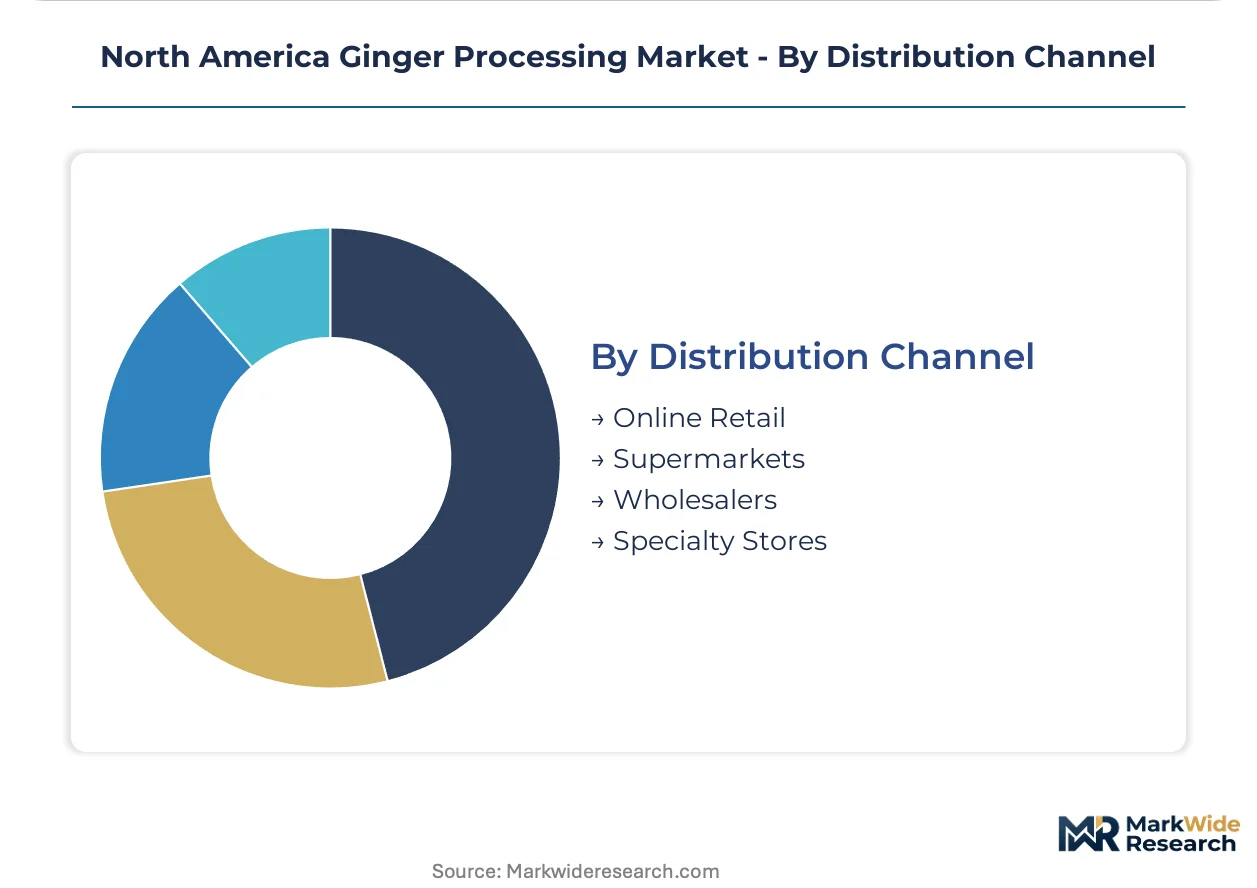
- Wholesalers:Traditional spice brokers consolidate fragmented demand from small and mid-size food manufacturers, though direct-to-processor digital platforms are eroding their intermediation role.
- Supermarkets:Private label and branded retail spice sales require packaging compliance with FDA nutrition labeling and state-level organic certification display regulations.
- Online Retail:Direct-to-consumer channels for specialty and organic formats are expanding fastest, particularly for premium extracts and small-batch dried products.
- Specialty Stores:Ethnic grocery and natural food retailers prioritize certified organic and fair-trade sourcing with transparent supply chain documentation.
Wholesalers retain volume concentration; Online Retail shows steepest expansion trajectory on procurement platform digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peruvian and Chinese coastal growing regions anchor raw ginger supply into North American processing facilities, with import dependency shaping regional distribution patterns across the continent.
United States
Beverage manufacturers in California and Florida pull concentrated extract volumes for kombucha and functional soda formulation. FDA FSMA Section 204 traceability mandates require lot-level digital tracking infrastructure by January 2026. California's Central Valley processing cluster near Fresno and Bakersfield concentrates supercritical CO2 extraction capacity serving West Coast distribution networks.
Canada
Health Canada regulations govern natural health product licensing for ginger extract dietary supplements entering retail pharmacy channels. USDA organic certification and Non-GMO Project verification function as de facto requirements for premium natural food distribution across Ontario and British Columbia. Toronto and Vancouver metropolitan areas concentrate import warehousing and re-export logistics for Asian feedstock.
Mexico
Smaller processing operators in Veracruz and Chiapas supply raw material preparation services for US-bound shipments. The country's national food safety regulator enforces HACCP documentation alignment with FDA import requirements. Port congestion at Lázaro Cárdenas and Manzanillo creates intermittent supply chain friction for Pacific Coast processors.
North America Ginger Processing Market Key Industry Players
Backward integration into quality-controlled sourcing partnerships dominates the current landscape as processors secure supply chain resilience against import volatility. The vendor base spans multinational spice conglomerates, regional organic specialists, and commodity brokers with varying certification capabilities. Three archetypes define competitive positioning: scale-driven extract manufacturers, certified organic specialists, and diversified agricultural traders. M&A activity and pharmaceutical-grade certification acquisition represent the primary competitive vectors for margin expansion.
Among established North American processors, Spice World Inc., McCormick and Co. Inc., and Frontier Co-op occupy distinct tier positions. Spice World exemplifies the procurement-network archetype through multi-source agricultural sourcing. McCormick represents scale-driven backward integration into controlled supply partnerships. Frontier Co-op anchors the certified organic specialist tier with fair-trade supply chain positioning. These three entities collectively illustrate how certification depth and sourcing control separate premium-channel access from commodity competition.
| Leading Market Players |
|---|
| Frontier Co-op |
| Buderim Ginger |
| The Ginger People |
| Vera Herbals LLC |
| Olam Group Ltd. |
| Spice World Inc. |
| McCormick and Co. Inc. |
| Monterey Bay Herb Co. |
| Fisherville Finest |
| Others |
Cost & Logistics Intelligence
Supercritical CO2 extraction engineer scarcity in California's Central Valley and Florida's emerging organic zones widens labor-cost spreads between pharmaceutical-grade certified processors and commodity steam-distillation operators, compressing margin structures at the economy tier while premium extract pricing holds firm.
Pricing Analysis
Warranty and analytical certification bundling separates pharmaceutical-grade USP/NSF verified extracts from unbundled commodity spice oils. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and extraction technology: supercritical CO2 systems command premium positioning, steam-distilled oils occupy mid-tier functional beverage supply, and conventional dried ginger serves cost-sensitive baking applications. Pricing pressure stems from El Niño-driven raw material volatility in Peruvian and Chinese coastal growing regions. Beverage manufacturers exhibit lowest price sensitivity due to formulation standardization requirements, while conventional food manufacturers resist premium migration.
Supply Chain Analysis
USDA organic certification and FDA FSMA traceability mandates gate market access, excluding smaller Mexican and Central American processors lacking compliance infrastructure. Raw ginger supply concentrates in Peru, China, and India, with coastal growing regions vulnerable to precipitation disruption and port congestion. Processors draw from rhizome feedstock, extraction solvents, and analytical testing services. Single-source dependency on Peruvian and Chinese imports creates structural vulnerability. Distribution runs through California's Central Valley processing cluster for West Coast beverage manufacturers, with re-export logistics anchoring Toronto and Vancouver for Canadian premium channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's Food Safety Modernization Act Section 204 traceability mandates erect a cost-of-compliance barrier that entrenches incumbent processors with existing digital infrastructure while excluding undercapitalized competitors from US-bound supply chains.
For Market Incumbents: Hedge against El Niño-driven supply disruption by anchoring backward integration into Florida's emerging organic ginger cultivation in Immokalee and Palmetto regions. Fortify market position through pharmaceutical-grade USP certification acquisition to capture dietary supplement contract manufacturing volumes that exclude uncertified rivals. For New Entrants and Emerging Players: Enter via direct-to-processor digital sourcing platforms that disintermediate traditional spice brokers for mid-size kombucha and functional soda manufacturers. Target Florida's organic ginger processing gap with certified extraction capacity serving beverage formulators seeking domestic supply chain resilience. For Investors and Strategic Acquirers: Re-rating potential sits with supercritical CO2-equipped processors given pharmaceutical-grade certification demand acceleration. Long-term viability favors facilities with captive organic supply or quality-controlled sourcing partnerships. Watch for FDA enforcement action against non-compliant Mexican processors as an inflection signal for market share consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | California processors deploying these systems capture pharmaceutical-grade premiums from dietary supplement manufacturers. |
| Backward Integration into Organic Cultivation | Florida acreage development reduces import exposure for certified processors serving premium beverage channels. |
| Pharmaceutical-Grade Certification Acquisition | USP and NSF standards unlock contract manufacturing volumes that exclude smaller analytical-laboratory-deficient competitors. |
| Digital Procurement Platform Development | Direct-to-processor marketplaces disintermediate traditional spice brokers for mid-size kombucha and functional soda manufacturers. |
| FSMA Traceability Infrastructure Investment | Lot-level digital tracking systems maintain US market access as FDA enforcement accelerates facility modernization requirements. |
Research Approach
Trade publications, FDA enforcement documentation, and agricultural commodity databases formed the secondary backbone for this analysis. Primary interviews with extraction facility engineers, beverage manufacturer procurement directors, organic certification auditors, and spice distributor logistics managers validated supply chain dynamics and pricing structures. Bottom-up and top-down triangulation cross-referenced facility capacity estimates against end-use demand segmentation.
Bottom-up modeling built from individual processor capacity, extraction technology yields, and certification status across California, Florida, and Canadian facilities. Top-down verification anchored against beverage industry formulation trends and pharmaceutical dietary supplement production volumes. Segmentation dimensions spanned product type, end-use channel, extraction technology tier, and geographic processing cluster. CAGRs derived from trend extrapolation of functional beverage formulation adoption and regulatory compliance investment cycles.
Revisions become necessary when El Niño precipitation patterns disrupt Peruvian and Chinese coastal harvests or when FDA accelerates FSMA enforcement timelines beyond current facility retrofit capacities. Forecasts reflect assumptions about certification penetration rates and extraction technology upgrade cycles. A model refresh is warranted upon material change in beverage manufacturer direct-to-processor procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Yogurt Makers Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Brewery Equipment Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Optical Sorter Market